
 Wireless Sensor Tags Market | 2026-2036
Wireless Sensor Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Sensor Tags Market Analytics
Distributor networks for industrial sensor hardware is narrowing as direct-to-fleet procurement gains ground among logistics operators. Texas Instruments Incorporated anchors North American supply through its integrated radio-frequency chipsets that power active tag architectures. STMicroelectronics competes in European industrial channels with ultra-low-power microcontroller platforms purpose-built for multi-year battery life. Honeywell International Inc. dominates building-automation verticals where sensor tags feed directly into its captive building-management software ecosystems.
Wireless sensor tags are compact, battery-operated or energy-harvesting transponder devices that encode identifier data and environmental measurements into radio-frequency transmissions readable by gateway receivers at ranges from centimeters to hundreds of meters. Their primary commercial purpose is to automate visibility into location, condition, and custody of mobile assets without requiring wired infrastructure or manual scanning. Active tags command premium positioning in cold-chain pharmaceutical monitoring where real-time temperature telemetry justifies higher unit costs and recurring connectivity fees. Passive RFID tags sustain volume leadership in retail inventory management where unit economics favor disposable, interrogator-powered designs at pallet and item level. Bluetooth Low Energy tags are capturing share in healthcare asset-tracking deployments where smartphone-grade receiver density eliminates dedicated infrastructure requirements.
FDA traceability rules for pharmaceutical distribution reshape product requirements toward tamper-evident, temperature-logging tag architectures with audit-ready data retention. FCC Part 15 emissions limits constrain radio power and duty-cycle design choices for tags operating in unlicensed ISM bands across the United States. ISO 18000-6C and EPC Gen2 standards govern interoperability mandates that determine market access for passive UHF RFID suppliers serving retail and logistics buyers. Stakeholders must weigh captive platform strategies against open-standard compatibility as buyer procurement committees harden interoperability requirements into contract specifications.
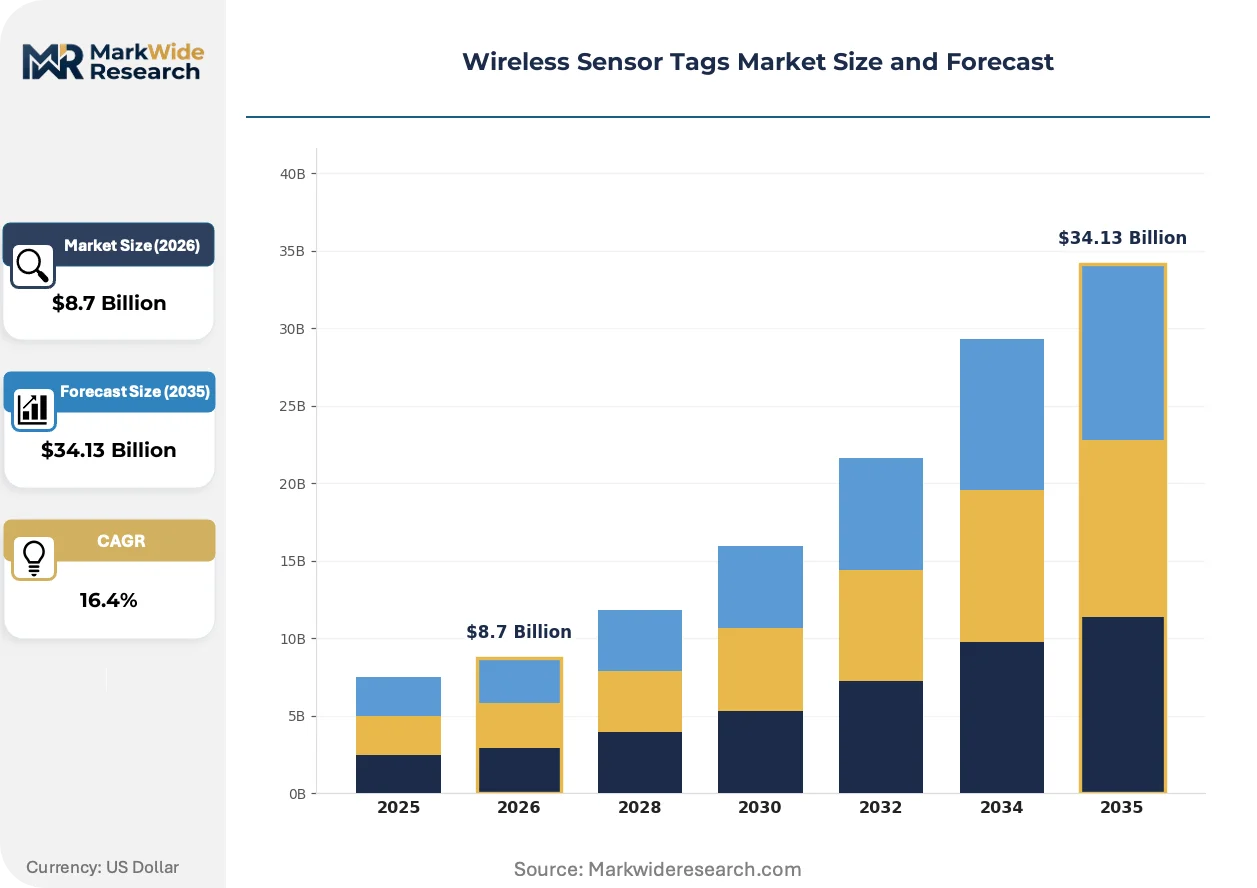
Market Dynamics
Cold chain pharmaceutical operators face FDA traceability mandates that force immediate replacement of passive tracking with active temperature-logging architectures, compressing procurement cycles and rewiring supplier relationships toward integrated telemetry platforms.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Mandates for unit-level traceability drive pharmaceutical distributors toward serialized RFID and Bluetooth tag deployments with tamper-evident enclosures.
- Predictive maintenance adoption:German industrial manufacturing clusters deploy environmental monitoring tags to feed vibration and thermal data into digital-twin asset management systems.
- Energy harvesting advances:Photovoltaic and thermoelectric transducers extend tag lifespans beyond battery limits in logistics yards with high solar exposure or thermal gradients.
Market Restraints
- Lithium primary cell volatility:Active tag architectures depend on non-rechargeable coin cells whose cobalt and lithium supply chains concentrate in politically unstable extraction zones.
- FCC Part 15 duty-cycle limits:Unlicensed ISM band restrictions cap transmission frequency and range, forcing denser gateway infrastructure in large-scale warehouse deployments.
- Passive RFID substitution in retail:Ultra-low-cost UHF inlays satisfy inventory visibility requirements without recurring connectivity fees, constraining active tag pricing power in non-temperature-critical applications.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO is tightening distribution documentation requirements, opening demand for temperature-logging tags in a market historically dependent on manual record-keeping.
- LoRaWAN-Bluetooth convergence:Hybrid radio architectures combine long-range backhaul with smartphone-compatible edge connectivity, eliminating dedicated reader infrastructure in mid-scale healthcare facilities.
- EU Green Deal circularity mandates:Battery-free tag designs using printed electronics and paper substrates align with emerging Extended Producer Responsibility frameworks for disposable electronics.
Industry Challenges
- RF firmware engineering scarcity:Tag vendors compete for embedded developers capable of optimizing ultra-low-power stack implementations across multiple regional spectrum allocations.
- ISO 18000-6C certification timelines:Interoperability testing against heterogeneous reader populations extends product launch schedules by six to twelve months.
- Legacy WMS integration friction:Enterprise warehouse management systems require custom middleware development to ingest real-time tag telemetry alongside batch-scanned barcode records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Sensor Tags Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Tags, Passive Tags, Semi-Passive Tags, Smart Tags Technology: Bluetooth, RFID, Zigbee, NFC Application: Inventory Management, Asset Tracking, Environmental Monitoring, Healthcare End User: Retail, Manufacturing, Logistics, Transportation |
| Companies Covered | TE Connectivity, ON Semiconductor, Texas Instruments Incorporated, Intel Corporation, STMicroelectronics, Infineon Technologies, Cao Gadgets LLC, Honeywell International Inc., Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Sensor Tags Market Evolving Landscape
Radio architectures and power harvesting methods are converging to collapse the traditional trade-off between tag cost and functional capability, enabling sensor density levels that rewrite asset visibility economics.
Printed electronics manufacturing is rendering obsolete the conventional etched-circuit tag substrates that dominated disposable logistics applications. Roll-to-roll gravure and inkjet deposition of conductive silver traces onto polymer films cut unit costs below the threshold for item-level retail tagging. Mass-market apparel retailers in North American distribution hubs now embed humidity and impact sensors directly into hangtag form factors.
EMA serialization requirements for investigational medicinal products impose data-integrity standards that cascade into tag firmware design. European clinical-trial logistics providers must deploy tags with cryptographically signed temperature logs and blockchain-anchored custody handoffs. German pharmaceutical 3PLs are qualifying tag vendors based on audit-trail completeness rather than hardware specifications alone.
Direct procurement from hardware specialists is displacing traditional industrial distribution channels for fleet-scale tag deployments. Large logistics operators in the United States negotiate multi-year telemetry service contracts that bundle tags, gateways, and cloud analytics, bypassing regional sensor distributors. This channel compression concentrates volume with integrated platform vendors capable of end-to-end solution accountability.
Wireless Sensor Tags Market Segmentation
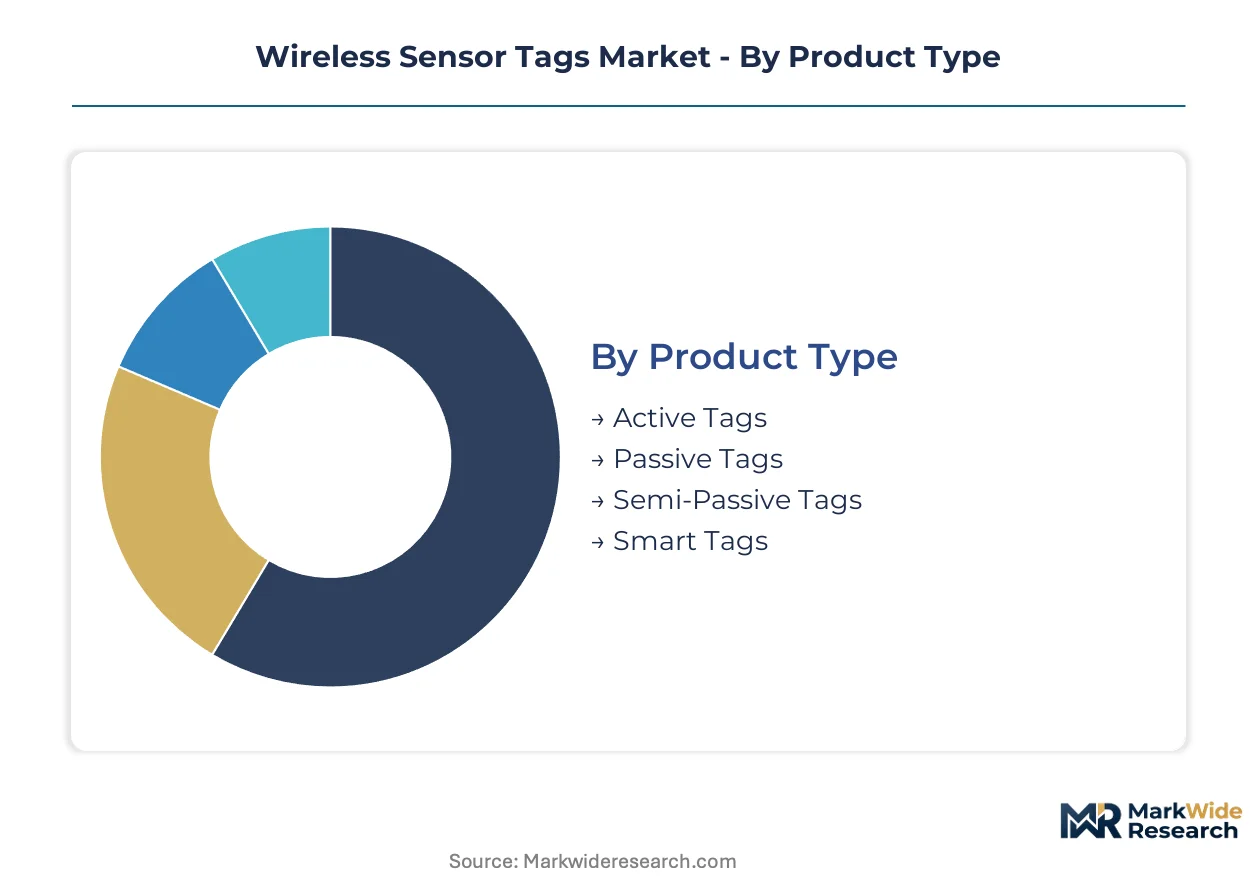
Segmentation in wireless sensor tags reveals divergent procurement rhythms, with cold-chain pharmaceutical buyers replacing hardware on compressed FDA-mandated cycles while retail inventory managers amortize passive tag investments over multi-year depreciation schedules. Understanding these velocity differentials helps vendors align service models, inventory buffers, and R&D roadmaps to the specific cash-flow profiles of each buyer cluster.
Product Type:
Active tags turn over fastest due to battery depletion and regulatory-driven refresh cycles, while passive tags operate on decade-long replacement horizons anchored to infrastructure amortization.
- Active Tags:Battery-powered transponders with onboard processors enable real-time telemetry transmission across extended ranges. Pharmaceutical cold-chain operators in the United States deploy these under FDA Drug Supply Chain Security Act mandates, accepting higher unit costs and recurring connectivity fees to secure temperature audit trails. Active tags anchor the volume base while Smart Tags gain share at the steepest rate.
- Passive Tags:Interrogator-powered designs harvest energy from reader emissions, eliminating onboard power sources entirely. Mass-market apparel retailers in North American distribution hubs embed humidity and impact sensors into hangtag form factors, prioritizing unit economics over real-time visibility. These tags represent the fastest-growing trajectory in retail inventory management where disposable economics dominate procurement criteria.
- Semi-Passive Tags:Battery-assisted backscatter architectures combine passive-range economics with sensor-actuation capability.
- Smart Tags:Integrated microcontrollers with edge-processing capability enable local analytics before transmission.
Passive tags anchor the volume base while Smart Tags gain share at the steepest rate.
Technology:
Cost tiering separates premium radio architectures with dedicated infrastructure requirements from economy-tier protocols piggybacking on existing receiver density.
- Bluetooth:Low-energy stacks leverage smartphone-grade receiver ubiquity, eliminating dedicated gateway capital for mid-scale deployments. Healthcare asset-tracking installations in German hospital networks favor Bluetooth for room-level precision without proprietary reader infrastructure. Bluetooth anchors the volume base while RFID gains share at the steepest rate.
- RFID:UHF backscatter dominates pallet and item-level logistics where interrogator infrastructure already exists. Cold-chain pharmaceutical distributors in India deploy RFID under tightening CDSCO documentation requirements, migrating from manual record-keeping to automated custody verification.
- Zigbee:Mesh-networking protocol optimized for building-automation density with self-healing topology.
- NFC:Near-field induction for tap-to-pair consumer interactions and last-meter authentication workflows.
RFID anchors the volume base while Bluetooth gains share at the steepest rate.
Application:
Customer type stratification separates mission-critical telemetry buyers with compliance-driven procurement from efficiency-seeking operators optimizing labor substitution.
- Environmental Monitoring:Multi-sensor tags track temperature, humidity, vibration, and shock events through supply chain custody. Siemens and Bosch facilities in Germany's industrial manufacturing corridor feed this data into digital-twin asset management systems for predictive maintenance workflows.
- Asset Tracking:Location-centric architectures prioritize spatial precision over environmental telemetry. Healthcare networks deploy these for mobile equipment visibility, reducing capital expenditure on redundant device fleets.
- Inventory Management:High-volume, low-unit-cost tagging for retail and wholesale stock visibility.
- Healthcare:Patient-centric applications spanning wristband identification to infusion pump tracking.
Inventory Management anchors the volume base while Environmental Monitoring gains share at the steepest rate.
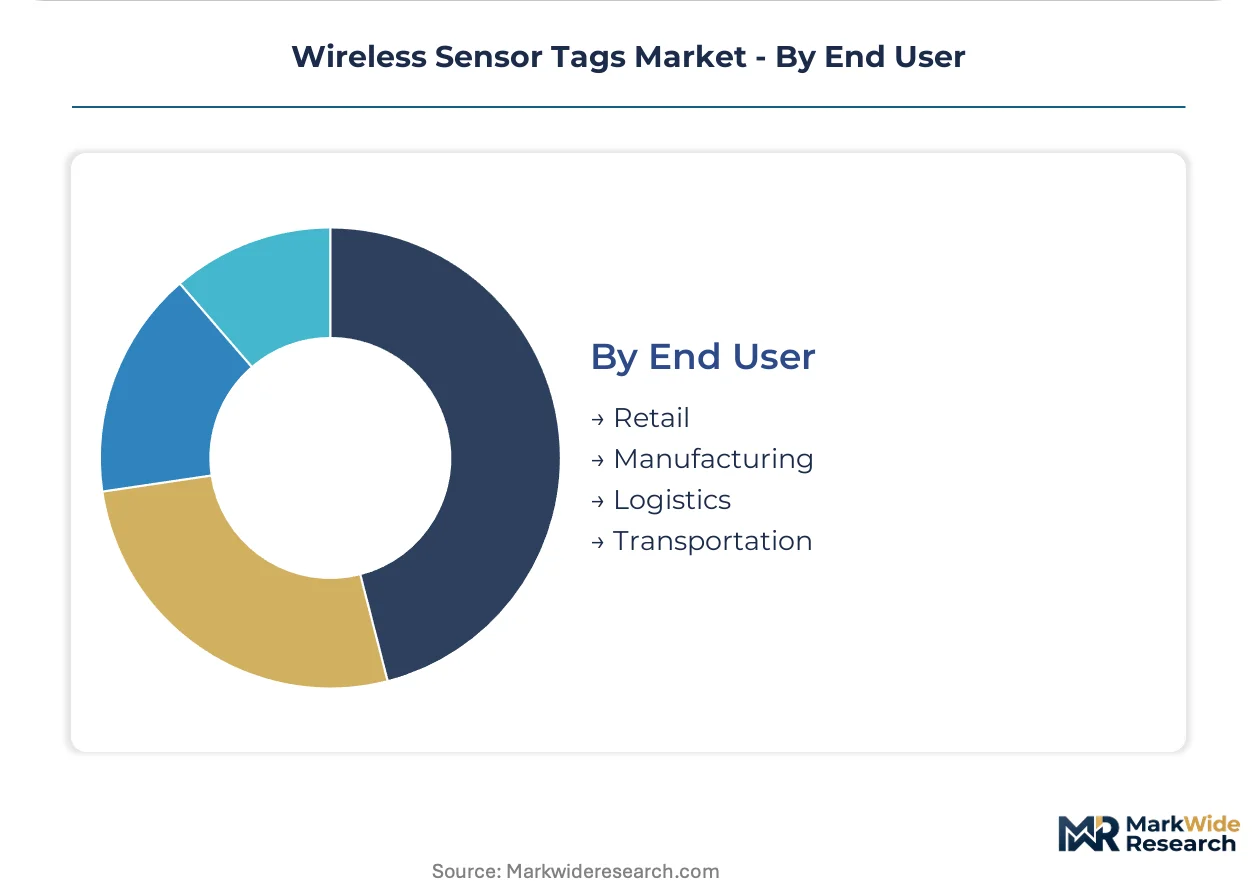
End User:
Supply concentration maps directly to regulatory exposure, with pharmaceutical-facing logistics operators facing the most compressed hardware replacement cycles.
- Logistics:Third-party providers bundle tags, gateways, and cloud analytics into multi-year telemetry service contracts, bypassing regional sensor distributors through direct procurement. Large United States operators negotiate these arrangements to secure end-to-end solution accountability.
- Manufacturing:Industrial facilities embed tags into work-in-process tracking and condition-based maintenance workflows. German automotive suppliers qualify vendors on audit-trail completeness rather than hardware specifications alone.
- Retail:Mass-market inventory visibility with extreme unit-cost sensitivity.
- Transportation:Fleet-scale deployments spanning rail, air cargo, and over-the-road trucking.
Retail anchors the volume base while Logistics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure anchors European logistics digitization, while the Union Pacific rail network and Qingdao port complex underwrite trans-Pacific cold-chain corridors for pharmaceutical telemetry hardware.
United States
Pharmaceutical 3PLs in Memphis and Louisville deploy active temperature-logging tags under FDA Drug Supply Chain Security Act mandates. FCC Part 15 emissions limits constrain radio power design choices for tags operating in unlicensed ISM bands. Dallas-Fort Worth logistics clusters drive direct-to-fleet procurement of integrated telemetry platforms.
Germany
Siemens and Bosch facilities in Bavaria's industrial manufacturing corridor feed vibration and thermal sensor data into digital-twin asset management systems. EU Green Deal circularity mandates accelerate battery-free tag designs using printed electronics. Stuttgart automotive suppliers qualify vendors on audit-trail completeness rather than hardware specifications alone.
India
CDSCO is tightening pharmaceutical distribution documentation requirements, opening demand for temperature-logging tags in a market historically dependent on manual record-keeping. Mumbai and Hyderabad cold-chain operators migrate from paper-based custody records to automated RFID verification. Gujarat pharmaceutical manufacturing clusters pilot LoRaWAN-Bluetooth hybrid architectures for mid-scale facility tracking.
China
NMPA traceability rules for vaccine distribution reshape product requirements toward tamper-evident tag architectures with audit-ready data retention. Shanghai and Shenzhen electronics manufacturing hubs supply roll-to-roll gravure-printed conductive substrates for disposable logistics tags. Yangtze River Delta pharmaceutical distributors negotiate multi-year telemetry service contracts bundling hardware and cloud analytics.
Japan
METI industrial digitization programs accelerate environmental monitoring tag deployment in automotive and precision manufacturing facilities. PMDA serialization requirements for investigational medicinal products impose data-integrity standards cascading into tag firmware design. Nagoya industrial clusters integrate sensor tags into predictive maintenance workflows for production line equipment.
Wireless Sensor Tags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio-frequency chipsets and ultra-low-power microcontrollers. Market structure concentrates around semiconductor conglomerates with captive wireless divisions and specialized sensor-tag pure-plays with logistics-sector relationships. Three archetypes dominate: integrated platform vendors bundling hardware and cloud analytics, component suppliers selling chipsets into third-party tag assemblies, and vertical-focused specialists targeting pharmaceutical cold-chain compliance. Competitive moves center on strategic partnerships between tag vendors and cloud analytics providers, plus backward integration into energy-harvesting transducer manufacturing.
Among semiconductor specialists, Texas Instruments Incorporated and STMicroelectronics exemplify the component-supplier archetype, anchoring North American and European supply channels respectively through integrated radio-frequency and microcontroller platforms. Honeywell International Inc. occupies a position within the integrated-platform tier, leveraging captive building-management software ecosystems to capture building-automation verticals. Cao Gadgets LLC represents the specialized pure-play segment, sitting within the logistics-focused hardware tier without upstream semiconductor fabrication capabilities.
| Leading Market Players |
|---|
| TE Connectivity |
| ON Semiconductor |
| Texas Instruments Incorporated |
| Intel Corporation |
| STMicroelectronics |
| Infineon Technologies |
| Cao Gadgets LLC |
| Honeywell International Inc. |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's automated container handling corridors transmit cost volatility directly into wireless sensor tag pricing, compressing margins for European distributors while amplifying pricing power for integrated platform vendors with captive gateway manufacturing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cold-chain tags from industrial monitoring units and disposable retail inlays. Price differentiation hinges on certification grade—ISO 18000-6C and EPC Gen2 interoperability testing adds six-to-twelve-month qualification overhead—and volume scale, with fleet-scale logistics operators extracting double-digit unit discounts. Pricing pressure stems from passive RFID substitution in retail inventory management, where ultra-low-cost UHF inlays satisfy visibility requirements without recurring connectivity fees. Retail inventory managers exhibit extreme price sensitivity, while pharmaceutical 3PLs prioritize audit-trail completeness over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for radio-frequency chipset procurement. Manufacturing concentrates in China, Taiwan, and South Korea, with Shanghai and Shenzhen electronics hubs supplying roll-to-roll gravure-printed conductive substrates. Raw material dependencies include lithium primary cells, cobalt extraction from politically unstable zones, and silver conductive inks for printed electronics. Distribution runs through direct-to-fleet procurement channels that displace traditional industrial distributors, with large United States logistics operators negotiating multi-year telemetry service contracts bundling hardware, gateways, and cloud analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless sensor tag demand is recovering from its cyclical trough as FDA traceability mandates force pharmaceutical distributors into compressed hardware replacement cycles, creating predictable procurement visibility for vendors with compliance-ready platforms.
For Market Incumbents: Build switching-cost moats through captive cloud analytics integration that locks pharmaceutical 3PLs into multi-year telemetry service contracts. Deepen backward integration into energy-harvesting transducer manufacturing to offset lithium primary cell volatility. Invest in ISO 18000-6C pre-certification testing infrastructure to compress six-to-twelve-month interoperability timelines that currently delay product launches.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical cold chain where CDSCO documentation tightening is displacing manual record-keeping with automated RFID verification. Target mid-scale healthcare facilities with LoRaWAN-Bluetooth hybrid architectures that eliminate dedicated reader infrastructure. Lead with printed electronics manufacturing partnerships that deliver battery-free tag designs aligned with EU Green Deal circularity mandates.
For Investors and Strategic Acquirers: Carve-out targets emerge from semiconductor conglomerates with non-core wireless sensor tag divisions that lack logistics-sector relationships. The five-to-ten-year viability window favors integrated platform vendors with end-to-end solution accountability over component suppliers exposed to commoditization pressure. Monitor FDA enforcement patterns for DSCSA serialization deadlines as the inflection indicator for cold-chain hardware demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| LoRaWAN-Bluetooth Hybrid Architecture Development | Eliminates dedicated gateway infrastructure for mid-scale German healthcare facilities. |
| Printed Electronics Manufacturing Scale-Up | Enables battery-free tag designs compliant with EU Green Deal circularity mandates. |
| Direct-to-Fleet Telemetry Service Contracts | Bypasses regional distributors and captures multi-year recurring revenue from United States logistics operators. |
| Energy-Harvesting Transducer Backward Integration | Reduces dependency on lithium primary cells from politically unstable extraction zones. |
| ISO 18000-6C Pre-Certification Infrastructure Investment | Compresses product launch timelines against heterogeneous reader populations. |
Research Methodology
The analysis maps active tag architectures, passive RFID inlays, and Bluetooth Low Energy deployments, each validated through cold-chain logistics operators, pharmaceutical 3PL procurement committees, semiconductor component specialists, and building-automation systems integrators. Primary interviews with these stakeholders were cross-referenced against FDA DSCSA guidance documents, FCC Part 15 emissions filings, EPC Gen2 interoperability test reports, and EU Green Deal circularity framework drafts. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Assumptions held fixed include FDA enforcement timelines for pharmaceutical traceability, FCC Part 15 duty-cycle limits on unlicensed ISM band operation, and ISO 18000-6C interoperability standards as market access preconditions. Variables included energy-harvesting technology maturation curves, lithium supply chain disruption scenarios, and retail inventory management automation adoption rates. CAGRs were derived from segment-level growth differentials across product type, technology protocol, and end-user vertical, with pharmaceutical cold-chain compliance mandates and German industrial predictive maintenance adoption serving as primary demand anchors.
Sensitivities concentrate around FDA enforcement acceleration or delay, lithium primary cell supply disruptions, and passive RFID cost curves that could accelerate substitution in non-temperature-critical applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market