
 High Voltage Cables Market | 2026-2036
High Voltage Cables Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Cables Market Analysis
The EU F-Gas Regulation is consolidating the competitive landscape for gas-insulated cable accessories and pushing manufacturers toward solid-dielectric alternatives. Prysmian Group leverages its submarine cable fabrication footprint in Italy and Finland to anchor European offshore wind interconnectors. Nexans competes through R&D intensity in 525 kV extruded HVDC systems, while Sumitomo Electric Industries dominates XLPE insulation compound supply for ultra-high voltage land cables.
High voltage cables are insulated conductors rated above 60 kV, typically employing cross-linked polyethylene or oil-impregnated paper insulation within aluminum or copper conductors, designed to transmit bulk electrical power across long distances with minimal resistive losses. AC cables remain the mature workhorse for national grid backbones and urban underground networks, while DC cables represent the fastest-growing margin pool as point-to-point offshore wind and intercontinental links displace conventional HVAC for routes exceeding 600 kilometers. Submarine installation commands premium pricing due to specialized armoring and laying vessel scarcity, whereas overhead segments face margin compression from commodity conductor competition.
Grid operators must navigate CE marking under the EU Construction Products Regulation, IEC 62067 testing protocols for XLPE-insulated systems, and country-specific national grid codes from Germany's Bundesnetzagentur and the UK's National Grid. These frameworks dictate insulation thickness tolerances, partial discharge limits, and route approval timelines that directly shape project viability and manufacturer qualification requirements. Stakeholders should monitor how evolving carbon-border adjustment mechanisms and raw material traceability mandates reshape sourcing economics for copper and aluminum feedstock.
Market Dynamics
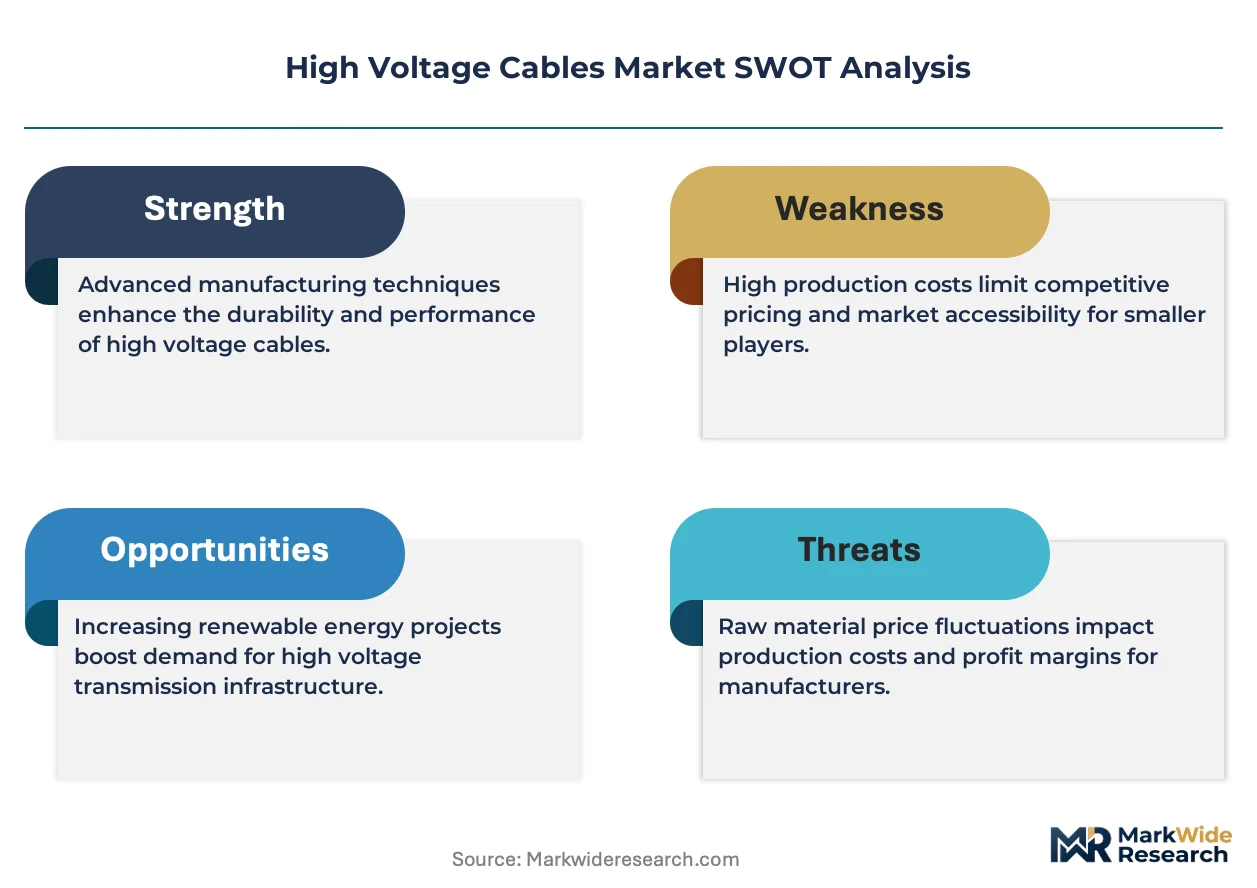
The EU F-Gas Regulation is forcing a wholesale insulation technology transition across European transmission infrastructure, eliminating sulfur hexafluoride-dependent switchgear and cable accessories while accelerating solid-dielectric and extruded DC system deployment.
Growth Catalysts
- Offshore Wind Scaling:North Sea developers are expanding submarine cable procurement for grid-connected wind farms, driving demand for specialized armored DC systems with enhanced mechanical protection.
- Extruded DC Technology Maturation:525 kV+ extruded cable systems are displacing oil-impregnated paper insulation for long-distance bulk power transmission, reducing maintenance requirements and environmental risk profiles.
- India's Transmission Modernization:State transmission utility tenders under the Central Electricity Authority are accelerating domestic conductor procurement for interstate high-capacity corridors.
Market Restraints
- Copper Price Volatility:Raw material cost swings for electrolytic copper cathode compress manufacturing margins and complicate long-dated project bidding for cable fabricators.
- Laying Vessel Scarcity:Specialized submarine cable installation fleet concentration limits project execution bandwidth and extends delivery timelines for offshore interconnectors.
- SF6 Phase-Out Transition Costs:The EU F-Gas Regulation mandates capital-intensive retooling of gas-insulated accessory production lines before viable solid-dielectric alternatives achieve cost parity.
Strategic Opportunities
- Sub-Saharan Grid Expansion:Underelectrified markets in Nigeria and Kenya present demand for 132-400 kV land cable systems as multilateral development finance accelerates backbone transmission investment.
- Hydrogen Electrolyzer Integration:Point-to-point HVDC links dedicated to renewable-powered hydrogen production clusters create specialized cable demand with premium technical specifications.
- Carbon Border Adjustment Positioning:EU CBAM implementation favors cable producers with verified low-carbon aluminum and copper smelting supply chains, creating qualification advantages for certified manufacturers.
Industry Challenges
- Partial Discharge Testing Expertise Gap:Specialized technician shortages for IEC 62067 compliance testing extend qualification timelines and inflate quality assurance costs for XLPE system deployments.
- Route Approval Complexity:Bundesnetzagentur and National Grid permitting processes for subterranean corridors generate multi-year regulatory delays that strain project financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Cables Market |
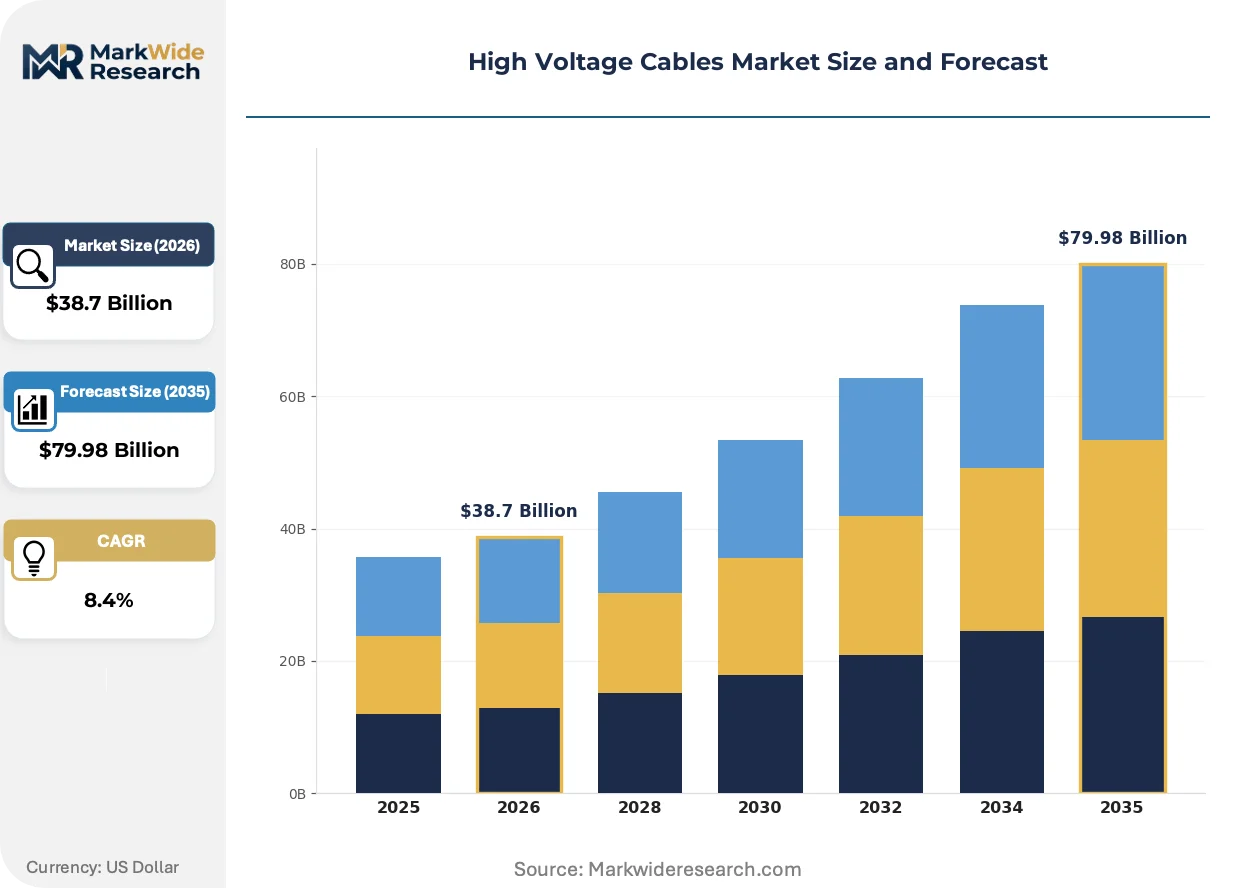
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Cables, DC Cables, Fiber-Optic Cables, Composite Cables Installation Type: Underground, Overhead, Submarine, Indoor End User: Utilities, Industrial Facilities, Renewable Energy, Construction Material: Copper, Aluminum, Steel, Composite |
| Companies Covered | Prysmian Group, Nexans, Sumitomo Electric Industries, NKT A/S, LS Cable & System, Southwire Company, ABB, Furukawa Electric, Dubai Cable Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Cables Market Emerging Trajectories
Extruded insulation platforms are consolidating technical leadership across voltage classes while regulatory chemistry restrictions and procurement centralization reshape competitive access and margin structures.
Cross-linked polyethylene (XLPE) insulation is consolidating its position as the dominant dielectric technology for land-based AC and DC systems above 220 kV. Grid operators in Germany and the UK are specifying XLPE for new urban underground networks and intercity corridors. This material transition is consolidating manufacturing scale around compound suppliers with integrated polyethylene resin and peroxide cross-linking capabilities.
The EU F-Gas Regulation is banning sulfur hexafluoride in new switchgear and cable terminations from 2030. Cable accessory manufacturers face mandatory reformulation of gas-insulated products toward vacuum-interrupter and solid-dielectric designs. This regulatory compression most affects 145-420 kV GIS-connected cable systems in continental Europe, where utilities are pre-qualifying SF6-free alternatives ahead of statutory deadlines.
Centralized procurement by transmission system operators is consolidating vendor relationships and compressing supplier margins. National Grid and TenneT are bundling cable, installation, and long-term service contracts into single-tender packages. This purchasing concentration is most advanced in the North Sea offshore wind sector, where developers favor integrated EPC arrangements over component-level sourcing.
High Voltage Cables Market Segmentation
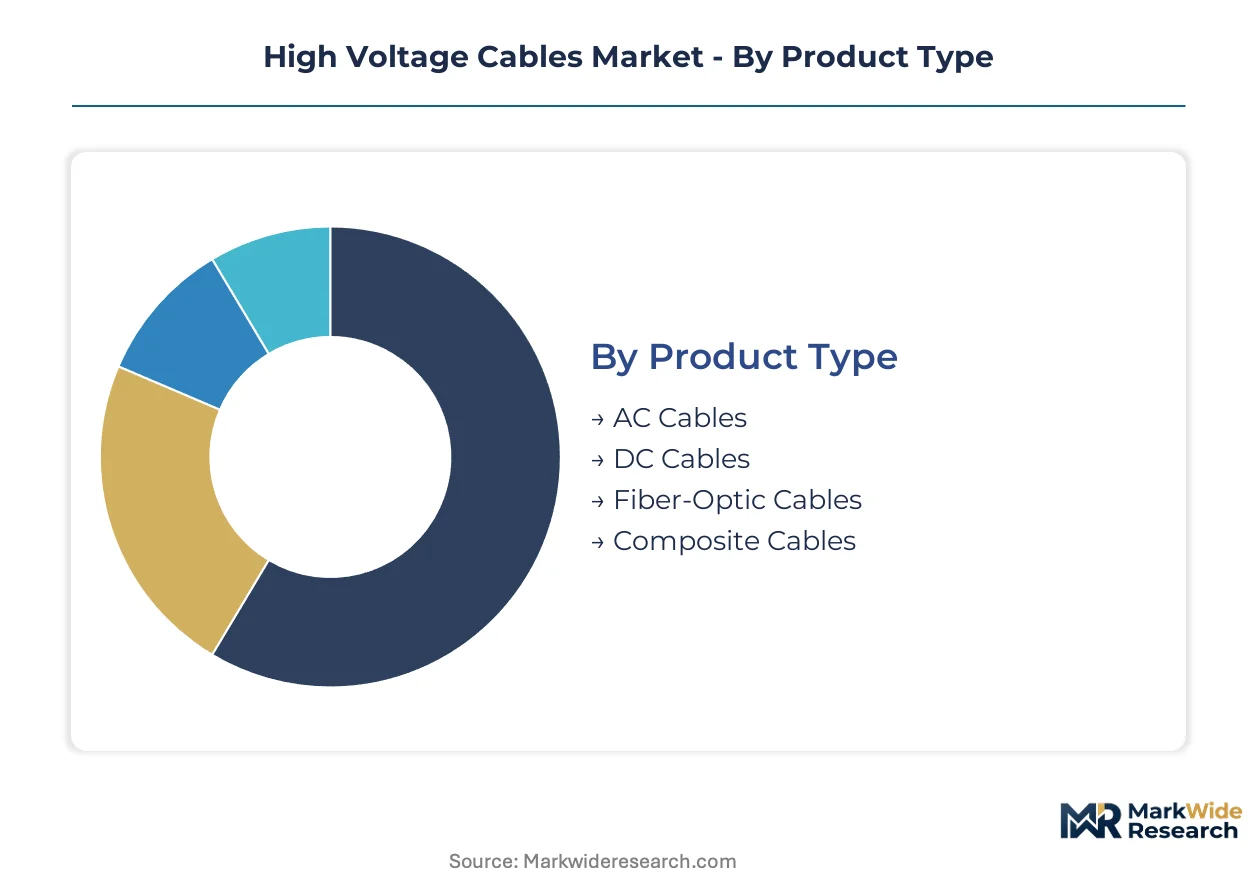
High voltage cable procurement decisions hinge on route characteristics, voltage requirements, and environmental exposure. Each segmentation dimension shapes insulation specifications, armoring requirements, and installation economics differently.
Product Type:
AC cable systems function as standalone grid backbone components, while DC and composite configurations embed within integrated transmission architectures requiring converter station pairing.
- AC Cables:Cross-linked polyethylene or oil-impregnated paper insulation systems rated 60-500 kV serve national grid interconnections and urban underground networks. German Bundesnetzagentur specifications and UK National Grid codes drive procurement for 220-400 kV XLPE land corridors connecting onshore substations.
- DC Cables:Extruded insulation platforms at 320-525 kV enable point-to-point bulk power transmission beyond 600 kilometers without reactive compensation. North Sea offshore wind developers specify these for grid-connected arrays, with Italy and Finland fabrication facilities supplying armored submarine variants.
- Fiber-Optic Cables:Composite power-communication designs embed optical fibers within high voltage conductors for grid monitoring and SCADA integration.
- Composite Cables:Hybrid constructions combining conductive cores with optical or control elements reduce right-of-way requirements for constrained urban routes.
Volume placements concentrate in AC Cables; the faster expansion belongs to DC Cables.
Installation Type:
Cost tier stratification separates premium submarine systems from commodity overhead conductors, with underground installations commanding mid-tier positioning based on urban density premiums.
- Underground:XLPE-insulated land cables with lead or corrugated aluminum sheathing deploy in dense urban corridors and environmentally restricted zones. German cities including Hamburg and Munich mandate undergrounding for 110-220 kV distribution, while India's Central Electricity Authority accelerates interstate buried corridor tenders.
- Submarine:Specialized armoring with galvanized steel wire and polyethylene jackets protects against seabed abrasion and hydrostatic pressure. North Sea routes between Germany, Denmark, and the UK face laying vessel scarcity that extends delivery timelines and inflates project costs.
- Overhead:ACSR and ACSS conductor strands with aluminum-clad steel cores span rural and industrial zones with lower capital intensity.
- Indoor:Gas-insulated or solid-dielectric terminations and joints within substations face EU F-Gas Regulation phase-out deadlines forcing SF6-free retooling.
Revenue concentration sits with Submarine installations; margin compression hits Overhead most severely.
End User:
Customer type determines technical specification rigor, with utilities enforcing IEC 62067 testing protocols and renewable developers prioritizing route flexibility for remote generation clusters.
- Utilities:Transmission system operators in Germany, the UK, and India specify 220-525 kV systems with partial discharge limits and 40-year service life guarantees. Centralized procurement by National Grid and TenneT bundles cable, installation, and long-term service into single-tender packages.
- Renewable Energy:Offshore wind developers in the North Sea scale procurement of extruded DC submarine systems with enhanced mechanical protection for turbine inter-array and export cables.
- Industrial Facilities:Steel, aluminum smelters, and petrochemical complexes demand dedicated 132-220 kV supply feeders with high short-circuit withstand ratings.
- Construction:Infrastructure projects including airports, railways, and data centers specify medium-to-high voltage distribution for campus-style power delivery.
Contract value pools deepest with Utilities; Renewable Energy claims the steepest expansion trajectory.
Material:
Supply concentration and carbon-border exposure differentiate conductor economics, with copper facing volatile cathode pricing and aluminum benefiting from EU CBAM positioning for low-carbon smelting verification.
- Copper:Electrolytic cathode with 99.9% conductivity serves high-current density applications and submarine cables where compact dimensions reduce armoring mass. Raw material price swings compress manufacturing margins and complicate long-dated project bidding.
- Aluminum:Alloy 1350 and 6201 conductors reduce weight and cost for overhead lines and long-distance land corridors. Chinese and Indian smelters dominate feedstock supply, with EU CBAM implementation favoring verified low-carbon sourcing.
- Steel:Galvanized high-strength wires provide tensile armoring for submarine and buried installations.
- Composite:Carbon fiber reinforced polymer cores enable high-temperature low-sag overhead conductors for reconductoring projects.
procurement tonnage favors Aluminum; premium applications anchor on Copper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces anchor manufacturing concentration for extruded cable compounds and copper processing. India's transmission corridors and Europe's offshore wind clusters drive divergent demand patterns across three distinct regulatory environments.
China
State Grid Corporation tenders for 525 kV+ extruded DC systems dominate procurement volumes in Jiangsu and Shandong provinces. MIIT industrial standards for ultra-high voltage cable insulation compound production concentrate technical capacity around Yangtze River Delta chemical parks. Zhejiang and Jiangsu host integrated polyethylene resin and cross-linking facilities serving domestic and export markets.
Germany
Bundesnetzagentur grid codes mandate XLPE insulation for 220-400 kV urban underground corridors connecting Hamburg and Munich substations. The EU F-Gas Regulation phases out SF6-insulated cable terminations by 2030, forcing accessory retooling at industrial clusters in North Rhine-Westphalia. Siemens Energy and Prysmian maintain fabrication presence in Lower Saxony and Bavaria for North Sea interconnector supply.
United Kingdom
National Grid bundled tenders combine submarine cable, installation, and long-term service contracts for North Sea offshore wind export routes. The UK Energy Act implementation accelerates consent timelines for subterranean transmission corridors between Scotland and England. Grimsby and Great Yarmouth serve as cable marshalling hubs for North Sea array connections.
India
Central Electricity Authority interstate corridor tenders under the Green Energy Corridors program accelerate 400 kV XLPE procurement across Maharashtra and Gujarat. BIS certification requirements for 132-220 kV land cable systems concentrate domestic manufacturing in Haryana and Tamil Nadu. Power Grid Corporation of India Limited pre-qualifies vendors for dedicated renewable energy transmission spokes.
Italy
Prysmian Group's submarine cable fabrication facility in Arco Felice anchors European offshore wind interconnector supply. CE marking under the EU Construction Products Regulation governs insulation thickness tolerances for Tyrrhenian Sea crossings. Sicily-Calabria mainland connections and planned links to Tunisia drive specialized armored DC system demand.
High Voltage Cables Market Vendor Landscape
Italian and German producers anchor the premium submarine tier; Japanese and South Korean specialists hold positions in compound supply and land cable fabrication. The market structures around three tiers: integrated energy conglomerates with cable divisions, pure-play wire and cable manufacturers, and regional specialists serving national utility procurement. Strategic moves concentrate on backward integration into polyethylene resin production and captive installation vessel access.
Within the integrated conglomerate tier, Prysmian Group and Nexans exemplify European-based fabricators with submarine fabrication footprints. Sumitomo Electric Industries occupies a position representing Japanese compound and insulation technology specialization. These three anchors demonstrate how geographic origin and corporate structure map to distinct competitive positioning across AC land systems, DC extruded platforms, and submarine armored variants.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Sumitomo Electric Industries |
| NKT A/S |
| LS Cable & System |
| Southwire Company |
| ABB |
| Furukawa Electric |
| Dubai Cable Company |
| Others |
Supply Flow & Price Mechanics
Transmission system operator bundled tenders in the North Sea offshore wind corridor anchor contract-based long-term offtake pricing, with centralized procurement compressing supplier margins across submarine and land cable segments alike.
Pricing Analysis
Short lead-time premiums for laying vessel availability and specialized armoring drive price stratification across project timelines, with spot procurement for installation windows commanding substantial uplifts over scheduled deliveries. Three-tier pricing structure across premium, standard, and economy levels separates integrated EPC bundles from component-only supply and commodity overhead conductors. Cost compression in overhead segments stems from aluminum conductor competition, while submarine systems retain pricing resilience. Industrial facilities demonstrate highest price sensitivity due to capital budget constraints, whereas utilities exhibit lowest sensitivity given regulatory-pass-through mechanisms.
Supply Chain Analysis
IEC 62067 qualification protocols and CE marking under the EU Construction Products Regulation gate supplier access, extending vendor onboarding timelines and concentrating qualified capacity. China, Italy, and Finland anchor extruded cable compound and submarine fabrication supply. Raw material flows draw from electrolytic copper cathode, polyethylene resin, and galvanized steel wire feedstocks. Single-source vulnerability concentrates in specialized laying vessel fleets and XLPE compound supply. Distribution runs through transmission system operator tender platforms and EPC contractor channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized submarine cable installation vessel scarcity props pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with captive fleet access.
For Market Incumbents: Extend fabrication footprints into polyethylene resin production to secure compound supply and reduce feedstock cost volatility. Prysmian Group and Nexans should accelerate SF6-free accessory qualification ahead of EU F-Gas Regulation deadlines to defend market position against solid-dielectric specialists. Capacity addition in Southeast Asia addresses India's transmission modernization tenders. For New Entrants and Emerging Players: 525 kV extruded HVDC technology specialization offers entry wedge into offshore wind interconnector procurement, where incumbent capacity constraints create qualification windows. Sub-Saharan grid expansion in Nigeria and Kenya presents most penetrable geography, with 132-220 kV land cable demand outpacing local supply. Partner with multilateral development finance institutions for project co-financing credibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor cable accessory manufacturers with SF6-free product pipelines in Germany and Italy, where regulatory transition costs strain mid-tier competitors. Five-to-ten year viability hinges on extruded DC technology maturation and offshore wind execution bandwidth. Monitor laying vessel orderbook activity as inflection indicator for supply constraint duration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Resin | Captive compound supply reduces exposure to Yangtze River Delta chemical park pricing volatility. |
| SF6-Free Accessory Qualification | CE marking for solid-dielectric terminations secures Bundesnetzagentur grid code compliance ahead of phase-out. |
| Laying Vessel Fleet Expansion | Dedicated installation capacity captures North Sea offshore wind bundling premiums. |
| Sub-Saharan Market Entry | Early positioning in Green Energy Corridor-linked tenders builds reference projects for multilateral finance. |
| Low-Carbon Aluminum Sourcing | EU CBAM verification creates qualification advantage for transmission system operator procurement. |
Methodological Framework
Regulatory filings from Bundesnetzagentur and National Grid, IEC standard documentation, and customs trade data formed the secondary backbone, supplemented by primary interviews with submarine cable project managers, transmission utility procurement officers, EPC contractor supply chain leads, and XLPE compound technical directors. Bottom-up project pipeline analysis triangulated against top-down transmission investment forecasts.
Historical trendline analysis of transmission system operator tender awards and offshore wind lease round timing informed the projection framework across the analysis window. Segmentation modeling incorporated voltage class, installation environment, insulation technology, and end-use customer type. CAGRs derived from capacity expansion announcements, vessel orderbook analysis, and raw material price trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged laying vessel scarcity or copper price volatility extremes. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or North Sea offshore wind consent acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Japan Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
Premise Cable Market
Cables
HVDC Cables Market
Cables
USB Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Latin America Wire and Cable Market
Cables
North America Coaxial Cable Market
Cables
Polyurethane Cable Market
Cables
Global Ethernet Cable Market
Cables
Global Cable Tie Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Anti-Static Space Wires Market
Cables
Cable Management System Market
Cables
Europe Cable Management Market
Cables
Solar Cable Market