
 Cable Testers Market | 2026-2036
Cable Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Testers Market Analytics
Leasing-based procurement for high-end test equipment is reconfiguring competitive dynamics for mid-tier contractors who previously faced capital barriers. Fluke Networks leverages its calibration-service infrastructure to sustain recurring revenue alongside hardware sales. Keysight Technologies anchors its position through R&D intensity in millimeter-wave cable characterization. Viavi Solutions Inc. competes by specializing in modular platforms that reduce fleet redundancy for telecom operators.
A cable tester is an electronic instrument that validates electrical continuity, signal integrity, and transmission performance across copper, fiber, and coaxial conductors, typically measuring parameters such as insertion loss, return loss, and crosstalk with precision to decimal-decibel resolution. Its primary purpose is to certify that installed cabling meets industry performance standards before network activation, preventing costly downstream failures in data centers and broadband infrastructure. Handheld units dominate field-service workflows due to portability requirements, while rack-mounted systems serve centralized lab environments where throughput and automation drive value. Optical time domain reflectometry technology leads fiber-optic segments because submarine and metro deployments require precise fault-location capabilities across spans exceeding 100 kilometers.
FCC equipment authorization rules in the United States shape product development cycles by mandating electromagnetic-compatibility verification before commercial distribution. The EU AI Act and CE marking requirements under the Radio Equipment Directive influence how European vendors design automated diagnostic features and software-defined test routines. EMA and ECHA frameworks indirectly affect cable-tester supply chains through restrictions on hazardous substances in printed-circuit-board assemblies. Stakeholders must monitor how evolving cybersecurity certification for networked test instruments alters procurement criteria and vendor qualification timelines.
Market Dynamics
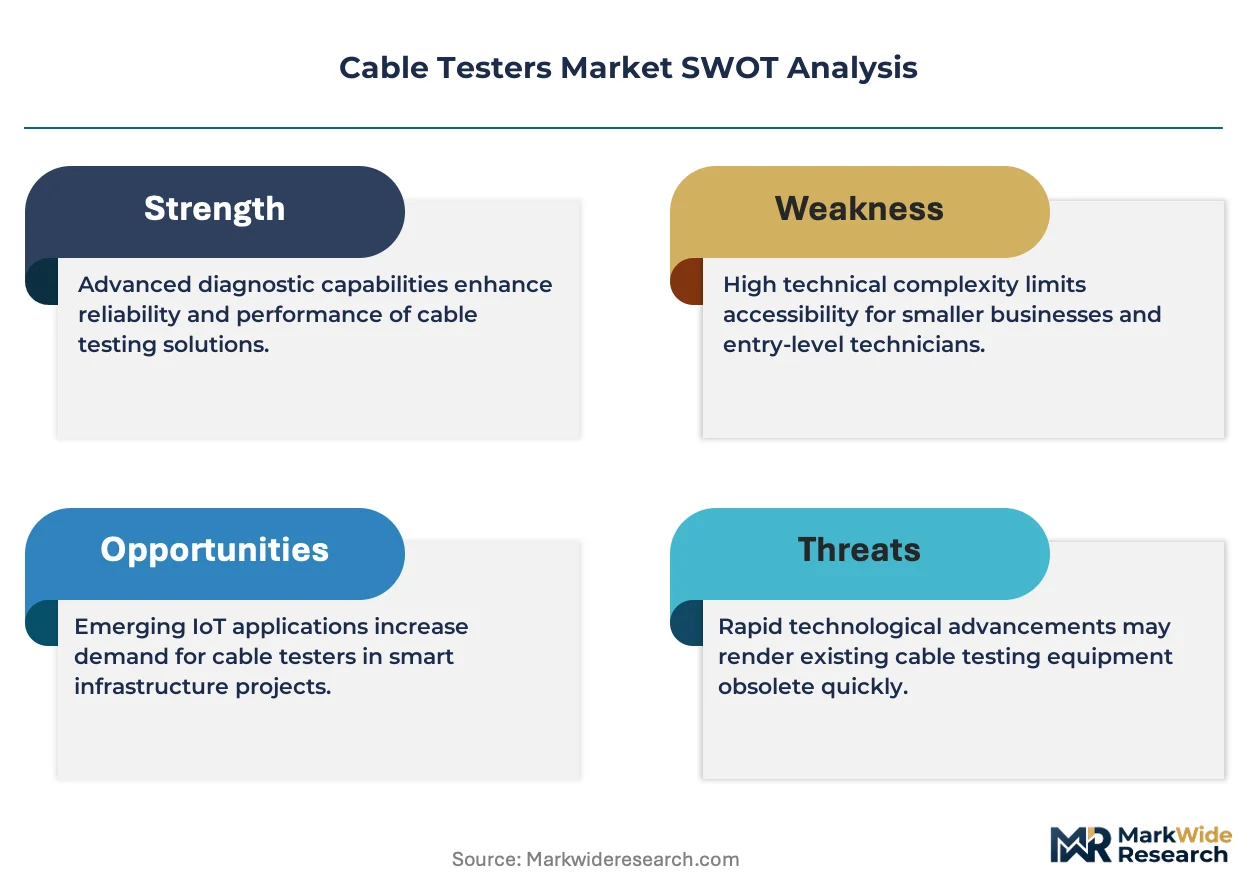
Leasing-based procurement is collapsing capital barriers for mid-tier contractors while compressing ownership cycles for high-end fiber certification equipment. This structural shift reconfigures vendor revenue streams toward recurring service contracts and away from one-time hardware sales.
Growth Catalysts
- EU Green Deal connectivity mandates:German telecom operators are expanding fiber certification programs to meet binding broadband deployment targets, creating sustained demand for OTDR-capable field units.
- Submarine cable fault-location precision:Japan-based system integrators are concentrating procurement of specialized OTDR modules for transoceanic fiber deployments exceeding 100-kilometer spans.
- Millimeter-wave characterization:5G backhaul densification requires cable testers capable of validating signal integrity at frequencies above 24 GHz, pulling R&D investment toward next-generation hardware.
Market Restraints
- Semiconductor input volatility:Printed-circuit-board assemblies for precision measurement modules face supply uncertainty from concentrated foundry capacity in East Asia.
- CE marking complexity under RED:The Radio Equipment Directive's electromagnetic-compatibility verification adds 4-6 months to European product launch timelines.
- Software-defined radio substitution:General-purpose spectrum analyzers with cable-testing firmware threaten standalone handheld unit volumes in price-sensitive segments.
Strategic Opportunities
- India smart city fiber backbone:Municipal broadband projects under the PLI scheme create first-mover advantage for vendors establishing local calibration infrastructure.
- Modular platform convergence:Swappable copper, fiber, and coaxial test heads on unified chassis reduce fleet redundancy for multi-technology operators.
- Cybersecurity certification tailwind:Networked test instruments with encrypted data logging qualify for preferential procurement in defense and critical infrastructure verticals.
Industry Challenges
- OTDR interpretation expertise gap:Field technicians lack training in trace analysis for complex fiber topologies, slowing deployment velocity and increasing callback rates.
- FCC authorization timeline compression:Equipment labs face backlog for electromagnetic-compatibility verification, delaying US commercial launches by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Testers Market |
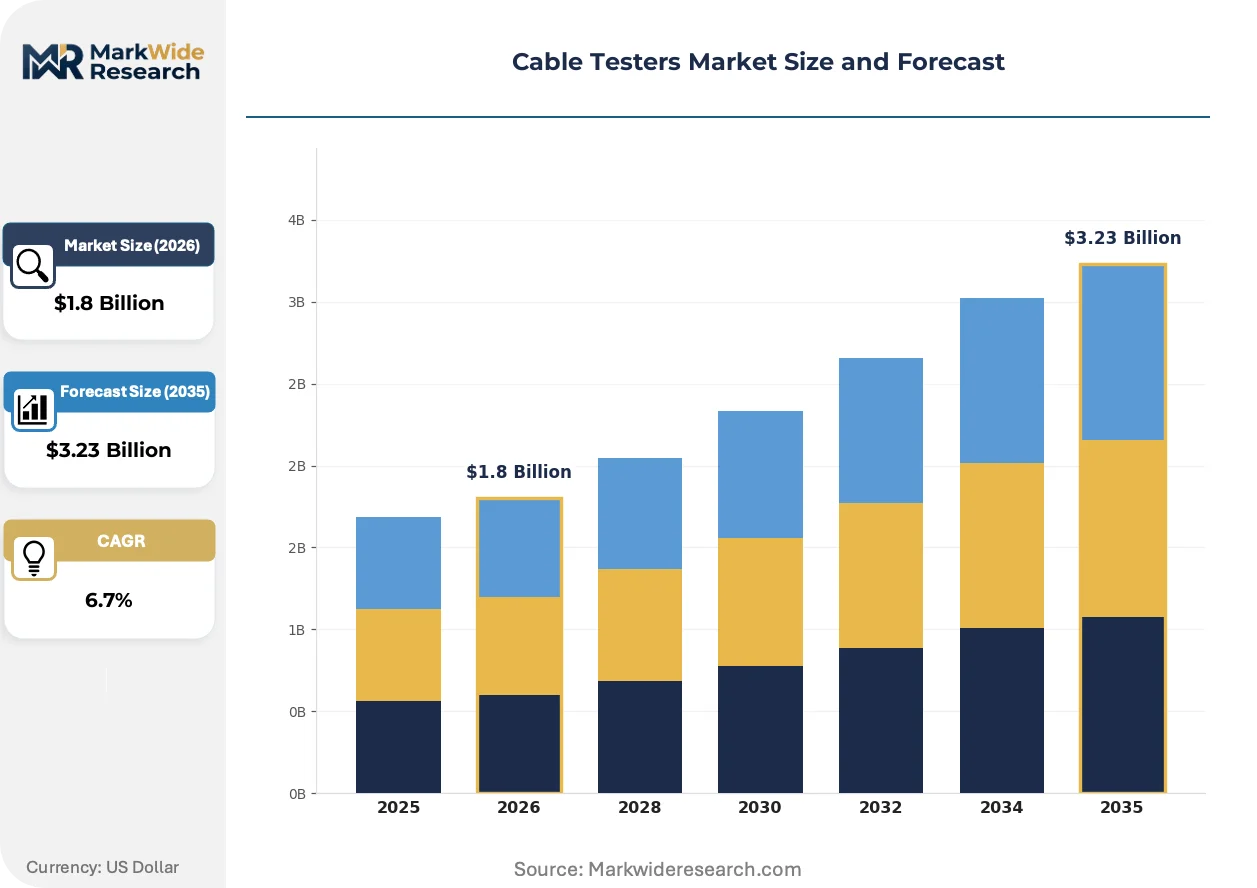
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Rack-mounted, Modular, Fixed Technology: Time Domain Reflectometry, Optical Time Domain Reflectometry, Ethernet, Coaxial End User: Telecom, IT, Construction, Broadcasting Connectivity: Wired, Wireless, Fiber, Twisted Pair |
| Companies Covered | Fluke Networks, Keysight Technologies, Viavi Solutions Inc., EXFO Inc., Anritsu Corporation, Ideal Industries, Klein Tools, Tektronix Inc., Megger Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Testers Market Evolving Landscape
Cloud-native test data management is collapsing the boundary between field instrumentation and enterprise asset systems, forcing vendors to rearchitect software stacks around API-first connectivity rather than isolated device operation.
Multi-function fiber characterization engines are collapsing the distinction between OTDR, optical loss test sets, and visual fault locators into single handheld platforms. Tier-one data center operators in Singapore and Ireland are standardizing on these consolidated units to reduce technician truck rolls. This compression eliminates redundant hardware SKUs while raising firmware complexity and calibration service attach rates.
REACH substance restrictions under ECHA frameworks are forcing redesigns of PCB solder masks and connector plating chemistries. Vendors serving European utilities must document full material declarations to maintain CE marking eligibility. German network operators now require supplier certificates of compliance as mandatory bid prerequisites, filtering out Asian contract manufacturers with incomplete chemical traceability.
Leasing penetration among North American electrical contractors is displacing outright purchase for units above fifteen thousand dollars. Equipment finance firms are embedding remote diagnostics and automated calibration scheduling as contract terms, capturing aftermarket revenue that previously flowed to manufacturer service departments. This channel shift concentrates bargaining power with lessors who negotiate fleet-wide pricing across multiple vendor portfolios.
Cable Testers Market Segmentation
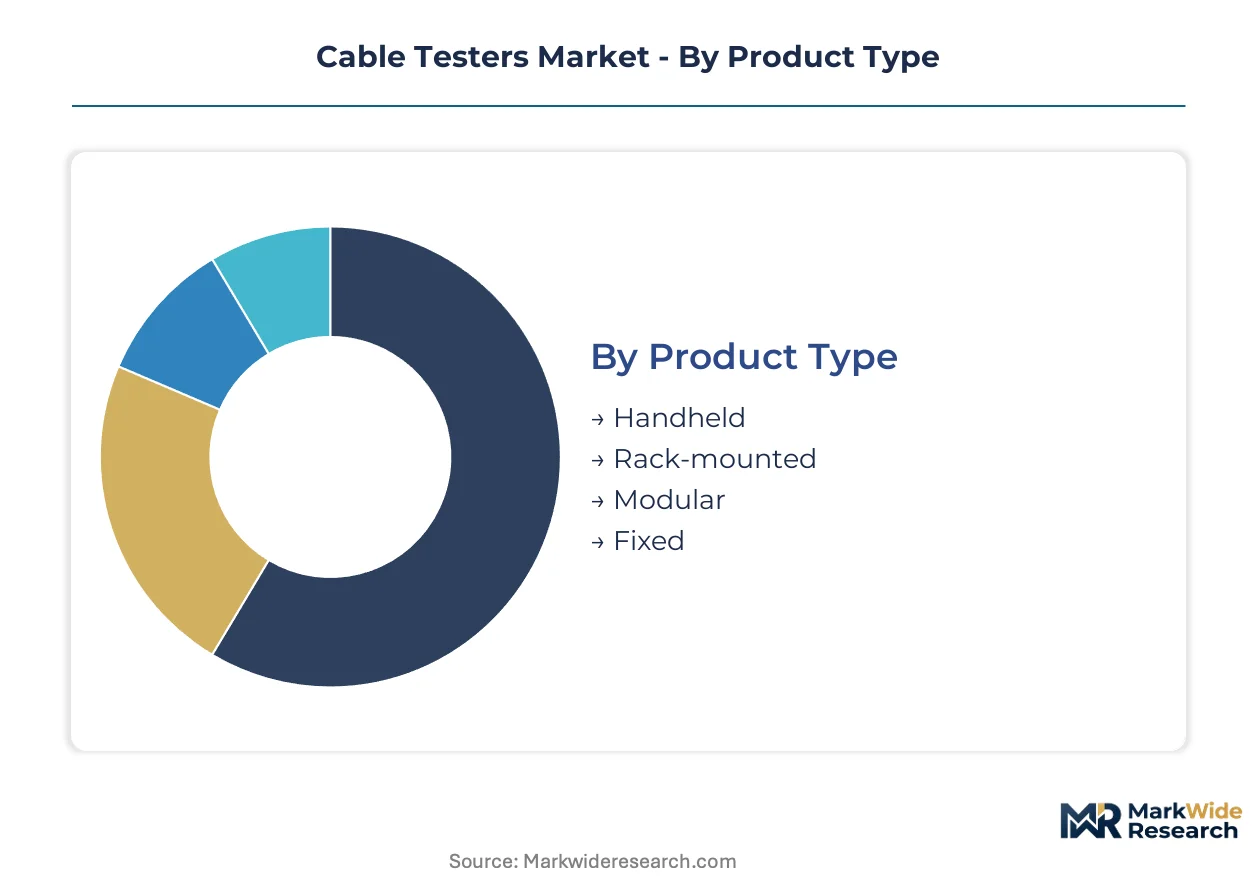
Segmentation in cable testers reflects divergent operational constraints across field deployment, centralized certification, and multi-technology convergence. Procurement patterns fragment sharply between capital-intensive rack systems for labs and portable units for technician mobility, while technology choices track infrastructure substrate—copper, fiber, or hybrid coaxial networks.
Product Type:
Mature form factors dominate revenue concentration, yet emerging chassis architectures are compressing fleet footprints for multi-technology operators.
- Handheld:Battery-powered portable units integrate OTDR, copper certification, and visual fault location into sub-two-kilogram enclosures. German telecom field crews under EU Green Deal fiber mandates deploy these for pole-mounted splice verification and subscriber drop certification.
- Rack-mounted:Stationary systems automate throughput testing for data center cable harness manufacturers and central office labs. Singapore-based hyperscale facilities specify these for pre-deployment burn-in of fiber trunk assemblies.
- Modular:Swappable test-head architectures reduce spare inventory for contractors serving mixed copper-fiber plant. Swappable test-head architectures reduce spare inventory for contractors serving mixed copper-fiber plant.
- Fixed:Permanent-installation monitors track degradation in submarine cable landing stations and utility substations. Permanent-installation monitors track degradation in submarine cable landing stations and utility substations.
Handheld units retain volume leadership; modular platforms hold the steepest expansion curve.
Technology:
Cost tiers separate precision instrumentation from commodity validation tools, with premium modules commanding calibration-service attach rates above thirty percent.
- Time Domain Reflectometry:Electrical pulse-echo techniques locate impedance discontinuities in twisted-pair and coaxial runs. Japanese system integrators specify TDR modules for building automation networks where copper persists for cost-sensitive horizontal cabling.
- Optical Time Domain Reflectometry:Laser-based backscatter analysis pinpoints fiber breaks, bends, and splice losses across spans exceeding 100 kilometers. OTDR engines absorb the majority of R&D investment as submarine and metro fiber densification accelerates.
- Ethernet:Protocol-aware testers validate Power over Ethernet budgets and 10G/25G signal integrity for enterprise LAN certification. Protocol-aware testers validate Power over Ethernet budgets and 10G/25G signal integrity for enterprise LAN certification.
- Coaxial:Legacy DOCSIS 3.1 and 4.0 test sets sustain demand in North American cable operator maintenance fleets. Legacy DOCSIS 3.1 and 4.0 test sets sustain demand in North American cable operator maintenance fleets.
OTDR commands the premium tier; Ethernet testers are expanding most quickly through PoE-driven smart building deployment.
End User:
Customer type determines specification intensity, with regulated utilities and defense contractors imposing cybersecurity and traceability requirements absent in commercial construction.
- Telecom:Carrier procurement concentrates on OTDR-capable field units for fiber-to-the-home rollout and 5G fronthaul validation. Indian operators under PLI scheme incentives are localizing test equipment sourcing with mandatory calibration infrastructure.
- IT:Enterprise data center operators prioritize automated copper certification and fiber loss test sets for structured cabling warranty programs. Enterprise data center operators prioritize automated copper certification and fiber loss test sets for structured cabling warranty programs.
- Construction:Electrical contractors favor leased handheld units for commercial building commissioning, with finance firms embedding remote diagnostics in contract terms. Electrical contractors favor leased handheld units for commercial building commissioning, with finance firms embedding remote diagnostics in contract terms.
- Broadcasting:Media infrastructure operators require 12G-SDI and SMPTE fiber characterization for mobile production and remote studio connectivity. Media infrastructure operators require 12G-SDI and SMPTE fiber characterization for mobile production and remote studio connectivity.
Telecom retains volume leadership; IT verticals are gaining share fastest through hyperscale data center construction.
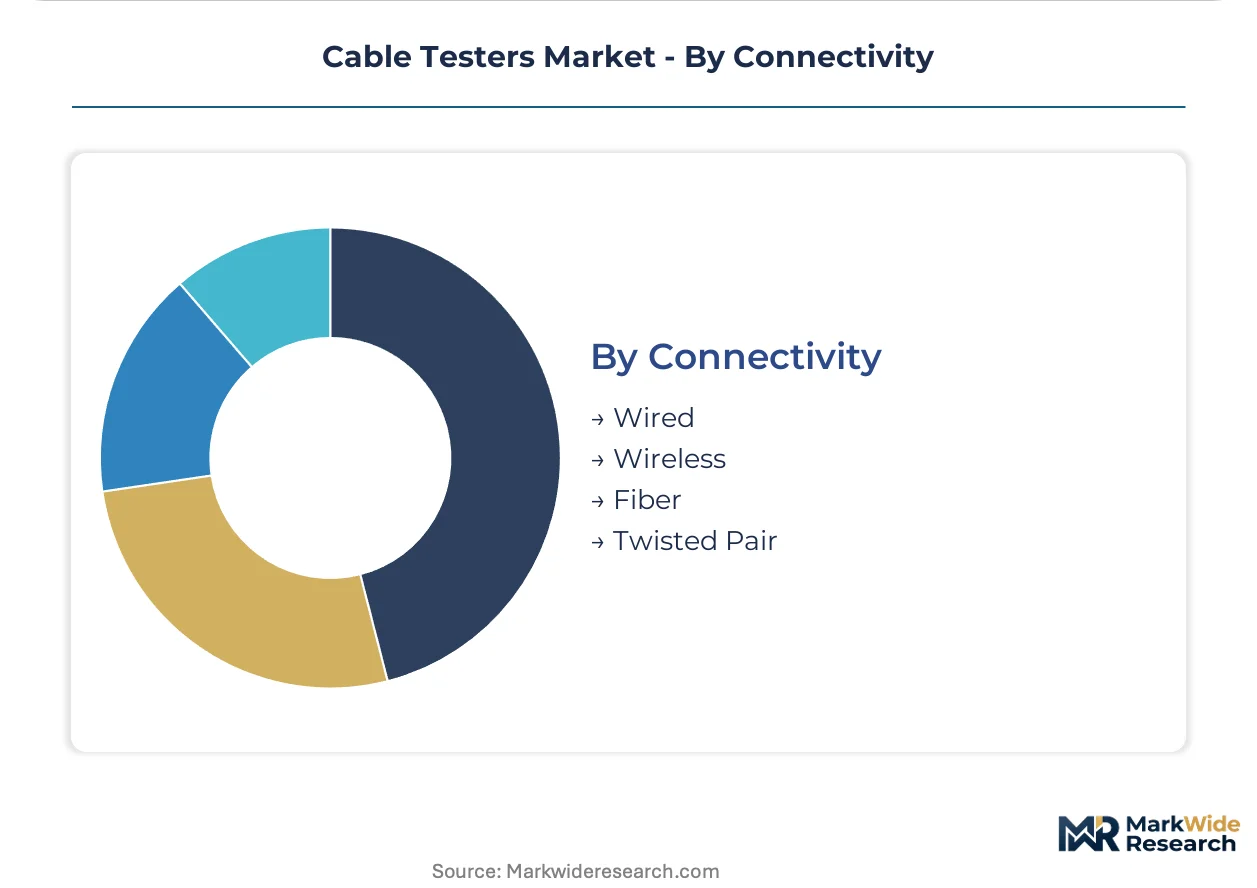
Connectivity:
Application context dictates media selection, with industrial environments tolerating wireless diagnostic links prohibited in secure facilities.
- Wired:USB-tethered and Ethernet-controlled testers dominate lab environments where electromagnetic isolation ensures measurement repeatability. USB-tethered and Ethernet-controlled testers dominate lab environments where electromagnetic isolation ensures measurement repeatability.
- Wireless:Bluetooth and Wi-Fi connectivity enable tablet-based trace visualization and cloud upload from confined spaces like manholes and aerial lifts. Bluetooth and Wi-Fi connectivity enable tablet-based trace visualization and cloud upload from confined spaces like manholes and aerial lifts.
- Fiber:Single-mode and multimode test interfaces constitute the core revenue pool, with APC polish requirements filtering out low-cost competitors. Single-mode and multimode test interfaces constitute the core revenue pool, with APC polish requirements filtering out low-cost competitors.
- Twisted Pair:Cat 6A and Cat 8 certification modules sustain replacement demand in copper-centric enterprise retrofits. Cat 6A and Cat 8 certification modules sustain replacement demand in copper-centric enterprise retrofits.
Fiber interfaces retain volume leadership; wireless connectivity is climbing the fastest as field workflow digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal broadband targets and India's PLI scheme for telecom equipment are redirecting procurement flows across major economies. Submarine cable landing stations and hyperscale data center clusters concentrate demand in specific coastal and metro zones.
United States
FCC equipment authorization rules govern electromagnetic-compatibility verification timelines for cable testers entering commercial distribution. Equipment labs in Maryland and California face persistent backlogs, delaying product launches by 8-12 weeks. Dallas-Fort Worth data center corridors drive rack-mounted system demand for pre-deployment fiber burn-in.
Germany
Telecom operators under binding EU Green Deal connectivity mandates are expanding fiber certification programs nationwide. CE marking under the Radio Equipment Directive adds 4-6 months to product launch timelines for European market entry. Munich and Frankfurt landing stations anchor submarine cable OTDR procurement for transoceanic span verification.
Japan
System integrators concentrate procurement of specialized OTDR modules for submarine cable deployments exceeding 100-kilometer spans. METI industrial standards shape precision measurement module specifications for domestic infrastructure projects. Yokohama and Kobe harbor zones host concentrated maintenance fleets for undersea fiber systems.
India
PLI scheme incentives require telecom operators to localize test equipment sourcing with mandatory calibration infrastructure. BIS certification protocols filter import eligibility for networked test instruments entering government broadband projects. Mumbai and Bengaluru smart city fiber backbones create first-mover opportunities for vendors establishing regional service centers.
Singapore
Hyperscale data center operators standardize on multi-function fiber characterization engines to reduce technician truck rolls. IMDA regulatory frameworks govern cybersecurity certification for networked test instruments in critical infrastructure. Tuas and Changi North data center clusters drive consolidated handheld platform adoption for structured cabling warranty programs.
Cable Testers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered service and hardware segments. Calibration-service infrastructure and leasing-based procurement models concentrate bargaining power with equipment finance firms negotiating fleet-wide pricing. Three archetypes dominate: full-stack instrumentation conglomerates, modular platform specialists, and regional calibration-service integrators. Dominant competitive moves include backward integration into semiconductor sourcing and geographic expansion through local calibration infrastructure partnerships.
Among North American instrumentation conglomerates, Fluke Networks and Keysight Technologies exemplify contrasting strategic positions. Fluke Networks represents the service-anchored archetype, leveraging calibration infrastructure to capture recurring revenue streams alongside hardware placement. Keysight Technologies occupies the R&D-intensive position, anchoring premium-tier positioning through millimeter-wave characterization capabilities. Viavi Solutions Inc. sits within the modular-specialist tier, competing through platform architectures that reduce fleet redundancy for multi-technology operators.
| Leading Market Players |
|---|
| Fluke Networks |
| Keysight Technologies |
| Viavi Solutions Inc. |
| EXFO Inc. |
| Anritsu Corporation |
| Ideal Industries |
| Klein Tools |
| Tektronix Inc. |
| Megger Group |
| Others |
Value Network & Pricing Analysis
The Shanghai-Long Beach transpacific corridor shapes cost dynamics for precision measurement modules, concentrating supply leverage among East Asian contract manufacturers while forcing downstream price differentiation between CE-marked European units and FCC-authorized North American variants.
Pricing Analysis
Certification level creates the primary spread, with CE-marked units under RED electromagnetic-compatibility verification commanding premiums over non-certified Asian alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks calibration service bundling and firmware customization depth. Cost compression in economy handheld segments intensifies because general-purpose spectrum analyzers with cable-testing firmware substitute at lower price points. Electrical contractors leasing through equipment finance firms show highest price sensitivity, while German telecom operators under EU Green Deal mandates absorb premium tiers for OTDR-capable field certification.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for printed-circuit-board assemblies and precision optical components. Concentrated foundry capacity in Taiwan, South Korea, and Japan feeds semiconductor inputs for measurement engines. REACH substance restrictions under ECHA frameworks draw from specialized solder mask chemistries and connector plating materials. Single-source vulnerability persists for OTDR laser diodes and high-speed ADCs. Distribution runs through authorized calibration-service integrators who control fleet-wide procurement negotiations for North American electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable participation in cable testers hinges on scarce OTDR trace-analysis expertise and captive calibration infrastructure, assets concentrated among incumbent service-anchored players with decade-long technician training pipelines.
For Market Incumbents: Pre-empt software-defined radio substitution by embedding encrypted data logging and cloud-native test data management as standard features, not premium add-ons. Deepen backward integration into semiconductor sourcing for OTDR laser modules to reduce single-source vulnerability. Lock channel control through exclusive calibration-service partnerships with equipment finance firms negotiating multi-vendor fleet pricing. For New Entrants and Emerging Players: Establish a beachhead in India's smart city fiber backbone projects under PLI scheme localization mandates, where mandatory calibration infrastructure requirements filter out established Asian competitors with incomplete chemical traceability. Target municipal broadband procurement with modular platform architectures that reduce spare inventory for mixed copper-fiber contractors. Lead with cybersecurity certification as a go-to-market wedge for defense and critical infrastructure verticals. For Investors and Strategic Acquirers: Regional calibration-service integrators with captive technician training pipelines and BIS-compliant infrastructure in India represent the most defensible acquisition profile. Long-term viability over the coming decade rests on software-defined test routine capabilities and API-first connectivity architectures. Watch for inflection when FCC equipment authorization backlogs compress below six weeks, signaling accelerated product launch velocity for well-capitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Localization | PLI scheme compliance in India filters competitors lacking BIS-certified service centers. |
| Modular Platform Convergence | Swappable test heads reduce fleet redundancy for multi-technology operators in Germany. |
| Cybersecurity Certification Investment | Encrypted data logging qualifies for preferential procurement in Singapore critical infrastructure. |
| Cloud-Native Test Data Management | API-first connectivity collapses boundaries between field instrumentation and enterprise asset systems. |
| Backward Integration into Optoelectronics | In-house OTDR laser diode sourcing mitigates Taiwan foundry concentration risk. |
Research Methodology
The analysis maps handheld field units, rack-mounted lab systems, modular platforms, and permanent-installation monitors, each validated through interviews with fiber network engineers, calibration service technicians, telecom procurement managers, and electrical contractor fleet operators. Primary fieldwork combined with secondary validation from FCC equipment authorization databases, ECHA REACH substance declarations, BIS certification protocols, and hyperscale data center capex disclosures. Bottom-up unit economics triangulated against top-down infrastructure spending projections across submarine cable, metro fiber, and data center verticals.
Assumptions around EU Green Deal connectivity target achievement, PLI scheme localization timelines, and semiconductor input cost trajectories were held fixed across scenarios while varying 5G backhaul densification pace and leasing penetration rates among North American contractors. Segmentation dimensions modeled include product form factor, underlying technology, end-user vertical, and connectivity interface. CAGRs were derived from installed base replacement cycles and net new deployment requirements across the projection horizon. Forecast inputs incorporated OTDR module procurement patterns from Japan-based system integrators and hyperscale fiber characterization engine standardization in Singapore.
Stress conditions across East Asian foundry capacity utilization, CE marking timeline compression, and software-defined radio substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including REACH substance restriction expansion, cybersecurity certification mandate acceleration, and FCC authorization backlog resolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Flexible Cables Market
Cables
Coaxial Cable Market
Cables
US Cables Market
Cables
Copper Stranded Wire Market
Cables
Low Voltage Cable Accessories Market
Cables
North America Copper Wire and Cable Market
Cables
Cable Testing Market
Cables
Sensing Cable Market
Cables
Cable Racks Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Downhole Cables Market
Cables
United States Cable Accessories Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Cable Management Accessories Market
Cables
LASER Light Cables Market