
 Medium Voltage Cables Market | 2026-2036
Medium Voltage Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Voltage Cables Market Intelligence
Demand from traditional power generation companies is rotating towards energy contractors leading large-scale infrastructure and renewable energy projects. This shift favors suppliers with project management capabilities. Prysmian Group leverages its global manufacturing footprint to serve these large projects. Nexans specializes in cable solutions for the renewable energy sector, while Southwire Company anchors its position in the United States through extensive channel control.
Medium voltage cables are electrical conductors designed to operate in the 1 kV to 36 kV range for power distribution. These cables typically feature a copper or aluminum conductor, a dielectric insulation layer like cross-linked polyethylene (XLPE), and a protective outer sheath. XLPE insulated cables command the largest share due to their superior dielectric strength and thermal properties. Within applications, renewable energy projects represent the fastest-growing source of new demand, driving a preference for underground installations in urban and environmentally sensitive areas.
International Electrotechnical Commission (IEC) standards, particularly IEC 60502, govern cable design and testing protocols. In Europe, CE marking is mandatory for market access, while in the United States, the EPA's regulations on chemical substances impact insulation material choices. Suppliers must navigate the trade-off between investing in advanced, compliant materials like TR-XLPE and maintaining cost-competitiveness for large-scale utility tenders.
Market Dynamics
The market's central tension lies in balancing the capital investment required for grid modernization with the cost-competitiveness demanded by utility-scale renewable energy projects. This dynamic forces a trade-off between advanced, compliant insulation materials and volume-driven procurement models.
Growth Catalysts
- Grid Modernization Mandates:Government-led initiatives, such as the United States' Inflation Reduction Act (IRA), accelerate investment in upgrading aging power distribution networks, directly boosting demand for new medium voltage cable installations.
- Renewable Energy Expansion:The build-out of wind and solar farms, particularly in countries like Germany and Spain, requires extensive underground and submarine medium voltage cables for power collection and transmission to the grid.
- Advanced Insulation Materials:The adoption of terminally-retardant cross-linked polyethylene (TR-XLPE) enhances cable longevity and performance in harsh environments, expanding the addressable market to more demanding industrial applications.
Market Restraints
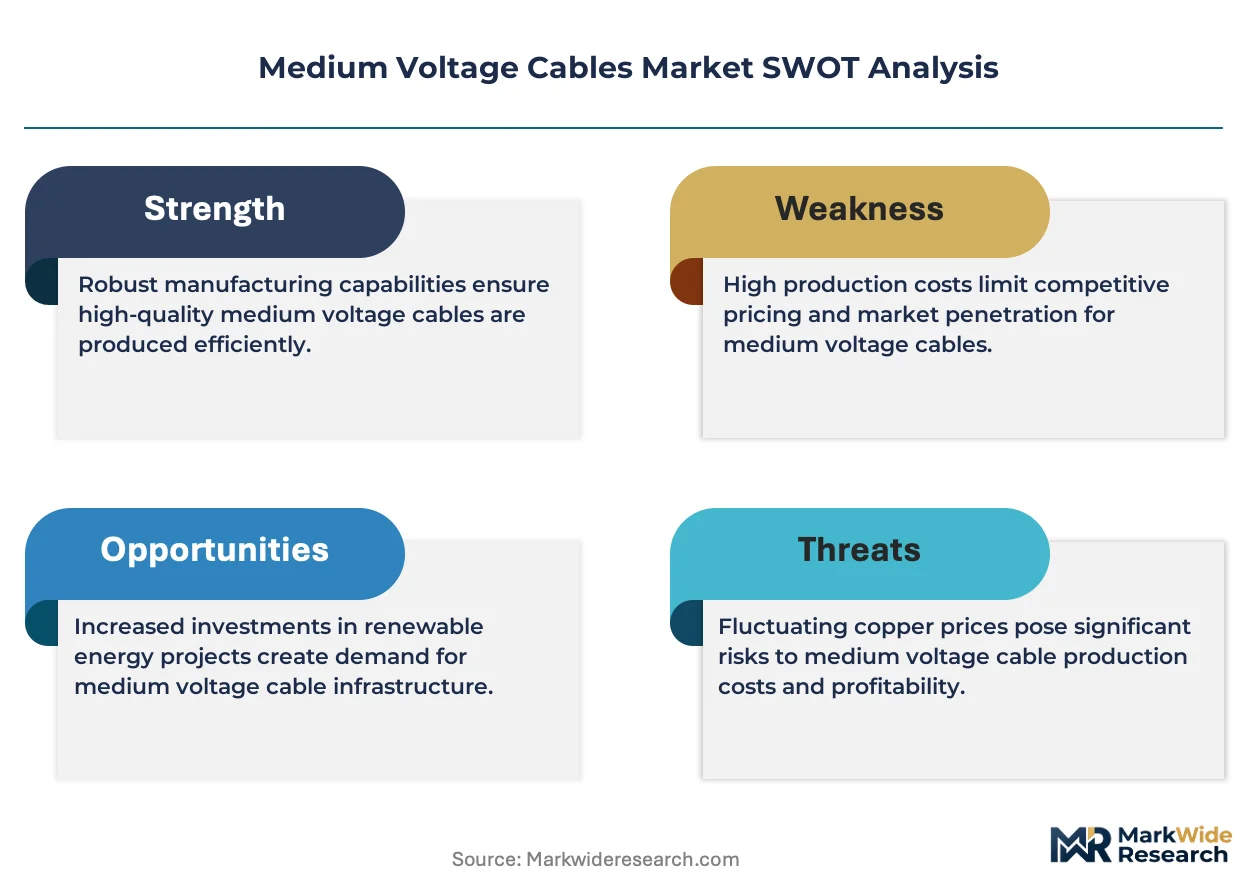
- Raw Material Volatility:Price fluctuations in core conductor materials, specifically copper and aluminum, create significant margin pressure and forecasting challenges for manufacturers engaged in long-term project contracts.
- Installation Complexity:The technical skill required for splicing and terminating high-performance cables, especially in underground or submarine settings, creates bottlenecks and increases project execution risk for energy contractors.
- Stringent Regulatory Compliance:Navigating disparate international standards, such as IEC 60502 in some regions and specific utility requirements in others, increases testing costs and can delay market entry for new product innovations.
Strategic Opportunities
- Electrification in Southeast Asia:Rapid urbanization and industrialization in countries like Vietnam and Indonesia present significant white-space opportunities for extending power distribution grids into previously underserved areas.
- Data Center Power Infrastructure:The exponential growth of hyperscale data centers requires highly reliable, high-capacity medium voltage power distribution systems, creating a new, high-value demand segment.
- Decarbonization Policies:The European Union's Green Deal and its associated grid-readiness initiatives provide a long-term policy tailwind for investments in cable infrastructure that supports electrification of transport and industry.
Industry Challenges
- Skilled Labor Shortages:A deficit of qualified cable jointers and technicians capable of handling advanced dielectric materials and complex installation environments constrains the pace of project deployment.
- Intensive Capital Expenditure:Expanding manufacturing capacity for specialized cables, such as those with TR-XLPE insulation, requires substantial upfront investment in production lines and testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Voltage Cables Market |
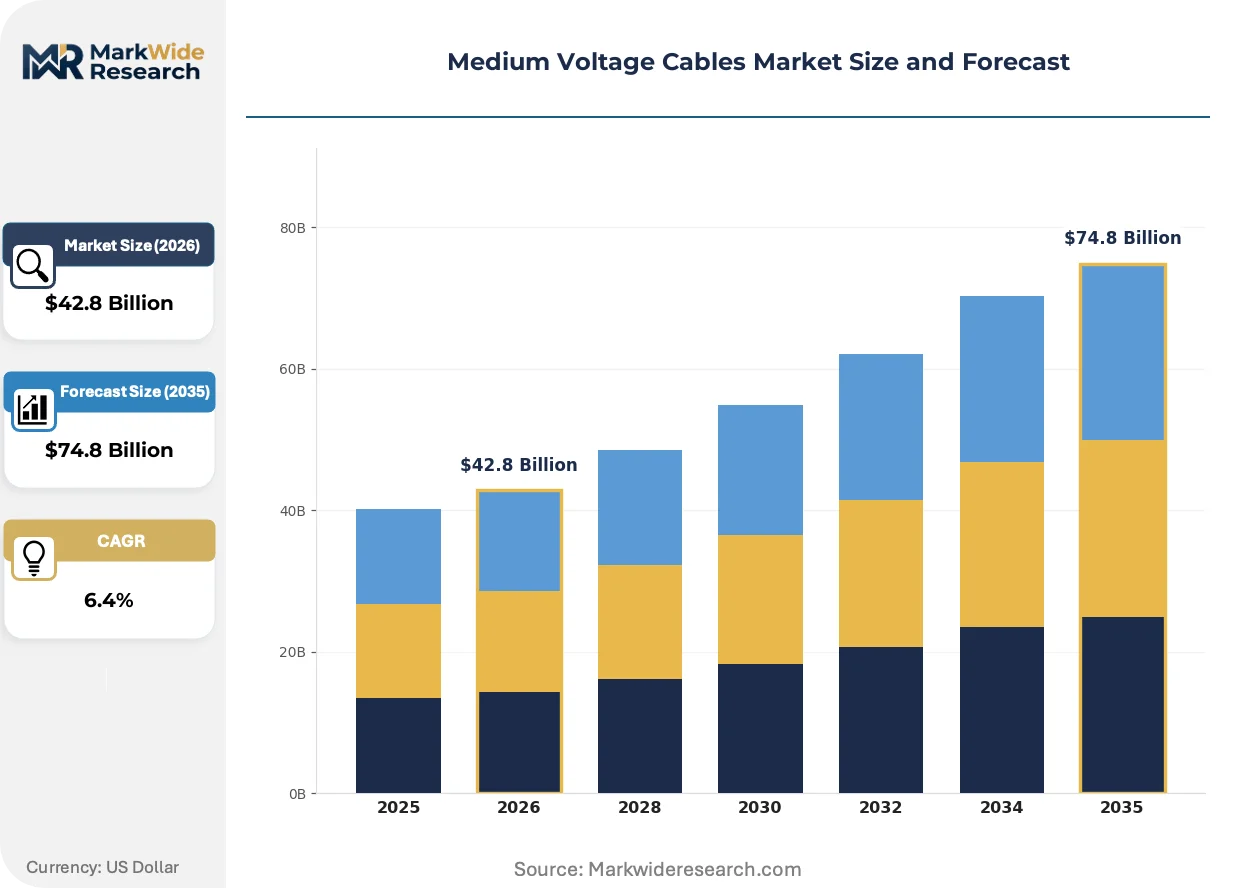
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: XLPE Insulated, EPR Insulated, PILC Cables, TR-XLPE Cables, Others Application: Power Distribution, Infrastructure Projects, Renewable Energy, Utility Transmission, Industrial Plants End User: Power Generation Companies, Energy Contractors, Electrical Substations, Municipal Service Providers Installation Type: Underground, Overhead, Submarine, Direct Buried |
| Companies Covered | Prysmian Group, Nexans, NKT A/S, Southwire Company, Sumitomo Electric Industries, Brugg Cables, General Cable Technologies Corporation, LS Cable & System, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Voltage Cables Market Strategic Shifts & Innovations
Material science advancements are converging with evolving project delivery models to redefine performance and reliability standards in the medium voltage cable market. These shifts prioritize lifecycle cost and operational resilience over simple initial purchase price, altering supplier-customer relationships.
Terminally-retardant cross-linked polyethylene (TR-XLPE) is an advanced insulation material engineered to mitigate water treeing, a primary cause of premature cable failure. Utilities and renewable energy developers are rapidly adopting TR-XLPE for critical infrastructure projects where long-term reliability is paramount. The superior longevity of this material is decomposing the traditional replacement cycle, shifting procurement focus towards total cost of ownership rather than upfront cable price.
The European Union's REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) regulation governs the chemical substances used in cable manufacturing, including plasticizers and flame retardants. This regulation imposes strict compliance and reporting duties on manufacturers, influencing the formulation of insulation and sheathing compounds. Cable producers targeting the EU market must invest in compliant material science to avoid market access restrictions, particularly affecting PVC-based cable components.
A demand-side shift sees large energy contractors, not just traditional utilities, managing procurement for major infrastructure and renewable projects. This change displaces transactional purchasing with a preference for suppliers offering integrated project management and logistical support. The trend is most visible in the United States and Europe on large-scale grid modernization and offshore wind projects.
Medium Voltage Cables Market Segmentation
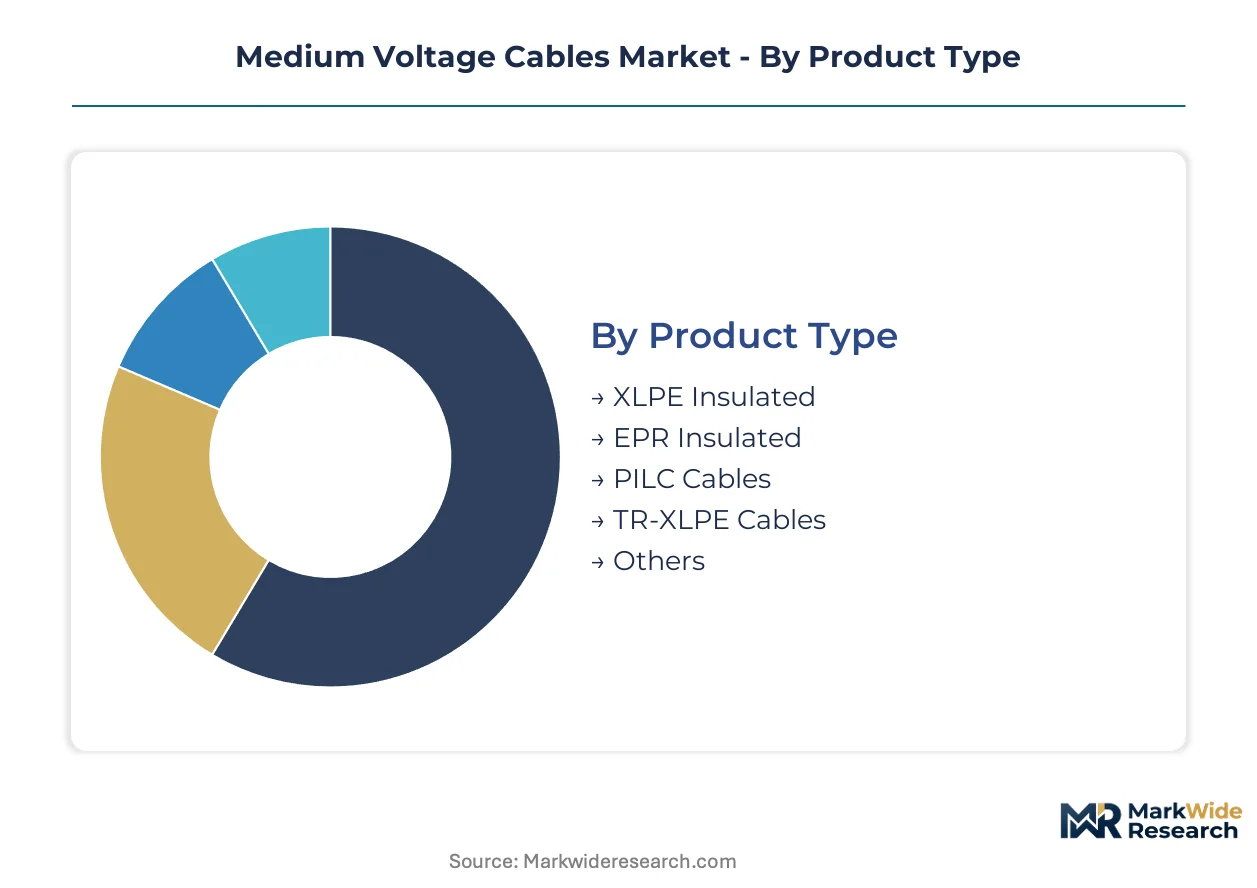
Understanding the varied segments within the medium voltage cables market reveals distinct demand patterns and compliance requirements. Each segment reflects specific operational needs, material preferences, and installation complexities across diverse power infrastructure projects. This detailed segmentation allows for targeted product development and strategic market positioning.
Product Type:
Regulatory frameworks heavily influence product type selection, with standards like IEC 60502 dictating material specifications and performance benchmarks across Europe and Asia. The EPA's regulations in the United States also shape insulation material choices, particularly for environmental compliance.
- XLPE Insulated:These cables utilize cross-linked polyethylene as a dielectric, offering superior thermal stability and dielectric strength for general power distribution. Their widespread adoption in utility grids across Germany and the United States establishes them as a foundational component for reliable electricity delivery.
- TR-XLPE Cables:Terminally-retardant cross-linked polyethylene insulation mitigates water treeing, significantly extending cable lifespan and enhancing reliability in demanding environments. Utilities and renewable energy developers in countries like Spain prioritize TR-XLPE for critical infrastructure where long-term performance is paramount.
- EPR Insulated:Ethylene propylene rubber insulation provides high flexibility and resistance to ozone and UV radiation, making it suitable for industrial applications.
- PILC Cables:Paper-insulated lead-covered cables are an older technology, still found in legacy grid infrastructure in some urban centers.
- Others:This segment includes various specialized insulation materials and composite cable designs tailored for niche applications.
Established volume favors XLPE Insulated; emerging adoption favors TR-XLPE Cables.
Application:
Demand concentration varies significantly across application areas, driven by the scale and technical requirements of different power projects. Each application demands specific cable characteristics related to voltage, current capacity, and environmental resilience.
- Renewable Energy:This application includes power collection and transmission from wind farms and solar installations, often requiring extensive underground or submarine cables. Projects in the North Sea for offshore wind, or large solar farms in the Southwestern United States, exemplify this demand.
- Power Distribution:This segment involves the delivery of electricity from substations to end-users within towns and cities, typically operating at 1 kV to 36 kV. Grid modernization initiatives in the United States and infrastructure upgrades in Southeast Asia are driving this segment.
- Infrastructure Projects:This encompasses large-scale public and private developments requiring dedicated power supply, such as railway electrification or new industrial parks.
- Utility Transmission:Cables in this category connect substations and power plants, forming the backbone of national grids.
- Industrial Plants:Manufacturing facilities and heavy industries require robust medium voltage cables for internal power distribution and machinery operation.
The expansion of Renewable Energy drives significant demand, while Infrastructure Projects present an evolving opportunity.
End User:
Procurement models are shifting among end-users, with large-scale projects increasingly managed by energy contractors who seek integrated solutions. This change influences how suppliers engage with the market and the services they must provide.
- Energy Contractors:These entities manage the design, procurement, and installation of large-scale power infrastructure and renewable energy projects. Their preference for suppliers offering comprehensive project management and logistical support is evident in European offshore wind developments.
- Power Generation Companies:Traditional power generators, including those operating fossil fuel and nuclear plants, require medium voltage cables for internal plant distribution and grid connections. These companies often have established procurement channels.
- Electrical Substations:Substations use medium voltage cables for internal connections and for interfacing with distribution networks.
- Municipal Service Providers:Local government-owned utilities procure cables for maintaining and expanding urban power distribution networks.
Traditional utility procurement remains substantial, but specialized contractors are gaining influence in large-scale projects.
Installation Type:
Environmental considerations and operational resilience are key drivers for different installation types, impacting cable design and project execution. Urbanization and the need for grid hardening against extreme weather events influence these choices.
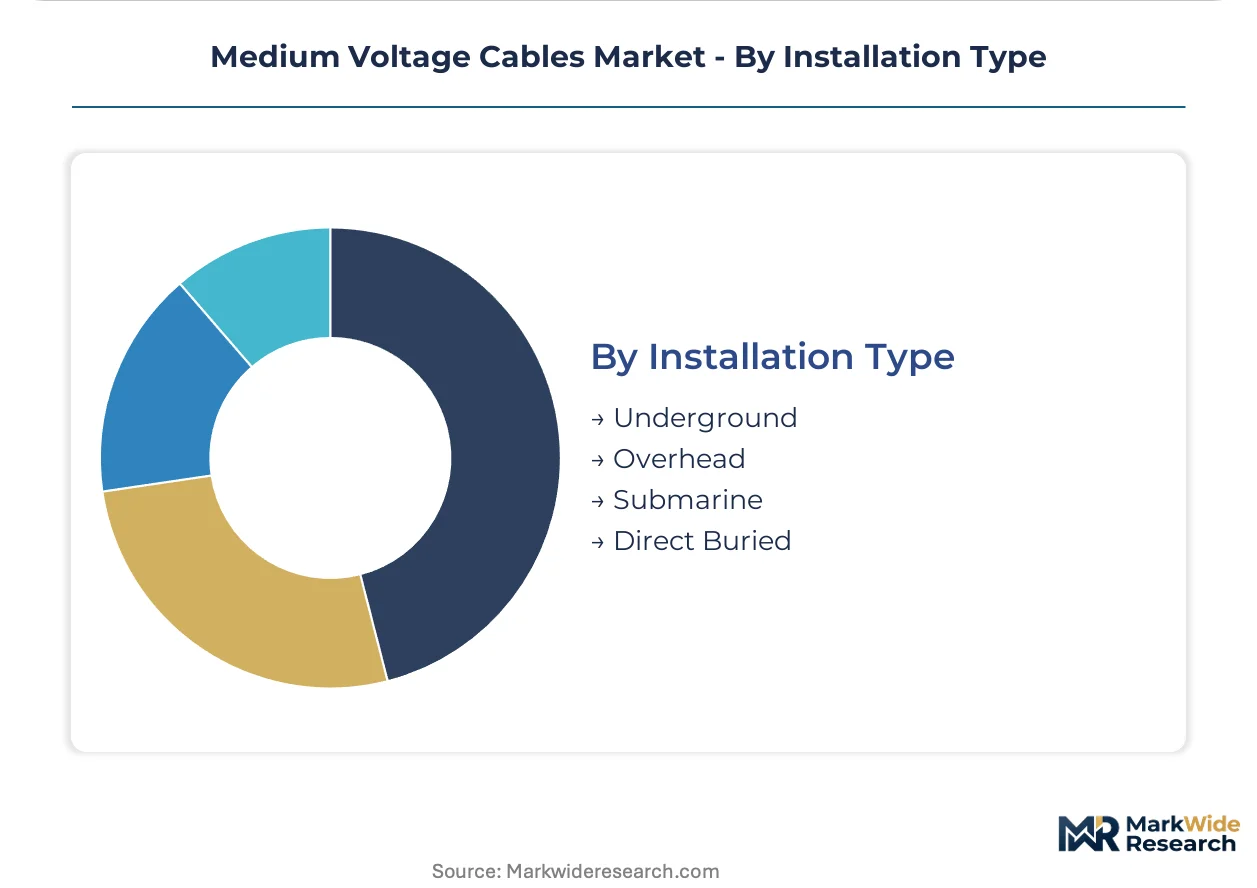
- Underground:Cables installed beneath the surface offer enhanced aesthetics, reduced exposure to weather, and increased security for power delivery in urban areas. Cities like London and New York increasingly favor underground installations for grid resilience.
- Submarine:These specialized cables are designed for underwater environments, connecting offshore wind farms to mainland grids or linking islands. Projects in the North Sea and along the coastlines of Japan demand robust submarine cable solutions.
- Overhead:Cables suspended on poles are a cost-effective solution for power distribution in rural and less densely populated areas.
- Direct Buried:This method involves placing cables directly into the ground without conduits, often used in less congested areas to reduce installation costs.
The need for reliable urban power underpins Underground installations, with specialized engineering supporting Submarine projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of medium voltage cables from European manufacturers to infrastructure projects in Southeast Asia highlights evolving supply dynamics. Demand concentrates in regions undertaking extensive grid modernization and renewable energy build-outs. Policy incentives and regulatory frameworks heavily influence investment patterns across diverse geographies.
United States
Grid modernization mandates from the Inflation Reduction Act (IRA) accelerate investment in upgrading aging power distribution networks. The EPA's regulations impact insulation material choices, while extensive infrastructure upgrades across California and Texas require high-reliability cable installations for expanding urban and industrial centers.
Germany
Renewable energy expansion, particularly offshore and onshore wind farms, requires extensive underground and submarine medium voltage cables. CE marking is mandatory for market access, with the North Sea region demanding robust submarine cable solutions for connecting wind farms to the national grid.
China
Rapid urbanization and industrialization necessitate significant investment in new power distribution grids across China. GB standards govern cable design and testing, ensuring product quality for domestic projects, particularly in large-scale infrastructure developments within the Yangtze River Delta region.
India
Electrification initiatives and infrastructure development projects are extending power distribution grids into underserved areas. The CEA sets technical standards for power system components, with major industrial corridors like the Delhi-Mumbai Industrial Corridor requiring robust power infrastructure for new manufacturing facilities.
Spain
The build-out of solar and wind farms drives demand for underground medium voltage cables to integrate renewable energy into the grid. IEC 60502 standards are widely adopted, and utilities in Andalusia prioritize TR-XLPE cables for critical infrastructure projects, ensuring long-term reliability.
Medium Voltage Cables Market Key Industry Players
Player mix skews toward large, vertically integrated manufacturers with global operational footprints. The market structure exhibits a tiered consolidation, with a few dominant players alongside numerous regional specialists and niche providers. Strategic archetypes include diversified industrial conglomerates and specialized cable solution providers focusing on specific applications. Companies primarily engage in capacity expansion and strategic partnerships to secure market share in key growth regions.
Among the established global manufacturers, Prysmian Group exemplifies a broad portfolio and extensive manufacturing base, supporting large-scale infrastructure projects worldwide. This Italian-based industrial conglomerate maintains a significant presence across diverse geographies. Nexans, a French-based company, occupies a strong position in cable solutions for the renewable energy sector, emphasizing specialized technical offerings. Southwire Company, an American manufacturer, anchors its competitive positioning through extensive channel control and robust distribution networks within the United United States market, serving both utilities and contractors.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT A/S |
| Southwire Company |
| Sumitomo Electric Industries |
| Brugg Cables |
| General Cable Technologies Corporation |
| LS Cable & System |
| ABB |
| Others |
Cost & Logistics Intelligence
Project-based contracts for medium voltage cables lock in both supply access and price visibility for large-scale infrastructure developments. This structure balances manufacturer capital investment with utility procurement needs.
Pricing Analysis
The technology-generation pricing gap differentiates standard XLPE cables from advanced TR-XLPE solutions. Contract-based long-term offtake agreements dominate, with price differentiation driven by insulation material quality and specific regulatory compliance certifications like CE marking. Margin pressure stems from volatile copper and aluminum prices, impacting manufacturers engaged in long-term project contracts. Utility-scale renewable energy projects exhibit high price sensitivity, while critical infrastructure developers prioritize long-term reliability over initial cost.
Supply Chain Analysis
Inventory optimization for medium voltage cables balances just-in-time delivery with strategic reserves for large projects. Manufacturing supply concentrates in Europe, the United States, and Asia, drawing heavily from global sources for copper and aluminum. Raw material volatility for conductors and specialized insulation compounds like XLPE represents a significant structural risk. Distribution runs through established utility procurement channels and increasingly through large energy contractors managing project logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medium voltage cables market requires a strong substitution defense as distributed generation and smart grid technologies reduce reliance on traditional large-scale cable networks. Incumbents must navigate this shift by offering integrated solutions.
For Market Incumbents:Shield existing market share by investing in advanced material R&D, particularly for TR-XLPE, which extends cable longevity and decomposes traditional replacement cycles. Consolidate manufacturing capacity in regions with high grid modernization mandates, such as the United States, to meet increased demand. Form strategic partnerships with large energy contractors to secure project-based procurement and leverage their project management capabilities. Strengthen channel control in key markets to counter emerging competition.
For New Entrants and Emerging Players:Differentiate on specialized cable solutions for high-growth, niche applications. Target the electrification white-space opportunities in Southeast Asia, where rapid urbanization creates demand for new power distribution grids. Focus on data center power infrastructure, offering highly reliable, high-capacity medium voltage systems. A go-to-market angle emphasizing localized compliance expertise and agile project delivery can penetrate underserved markets.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized cable solution providers with advanced material expertise, particularly in TR-XLPE, and strong project management capabilities. The market exhibits long-term viability, supported by sustained decarbonization policies and grid modernization initiatives. Acquisition targets should demonstrate strong intellectual property in insulation materials or extensive channel control in high-growth regions. The pace of government-mandated grid modernization spending serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for TR-XLPE | Boosts production of advanced insulation materials, meeting demand from critical infrastructure projects. |
| Joint Ventures with Energy Contractors | Integrates cable supply with large-scale project execution, enhancing market access in Europe. |
| R&D in Sustainable Insulation Materials | Ensures compliance with EU REACH regulations and supports decarbonization policies. |
| Geographic Expansion into Southeast Asia | Captures white-space opportunities from rapid urbanization and industrialization in Vietnam. |
| Digitalization of Supply Chain Logistics | Reduces lead times and manages raw material volatility for copper and aluminum. |
Research Approach
Initial hypotheses were tested against primary input from utility planning officers, renewable energy developers, and material science engineers, then refined through iterative processes. This approach combined in-depth interviews with extensive secondary validation from sources like IEC standards, EPA regulations, and national grid development plans. Bottom-up data aggregation from specific projects and top-down market sizing provided robust triangulation.
Variance decomposition identified key drivers impacting medium voltage cable demand across the analysis window. The analytical framework modeled market segments by product type, application, end-user, installation type, and regional regulatory compliance. Compound annual growth rates were derived from projected grid modernization investment and planned renewable energy capacity additions. This comprehensive segmentation ensured granular forecast accuracy.
Material uncertainties — such as geopolitical instability or unforeseen technological disruptions — sit outside the modeled envelope, influencing long-term market trajectories. Forecasts reflect assumptions regarding sustained grid modernization and renewable energy expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Management Accessories Market
Cables
Global Wires and Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Network Cable Tester Market
Cables
Cable Tags Market
Cables
Military Fiber Optic Cables Market
Cables
Polyurethane Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
South Africa Wire and Cable Market
Cables
Global Cable Tie Market
Cables
Data Center Wire and Cable Market
Cables
Cable Tray Market
Cables
North America Patch Cable Market
Cables
Multicore Cables Market
Cables
Aluminium Battery Cable Market
Cables
Hybrid Cables Market