
 Anti-Static Space Wires Market | 2026-2036
Anti-Static Space Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Space Wires Market Insights
Project finance tied to satellite constellation deployments is reshaping competitive access in the Anti-Static Space Wires Market, enabling asset-light entrants to bid on prime contractor programs without captive manufacturing. W. L. Gore & Associates leverages its vertical integration in expanded PTFE to dominate high-reliability shielded cable supply for geostationary programs. TE Connectivity anchors its position through backward integration into precision connector termination, bundling wire harnesses with value-added assembly. Prysmian Group competes on manufacturing scale across European launch supply chains, sustaining dual-source relationships with ArianeGroup.
Anti-static space wires are specialized conductive cabling systems engineered to dissipate electrostatic charge accumulation in orbital environments, typically incorporating carbon-loaded or metallic filler layers within PTFE or polyimide dielectric insulation to maintain surface resistivity below specified thresholds. These conductors prevent spacecraft charging anomalies that can trigger arc discharges, protecting avionics and power distribution in vacuum conditions. Shielded multi-core configurations lead product mix due to their integration density advantages in satellite bus architectures, while PTFE material grades command premium positioning because of their outgassing performance under thermal vacuum cycling. Launch vehicle application demand is accelerating fastest, driven by reusable booster programs requiring rapid harness turnaround and standardized cable qualification.
FAA launch licensing requirements and NASA-STD-4003 spacecraft charging standards shape material selection and qualification protocols for domestic suppliers, while ESA ECSS-Q-ST-70-11C imposes comparable outgassing and electrostatic discharge controls across European procurement. REACH restrictions on perfluorinated compound formulations are pressuring PTFE supply chains to certify alternative dielectric chemistries without sacrificing orbital performance. Stakeholders must monitor evolving debris mitigation regulations that could mandate extended mission lifetimes, requiring wire insulation systems to demonstrate enhanced radiation tolerance and thermal aging resistance beyond current qualification baselines.
Market Dynamics
Satellite constellation operators are compressing procurement cycles from multi-year custom programs to commodity-style annual contracts, forcing wire manufacturers to requalify materials against accelerated mission profiles without sacrificing NASA-STD-4003 certification baselines.
Growth Catalysts
- Launch cadence acceleration:Reusable booster programs at Cape Canaveral and Vandenberg Space Force Base are consuming standardized harness configurations at volumes that amortize qualification costs across multiple missions.
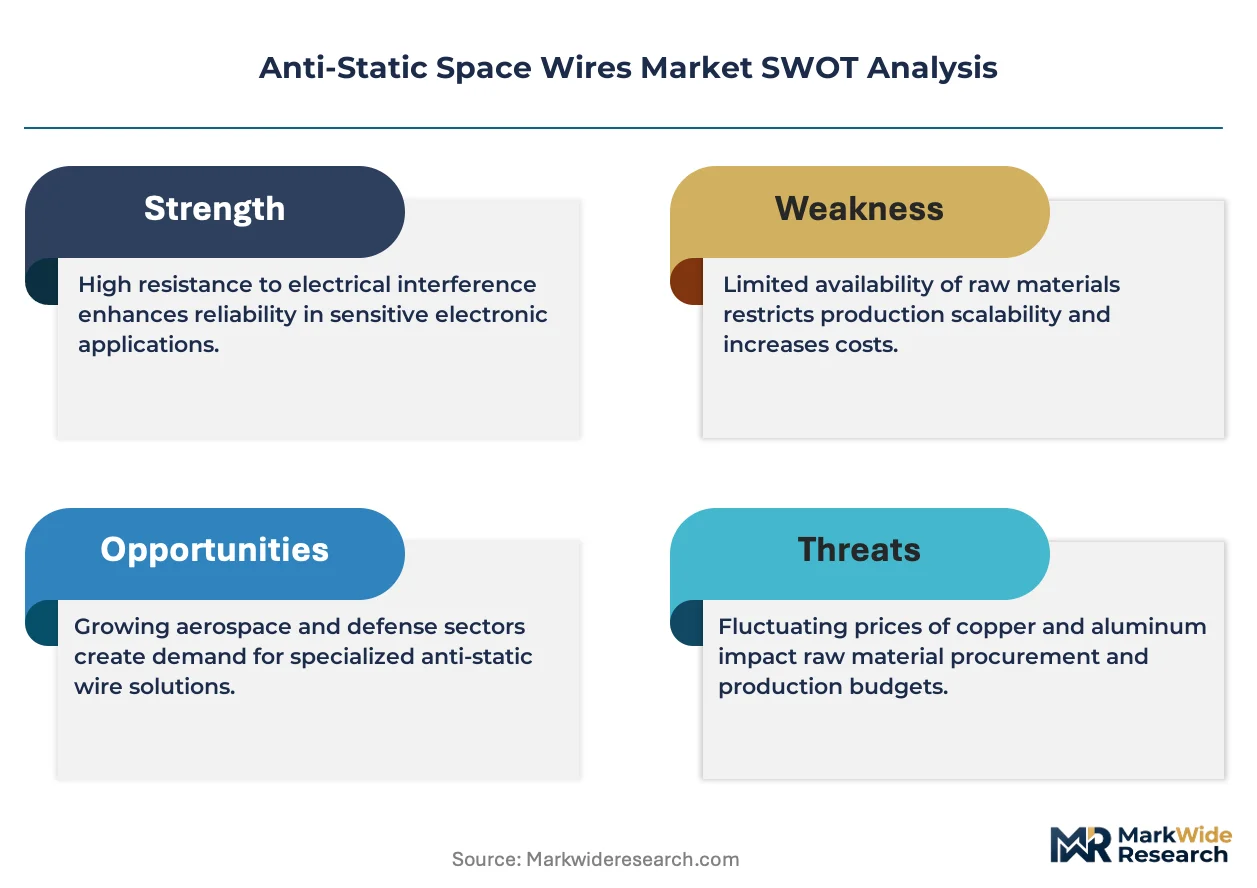
- NASA-STD-4003 updates:Tighter spacecraft charging mitigation standards are mandating carbon-loaded PTFE insulation for all geostationary and medium Earth orbit platforms, eliminating unshielded conductor options from prime contractor specifications.
- Copper-silver alloy conductors:These materials are penetrating launch vehicle applications where rapid thermal cycling resistance outweighs the mass penalties of traditional silver-plated copper cores.
Market Restraints
- PTFE feedstock concentration:Expanded PTFE membrane supply chains concentrate among three North American chemical processors, exposing harness assemblers to fluoropolymer price volatility when semiconductor demand competes for resin allocation.
- REACH perfluorinated compound restrictions:ECHA pressure on long-chain fluorinated formulations is forcing European suppliers to recertify alternative dielectric chemistries through multi-year outgassing validation protocols.
- Polyimide substitution ceiling:Radiation-hardened polyimide insulation cannot match PTFE's thermal vacuum stability for geostationary missions, limiting downward material substitution in premium orbital segments.
Strategic Opportunities
- Indian launch market opening:ISRO's commercialization push at Satish Dhawan Space Centre creates demand for ITAR-compliant wire harnesses that bypass traditional US-European supply channels.
- Lunar surface power distribution:Artemis program lunar landers require anti-static cabling that maintains surface resistivity through regolith abrasion and extreme thermal gradients.
- Dual-use defense crossover:Space Force rapid acquisition pathways are accepting modified automotive-grade shielded cables for tactical satellite buses, compressing supplier qualification timelines.
Industry Challenges
- Vacuum chamber certification backlog:Thermal cycling validation at accredited facilities now extends eighteen months, delaying new product introductions regardless of technical readiness.
- Orbital debris mitigation compliance:Extended mission lifetime mandates are requiring insulation systems to demonstrate radiation tolerance beyond current 15-year qualification baselines without redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Space Wires Market |
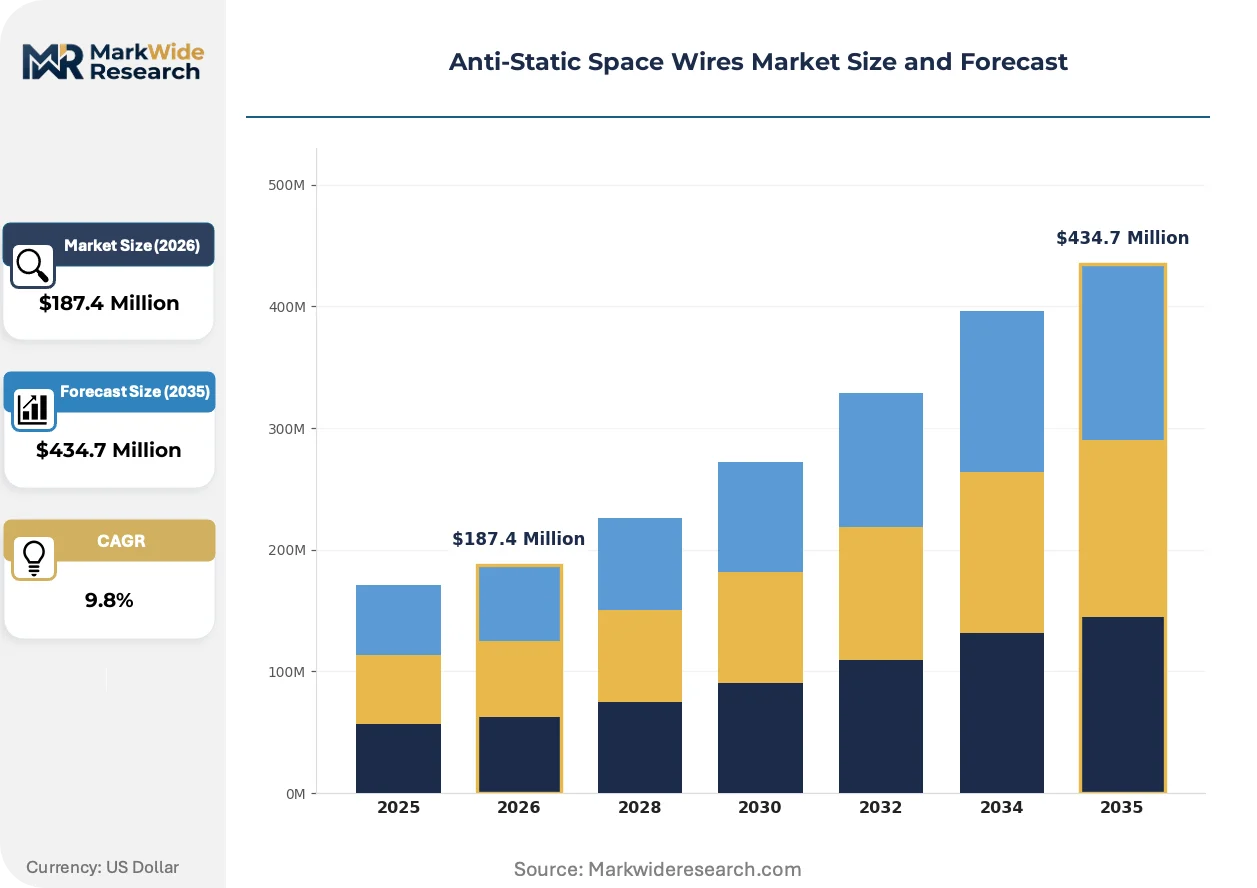
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Core, Multi-Core, Shielded, Unshielded End User: Aerospace, Military, Telecommunications, Automotive Material: PTFE, PVC, Polyethylene, Nylon Application: Satellite, Launch Vehicles, Space Probes, Scientific Instruments |
| Companies Covered | W. L. Gore & Associates, TE Connectivity, Nexans, Prysmian Group, Amphenol Corporation, Leoni, Axon' Cable, Lapp Group, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Space Wires Market Trends and Innovations
Material science advances and procurement model compression are converging to redefine competitive advantage around qualification velocity rather than heritage performance alone.
Carbon nanotube-doped conductor coatings are rendering obsolete traditional metallic filler layers in PTFE-insulated harnesses. Small satellite bus manufacturers are specifying these materials for constellation programs requiring ten-thousand-unit annual volumes. The technology is rendering obsolete the cost structure of hand-laid shielding in favor of extruded composite conductors that cut assembly labor by half.
REACH restrictions on perfluorinated compound formulations are forcing European suppliers to submit alternative dielectric chemistries through ESA ECSS-Q-ST-70-11C outgassing protocols. This regulatory friction is compressing the supplier base to those with captive polymer development capabilities. Launch vehicle harness segments are responding by dual-sourcing PTFE and polyimide configurations to maintain program continuity.
Prime contractors are unbundling wire harness procurement from system integration contracts, creating direct purchasing relationships between constellation operators and specialized cable assemblers. This channel disintermediation is displacing the traditional tiered supplier structure in low Earth orbit satellite programs. The shift is most visible in United States procurement, where Space Force rapid acquisition pathways now permit direct awards to qualified harness specialists.
Anti-Static Space Wires Market Segmentation
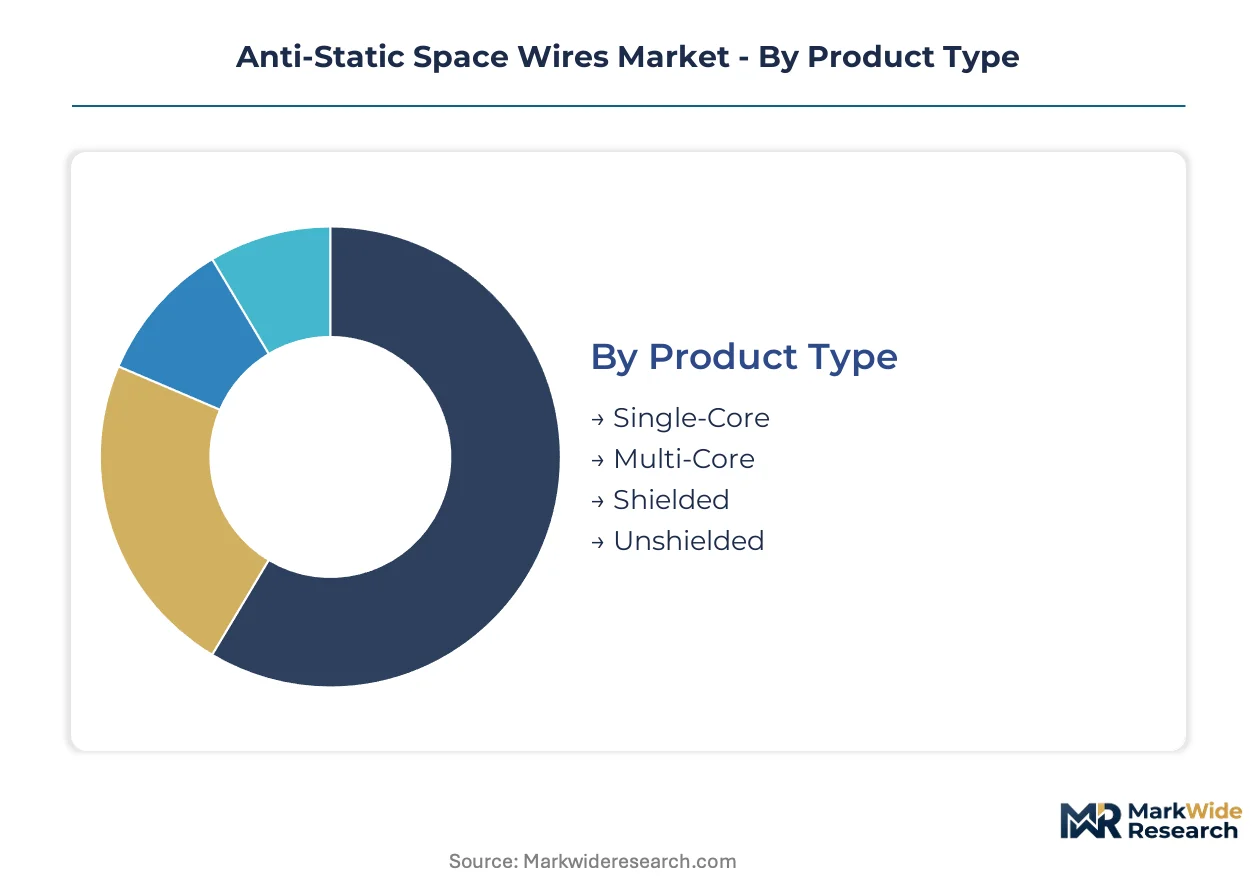
Anti-static space wire procurement cycles vary dramatically by orbital mission profile, with launch vehicle harnesses turning over in months versus geostationary satellite cabling lasting decades. Segment boundaries are blurring as constellation operators demand standardized configurations across previously custom product categories.
Product Type:
Shielded multi-core configurations compress procurement cycles to commodity-style annual contracts, while unshielded single-core products linger in multi-year qualification pipelines for deep-space missions.
- Shielded:Carbon-loaded PTFE insulation with metallic braid shielding dissipates electrostatic charge in vacuum environments. Cape Canaveral launch cadence concentrates demand for standardized harness configurations that amortize qualification costs across reusable booster programs.
- Multi-Core:Bundled conductor architectures integrate power and signal distribution within single harness assemblies. Satellite bus manufacturers at Vandenberg Space Force Base specify these for constellation deployment density, though NASA-STD-4003 recertification extends lead times.
- Single-Core:Dedicated conductor lines for high-voltage power distribution in traditional geostationary platforms.
- Unshielded:Legacy configurations retained for specific scientific instrument grounding applications.
Shielded dominates installed base. Multi-core is where expansion concentrates.
End User:
Procurement authority is shifting from prime contractors to direct operator relationships, with telecommunications constellation developers compressing supplier margins fastest.
- Aerospace:Prime contractors bundle wire harnesses with satellite bus integration, though channel disintermediation is displacing this tiered structure. Space Force rapid acquisition pathways now permit direct awards to qualified harness specialists, collapsing traditional procurement timelines.
- Telecommunications:Constellation operators like Starlink and OneWeb specify ten-thousand-unit annual volumes with commodity-style contracting. Carbon nanotube-doped conductors are penetrating this segment as hand-laid shielding becomes cost-prohibitive at scale.
- Military:Space Force procurement anchors domestic consumption with ITAR-compliant supply chain requirements.
- Automotive:Modified automotive-grade shielded cables cross over for tactical satellite buses under rapid acquisition pathways.
Aerospace retains revenue concentration. Telecommunications is climbing the fastest.
Material:
REACH restrictions on perfluorinated compounds are forcing recertification timelines that favor suppliers with captive polymer development capabilities.
- PTFE:Expanded polytetrafluoroethylene maintains thermal vacuum stability through fifteen-year qualification baselines. ECHA pressure on long-chain fluorinated formulations is forcing European suppliers through multi-year outgassing validation, compressing the supplier base to North American chemical processors.
- Polyimide:Radiation-hardened insulation serves medium Earth orbit missions where thermal cycling resistance outweighs PTFE's outgassing performance. Launch vehicle harness segments dual-source PTFE and polyimide configurations to maintain program continuity amid regulatory friction.
- PVC:Ground-support equipment applications where orbital outgassing requirements do not apply.
- Nylon:Limited terrestrial aerospace uses with minimal spaceflight qualification.
PTFE dominates installed base. Polyimide is gaining share fastest.
Application:
Mission lifetime extension mandates are requiring insulation systems to demonstrate radiation tolerance beyond current baselines without redesign.
- Launch Vehicles:Reusable booster programs at Cape Canaveral and Vandenberg consume standardized harness configurations at volumes that amortize qualification costs. Copper-silver alloy conductors penetrate this segment where rapid thermal cycling resistance outweighs traditional silver-plated copper mass penalties.
- Satellite:Geostationary and medium Earth orbit platforms mandate carbon-loaded PTFE insulation under updated NASA-STD-4003 standards, eliminating unshielded conductor options from prime contractor specifications.
- Space Probes:Extended mission profiles require enhanced radiation tolerance and thermal aging resistance beyond current qualification baselines.
- Scientific Instruments:Specialized payload cabling with precision signal integrity requirements for observational platforms.
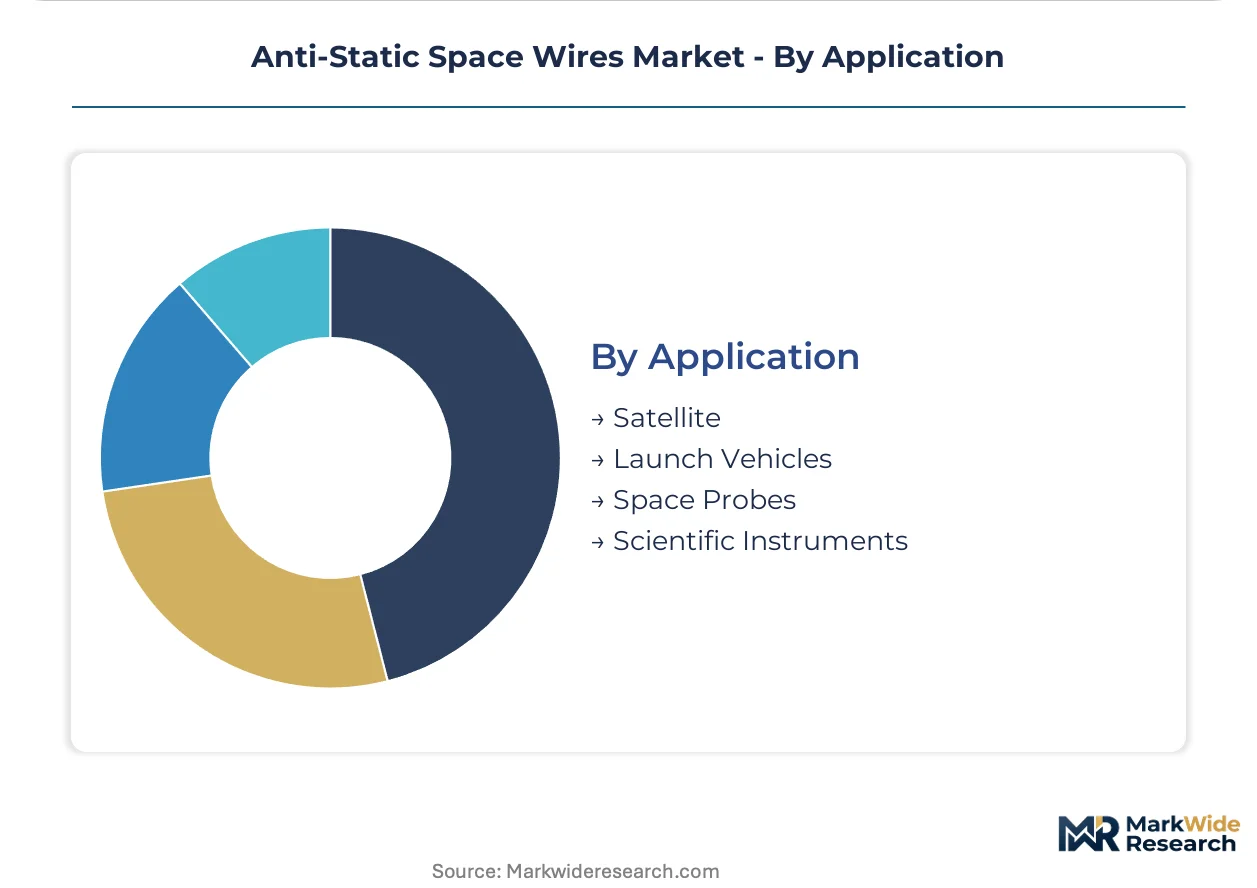
Satellite dominates installed base. Launch vehicles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch vehicle operators and satellite constellation developers concentrate procurement authority in jurisdictions with established aerospace infrastructure and permissive export control frameworks. National space agencies anchor domestic demand through qualification protocols that privilege locally certified suppliers.
United States
Cape Canaveral launch cadence and Vandenberg Space Force Base operations consume standardized harness configurations at volumes that amortize qualification costs. FAA launch licensing requirements and NASA-STD-4003 spacecraft charging standards shape material selection protocols for domestic suppliers. Colorado and California host prime contractor integration facilities that source directly from qualified harness specialists under Space Force rapid acquisition pathways.
France
ArianeGroup procurement sustains dual-source relationships with European wire manufacturers for Ariane 6 launch vehicle programs. ESA ECSS-Q-ST-70-11C outgassing and electrostatic discharge controls impose certification requirements across European supply chains. The Toulouse aerospace cluster anchors satellite bus integration activity with demand for shielded multi-core harnesses in geostationary programs.
Germany
REACH restrictions on perfluorinated compound formulations pressure PTFE supply chains to certify alternative dielectric chemistries. The country's national chemical regulator enforces multi-year validation protocols for orbital materials. Bavaria hosts precision connector termination facilities that bundle wire harnesses with value-added assembly for export markets.
Japan
METI space industry development programs support domestic qualification of carbon-loaded insulation for medium Earth orbit platforms. JIS standards govern material certification timelines that extend supplier relationships across mission lifecycles. The Nagoya aerospace corridor concentrates satellite component manufacturing with integrated harness procurement from regional specialists.
India
ISRO commercialization at Satish Dhawan Space Centre creates demand for ITAR-compliant wire harnesses that bypass traditional US-European supply channels. The country's national space agency relaxes import substitution mandates for critical orbital materials. Andhra Pradesh and Karnataka host emerging satellite manufacturing facilities that source anti-static cabling for constellation programs.
Anti-Static Space Wires Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with constellation operators and prime contractors. The supplier base concentrates around three strategic archetypes: vertically integrated polymer developers, precision connector assemblers, and manufacturing-scale cable producers. Consolidation pressures favor entities with captive qualification capabilities and accelerated certification velocity. Strategic moves center on backward integration into polymer development and geographic expansion into Indian launch markets.
Among US-based material developers, W. L. Gore & Associates exemplifies the vertically integrated archetype with upstream control over expanded PTFE production. TE Connectivity anchors the connector-termination tier through harness assembly bundling. European manufacturing-scale competitors include Prysmian Group, which occupies a position across ArianeGroup supply chains. These three entities represent distinct competitive vectors: polymer innovation, assembly integration, and production scale.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| TE Connectivity |
| Nexans |
| Prysmian Group |
| Amphenol Corporation |
| Leoni |
| Axon' Cable |
| Lapp Group |
| Molex |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific freight corridors connecting expanded PTFE resin processors in North America to harness assemblers in Japan and India transmit fluoropolymer cost volatility downstream, concentrating pricing power among suppliers with captive polymer production while fragmenting margin structures across tiered certification grades.
Pricing Analysis
Long-term cost-plus contracts indexed to copper and silver commodity benchmarks dominate procurement between prime contractors and qualified harness specialists. Price differentiation rests on NASA-STD-4003 certification tier and volume scale, with constellation operators commanding standard-grade discounts unavailable to deep-space mission buyers. Cost compression in telecommunications-grade cabling is intensifying because carbon nanotube-doped conductors displace hand-laid shielding labor. Telecommunications constellation developers exhibit highest price sensitivity; geostationary satellite operators remain least sensitive due to mission-critical reliability requirements.
Supply Chain Analysis
ITAR and EAR export controls restrict expanded PTFE membrane technology flows from the United States to non-allied launch markets, segmenting supply access by national security clearance. Manufacturing concentrates in the United States, Germany, and Japan for qualified insulation systems. Supply chains draw from North American fluoropolymer resin, Japanese precision conductors, and European braid shielding. Single-source vulnerability concentrates in expanded PTFE feedstock among three chemical processors. Distribution runs through prime contractor integration facilities and direct operator relationships under Space Force rapid acquisition pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified vacuum chamber certification slots represent the binding constraint in this market, with eighteen-month validation backlogs creating durable competitive moats for incumbents possessing accredited thermal cycling facilities.
For Market Incumbents: Harden qualification asset utilization by expanding captive vacuum chamber capacity at Vandenberg and Cape Canaveral corridor facilities. Deepen backward integration into carbon-loaded PTFE compounding to offset fluoropolymer resin price volatility from semiconductor demand competition. Lock in multi-year cost-plus contracts with emerging Indian launch operators before export control harmonization closes access windows. For New Entrants and Emerging Players: Build out ITAR-compliant manufacturing footprints in Colorado or California to access Space Force rapid acquisition pathways bypassing prime contractor tiers. The Indian launch market at Satish Dhawan Space Centre offers the most penetrable geography given ISRO's relaxation of import substitution mandates. Lead with commodity-grade shielded multi-core harnesses for telecommunications constellations, positioning carbon nanotube-doped conductors as cost-disruptive alternatives to incumbent metallic filler architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant aerospace wire divisions lacking recent NASA-STD-4003 recertification. Long-term viability hinges on sustained launch cadence acceleration and Artemis program lunar surface power distribution scale-up. Monitor ECHA REACH enforcement timelines as inflection signals for European supplier base consolidation and alternative dielectric chemistry validation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive PTFE production insulates margin structures from semiconductor resin competition. |
| Vacuum Chamber Certification Expansion | Additional thermal cycling capacity at accredited facilities accelerates new product velocity. |
| Direct Operator Relationship Development | Bypassing prime contractor tiers captures procurement authority shifts in constellation programs. |
| Alternative Dielectric Chemistry Validation | REACH-compliant insulation pathways secure European market access amid regulatory friction. |
| Indian Manufacturing Footprint Establishment | ITAR-compliant facilities near Satish Dhawan Space Centre access ISRO commercialization demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NASA technical standards documentation, ESA ECSS qualification protocols, and customs trade data for fluoropolymer resin flows. Interviews with harness procurement officers at prime contractors, thermal cycling facility managers, constellation operator supply chain directors, and ESA materials qualification engineers informed demand segmentation. Secondary sources include FAA launch licensing records, REACH regulatory filings, and SEC disclosures from wire and cable manufacturers. Bottom-up build-ups of launch vehicle and satellite harness demand were cross-checked against top-down aerospace wire market estimates.
Forecast inputs span product type, orbital application, material grade, and end-user procurement authority across the projection horizon. Segment-level CAGRs were derived from launch cadence trajectories, constellation deployment schedules, and regulatory recertification timelines. Modeling incorporated NASA-STD-4003 revision implementation curves, reusable booster program standardization rates, and Indian launch market commercialization pace as industry-specific demand drivers.
Stress conditions across fluoropolymer resin price volatility, REACH enforcement severity, and vacuum chamber capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sustained Cape Canaveral launch cadence and Space Force procurement budget trajectories. Material shifts in ECHA perfluorinated compound restrictions or ITAR export control harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Hybrid Cables Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Submarine Cables Market
Cables
High Voltage Cables Market
Cables
Wire and Cable Materials Market
Cables
Single Core Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Insulated Wire and Cable Market
Cables
Magnetic Charging Cable Market
Cables
Cable Fault Locator Market
Cables
Cable Tags Market
Cables
Asia-Pacific Cable Joints Market
Cables
Fire Resistance Cable Market
Cables
Cable Clamp Market
Cables
Cable Flange Market
Cables
Shipboard Cable Market