
 Paper Packaging Market | 2026-2036
Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Packaging Market Intelligence
The capital-intensity divergence between integrated pulp-to-box operators and merchant converters is rotating competitive advantage toward firms with captive fiber supply. International Paper Company leverages its North American timberland base and mill network to sustain raw material cost advantages. Mondi plc anchors its position through kraft paper integration across European and South African operations. Smurfit Westrock competes on containerboard scale, while DS Smith Plc differentiates through lightweight corrugated engineering for FMCG clients.
Paper packaging comprises fiber-based enclosures, carriers, and protective structures manufactured from virgin or recycled cellulose pulp, typically ranging from 80 to 400 grams per square meter in basis weight, designed to contain, protect, and present goods through distribution and retail channels. Kraft paper grades dominate industrial shipping applications due to tensile strength and tear resistance, while coated paper variants serve premium consumer-facing print requirements. Boxes and bags represent the mature volume core, whereas pouches claim expanding share in dry food and pharmaceutical sachet formats. E-commerce end users command the fastest growth trajectory, with recycled paper substrates gaining preference as brands respond to retailer sustainability scorecards.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and minimum recycled content thresholds, directly altering material specifications for carton board suppliers. The US EPA guides municipal recycling stream standards that affect recovered fiber availability and contamination limits for Packaging Corporation of America and WestRock Company mills. China's GB standards and SAMR packaging rules restrict excessive layering and prescribe material minimization for express parcels. Stakeholders must monitor regulatory divergence between jurisdictions where fiber sourcing rules, recyclability labeling, and plastic substitution mandates are tightening in parallel.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for carton converters while e-commerce fulfillment networks are pulling corrugated tonnage toward automated box-on-demand systems.
Growth Catalysts
- Extended Producer Responsibility frameworks:The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, compelling brand owners to specify post-consumer fiber grades.
- E-commerce fulfillment automation:Amazon and Zalando distribution hubs in Germany are deploying right-size box technologies that consume linerboard at accelerated rates.
- Kraft paper substitution:Industrial shippers are replacing plastic stretch wrap with paper-based protective formats for pallet stability.
Market Restraints
- Recovered fiber price volatility:Old corrugated container bales fluctuate with municipal collection efficiency and export demand from Asian packaging mills.
- Nordic pulp supply concentration:Bleached kraft pulp production clusters in Sweden and Finland, exposing converters to freight cost surges and currency exposure.
- Coated board technical limitations:Polyethylene barriers required for liquid containment compromise repulpability, constraining circularity claims.
Strategic Opportunities
- Pharmaceutical serialization compliance:The EU Falsified Medicines Directive is expanding demand for tamper-evident folding cartons with integrated track-and-trace features.
- India express parcel growth:Flipkart and Reliance JioMart fulfillment networks are adopting paper-based mailers to preempt plastic bans under BIS packaging standards.
- Bio-based barrier coatings:Chitosan and alginate formulations are converging with nanocellulose deposition to replace fossil-derived moisture barriers.
Industry Challenges
- Corrugator technician scarcity:Skilled operators for flute profile adjustment and starch adhesive calibration are retiring faster than vocational programs replenish supply.
- Food-contact certification timelines:FDA and EFSA migration testing for recycled fiber food packaging extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Packaging Market |
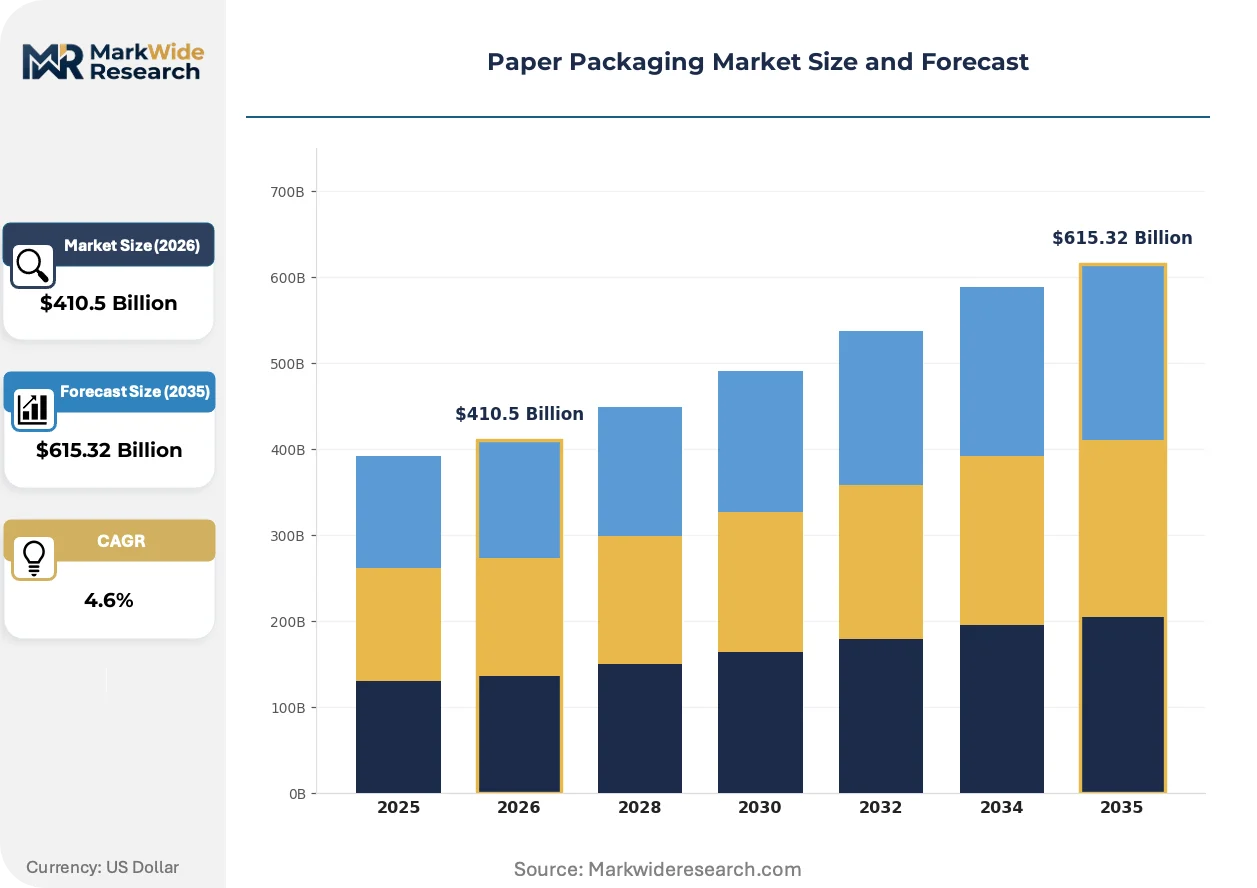
| Market Size in 2026 | $410.5 Billion |
| Market Size in 2035 | $615.32 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Pouches Use Case: Consumer Goods, Foodservice, Healthcare, Electronics Material: Kraft Paper, Coated Paper, Recycled Paper, Carton Board End User: Retail, E-Commerce, Food Industry, Pharmaceutical |
| Companies Covered | Stora Enso Oyj, DS Smith Plc, International Paper Company, Nippon Paper Industries Co., Ltd., Packaging Corporation of America, Smurfit Westrock, Mondi plc, Oji Holdings Corporation, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Packaging Market Strategic Shifts & Innovations
Digital printing and barrier coating advances are collapsing minimum order quantities while regulatory pressure on recyclability is eliminating multi-material laminates from premium packaging specifications.
Water-based flexographic printing with extended color gamut inks is displacing rotogravure for short-run folding carton work. Cosmetic and nutraceutical brands are adopting these systems for seasonal packaging refreshes. This displacement is compressing prepress lead times from weeks to days and eroding the volume threshold advantage of traditional cylinder-based methods.
The EU Green Deal's packaging waste reduction targets are accelerating design-for-recycling protocols across the continent. Mono-material polyethylene-coated boards are losing specification share to uncoated or water-dispersible barrier alternatives. German retailers including Aldi and Lidl are demanding recyclability labeling compliance that disqualifies legacy multi-ply structures from private-label food ranges.
Brand sustainability scorecards are reshaping procurement specifications for corrugated shipping containers. Unilever and Nestlé purchasing teams now weight post-consumer recycled content above unit cost in supplier qualification. This behavioral shift is most pronounced in Benelux and Nordic markets where consumer-facing carbon footprint labeling drives shelf placement decisions.
Paper Packaging Market Segmentation
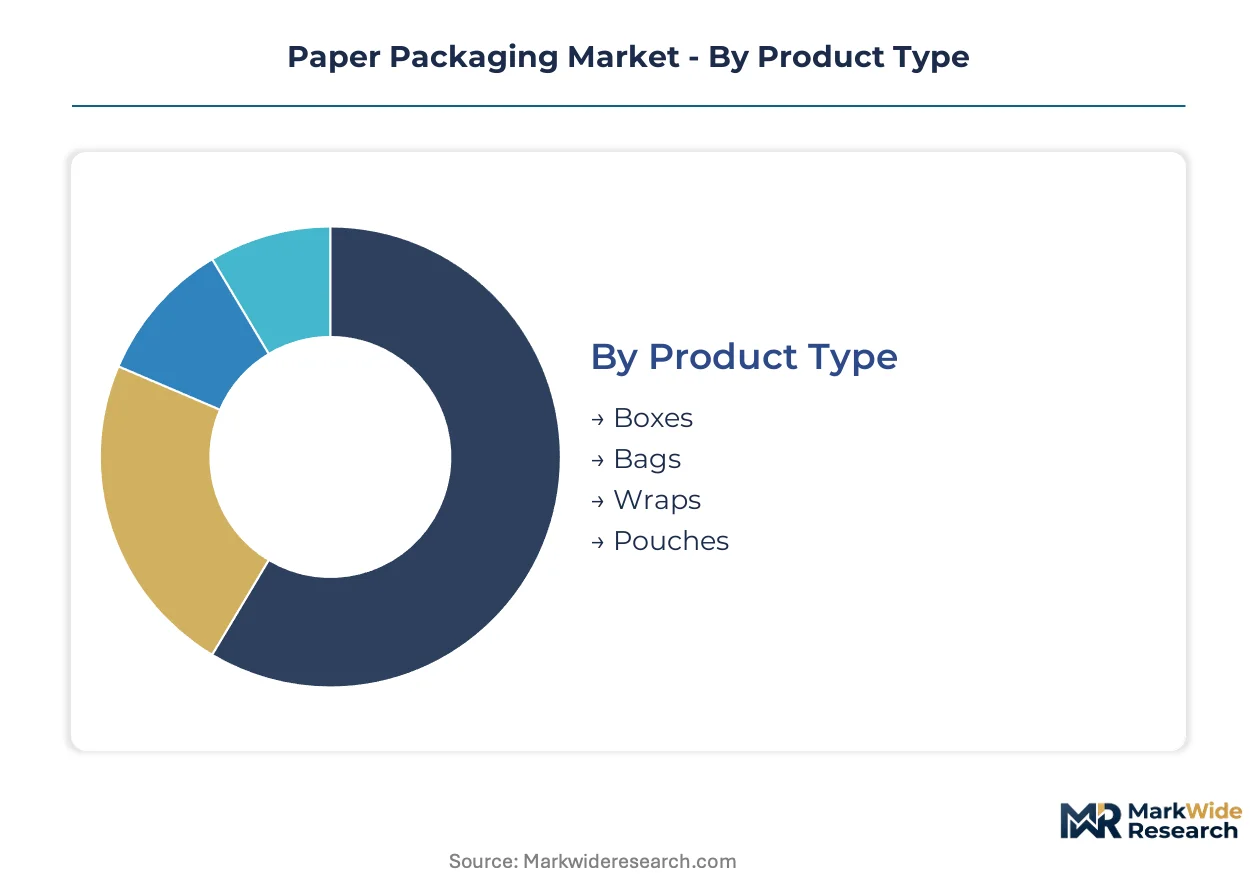
Paper packaging segmentation reveals divergent margin structures across substrate grades and fulfillment channels. Material integration levels and end-use regulatory exposure determine profitability pockets for converters and integrated producers.
Product Type:
Premium margin pools concentrate in protective formats where engineering specifications command price premiums over commodity shipping containers.
- Boxes:Corrugated fiberboard containers ranging from single-wall to triple-wall flute profiles, specified by edge crush test and burst strength ratings. Amazon and Zalando fulfillment hubs in Germany deploy automated box-on-demand systems consuming linerboard at accelerated rates. Kraft linerboard integration separates profitable operators from merchant converters.
- Bags:Multiwall sacks and retail carry formats manufactured from extensible kraft or bleached sulfate paper, with pinch-bottom and valve configurations for industrial powders. Construction chemical and food ingredient sectors in the US specify these for moisture protection and pallet stability.
- Wraps:Protective interleaving and cushioning sheets, typically 40-80 gsm, substituting for plastic bubble formats in e-commerce void fill applications.
- Pouches:Flat-bottom and stand-up flexible formats with heat-sealed closures, expanding in dry food and pharmaceutical sachet segments where barrier coatings enable shelf-stable claims.
The dominant share belongs to Boxes, while Pouches is closing the gap fastest.
Use Case:
Application-driven specifications split procurement between brand-owner sustainability scorecards and industrial performance mandates.
- Consumer Goods:Folding cartons and rigid boxes for cosmetics, personal care, and premium confectionery, requiring high-fidelity print reproduction and structural rigidity. Unilever and Nestlé purchasing teams in Benelux weight post-consumer recycled content above unit cost in supplier qualification.
- Foodservice:Grease-resistant wraps, clamshells, and beverage carriers replacing expanded polystyrene under municipal plastic restrictions. FDA migration testing for recycled fiber food contact extends qualification cycles by 18-24 months.
- Healthcare:Tamper-evident folding cartons with integrated track-and-trace features for pharmaceutical serialization compliance under the EU Falsified Medicines Directive.
- Electronics:Anti-static corrugated and molded pulp cushioning for device protection, specified by OEMs for unboxing experience and damage rate reduction.
Consumer Goods commands the largest specification volume, though Foodservice is expanding most quickly as plastic substitution mandates proliferate.
Material:
Raw material cost structures and circularity credentials differentiate substrate positioning in procurement decisions.
- Kraft Paper:Unbleached sulfate pulp with high tear resistance and tensile strength, dominating industrial shipping and protective applications. International Paper Company leverages North American timberland bases to sustain cost advantages in this grade.
- Coated Paper:Clay or polymer-surfaced sheets for premium print reproduction in consumer-facing cartons. Polyethylene barriers required for liquid containment compromise repulpability, constraining circularity claims under EU Green Deal targets.
- Recycled Paper:Post-consumer fiber grades processed through deinking and screening, specified by retailer sustainability scorecards. Old corrugated container bale prices fluctuate with municipal collection efficiency and Asian mill export demand.
- Carton Board:Solid bleached and unbleached sulfate boards for rigid box and liquid packaging applications, with Swedish and Finnish pulp concentration exposing converters to freight cost surges.
Kraft Paper retains the volume lead, yet Recycled Paper is gaining specification share fastest as brand sustainability commitments harden.
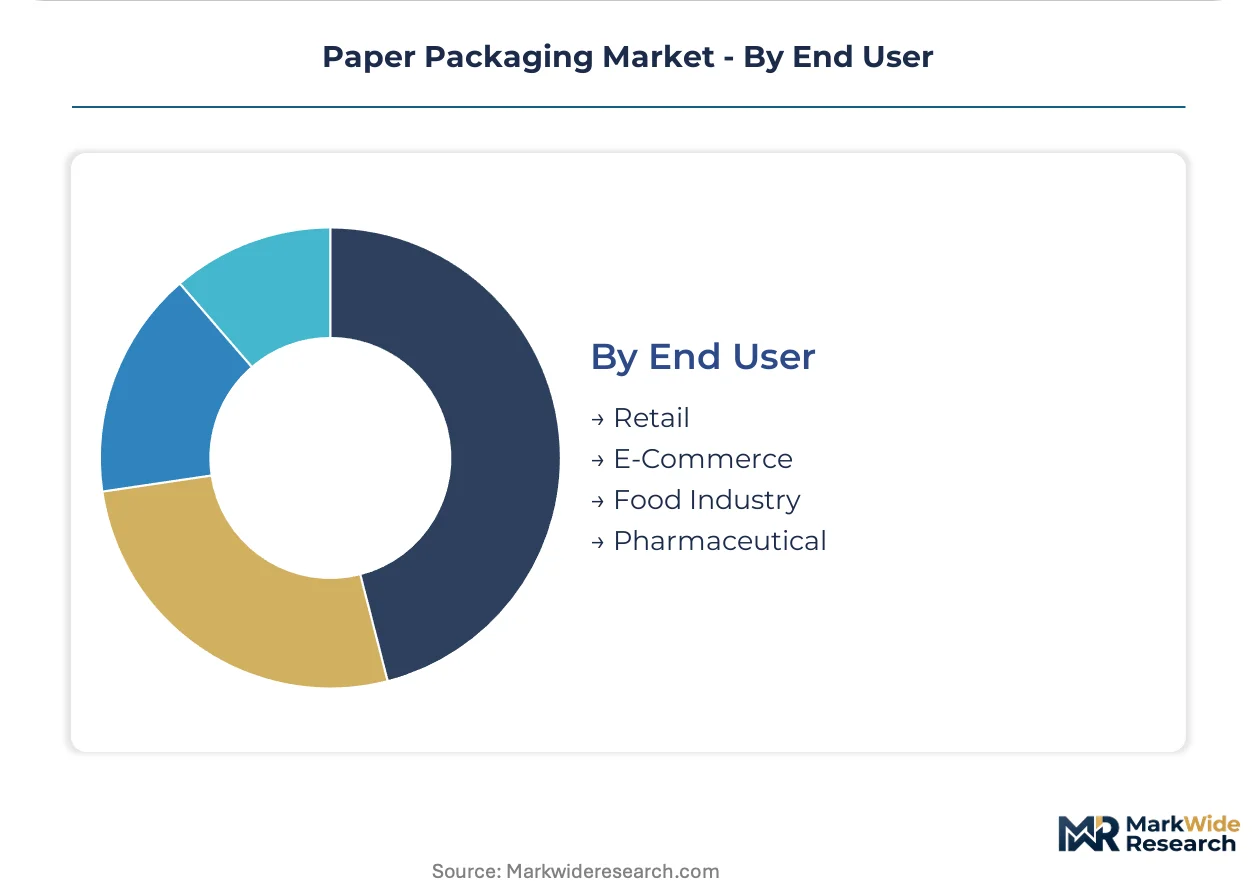
End User:
Fulfillment channel automation intensity and regulatory exposure segment demand patterns.
- Retail:Shelf-ready packaging and promotional displays for brick-and-mortar merchandising, with German retailers including Aldi and Lidl demanding recyclability labeling compliance.
- E-Commerce:Right-size shipping containers and protective formats for direct-to-consumer fulfillment. Flipkart and Reliance JioMart networks in India adopt paper-based mailers to preempt plastic bans under BIS packaging standards.
- Food Industry:Primary and secondary packaging for fresh, frozen, and shelf-stable products, governed by FDA and EFSA food-contact certification timelines.
- Pharmaceutical:Serialization-compliant cartons and patient information leaflets, with EU Falsified Medicines Directive expanding tamper-evident format demand.
Retail maintains the largest installed base, while E-Commerce climbs the fastest as fulfillment network automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany and the United States exhibit the lowest price elasticity, prioritizing supply security and sustainability credentials over unit cost. Price-sensitive procurement dominates Southeast Asian markets where converter margins compress under import competition.
United States
Amazon fulfillment network expansion and Walmart distribution automation sustain linerboard consumption across the Southeast and Midwest. EPA municipal recycling stream standards shape recovered fiber availability for Packaging Corporation of America and WestRock Company mills. The Pacific Northwest pulp-to-box corridor leverages timberland proximity to serve West Coast e-commerce hubs.
Germany
Amazon and Zalando fulfillment centers in Leipzig and Dortmund deploy right-size box-on-demand systems consuming kraft linerboard at accelerated rates. EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for carton board specifications. The Rhine-Ruhr industrial cluster concentrates corrugated converter capacity serving Benelux FMCG brand owners.
China
Express parcel volume from Alibaba and JD.com fulfillment networks drives demand for lightweight corrugated mailers. SAMR packaging rules and GB standards restrict excessive layering and prescribe material minimization for e-commerce parcels. The Yangtze River Delta manufacturing belt hosts integrated pulp-to-box operators supplying domestic and export markets.
India
Flipkart and Reliance JioMart adoption of paper-based mailers accelerates ahead of anticipated BIS packaging standards restricting single-use plastics. FSSAI food-contact certification requirements govern recycled fiber qualification for foodservice applications. Maharashtra and Gujarat industrial corridors concentrate kraft paper bag manufacturing for construction chemical and agricultural commodity sectors.
Japan
Precision electronics OEMs specify anti-static corrugated and molded pulp cushioning for device protection and unboxing experience. METI circular economy guidelines promote design-for-recycling protocols across packaging supply chains. The Chubu-Nagoya manufacturing cluster serves automotive and electronics tier-one suppliers with high-specification protective formats.
Paper Packaging Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the paper packaging value chain. The market structure consolidates around integrated pulp-to-box operators with captive fiber supply, merchant converters dependent on spot market purchases, and specialty engineers serving pharmaceutical and electronics niches. Strategic differentiation separates scale-driven containerboard producers from lightweight corrugated specialists and barrier-coated board innovators. Competitive moves concentrate on kraft paper integration and automated corrugator capacity expansion.
Among North American integrated producers, International Paper Company and Packaging Corporation of America occupy positions defined by timberland-backed raw material security. DS Smith Plc and Mondi plc represent European operators with kraft paper integration across continental and South African operations. Smurfit Westrock sits within the scale-driven containerboard tier following transatlantic merger consolidation.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| DS Smith Plc |
| International Paper Company |
| Nippon Paper Industries Co., Ltd. |
| Packaging Corporation of America |
| Smurfit Westrock |
| Mondi plc |
| Oji Holdings Corporation |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Recycled fiber substitution for virgin kraft pulp simultaneously redraws supply geography toward Nordic bleached kraft concentration and compresses pricing economics for merchant converters locked into spot OCC markets. This material shift rewards integrated operators with captive timberland while exposing dependent converters to freight cost surges and currency volatility.
Pricing Analysis
After-sales service contracts for corrugator maintenance and starch adhesive calibration drive lifetime value for equipment suppliers. Three-tier pricing structure across premium certified, standard grade, and economy uncoated levels separates integrated producers from merchant converters. Cost compression in standard-grade linerboard intensifies because Amazon and Zalando procurement teams weight post-consumer recycled content above unit cost. Industrial shippers exhibit the lowest price sensitivity, prioritizing burst strength ratings and supply security, while Southeast Asian converters face acute margin pressure from import competition.
Supply Chain Analysis
Sweden and Finland anchor bleached kraft pulp production for carton board specifications across European and Asian markets. The supply chain draws from Nordic timberland bases, recovered fiber collection networks, and chitosan barrier coating laboratories. Single-source vulnerability concentrates in OCC bale supply where municipal collection efficiency fluctuates with export demand from Asian packaging mills. Distribution runs through automated fulfillment hubs deploying right-size box-on-demand systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce fulfillment automation constitutes a high-growth disruption, with the EU Packaging and Packaging Waste Regulation mandating minimum recycled content thresholds that reconfigure procurement specifications across the value chain.
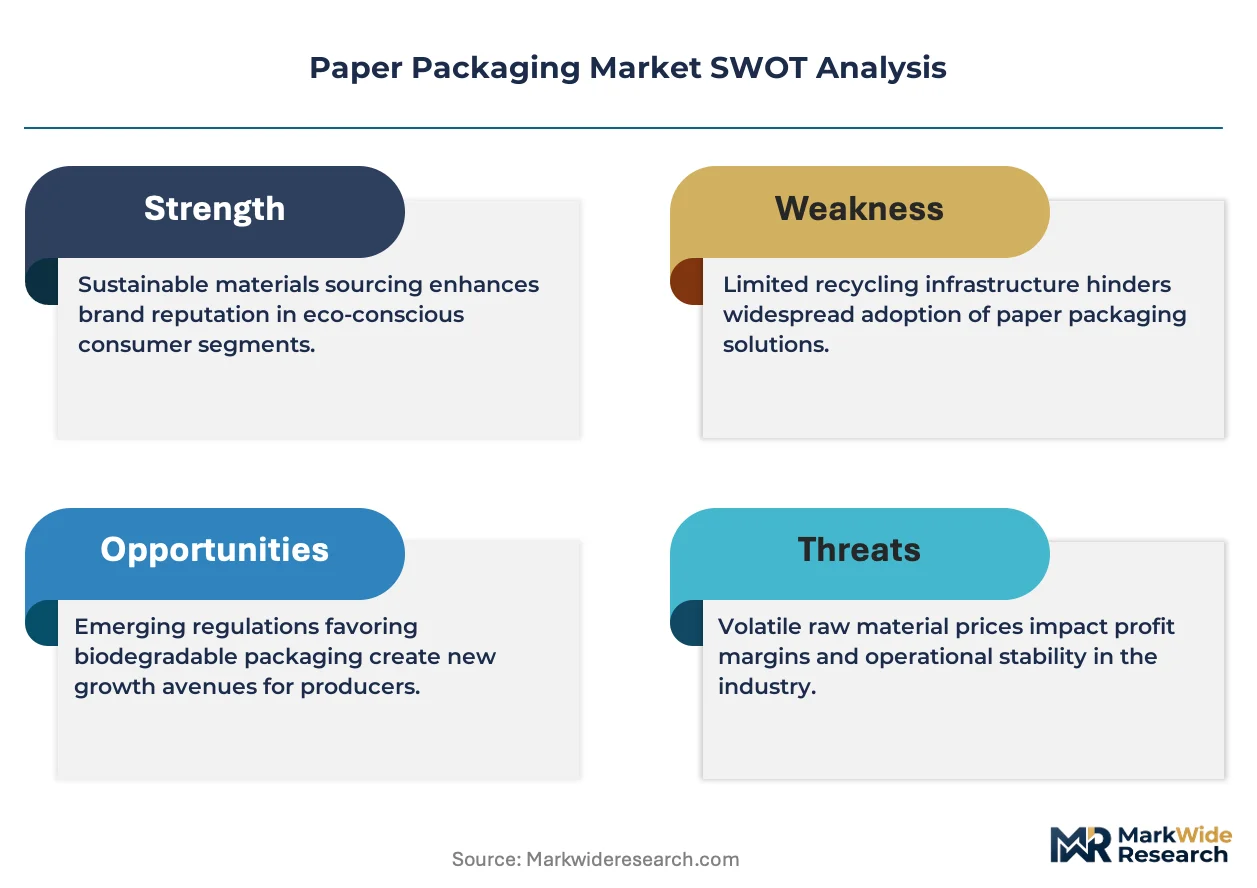
For Market Incumbents: Consolidate kraft linerboard integration through North American timberland acquisitions and expand automated corrugator capacity in Germany's Rhine-Ruhr cluster. Defensive positioning requires preemptive investment in water-dispersible barrier coatings before EU Green Deal protocols disqualify polyethylene-laminated boards from Aldi and Lidl private-label ranges. For New Entrants and Emerging Players: Lead with pharmaceutical serialization compliance formats for EU Falsified Medicines Directive mandates, where tamper-evident folding cartons with integrated track-and-trace features command specification premiums. India's express parcel segment offers penetrable white-space ahead of anticipated BIS packaging standards restricting single-use plastics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant converters lacking captive fiber supply but holding FDA food-contact certifications. Five-to-ten year viability hinges on backward integration completion or specialty barrier coating acquisition. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as the inflection signal for recycled content threshold compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Kraft Paper Integration | Captive timberland supply secures raw material cost advantages against OCC price volatility. |
| Automated Corrugator Expansion | Right-size box-on-demand deployment aligns with Amazon and Zalando fulfillment automation requirements. |
| Bio-Based Barrier Coating Development | Chitosan and alginate formulations replace fossil-derived moisture barriers under EU Green Deal targets. |
| Pharmaceutical Serialization Compliance | Tamper-evident folding cartons meet EU Falsified Medicines Directive track-and-trace mandates. |
| Recycled Fiber Certification Investment | FDA and EFSA migration testing completion accelerates food-contact qualification cycles. |
Research Approach
A spread of perspectives from corrugator operations managers, pulp procurement directors, FMCG packaging engineers, and retail sustainability officers converged on the working assumptions. Primary interviews combined with secondary validation from SEC 10-K filings, EU Packaging and Packaging Waste Regulation impact assessments, OCC trade flow databases, and forest products industry associations. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include substrate grade, end-use application, material type, and fulfillment channel automation intensity across the projection horizon. CAGRs derived from historical volume trajectories, regulatory compliance cost curves, and e-commerce penetration assumptions. Forecast inputs incorporated Amazon and Zalando fulfillment hub expansion plans alongside EU recycled content threshold enforcement schedules.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation, FDA food-contact certification timelines, and BIS packaging standards development; material policy shifts would require re-modeling. Specific risks include Nordic pulp supply disruption, OCC export demand fluctuation, and bio-based barrier coating technical qualification delays. Recalibration cycles align with material shifts in e-commerce fulfillment automation and extended producer responsibility framework implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Postal Papers Market