
 Kraft Bubble Mailers Market | 2026-2036
Kraft Bubble Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Bubble Mailers Market Outlook
FSC Chain of Custody certification is unwinding competitive access across European and North American supply chains, forcing smaller converters to absorb audit costs or exit retail channels entirely. Sealed Air Corporation leverages its global manufacturing footprint to sustain multi-region certification compliance without margin erosion. Pregis LLC anchors its position through in-house blown film production, insulating it from resin price volatility that disrupts merchant buyers.
Kraft bubble mailers are composite shipping envelopes constructed from outer kraft paper laminated to inner polyethylene bubble cushioning, typically ranging from 3/16 inch to 1/2 inch bubble height and designed to absorb impact during single-trip parcel distribution. The self-seal product category dominates volume due to fulfillment speed requirements, while recyclable variants are capturing premium positioning as Extended Producer Responsibility schemes expand across OECD markets. E-commerce application demand leads absolute consumption, though electronics shipping commands higher unit margins due to anti-static specifications and custom sizing requirements.
EPA guidelines on recycled content thresholds and REACH restrictions on heavy metal additives in packaging inks are reshaping material sourcing protocols for converters serving regulated jurisdictions. The EU Packaging and Packaging Waste Regulation mandates minimum recycled fiber content, pushing manufacturers toward certified supply chains or risk market exclusion. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California, New York, and Washington to anticipate compliance cost shifts before facility investment decisions lock in.
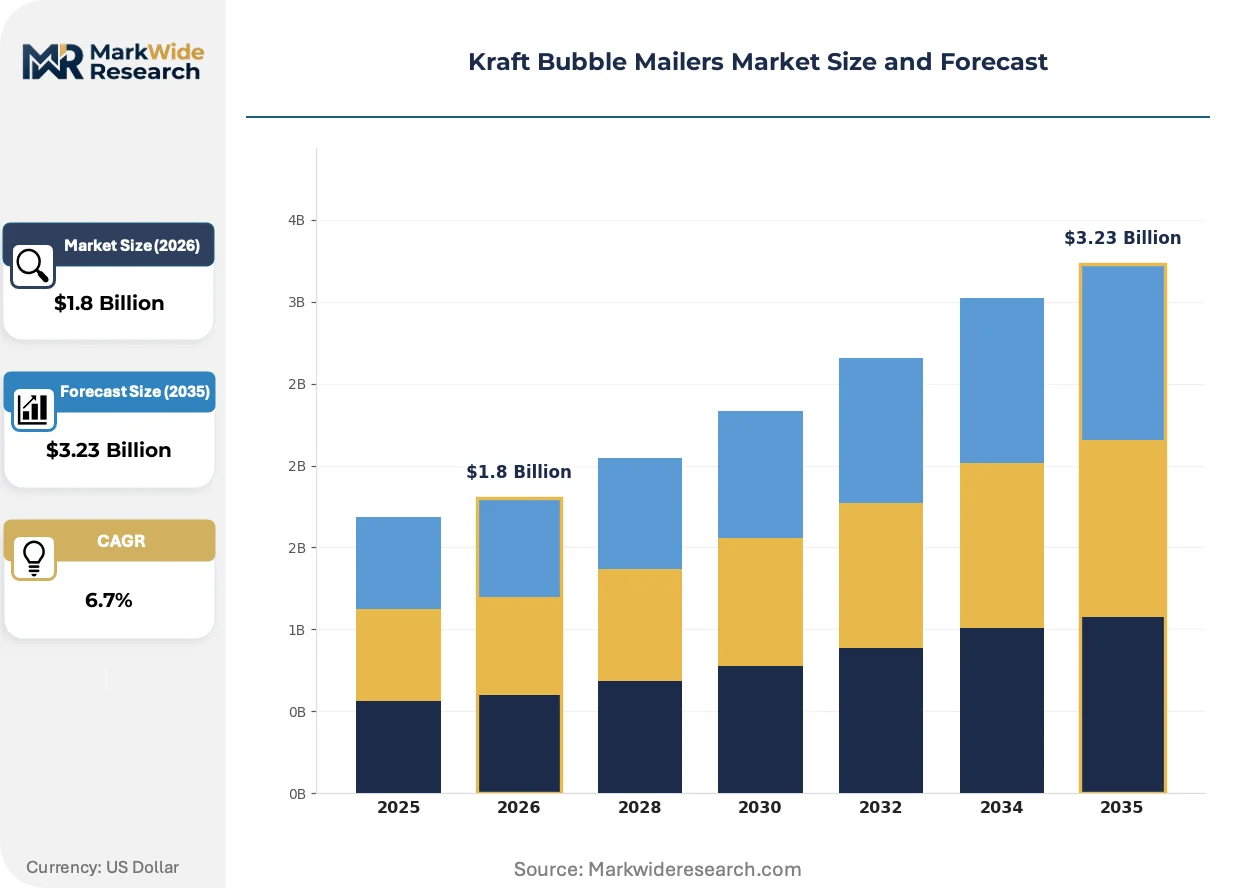
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins by mandating certified recycled fiber content, forcing supply chain reconfiguration toward FSC Chain of Custody compliance before facility investments lock in.
Growth Catalysts
- E-commerce fulfillment velocity:Lightweight parcel protection demand from cross-border online retail corridors in Germany is pulling padded mailer volume through centralized distribution hubs serving pan-European last-mile networks.
- REACH heavy metal restrictions:Packaging ink reformulation requirements are accelerating converter migration to certified supply chains that preempt regulatory exclusion across OECD jurisdictions.
- Extended Producer Responsibility expansion:State-level frameworks in California, New York, and Washington are creating compliance-driven procurement preferences for recyclable kraft bubble variants.
Market Restraints
- Resin price volatility:Polyethylene bubble cushioning input costs fluctuate with crude-linked petrochemical indices, compressing margins for converters without captive blown film production.
- FSC certification concentration:Audit cost absorption requirements favor multi-region manufacturers, forcing smaller converters toward retail channel exit or merchant buyer dependency.
- Single-trip design limitation:Composite kraft-polyethylene construction prevents closed-loop reuse, exposing the format to substitution pressure from pure-fiber alternatives in circular packaging mandates.
Strategic Opportunities
- Electronics anti-static specifications:Custom sizing and static-dissipative bubble formulations command premium positioning in semiconductor and consumer device shipping corridors.
- Self-seal automation integration:Fulfillment center robotics compatibility is opening specification windows for precision-die-cut closure systems in high-velocity European distribution hubs.
- California EPR pre-compliance:Early alignment with state extended producer responsibility frameworks creates first-mover positioning before 2027 enforcement windows activate.
Industry Challenges
- Blown film technician scarcity:In-house polyethylene bubble production requires specialized extrusion expertise that concentrates in legacy packaging manufacturing regions.
- Multi-jurisdiction certification timelines:Simultaneous EPA recycled content verification and EU FSC Chain of Custody audits extend product qualification cycles for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Bubble Mailers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Seal, Peel & Seal, Recyclable, Anti-Static, Tamper Evident, Printed Application: E-Commerce, Direct Mail, Document Protection, Gift Packaging, Electronics Shipping, Apparel Delivery Distribution Channel: Online Retailers, Wholesale Distributors, Brick & Mortar Stores, B2B Suppliers, Postal Service Providers, Specialty Packaging Shops Customer Type: Small Businesses, Enterprises, Logistic Companies, Print & Mail Houses, Nonprofit Organizations, Educational Institutions |
| Companies Covered | Sealed Air Corporation, Pregis LLC, PAC Worldwide Corporation, ProAmpac Holdings Inc., 3M Company, Intertape Polymer Group Inc., International Paper, Polyair Inter Pack Inc., Mondi plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Bubble Mailers Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape converter competitive position, with certification compliance and automation compatibility emerging as the primary axes of differentiation.
Water-based adhesive self-seal systems is supplanting solvent-based closures in fulfillment applications. E-commerce distribution centers in the Netherlands and Belgium are specifying these formulations to meet indoor air quality protocols. The transition is compressing qualification timelines for converters still running legacy hot-melt equipment.
REACH Annex XVII restrictions on phthalate plasticizers in packaging materials are forcing bubble cushioning reformulation across European supply chains. Converters serving German retail channels are accelerating migration to bio-based polyethylene alternatives. Electronics shipping specifications are tightening testing protocols to demonstrate compliance.
Direct-to-fulfillment procurement is consolidating specification authority with logistics operators rather than brand marketing departments. Amazon, Zalando, and Otto Group distribution networks are unbundling packaging selection from product design teams. This shift concentrates volume with converters capable of multi-SKU customization at regional hub proximity.
Kraft Bubble Mailers Market Segmentation
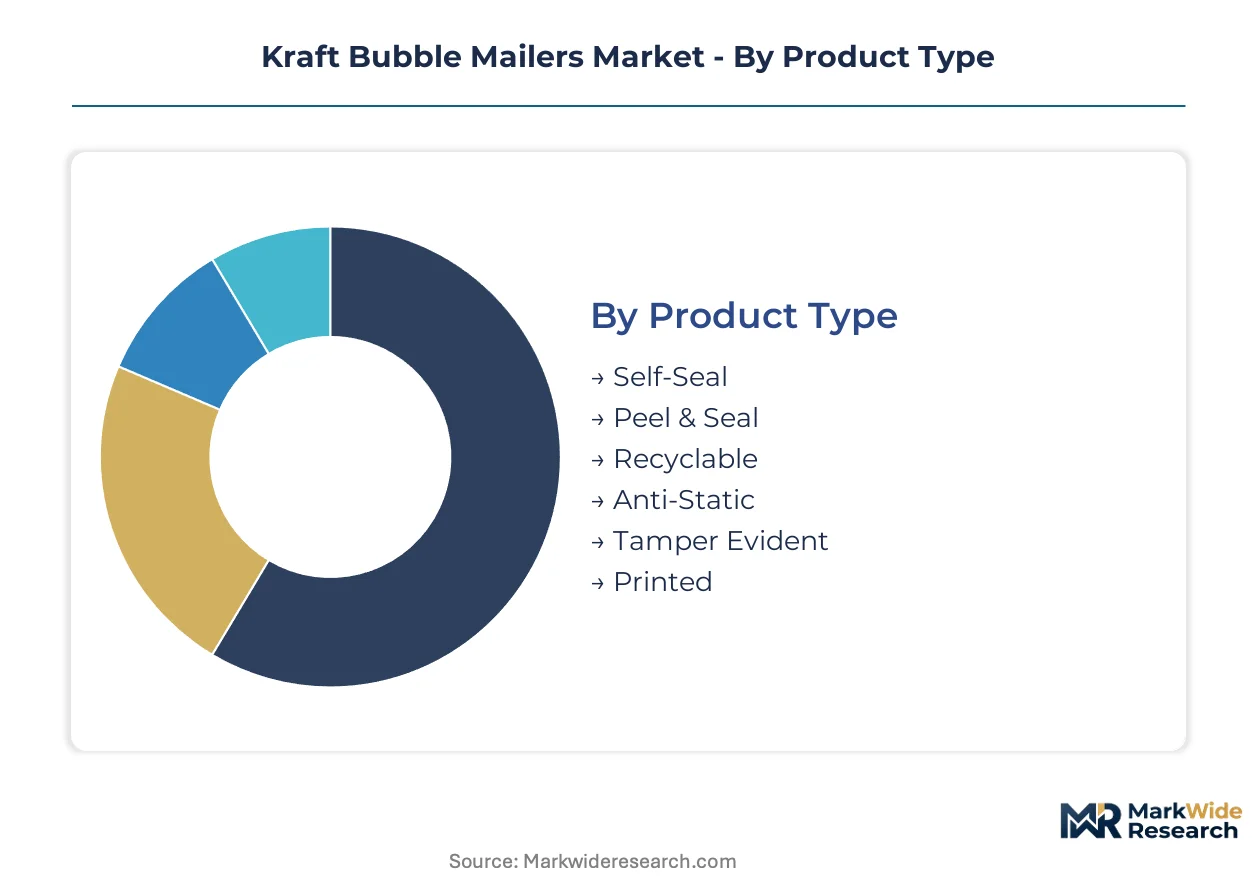
Kraft bubble mailer segmentation reveals divergent vulnerability to substitution across product formats and end-use channels. Understanding which segments face pressure from alternative protective packaging formats shapes procurement strategy and converter investment priorities.
Product Type:
Substitution pressure concentrates in closure systems and recyclability claims, where regulatory scrutiny and automation requirements are reshaping specification authority.
- Self-Seal:Pressure-sensitive adhesive strips enable single-handed closure at fulfillment velocity. Demand concentrates in German e-commerce distribution hubs where line-speed requirements dominate procurement specifications.
- Recyclable:Pure-fiber or mono-material constructions eliminate polyethylene separation barriers. California EPR frameworks and EU Packaging Waste Regulation compliance windows are accelerating specification migration in regulated corridors.
- Peel & Seal:Removable adhesive allows recipient reclosure for returns processing.
- Anti-Static:Carbon-loaded bubble formulations dissipate electrostatic discharge for semiconductor shipping.
- Tamper Evident:Fracture-pattern adhesives reveal unauthorized access attempts.
- Printed:Direct-surface branding eliminates secondary label application.
Self-Seal retains volume leadership; Recyclable holds the steepest expansion curve.
Application:
Margin tiering separates high-specification electronics corridors from commodity e-commerce fulfillment, with regulatory exposure varying sharply across end-use categories.
- E-Commerce:Lightweight parcel protection for single-trip distribution dominates absolute consumption. Cross-border retail corridors through Belgium and the Netherlands pull volume through centralized European hubs serving pan-European last-mile networks.
- Electronics Shipping:Anti-static specifications and custom sizing command premium positioning. REACH Annex XVII phthalate restrictions and static-dissipative testing protocols concentrate procurement with certified converters.
- Direct Mail:Document protection for financial and healthcare correspondence.
- Document Protection:Archival-grade buffering for legal and insurance records.
- Gift Packaging:Aesthetic surface finishes for consumer presentation.
- Apparel Delivery:Soft-goods protection with minimal dimensional tolerance requirements.
E-Commerce commands absolute volume; Electronics Shipping captures the highest margin realization.
Distribution Channel:
Channel consolidation toward direct-to-fulfillment procurement is unbundling packaging selection from brand marketing departments, concentrating volume with logistics operators.
- Online Retailers:Amazon, Zalando, and Otto Group distribution networks specify multi-SKU customization at regional hub proximity. Procurement authority has shifted from product design teams to logistics operators.
- B2B Suppliers:Long-term contract manufacturing relationships with enterprise shippers. Volume concentration favors converters with captive blown film production and FSC Chain of Custody certification.
- Wholesale Distributors:Inventory holding for small and mid-sized merchant buyers.
- Brick & Mortar Stores:Counter sales for walk-in commercial and consumer purchases.
- Postal Service Providers:National carrier procurement for retail shipping supplies.
- Specialty Packaging Shops:Niche specification for artisan and premium product shippers.
Online Retailers drive volume consolidation; B2B Suppliers anchor long-term contract stability.
Customer Type:
Customer scale determines certification burden absorption capacity, with smaller entities facing exit pressure from FSC audit cost requirements.
- Enterprises:Multi-facility procurement with centralized sustainability mandates. EPA recycled content thresholds and REACH compliance requirements favor suppliers with multi-region certification infrastructure.
- Logistic Companies:Third-party fulfillment operators specifying automation-compatible formats. Robotics integration requirements in high-velocity European hubs are opening specification windows for precision-die-cut closure systems.
- Small Businesses:Price-sensitive spot purchasing with minimal compliance documentation requirements.
- Print & Mail Houses:High-volume document processing with standardized sizing needs.
- Nonprofit Organizations:Donation-driven procurement with cost minimization priorities.
- Educational Institutions:Administrative shipping with seasonal volume concentration.
Enterprises dominate certified supply chain demand; Logistic Companies are expanding specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators in Germany dominate procurement volume through centralized distribution hubs serving cross-border e-commerce corridors. Their specification authority concentrates demand with converters holding FSC Chain of Custody certification and captive blown film capacity.
Germany
Cross-border online retail through Belgian and Dutch distribution hubs pulls padded mailer volume into North Rhine-Westphalia logistics clusters. The EU Packaging and Packaging Waste Regulation mandates minimum recycled fiber content, forcing supply chain reconfiguration toward certified sourcing. Duisburg and Cologne anchor pan-European fulfillment networks where automation-compatible self-seal formats dominate procurement specifications.
United States
State-level Extended Producer Responsibility frameworks in California, New York, and Washington create compliance-driven procurement preferences for recyclable variants. EPA recycled content thresholds reshape material sourcing protocols for converters serving regulated jurisdictions. Chicago and Dallas distribution corridors concentrate e-commerce fulfillment volume with third-party logistics operators unbundling packaging selection from brand marketing departments.
China
Domestic e-commerce platforms drive lightweight parcel protection demand through Yangtze River Delta manufacturing and fulfillment clusters. The country's national packaging regulator enforces evolving standards on composite material separation and recovery. Shanghai and Suzhou logistics hubs specify multi-SKU customization at regional proximity, concentrating volume with converters capable of precision-die-cut closure systems.
Netherlands
Indoor air quality protocols in Rotterdam and Amsterdam distribution centers accelerate water-based adhesive adoption over solvent-based closure systems. REACH Annex XVII restrictions on phthalate plasticizers force bubble cushioning reformulation across European supply chains serving Dutch retail channels. Eindhoven electronics shipping corridors command premium positioning for anti-static specifications with static-dissipative testing protocols.
United Kingdom
Post-Brexit customs friction redirects cross-border parcel volume through domestic fulfillment networks in Midlands distribution corridors. The country's national environmental regulator aligns packaging waste recovery requirements with evolving EU baseline standards. Birmingham and Manchester logistics hubs specify automation-compatible formats as robotics integration requirements tighten in high-velocity operations.
Kraft Bubble Mailers Market Competitive Environment
Player mix skews toward integrated packaging conglomerates with captive resin conversion and multi-region certification infrastructure. Tiered competitive structure separates multi-national converters with FSC Chain of Custody compliance from merchant-dependent regional players facing audit cost absorption pressure. Strategic archetypes include vertically integrated resin-to-mailer producers, certified supply chain specialists, and automation-focused fulfillment format developers. Dominant competitive moves center on backward integration into blown film production and geographic certification expansion ahead of regulatory enforcement windows.
Within the integrated conglomerate tier, Sealed Air Corporation and Pregis LLC represent archetypes of multi-region compliance capacity. Sealed Air leverages global manufacturing footprint positioning to sustain certification across jurisdictions without margin erosion. Pregis anchors competitive position through in-house blown film production, insulating operations from polyethylene price volatility that disrupts merchant buyers. PAC Worldwide Corporation occupies a specialist position in custom format development for high-velocity fulfillment applications.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| PAC Worldwide Corporation |
| ProAmpac Holdings Inc. |
| 3M Company |
| Intertape Polymer Group Inc. |
| International Paper |
| Polyair Inter Pack Inc. |
| Mondi plc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization above 85% at German blown film facilities creates margin leverage for integrated converters while forcing merchant buyers into spot-market polyethylene exposure. This scale asymmetry concentrates pricing power with Sealed Air Corporation and Pregis LLC, whose captive resin conversion insulates them from crude-linked petrochemical volatility that disrupts smaller competitors.
Pricing Analysis
Cost-plus contracts with polyethylene indexation dominate long-term B2B supply agreements, locking in resin pass-through mechanisms that protect converter margins while exposing buyers to petrochemical price swings. Price differentiation centers on FSC Chain of Custody certification grade and automation-compatible precision-die-cut closure systems, with certified anti-static variants commanding premium positioning over commodity self-seal formats. Pricing pressure intensifies in the recyclable segment as California EPR pre-compliance windows accelerate specification migration before enforcement activation. Small businesses exhibit highest price sensitivity due to spot purchasing without volume-scale leverage, while enterprise logistics operators prioritize automation compatibility over unit cost minimization.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Dutch e-commerce fulfillment hubs, compressing order-to-delivery cycles to 48-72 hours and forcing converters to maintain regional finished-goods staging near Rotterdam and Duisburg logistics clusters. Raw material sourcing concentrates on kraft paper from Nordic FSC-certified pulp mills, polyethylene resin from Belgian and German petrochemical complexes, and water-based adhesive formulations from Netherlands specialty chemical producers. Supply chain risk concentrates in single-source blown film technician scarcity, which limits in-house extrusion capacity expansion regardless of capital availability. Distribution runs through direct-to-fulfillment procurement channels where Amazon, Zalando, and Otto Group logistics operators consolidate specification authority away from brand marketing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kraft bubble mailers market sits in early-cycle expansion as EU Packaging and Packaging Waste Regulation compliance windows force supply chain reconfiguration toward certified sourcing before facility investments lock in. E-commerce fulfillment velocity through German cross-border corridors provides durable demand tailwind with limited substitution risk from alternative formats.
For Market Incumbents: Shield margin position through backward integration into blown film production, insulating operations from polyethylene price volatility that disrupts merchant-dependent regional converters. Accelerate FSC Chain of Custody certification expansion across North American facilities before California EPR enforcement windows activate, preempting competitor first-mover positioning in compliance-driven procurement corridors.
For New Entrants and Emerging Players: Automation-compatible precision-die-cut closure systems represent the most penetrable service-layer gap, as incumbent converters with legacy hot-melt equipment face compressed qualification timelines against Dutch indoor air quality protocols. Target Netherlands and Belgium fulfillment hub procurement specifications with water-based adhesive self-seal formats, leveraging regulatory-driven format migration to establish volume footholds before scaling geographic coverage.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated converters with captive blown film production and multi-region FSC certification infrastructure, as these assets generate durable contract renewal rates from enterprise logistics operators. Target acquisition candidates with underutilized extrusion capacity in Germany or the United States, where regional hub proximity and certification compliance create defensive moats against merchant buyer dependency. Watch for inflection when California EPR enforcement thresholds trigger accelerated specification migration toward recyclable variants, compressing valuation multiples for non-compliant regional players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film Production | Captive polyethylene supply insulates margins from crude-linked resin volatility disrupting merchant buyers. |
| FSC Chain of Custody Certification Expansion | Multi-region compliance preempts EU Packaging Waste Regulation exclusion risk across member state procurement. |
| Water-Based Adhesive Self-Seal System Development | Netherlands indoor air quality protocol alignment opens specification windows in Rotterdam and Amsterdam hubs. |
| Precision-Die-Cut Closure Automation Integration | Robotics compatibility in German distribution centers concentrates volume with format-qualified converters. |
| California EPR Pre-Compliance Positioning | Early alignment with state extended producer responsibility frameworks captures first-mover procurement preference. |
Study Parameters
A standing panel of blown film production engineers, e-commerce logistics procurement directors, FSC certification auditors, and specialty adhesive formulators provided ongoing calibration against operational realities across the value chain. Primary interviews with these stakeholders combined with secondary validation from EU Packaging Waste Regulation implementation documents, EPA recycled content threshold guidelines, REACH Annex XVII restriction filings, and customs trade data on kraft paper and polyethylene resin flows. Bottom-up volume modeling by product type and application triangulated against top-down macroeconomic demand drivers to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions including closure system type, recyclability certification status, end-use application, and regional regulatory cluster. CAGRs were derived from fitted trend analysis incorporating e-commerce penetration trajectories, regulatory enforcement timelines, and substitution elasticity estimates for alternative protective packaging formats. Industry-specific forecast inputs included German cross-border parcel volume growth and electronics shipping specification tightening for anti-static compliance.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation, California Extended Producer Responsibility frameworks, and REACH Annex XVII enforcement; material policy shifts would require re-modeling across the analysis window. Revision becomes warranted when polyethylene resin price volatility exceeds historical bands or when FSC certification audit backlogs extend qualification timelines beyond facility investment decision horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Mailer Box Market