
 Coated Paper Market | 2026-2036
Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Paper Market Analysis
Maintenance contracts for coating chemical recovery systems is rebalancing how mills monetize output beyond tonnage. Sappi Ltd leverages captive pulp supply in South Africa and North America to sustain margin control across fine paper grades. UPM-Kymmene Corp anchors European demand through integrated forestry-to-coating operations in Finland. Oji Holdings Corporation specializes in lightweight coated rolls for Japanese magazine publishers, occupying a defensible niche against regional competitors.
Coated paper consists of a base substrate—typically bleached chemical pulp or mechanical pulp—overlaid with mineral pigments such as kaolin clay and calcium carbonate bound with synthetic latex, yielding surface smoothness measured in Sheffield units below 200 for premium grades. Its primary purpose is to deliver high-resolution print reproduction with controlled ink absorption for commercial publishing and consumer packaging. Coated fine paper dominates margin pools in annual reports and luxury brand collateral, while coated specialty paper captures growth in pharmaceutical leaflets and food-contact labels. Coated groundwood paper remains structurally mature in catalog segments, pressured by postal rate inflation and retailer's shift to digital alternatives.
FDA food-contact substance notifications govern coated paper used in direct-contact packaging applications in the United States, while EU REACH restrictions on perfluorinated compounds constrain certain stain-resistant coating chemistries. China's GB standards for printing and packaging materials, enforced by SAMR, mandate heavy metal limits that reshape import qualification protocols for coated substrates. Stakeholders must monitor coating formulation disclosure requirements across jurisdictions, as chemical transparency rules tighten and brand owners demand certified recyclable streams.
Market Dynamics
Asia-Pacific packaging converters are aggressively expanding coated paperboard specifications to displace single-use plastics, while EU Ecodesign for Sustainable Products Regulation tightens recyclability thresholds that reshape substrate qualification protocols across export supply chains.
Growth Catalysts
- EU Ecodesign Regulation:Tightened recyclability thresholds for coated substrates force mills to reformulate mineral-pigment binders, accelerating demand for certified recyclable streams among brand owners.
- India's e-commerce fulfillment:Domestic publishing and e-commerce fulfillment drive sheet-fed coated orders, concentrating volume growth in South Asian packaging converters.
- Barrier coating chemistry:Advances in water-based polymer dispersions enable direct food-contact applications without fluorinated compounds, opening pharmaceutical leaflet and label segments.
Market Restraints
- Kaolin clay supply concentration:Premium-grade kaolin deposits concentrate in southeastern United States and Brazil, exposing coating costs to logistics volatility and export tariff friction.
- EU REACH restrictions:Perfluorinated compound limitations constrain stain-resistant coating chemistries, forcing reformulation cycles that extend qualification timelines for European converters.
- Digital substitution:Retail catalog segments face structural compression as postal rate inflation accelerates retailer migration to digital alternatives, eroding coated groundwood volume.
Strategic Opportunities
- India's domestic capacity gap:Underpenetrated domestic coated fine paper production creates white space for integrated forestry-to-coating investments serving publishing and luxury brand collateral.
- China's GB standard alignment:SAMR-mandated heavy metal limits for printing materials reshape import qualification, favoring regional mills with captive pulp and integrated coating operations.
- Pharmaceutical serialization:Track-and-trace mandates in European and North American markets expand demand for coated specialty paper with embedded security features and controlled ink absorption.
Industry Challenges
- Coating formulation disclosure:Chemical transparency rules across multiple jurisdictions require mills to document synthetic latex and mineral additive compositions, extending compliance timelines.
- Recovery system capex:Maintenance contracts for coating chemical recovery systems demand upfront capital deployment, compressing working capital availability for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Paper Market |
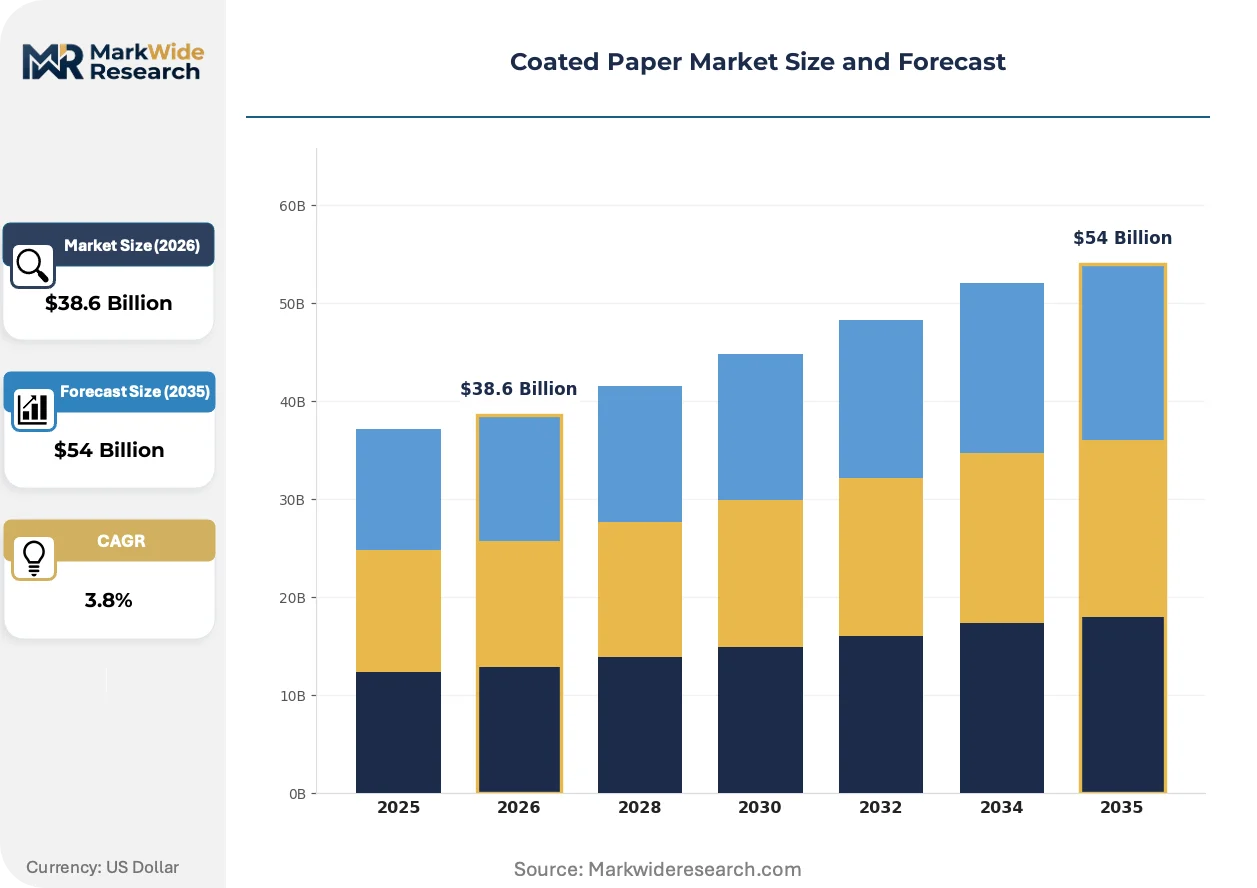
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Fine Paper, Coated Groundwood Paper, Coated Specialty Paper, Coated Art Paper End User: Publishing, Advertising, Packaging, Stationery Application: Magazines, Catalogs, Brochures, Labels Form: Sheet, Roll, Custom Size, Standard Size |
| Companies Covered | Sappi Ltd, UPM-Kymmene Corp, Stora Enso Oyj, Oji Holdings Corporation, Nippon Paper Industries, Asia Pulp & Paper Co. Ltd, Lecta Deutschland GmbH, Mondi plc, Dunn Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Paper Market Emerging Trajectories
Digital inkjet compatibility requirements are forcing coating layer redesigns, while sustainability mandates accelerate water-based binder substitution and barrier function diversification across packaging grades.
Water-based polymer dispersion technology is decentralizing barrier coating production by enabling regional mills to formulate food-contact-compliant surfaces without centralized fluorochemical supply chains. Japanese magazine publishers now specify lightweight coated rolls with inline aqueous barriers, compressing lead times from specialty chemical importers. This decentralization is fragmenting the historic concentration of barrier coating expertise among multinational chemical suppliers.
EU Ecodesign for Sustainable Products Regulation imposes mandatory recyclability thresholds on coated substrates entering European consumer goods supply chains. Mills must now demonstrate fiber recovery rates above specified minimums through third-party certification, forcing kaolin-to-calcium carbonate ratio adjustments. Finnish integrated operations have responded fastest, leveraging captive pulp streams to optimize coating layer delamination in standard repulping equipment.
Brand-owner specification consolidation is compressing supplier qualification cycles as multinational consumer goods companies centralize coated packaging procurement through sustainability scorecards. Converters in Germany and France now face consolidated tender processes that bundle volume across multiple product lines, displacing fragmented regional purchasing. This concentration is most visible in premium cosmetics and luxury spirits, where certified recyclable coated paperboard commands specification priority over uncertified alternatives.
Coated Paper Market Segmentation
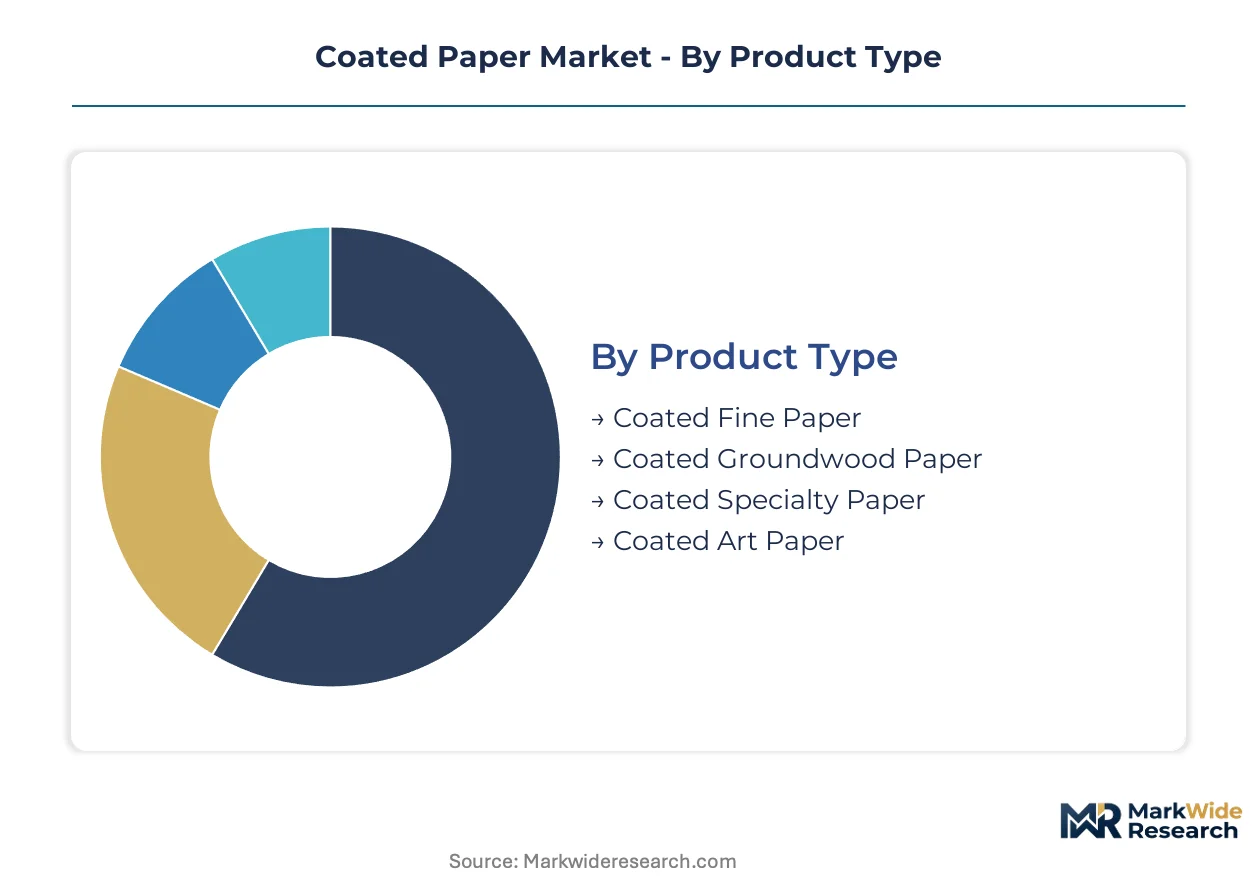
Coated paper segmentation reflects divergent margin structures across substrate grades and end-use requirements. Each category isolates distinct value pools where formulation chemistry, print compatibility, and regulatory compliance create separable competitive arenas.
Product Type:
Standalone premium grades command specification-driven procurement, while embedded commodity substrates compete on volume throughput and coating line efficiency.
- Coated Fine Paper:Bleached chemical pulp base with mineral pigment overlays below 150 Sheffield units delivers high-resolution reproduction for annual reports and luxury collateral. Demand concentrates in Indian domestic publishing and European cosmetics packaging, where EU Ecodesign recyclability certification now gates specification approval.
- Coated Groundwood Paper:Mechanical pulp substrate with lower brightness tolerances serves catalog and insert segments. Postal rate inflation across Germany and France accelerates retailer migration to digital alternatives, compressing volume in structurally mature North American catalog chains.
- Coated Specialty Paper:Functional coatings enable pharmaceutical leaflets and food-contact labels with controlled migration properties. FDA food-contact substance notifications and EU REACH perfluorinated restrictions reshape formulation roadmaps for direct-contact applications.
- Coated Art Paper:Ultra-smooth surfaces above 90 brightness support high-end photography reproduction and museum-quality prints. Japanese magazine publishers specify lightweight art paper variants with inline aqueous barriers.
Volume placements concentrate in coated fine paper; the faster expansion belongs to coated specialty paper.
End User:
Cost tier stratification separates brand-owner specification control from price-sensitive spot purchasing across converter tiers.
- Publishing:Magazine and book segments demand consistent printability across long press runs. Indian sheet-fed orders from domestic publishers concentrate growth in South Asian markets.
- Advertising:Point-of-sale and direct mail applications require rapid color turnaround with shorter run lengths. European brand owners now consolidate procurement through sustainability scorecards.
- Packaging:Coated paperboard specifications displace single-use plastics in Asia-Pacific converter expansion. Barrier coating chemistry advances enable direct food-contact compliance without fluorinated compounds.
- Stationery:Premium writing papers and corporate identity systems compete on tactile surface quality. Japanese specialty mills dominate lightweight coated stationery exports.
Margin concentration sits with packaging converters; publishing represents the most price-pressured tier.
Application:
Maturity gradients separate established print formats from emerging label and security applications with embedded authentication features.
- Magazines:Gloss and matte finishes for periodical publishing face digital substitution pressure. Japanese publishers specify lightweight coated rolls with compressed lead times.
- Catalogs:Retail distribution networks depend on postal economics and paper weight optimization. Groundwood-coated catalog volumes erode as retailers shift to digital alternatives.
- Brochures:Corporate and tourism marketing materials demand consistent color reproduction across regional print networks. EU Ecodesign thresholds now mandate third-party recyclability certification.
- Labels:Pharmaceutical serialization and track-and-trace mandates expand demand for security-featured coated substrates with controlled ink absorption.
Brochure volumes dominate current placements; label applications are climbing the fastest.
Form:
Supply concentration patterns differentiate standardized mill-run formats from customized dimension orders requiring dedicated sheeting investment.
- Sheet:Cut-size formats serve sheet-fed offset and digital presses in commercial printing. Indian e-commerce fulfillment drives sheet-fed coated orders for packaging inserts.
- Roll:Web-fed gravure and flexographic operations demand continuous substrate supply with splice consistency. Finnish integrated operations optimize roll formats for coating layer delamination in repulping.
- Custom Size:Non-standard dimensions for specialty packaging and display applications require sheeting line flexibility. Brand-owner consolidation compresses custom size qualification cycles.
- Standard Size:Mill-run dimensions maximize coating line throughput and minimize trim waste. Standard sizes dominate Asia-Pacific packaging converter procurement.
Roll formats capture the largest volume share; custom size orders gain share fastest in premium cosmetics segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coated paper production concentrates in pulp-rich northern latitudes while consumption gravitates toward Asia-Pacific packaging hubs and European print markets. This geographic split creates trade flows calibrated to coating chemistry expertise and e-commerce fulfillment density.
United States
Domestic publishing and direct-mail advertising sustain sheet-fed coated demand, though catalog volumes face compression from postal rate inflation. FDA food-contact substance notifications govern barrier-coated packaging substrates entering foodservice supply chains. Southeastern kaolin deposits near Sandersville, Georgia anchor premium pigment supply for coating operations serving Atlanta-based packaging converters.
China
GB standards enforced by SAMR mandate heavy metal limits for printing materials, reshaping import qualification protocols for coated substrates. Domestic e-commerce fulfillment drives massive roll-format consumption for corrugated box liners and shipping inserts. Yangtze River Delta mills around Shanghai optimize coating line throughput for standardized packaging specifications demanded by Shenzhen electronics exporters.
India
Domestic publishing and e-commerce fulfillment concentrate sheet-fed coated orders among Mumbai and Delhi-NCR converters. Bureau of Indian Standards certification requirements for printing and packaging materials tighten substrate qualification timelines. Gujarat-based integrated pulp-to-paper operations expand capacity to capture underpenetrated fine paper demand from luxury brand collateral producers.
Finland
EU Ecodesign for Sustainable Products Regulation recyclability thresholds force kaolin-to-calcium carbonate ratio adjustments in coating formulations. Integrated forestry-to-coating operations leverage captive pulp streams to optimize delamination in standard repulping equipment. Tampere-region mills supply certified recyclable coated paperboard to German cosmetics packaging converters facing consolidated sustainability scorecards.
Japan
Lightweight coated roll specifications from magazine publishers compress lead times and favor inline aqueous barrier integration. METI industrial standards govern printing material quality specifications for commercial publishing applications. Tokyo-Osaka corridor converters specialize in ultra-smooth art paper variants for museum-quality photography reproduction and high-end periodicals.
Coated Paper Market Vendor Landscape
Capital-heavy integrated pulp producers compete with specialty converters lacking captive fiber supply. The market structures around three tiers: multinational forestry-anchored giants with coating chemistry R&D, regional packaging-focused converters exploiting logistics proximity, and niche art paper specialists serving premium print segments. Strategic moves concentrate on coating formulation partnerships with chemical suppliers and certification investments for EU Ecodesign compliance.
Among forestry-anchored multinationals, Sappi Ltd and UPM-Kymmene Corp exemplify integrated operations sustaining margin control through captive pulp supply. Oji Holdings Corporation occupies a defensible position in lightweight coated rolls for Japanese publishing. These three represent distinct geographic anchoring strategies—South African and North American pulp bases, Finnish integrated forestry operations, and Japanese specialty magazine supply—rather than competing directly across all grade specifications.
| Leading Market Players |
|---|
| Sappi Ltd |
| UPM-Kymmene Corp |
| Stora Enso Oyj |
| Oji Holdings Corporation |
| Nippon Paper Industries |
| Asia Pulp & Paper Co. Ltd |
| Lecta Deutschland GmbH |
| Mondi plc |
| Dunn Paper Company |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign certification tiers bifurcate coated paper procurement into premium recyclable streams and uncertified commodity grades, concentrating pricing power among Finnish and South African integrated mills while compressing margins for regional converters lacking captive pulp supply.
Pricing Analysis
Cost compression in coated groundwood grades accelerates as German and French retailers migrate catalog volumes to digital channels, eroding spot-market premiums. Three-tier pricing structure across premium fine paper, standard packaging board, and economy catalog grades separates specification-controlled brand-owner procurement from price-sensitive converter spot purchasing. Premium-mid-economy pricing differentiation hinges on EU Ecodesign recyclability certification and FDA food-contact notification status. Brand-owner sustainability scorecards in cosmetics and spirits segments demonstrate least price sensitivity; mid-scale Asian packaging converters face acute margin pressure from kaolin logistics volatility.
Supply Chain Analysis
Skilled coating chemistry formulation talent concentrates in Finland's Tampere region and Japan's Tokyo-Osaka corridor, constraining rapid capacity scaling outside established mill clusters. Raw material supply draws from southeastern United States kaolin deposits, Brazilian calcium carbonate reserves, and synthetic latex production in Germany and South Korea. Single-source vulnerability in fluorinated compound alternatives exposes European converters to extended REACH qualification timelines. Distribution runs through integrated forestry-to-coating operations supplying German cosmetics packagers and Indian e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign for Sustainable Products Regulation erects a compliance moat around certified recyclable coated substrates, advantaging integrated mills with captive pulp streams over regional converters dependent on spot fiber purchases.
For Market Incumbents: Extend certification coverage across coated specialty paper grades to capture pharmaceutical serialization demand, while consolidating coating chemical recovery system maintenance contracts to lock in converter relationships. Digital substitution in retail catalog segments threatens coated groundwood volumes; backward integration into kaolin processing or captive latex synthesis secures formulation cost control against Brazilian and German chemical suppliers. For New Entrants and Emerging Players: Direct-to-brand-owner digital sampling platforms bypass incumbent converter gatekeepers in Indian luxury collateral and European cosmetics packaging segments. Gujarat's underpenetrated coated fine paper capacity gap offers the most penetrable white space; qualification acceleration through Bureau of Indian Standards pre-certification programs enables faster specification entry against established South Asian competitors. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pulp-to-paper operators possessing EU Ecodesign third-party certification, given tightening recyclability thresholds that structurally disadvantage merchant converters. Long-term viability centers on coating chemistry R&D capabilities and barrier formulation expertise. The signal to watch is consolidation in Indian domestic publishing supply chains as e-commerce fulfillment drives sheet-fed volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| EU Ecodesign Certification Investment | Third-party recyclability validation gates specification approval for German cosmetics packagers. |
| Water-Based Barrier Formulation Partnership | Collaboration with polymer dispersion suppliers enables FDA-compliant food-contact coating chemistry. |
| Integrated Pulp-to-Coating Capacity Expansion | Gujarat-based captive fiber supply captures underpenetrated Indian fine paper demand. |
| Coating Chemical Recovery System Deployment | Maintenance contract structures monetize output through service revenue beyond tonnage sales. |
| Pharmaceutical Security Feature Integration | Track-and-trace mandated serialization expands coated specialty paper specification pools. |
Methodological Framework
Independent corroboration across mill operations directors, packaging converter procurement leads, and coating chemical suppliers underwrites the qualitative findings in this study. Primary interviews with Finnish integrated forestry operators, Indian sheet-fed printing specialists, and Japanese magazine publishing supply managers combined with secondary validation from customs trade databases, SEC 10-K pulp and paper segment disclosures, and SAMR GB standard enforcement records. Bottom-up volume modeling triangulates against top-down pulp consumption benchmarks.
Rate-of-change decomposition across the projection horizon isolates volume drivers by coated paper grade tier, end-use industry concentration, and regional regulatory cluster intensity. Segmentation dimensions span product type, application format, and form specification, with coating chemistry compatibility and recyclability certification status as industry-specific forecast inputs. CAGRs derive from installed coating capacity utilization trends and pulp-to-paper integration economics across the modeling period.
The model holds under sustained EU Ecodesign enforcement and stable kaolin logistics costs; deviation in REACH perfluorinated compound restrictions or Indian e-commerce growth deceleration would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market