
 Italy Paper Packaging Market | 2026-2036
Italy Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Paper Packaging Market Insights
Market Context
Multi-source procurement for recycled pulp is repositioning how Italian converters secure fiber supply against price volatility. Smurfit Kappa Italia S.p.A. leverages its integrated mill network across the peninsula to stabilize input costs. Stora Enso Oyj anchors Nordic kraftliner flows into Mediterranean corrugated operations. DS Smith Packaging Italia S.p.A. specializes in shelf-ready formats for grocery retail chains.
Technical Definition and Segment Structure
Italy paper packaging encompasses paper-based containers, wraps, and labels engineered from virgin or recycled cellulose fibers, typically ranging from 150 gsm cartonboard to 450 gsm corrugated medium, designed to protect, transport, and merchandise goods across supply chains. Boxes dominate volume throughput in the food and beverage end use industry, where shelf-ready cases command premium positioning fees from retail buyers. Bags within personal care applications sustain faster growth as brands phase out plastic laminates under EU single-use directives.
Regulatory Framework and Outlook
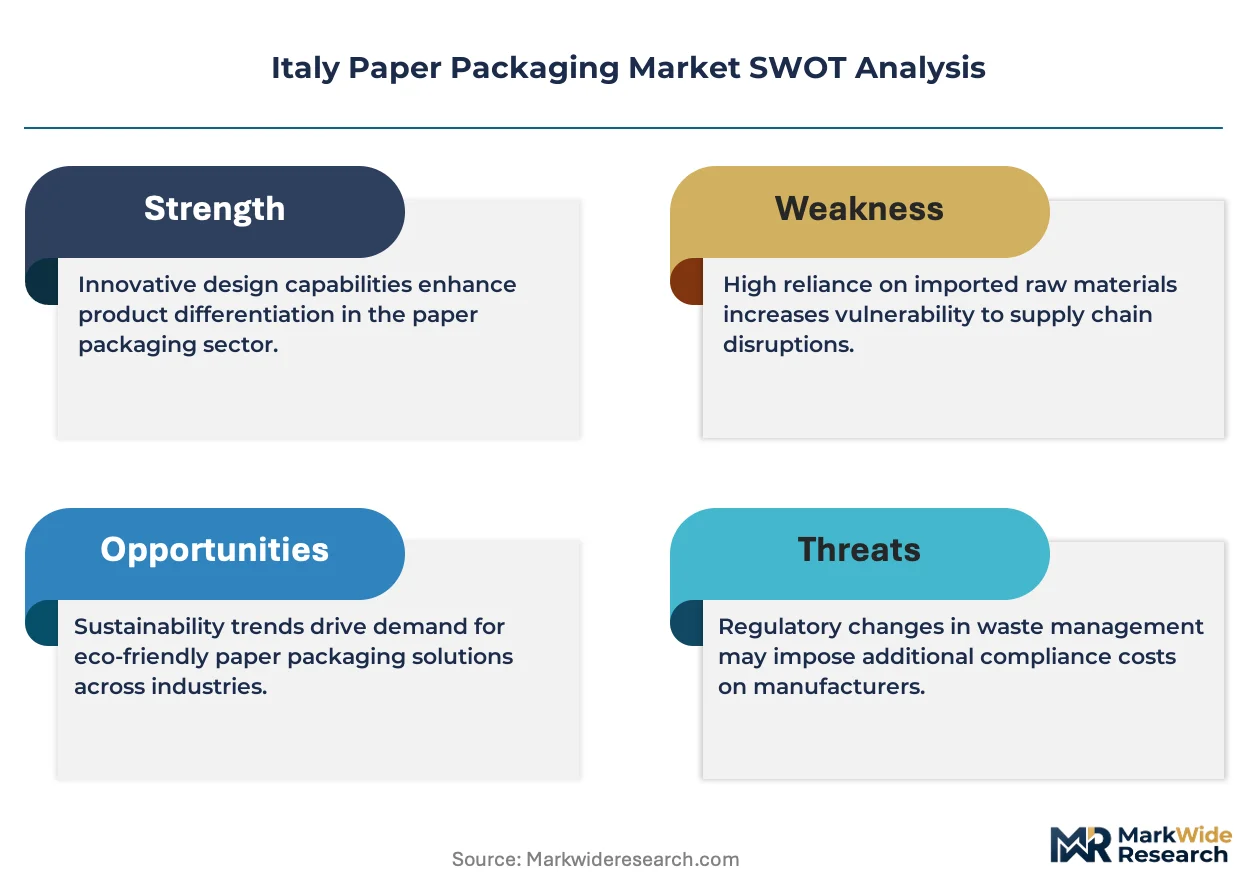
Italy's paper packaging sector operates under the EU Packaging and Packaging Waste Regulation, CE marking requirements, and national CONAI packaging consortium fees that penalize non-recyclable formats. ECHA REACH compliance constrains coatings and barrier additives, pushing converters toward water-based alternatives. Stakeholders must monitor how Italy's transposition of the EU Green Deal accelerates mandatory recycled content thresholds without sufficient domestic recovered paper collection infrastructure.
Market Dynamics
Italian converters face mounting pressure from the EU Packaging and Packaging Waste Regulation's mandatory recycled content floors, forcing mill-level investment in deinking capacity and fiber recovery systems across Lombardy and Emilia-Romagna production clusters.
Growth Catalysts
- Eco-modulated CONAI fees:Italy's packaging consortium penalizes non-recyclable formats while rewarding mono-material paper designs, redirecting investment toward water-based barrier coatings.
- Food and beverage export expansion:Premium shelf-ready cartonboard formats command positioning fees from German and French retail buyers, pulling volume through Northern Italian manufacturing corridors.
- Plastic laminate phase-out:EU single-use directives accelerate paper substitution in personal care sachets and flexible wraps, opening new substrate specifications for Italian converters.
Market Restraints
- Recovered paper supply deficit:Domestic collection infrastructure lags mandated recycled content thresholds, forcing dependence on Nordic and German pulp imports subject to freight volatility.
- ECHA REACH coating constraints:Barrier additive approvals face extended toxicology review timelines, delaying commercialization of grease-resistant alternatives to fluorinated chemistries.
- Energy cost exposure:Natural gas-intensive drying operations at Italian mills create margin compression against Nordic competitors with biomass and hydroelectric captive supply.
Strategic Opportunities
- Southern Italy capacity gaps:Calabria and Sicily lack integrated corrugated plants, creating white space for regional distribution hubs serving Mediterranean shipping lanes.
- Pharmaceutical serialization integration:Track-and-trace mandates under EU Falsified Medicines Directive enable premium folding carton positioning with embedded authentication features.
- Cellulose nanofiber barrier convergence:Cross-laminated nano-cellulose layers replace plastic films in modified atmosphere produce packs, unlocking fresh protein and ready-meal applications.
Industry Challenges
- Deinking technician scarcity:Specialized operators for high-consistency pulping and contaminant removal are concentrated among retiring workforce cohorts in Tuscany mills.
- Legacy ERP integration friction:Converter order-to-delivery systems require reconfiguration for mass-customization workflows demanded by e-commerce channel buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Paper Packaging Market |
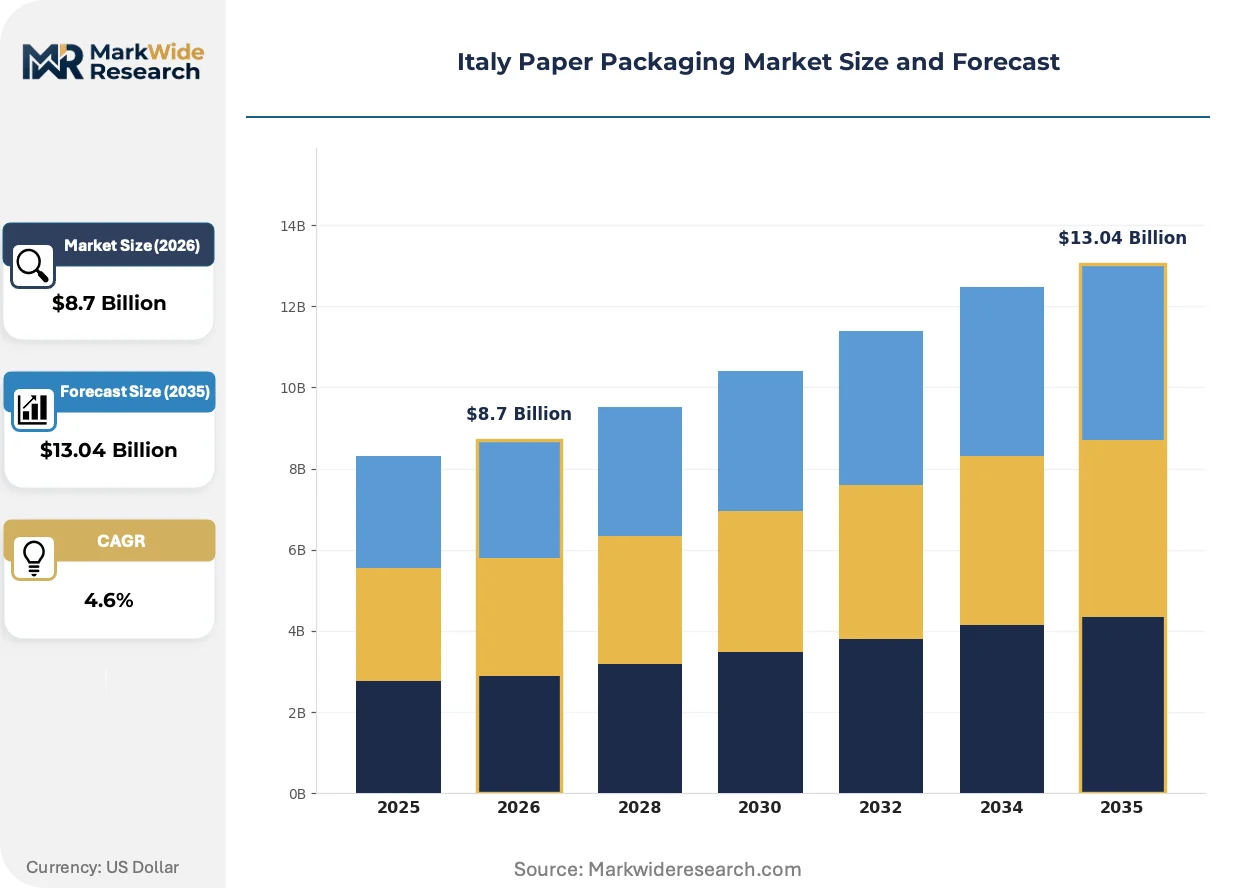
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Labels End Use Industry: Food & Beverage, Personal Care, Electronics, Pharmaceuticals Thickness: Lightweight, Mediumweight, Heavyweight, Custom Distribution Channel: Online, Wholesale, Retail, Direct |
| Companies Covered | Tetra Pak International SA, Stora Enso Oyj, Smurfit Kappa Italia S.p.A., Carton Pack SpA, Smurfit WestRock, DS Smith Packaging Italia S.p.A., Mondi plc, Italpack Cartons Srl, International Paper Italia S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Paper Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing run-length economics while enabling batch-level traceability demanded by Italian food exporters and retail compliance programs.
Water-based barrier coatings is overtaking extruded polyethylene laminates in chilled food applications. Mid-size Bologna converters are adopting these formulations to secure listings with Coop Italia and Conad procurement panels. The shift is overtaking conventional multi-material structures that previously dominated ready-meal and fresh pasta segments.
Italy's transposition of the EU Green Deal accelerates mandatory recycled content verification through blockchain-tracked mass balance accounting. Domestic mills must demonstrate fiber provenance from municipal collection streams rather than industrial scrap. Food contact cartonboard grades face the steepest compliance burden under EFSA safety assessments.
Consolidated grocery retail procurement is compressing supplier rosters toward full-service packaging partners capable of design-to-shelf coordination. Smaller Veneto converters lose access to Esselunga and Selex central buying unless they integrate structural design with logistics optimization. The pattern concentrates volume among integrated players with in-house sample prototyping and retail-ready format libraries.
Italy Paper Packaging Market Segmentation
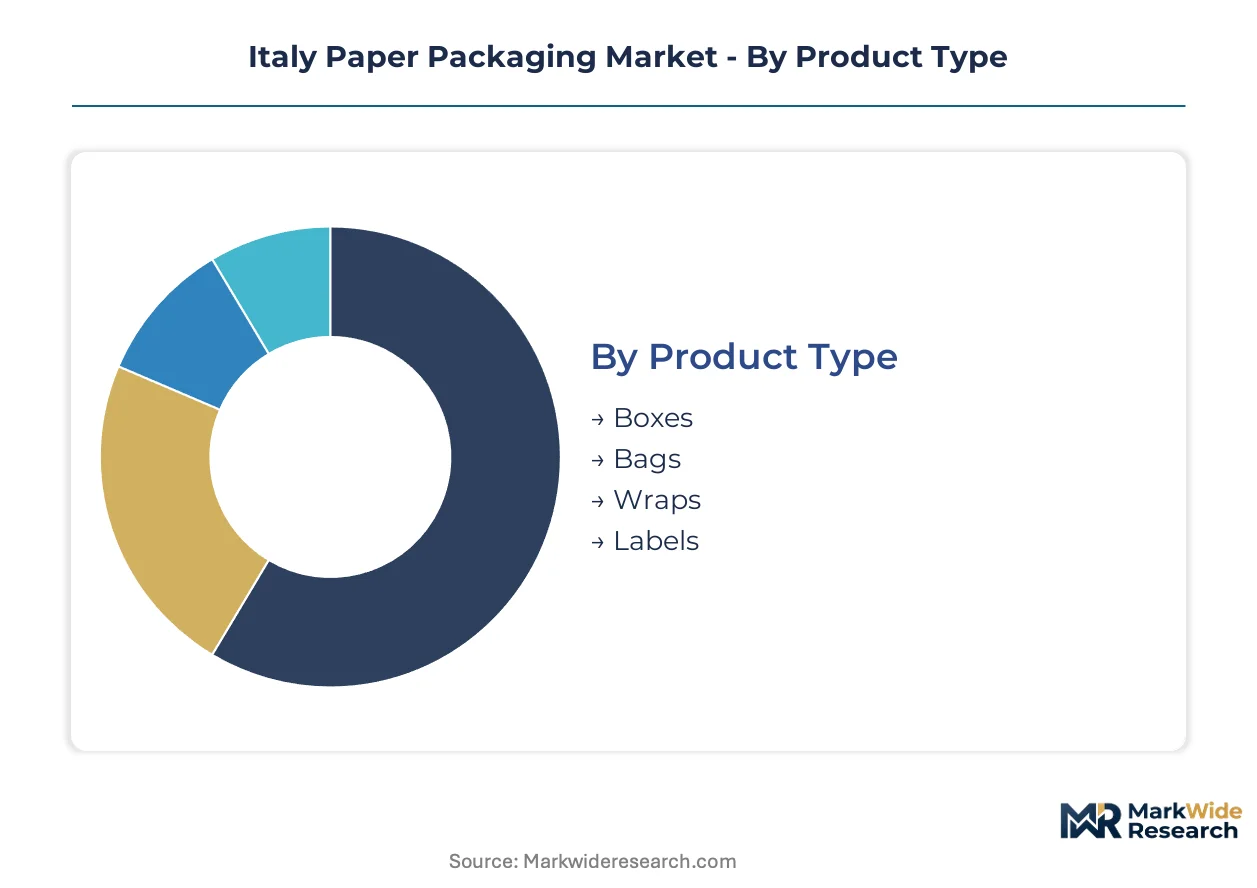
Italian converters configure production lines around thickness specifications and end-use performance requirements rather than commodity volume plays. Procurement panels at Coop Italia and Conad central buying desks filter supplier rosters through product-type compatibility and distribution-channel responsiveness criteria.
Product Type:
Retail buyers prioritize structural integrity and shelf-ready merchandising performance when selecting among format categories.
- Boxes:Corrugated and folding carton structures ranging from 150 gsm cartonboard to 450 gsm corrugated medium protect goods through distribution. Lombardy manufacturing corridors concentrate volume for German and French retail export channels where shelf-ready cases command positioning fees.
- Bags:Flexible paper substrates with twisted or flat handles serve personal care and specialty food applications. EU single-use directives accelerate substitution for plastic laminates in sachets and pouches, opening substrate specifications for Bologna-area converters.
- Wraps:Lightweight kraft and grease-resistant papers encase fresh produce and baked goods for direct retail sale.
- Labels:Pressure-sensitive and wet-glue adhesive papers carry branding and regulatory information across beverage and pharmaceutical containers.
Volume sits with Boxes; growth tilts toward Bags.
End Use Industry:
Regulatory compliance intensity and barrier performance requirements segment demand by application vertical.
- Food & Beverage:Modified atmosphere and chilled applications dominate Italian converter output. EFSA safety assessments for food contact cartonboard impose the steepest compliance burden on domestic mills verifying fiber provenance through blockchain-tracked mass balance accounting.
- Personal Care:Brands phase out plastic laminates under EU single-use directives, pulling paper substitution into sachets and flexible wraps. Water-based barrier coatings overtake extruded polyethylene laminates as Coop Italia and Conad procurement panels demand mono-material designs.
- Electronics:Anti-static corrugated and molded pulp cushions protect high-value components through e-commerce fulfillment networks.
- Pharmaceuticals:EU Falsified Medicines Directive track-and-trace mandates enable premium folding carton positioning with embedded authentication features.
Food & Beverage captures the revenue base; Personal Care expands most quickly.
Thickness:
Grammage selection directly determines machinery compatibility and end-use structural performance.
- Lightweight:Sub-200 gsm papers and wraps serve labels, interleaving, and protective overwrap applications with minimal material cost.
- Mediumweight:200-350 gsm folding cartonboard balances rigidity and convertibility for retail-ready formats across grocery and personal care segments.
- Heavyweight:350-450 gsm double-wall corrugated and solid fiberboard withstands stacking stress in palletized distribution for export-oriented food producers.
- Custom:Engineered specifications for pharmaceutical serialization integration and cellulose nanofiber barrier layers target fresh protein and ready-meal modified atmosphere packs.
Mediumweight commands the production hours; Custom specifications gain share fastest.
Distribution Channel:
Order-to-delivery speed and minimum run-length flexibility separate channel economics.
- Online:Digital storefronts enable direct converter-to-brand relationships with batch-level customization for mid-size personal care startups.
- Wholesale:Distributor networks aggregate demand from fragmented retail and foodservice accounts across Southern Italy capacity gaps.
- Retail:Consolidated grocery procurement compresses supplier rosters toward full-service partners with design-to-shelf coordination capabilities.
- Direct:Mill-direct relationships stabilize input costs for large-volume exporters leveraging integrated mill networks across the peninsula.
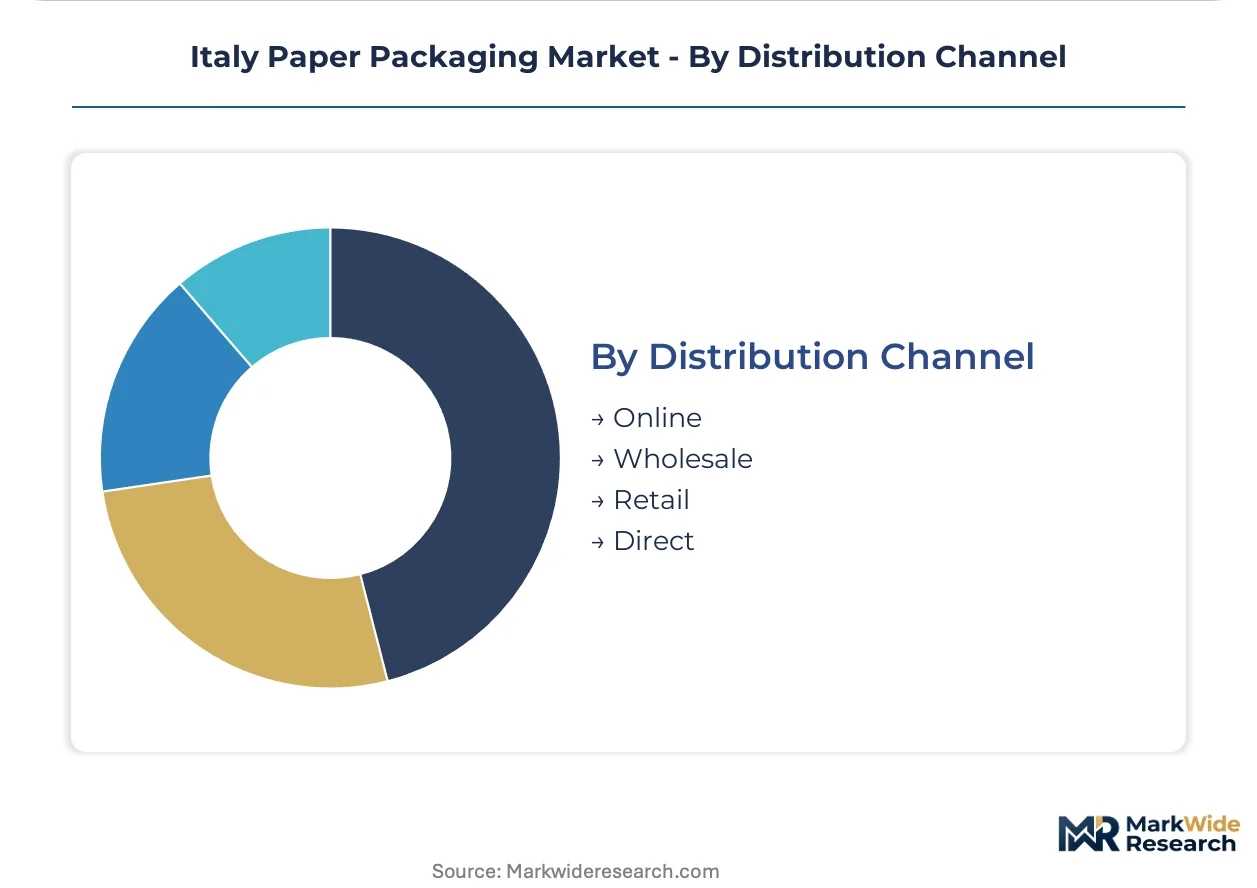
Retail concentrates the tonnage; Online climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian paper packaging demand clusters in Northern manufacturing belts, with Lombardy and Emilia-Romagna corridors processing the majority of export-oriented food and beverage volume. Southern regions present underdeveloped capacity relative to Mediterranean shipping lane access.
Lombardy
Milan's logistics hub anchors shelf-ready cartonboard production for German and French retail buyers demanding premium positioning formats. CONAI eco-modulation fees redirect converter investment toward water-based barrier coatings. Integrated mill networks in the Brianza zone stabilize fiber supply against Nordic import volatility.
Emilia-Romagna
Bologna-area converters supply Coop Italia and Conad procurement panels with modified atmosphere produce packs. EFSA food contact assessments impose compliance burdens on local mills verifying blockchain-tracked fiber provenance. The Packaging Valley cluster concentrates digital printing adoption for batch-level customization.
Piedmont
Turin-based automotive suppliers drive anti-static corrugated demand for component protection through e-commerce channels. EU Green Deal transposition accelerates recycled content verification requirements. Alpine proximity enables kraftliner rail flows from Nordic producers.
Veneto
Esselunga and Selex central buying desks compress supplier rosters toward full-service partners with design-to-shelf capabilities. Smaller converters face exclusion without integrated structural design and logistics optimization. The Treviso zone specializes in pharmaceutical serialization folding cartons under EU Falsified Medicines Directive mandates.
Tuscany
Pulp and paper heritage concentrates deinking technician expertise in Lucca and Pistoia mill zones. Retiring workforce cohorts create specialized operator scarcity for high-consistency pulping operations. Regional mills serve premium wine export packaging with ECHA REACH-compliant barrier formulations.
Italy Paper Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters respond to EU Packaging and Packaging Waste Regulation mandates. The vendor base organizes around three tiers: integrated multinational mill-converter hybrids, regional specialists with retail-ready format libraries, and mid-size Bologna-area players pivoting toward water-based coatings. Strategic archetypes include fiber-integrated cost leaders, design-service differentiation players, and niche pharmaceutical serialization specialists. M&A consolidation and mill-level deinking investment represent the dominant competitive moves reshaping positioning.
Among Nordic-anchored multinationals, Stora Enso Oyj exemplifies the integrated fiber-to-box archetype with kraftliner flows into Mediterranean operations. Smurfit Kappa Italia S.p.A. occupies a position within the peninsula-integrated cost leadership tier, while DS Smith Packaging Italia S.p.A. represents the retail-ready design-service differentiation model serving grocery central buying desks.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| Stora Enso Oyj |
| Smurfit Kappa Italia S.p.A. |
| Carton Pack SpA |
| Smurfit WestRock |
| DS Smith Packaging Italia S.p.A. |
| Mondi plc |
| Italpack Cartons Srl |
| International Paper Italia S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Recovered pulp fiber costs cascade through Italian converter pricing tiers, with Nordic kraftliner imports from Sweden and Finland anchoring premium corrugated grades while domestic deinked pulp feeds standard cartonboard production for Coop Italia and Conad procurement panels. Natural gas-intensive drying operations at Lombardy mills compress margins against Nordic biomass-powered competitors, forcing price differentiation between energy-exposed domestic output and imported linerboard.
Pricing Analysis
Volume throughput concentrates in standard-grade folding cartonboard for grocery retail chains, while margin capture tilts toward custom-engineered pharmaceutical serialization cartons with embedded authentication features. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA food contact certification status, fiber provenance verification, and design-to-shelf service bundling. Pricing pressure stems from CONAI eco-modulation fees penalizing non-recyclable formats and redirecting investment toward water-based barrier coatings. Small Veneto converters face acute price sensitivity without integrated structural design capabilities, whereas peninsula-integrated multinationals command premium positioning through captive mill networks.
Supply Chain Analysis
Post-consumer paper collection flows from municipal streams through Tuscan deinking facilities, yet domestic recovered fiber supply lags mandated recycled content thresholds under EU Packaging and Packaging Waste Regulation. Italian converters draw from Nordic kraftliner imports, German recycled pulp shipments, and domestic cartonboard production clustered in Lombardy and Emilia-Romagna corridors. Single-source vulnerability concentrates in Nordic linerboard flows through Alpine rail chokepoints subject to energy cost volatility and freight disruption. Distribution runs through consolidated grocery retail procurement desks compressing supplier rosters toward full-service partners with in-house sample prototyping capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are forcing consolidation among mid-size Bologna-area converters lacking deinking investment capacity, with weaker players exiting as compliance costs escalate and procurement panels demand mass-customization workflows.
For Market Incumbents: Lock in fiber supply security through backward integration into Tuscan deinking capacity or long-term offtake agreements with Nordic kraftliner producers, defending against substitute plastic barrier technologies and emerging cellulose nanofiber specialists. Prioritize water-based coating R&D to secure listings with Coop Italia and Conad central buying desks before regulatory deadlines tighten.
For New Entrants and Emerging Players: Direct-to-brand digital storefronts enable bypass of consolidated retail procurement gatekeepers, targeting mid-size personal care startups in Northern Italy seeking batch-level customization and fast sample turnaround. White space concentrates in Southern Italy's Calabria and Sicily distribution hubs serving Mediterranean shipping lanes, where corrugated capacity gaps persist and regional wholesale networks aggregate fragmented foodservice demand.
For Investors and Strategic Acquirers: Deinking technician scarcity in Tuscany's retiring workforce cohorts is the leading indicator that specialized operator training investments will differentiate viable acquisition targets from stranded assets. Long-term viability hinges on fiber-provenance verification infrastructure and blockchain-tracked mass balance accounting capabilities. Monitor ECHA REACH barrier additive approval timelines for grease-resistant alternatives as the signal for coating technology inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Mill-Level Deinking Investment | Captive fiber recovery from municipal streams secures compliance with EU recycled content mandates. |
| Water-Based Barrier Coating Adoption | Mono-material designs qualify for CONAI eco-modulation rewards and Coop Italia procurement listings. |
| Pharmaceutical Serialization Integration | EU Falsified Medicines Directive track-and-trace mandates enable premium folding carton positioning. |
| Southern Italy Distribution Hub Buildout | Calabria and Sicily capacity gaps create regional consolidation opportunities serving Mediterranean lanes. |
| Digital Printing Platform Deployment | Batch-level customization capabilities unlock e-commerce channel demand from mid-size brand startups. |
Research Methodology
CONAI packaging consortium fee schedules, EU ECHA REACH substance registrations, and Italian customs trade data formed the secondary backbone, cross-referenced with primary interviews involving converter operations managers, grocery retail procurement directors at Esselunga and Selex, and deinking technician training coordinators in Tuscany. Mill-level production data and corrugated capacity utilization metrics were validated against Nordic producer export disclosures and EFSA food contact safety assessments. Bottom-up segment sizing triangulated with top-down macroeconomic anchors across the analysis window.
Bottom-up modeling built volume and value outputs from machinery installation counts, grammage-specific throughput rates, and end-use industry demand patterns across food and beverage, personal care, electronics, and pharmaceutical verticals. Top-down constraints applied EU Green Deal recycled content trajectory assumptions and CONAI fee evolution scenarios. CAGRs were derived from segment-level growth rate blending weighted by revenue concentration in Northern Italy manufacturing corridors, with energy cost exposure and fiber import dependency as key forecast sensitivity inputs.
The model holds under stable EU regulatory implementation timelines; deviation in ECHA REACH barrier additive approval schedules or Nordic pulp supply disruptions would shift volume and value trajectories. Forecasts embed assumptions regarding municipal recovered paper collection infrastructure expansion and natural gas price normalization for Italian drying operations. Practitioners should monitor Tuscan deinking workforce retirement rates and blockchain fiber provenance pilot scalability for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
C1S Packaging Paper Market