
 Paper Release Liners Market | 2026-2036
Paper Release Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Release Liners Market Analytics
The paper release liners industry is pivoting toward divergent supply economics, with premium silicone-coated grades commanding sustained margin premiums while commodity polyethylene-coated volumes compete on throughput efficiency. LINTEC Corporation leverages its Asian manufacturing scale to dominate high-precision electronics applications. Sappi Limited anchors European demand through integrated pulp-to-liner production. Mondi Group specializes in sustainable substrate formulations that differentiate its offering in regulated medical and food-contact segments.
Paper release liners are engineered substrates, typically glassine or supercalendered kraft paper, treated with release agents such as solvent-based or emulsion silicone to achieve controlled peel forces between 5 and 50 grams per inch. These liners protect adhesive surfaces during converting, storage, and application across pressure-sensitive tape, label, and medical product manufacturing. Silicone coated liners lead value generation due to thermal stability requirements in automotive and electronics bonding applications, while medical device demand concentrates in acrylic coated variants where hypoallergenic release profiles command premium positioning. Non-coated segments occupy mature, cost-driven volumes in furniture and general industrial masking.
REACH in Europe governs silicone emulsion chemistries and substrate recyclability, while FDA 21 CFR substrate biocompatibility standards shape medical-grade liner qualification pathways in the United States. ISO 13485 quality system requirements further constrain supplier selection for device OEMs, consolidating procurement toward vertically qualified paper mills. Stakeholders must monitor evolving PFAS restrictions under EPA and state-level frameworks, as fluorochemical-free release coatings will determine qualification continuity across North American medical and food packaging channels.
Market Dynamics
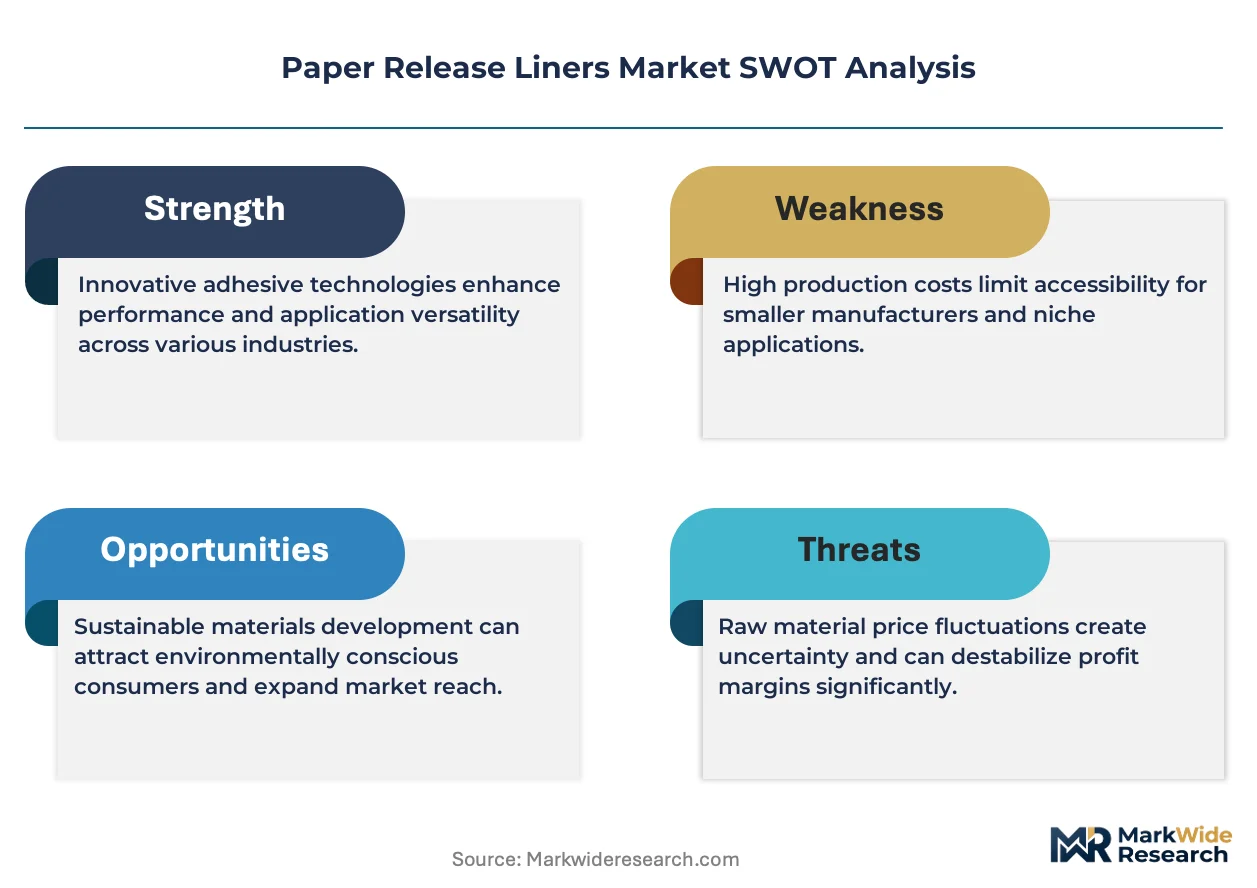
Silicone-coated liner specifications are tightening under converging FDA biocompatibility and REACH chemical disclosure mandates, forcing substrate suppliers to requalify formulations and compressing the qualified supplier base for medical-grade applications.
Growth Catalysts
- REACH Chemical Disclosure:European ECHA registration requirements for silicone emulsion chemistries are accelerating substrate recyclability investments and consolidating procurement toward vertically integrated paper mills with in-house coating capabilities.
- Wound Care Adhesive Expansion:Medical device manufacturers in Germany's Rhine corridor are scaling procurement of acrylic-coated liners for hypoallergenic diagnostic assemblies and transdermal drug delivery patches.
- Electronics Bonding Thermal Stability:Automotive OEMs in Japan and South Korea are specifying high-temperature silicone-coated liners for battery module assembly tapes, creating specification premiums over standard polyethylene-coated grades.
Market Restraints
- Pulp Cost Volatility:Glassine and supercalendered kraft substrate margins compress when northern bleached softwood pulp futures spike, exposing unintegrated converters to raw material pass-through limitations.
- Supplier Concentration Risk:Asia-Pacific silicone emulsion production clusters in Jiangsu province and the Osaka-Kobe corridor, creating single-source vulnerability for European and North American liner coaters.
- Fluorochemical Substitution Lag:PFAS-free release coatings remain technically immature for high-speed label converting, leaving medical and food-contact segments exposed to pending EPA state-level restrictions.
Strategic Opportunities
- India Medical Device Localization:CDSCO medical device rules and PLI scheme incentives are attracting liner converters to establish coating operations near Ahmedabad and Chennai diagnostic manufacturing clusters.
- Digital Printing Substrate Convergence:Inkjet-compatible release liners combining controlled porosity with silicone stability are capturing share from thermal transfer label stocks in e-commerce logistics applications.
- EU Green Deal Circular Mandates:Recyclable liner substrates certified under emerging EN 13432 compostability standards command procurement preference from multinational food and personal care brands.
Industry Challenges
- ISO 13485 Certification Timelines:Medical-grade liner qualification cycles now extend eighteen to twenty-four months, locking working capital and delaying revenue recognition for substrate suppliers entering device supply chains.
- Coating Technician Scarcity:Solvent-based silicone application expertise is retiring faster than emulsion technology training programs can replace, constraining capacity expansion at mid-tier converting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Release Liners Market |
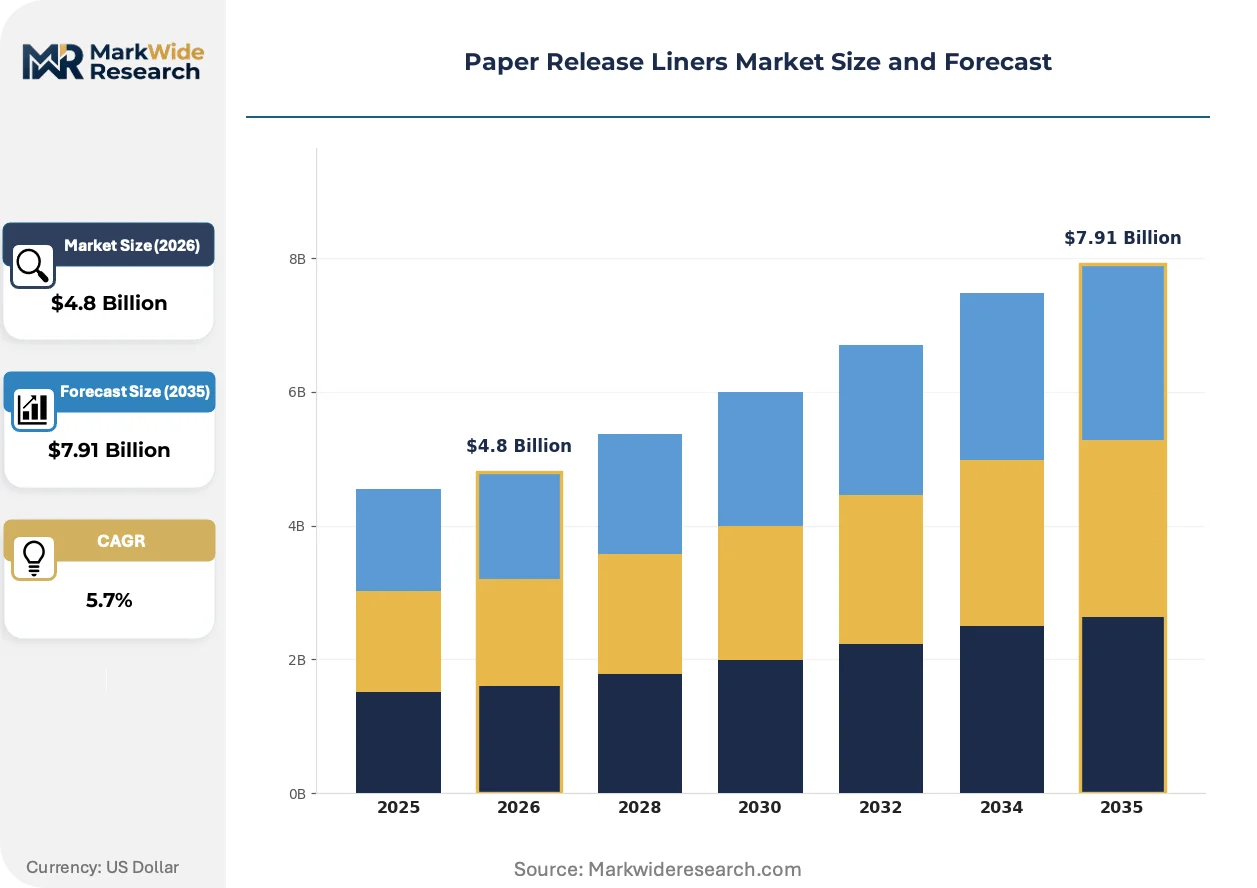
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Coated, Polyethylene Coated, Acrylic Coated, Non-Coated Application: Labeling, Tapes, Medical Devices, Furniture End User: Food & Beverage, Healthcare, Automotive, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | LINTEC Corporation, Loparex International B.V., Sappi Limited, UPM Raflatac, Ahlstrom-Munksjö, 3M Company, Mondi Group, Stora Enso Oyj, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Release Liners Market Evolving Landscape
Release liner technology is fragmenting into application-specific formulations, with coating chemistry and substrate engineering diverging sharply between medical, electronics, and industrial adhesive end-uses.
Water-based silicone emulsion coatings are modularizing release liner production by enabling lower-temperature curing and reduced volatile organic compound emissions compared to solvent-based systems. Electronics manufacturers in Japan and South Korea are adopting these formulations for flexible circuit bonding tapes. The technology is modularizing coating line configurations, allowing converters to switch between medical and industrial grades without dedicated solvent recovery infrastructure.
EPA state-level PFAS restrictions are forcing fluorochemical-free release coating development across North American medical and food packaging channels. Coating suppliers are reformulating with plant-derived waxes and plasma-treated surfaces to achieve comparable release profiles. Medical device OEMs in Minnesota and Massachusetts are qualifying these alternatives ahead of anticipated state enforcement actions.
Buyer consolidation among multinational label converters is compressing supplier negotiation cycles and unbundling technical service from volume contracts. Large European converters now specify liner performance metrics rather than substrate grades, shifting qualification burden upstream to paper mills. This pattern concentrates most visibly in Germany, where Düsseldorf and Frankfurt-based converters are reducing their qualified supplier panels by forty to sixty percent.
Paper Release Liners Market Segmentation
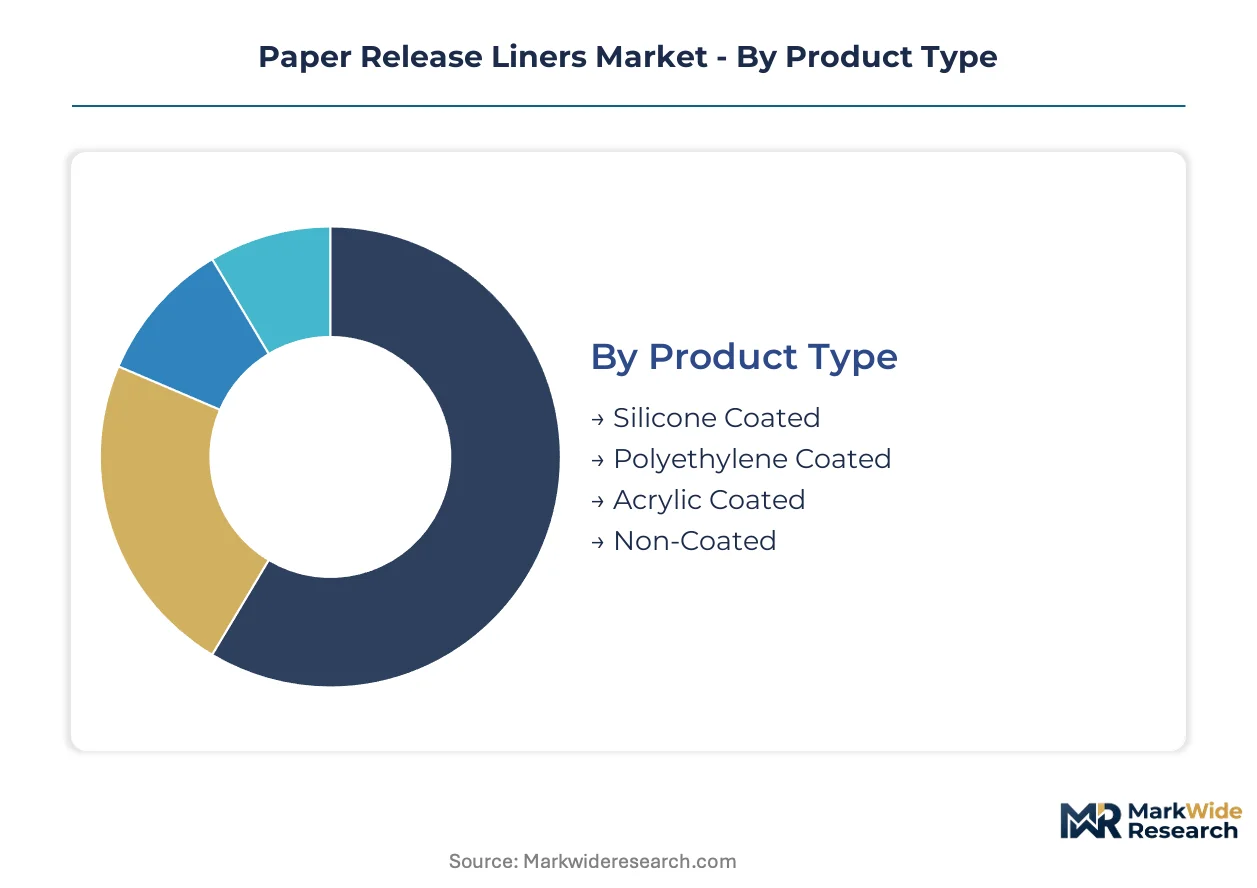
Paper release liner segmentation tracks divergent supply economics across coating chemistries and end-use specifications. Substrate suppliers configure coating lines around application-specific thermal, biocompatibility, and release force requirements that fragment procurement patterns.
Product Type:
Coating chemistry concentration determines margin structure, with silicone formulations commanding premium positioning due to raw material sourcing constraints and curing infrastructure requirements.
- Silicone Coated:Solvent-based and emulsion silicone systems deliver thermal stability between 150°C and 200°C for automotive battery module tapes and flexible circuit bonding. Japanese and South Korean electronics manufacturers specify these grades for high-temperature assembly applications where release consistency protects adhesive integrity.
- Acrylic Coated:Water-based acrylic release coatings achieve hypoallergenic profiles for transdermal drug delivery patches and diagnostic assemblies. German medical device manufacturers along the Rhine corridor are scaling procurement of these liners to meet ISO 13485 qualification pathways for wound care adhesives.
- Polyethylene Coated:Extruded PE films serve cost-driven industrial masking and general furniture protection where peel force precision is secondary to throughput efficiency.
- Non-Coated:Uncoated glassine and kraft substrates occupy mature segments with minimal value-add processing, primarily serving short-cycle protective applications.
Silicone coated liners absorb the bulk of installed capacity; acrylic coated variants are expanding most quickly.
Application:
Application segmentation reflects divergent qualification intensity, with medical and electronics channels imposing multi-year certification cycles that commodity labeling bypasses.
- Labeling:Pressure-sensitive label stock consumes the highest liner volumes, with inkjet-compatible porous substrates capturing share from thermal transfer grades in e-commerce logistics. European converters in Germany are unbundling technical service from volume contracts and specifying performance metrics rather than substrate grades.
- Medical Devices:Adhesive-backed wound care, diagnostic assemblies, and transdermal patches demand biocompatible release profiles under FDA 21 CFR substrate standards. REACH chemical disclosure mandates and evolving PFAS restrictions are compressing the qualified supplier base for these applications.
- Tapes:Industrial bonding and automotive assembly tapes specify silicone-coated liners for thermal stability during high-temperature curing cycles.
- Furniture:Surface protection during manufacturing and shipping represents a mature, price-sensitive segment with minimal coating specification differentiation.
Labeling channels anchor volume throughput; medical device applications command the steepest expansion trajectory.
End User:
End-user segmentation tracks regulatory exposure, with healthcare and food-contact segments facing tightening chemical disclosure and recyclability mandates.
- Healthcare:Medical device OEMs qualify liners under ISO 13485 quality systems with eighteen to twenty-four month certification timelines. CDSCO medical device rules and India's PLI scheme are attracting coating operations near Ahmedabad and Chennai diagnostic clusters.
- Electronics:Flexible circuit manufacturers in Japan specify water-based silicone emulsion coatings for lower-temperature curing and reduced volatile organic compound emissions.
- Food & Beverage:Compostable liner substrates certified under emerging EN 13432 standards command procurement preference from multinational brands navigating EU Green Deal circular mandates.
- Automotive:Battery module assembly tapes specify high-temperature silicone-coated liners for electric vehicle production lines in South Korea and Japan.
Healthcare end users concentrate qualification-driven value; electronics segments are climbing the fastest.
Distribution Channel:
Channel structure reflects customer scale fragmentation, with large converters consolidating procurement toward direct mill relationships while mid-tier buyers rely on distributor technical support.
- Direct Sales:Vertically integrated paper mills with in-house coating capabilities serve multinational label converters and medical device OEMs through dedicated account management. German converters in Düsseldorf and Frankfurt are reducing qualified supplier panels by forty to sixty percent, concentrating procurement toward direct mill relationships.
- Distributors:Regional stocking distributors provide technical service and smaller order fulfillment for mid-tier converting operations lacking solvent-based silicone application expertise.
- Wholesalers:Bulk volume channels serve commodity furniture and industrial masking segments with minimal specification differentiation.
- Online Retail:Digital procurement platforms capture niche and emergency replenishment orders from small converters and specialty adhesive manufacturers.
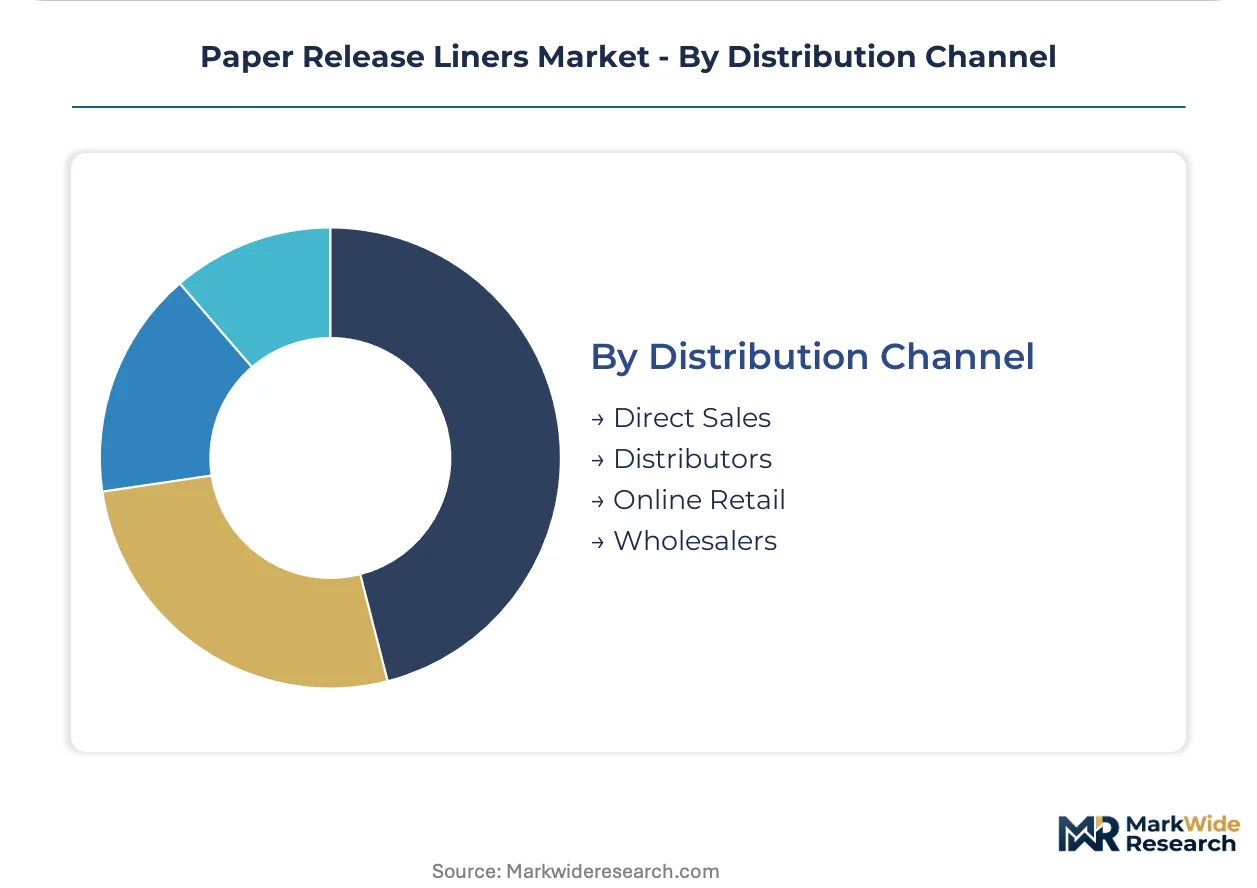
Direct sales channels capture the majority of premium-grade volume; distributor relationships are gaining share fastest among mid-tier converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Rhine corridor anchors paper release liner procurement, with label converters and medical supply chains clustering around Frankfurt and Düsseldorf to access qualified silicone coating capacity.
Germany
REACH chemical disclosure mandates from ECHA are accelerating substrate recyclability investments among glassine producers. The country's national chemical regulator enforces silicone emulsion registration requirements that compress qualification timelines. Frankfurt-based converters are reducing qualified supplier panels by forty to sixty percent, concentrating procurement toward vertically integrated paper mills.
United States
FDA 21 CFR substrate biocompatibility standards are shaping medical-grade liner qualification pathways for wound care adhesive manufacturers. EPA state-level PFAS restrictions are forcing fluorochemical-free release coating development across Minnesota and Massachusetts medical device clusters. Minneapolis and Boston OEMs are qualifying plant-derived wax alternatives ahead of anticipated enforcement actions.
Japan
Automotive OEMs specify high-temperature silicone-coated liners for battery module assembly tapes in electric vehicle production. METI industrial standards govern solvent-based versus emulsion silicone curing processes. Osaka-Kobe corridor coating operations supply flexible circuit manufacturers adopting water-based emulsion systems for reduced volatile organic compound emissions.
India
CDSCO medical device rules and PLI scheme incentives are attracting liner converters to establish coating operations near diagnostic manufacturing clusters. The national pharmaceutical regulator mandates quality system alignment for adhesive-backed wound care imports. Ahmedabad and Chennai host emerging converter operations serving localized medical device supply chains.
South Korea
Electronics manufacturers specify thermal stability requirements between 150°C and 200°C for automotive battery bonding applications. MFDS medical device standards influence acrylic-coated liner adoption for transdermal drug delivery patches. Seoul-Incheon industrial belt converters supply both domestic electronics OEMs and export markets with precision-coated substrates.
Paper Release Liners Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating chemistry specialization and qualification intensity. The supplier base concentrates around vertically integrated paper mills with in-house silicone application capabilities and independent converters dependent on toll coating relationships. Three archetypes dominate: Asian manufacturing scale leaders, European pulp-to-liner integrated producers, and specialty medical-grade qualification specialists. Consolidation through backward integration into pulp supply and forward integration into coating technology licensing represents the dominant competitive dynamic.
Within the integrated pulp-to-liner tier, Sappi Limited and Mondi Group exemplify substrate engineering capabilities that differentiate offerings in regulated medical and food-contact segments. LINTEC Corporation anchors the Asian manufacturing scale archetype, representing high-precision electronics application specialization. These three entities occupy positions across divergent supply economics, with premium silicone-coated grades commanding sustained margin premiums while commodity polyethylene-coated volumes compete on throughput efficiency.
| Leading Market Players |
|---|
| LINTEC Corporation |
| Loparex International B.V. |
| Sappi Limited |
| UPM Raflatac |
| Ahlstrom-Munksjö |
| 3M Company |
| Mondi Group |
| Stora Enso Oyj |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Northern bleached softwood pulp futures transmit volatility through glassine and supercalendered kraft substrate margins, compressing unintegrated converter profitability while vertically integrated paper mills capture pricing power through captive supply of release-coated liners.
Pricing Analysis
Throughput efficiency anchors pricing for polyethylene-coated commodity grades, while silicone-coated variants command value-based premiums tied to thermal stability performance in automotive battery module assembly. Price differentiation separates ISO 13485-certified medical-grade liners from industrial masking grades, with FDA 21 CFR substrate qualification tiers adding further stratification. Cost compression in commodity segments is intensifying because pulp cost pass-through limitations expose independent converters to margin erosion. Mid-tier label converters exhibit highest price sensitivity, whereas medical device OEMs prioritize qualification continuity over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle multinational converter and medical device manufacturer demand, while regional distributors serve mid-tier operations lacking in-house coating capabilities. Geographic supply concentration centers on Germany's Rhine corridor, Japan's Osaka-Kobe industrial belt, and India's emerging Ahmedabad-Chennai diagnostic clusters. Raw material dependencies draw from Jiangsu province silicone emulsion production, northern European pulp supply, and South Korean electronics-grade substrate imports. Single-source vulnerability in Asia-Pacific silicone chemistries creates supply chain risk for European and North American liner coaters. Distribution runs through vertically integrated paper mills with toll-coating relationships filling capacity gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper release liner competition is consolidating around backward integration into pulp supply and forward integration into coating technology licensing, with qualification intensity determining which players capture medical-grade margin premiums.
For Market Incumbents: Anticipate PFAS-free coating substitution mandates by accelerating plant-derived wax and plasma-treated surface qualification ahead of EPA state-level enforcement. Secure silicone emulsion supply through captive production or long-term offtake agreements with Jiangsu province and Osaka-Kobe corridor producers to defend against raw material concentration risk.
For New Entrants and Emerging Players: The gap between premium silicone-coated medical grades and economy polyethylene-coated industrial masking creates entry space for mid-tier acrylic-coated variants serving India's localized diagnostic manufacturing. Target CDSCO-compliant coating operations near Ahmedabad and Chennai clusters, leveraging PLI scheme incentives to establish qualification pathways without eighteen-month ISO 13485 certification delays.
For Investors and Strategic Acquirers: ECHA REACH registration deadline acceleration is the leading indicator that vertically integrated European paper mills with in-house silicone emulsion capabilities will consolidate distressed independent converters. Long-term viability favors acquisition targets possessing EN 13432 compostable substrate certification and established medical device OEM relationships, with coating technician training infrastructure as the critical capability scarcity signal to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive glassine production insulates margin from northern bleached softwood futures volatility. |
| PFAS-Free Coating Qualification | Plant-derived wax alternatives secure FDA 21 CFR continuity ahead of EPA state restrictions. |
| India Coating Facility Establishment | CDSCO alignment and PLI incentives capture localized diagnostic supply chain demand. |
| ISO 13485 Certification Investment | Eighteen-month qualification cycles lock medical device OEM relationships against mid-tier competition. |
| Water-Based Silicone Emulsion Adoption | Lower-temperature curing reduces VOC emissions for Japan and South Korea electronics manufacturers. |
Research Methodology
Trade flow databases, ECHA REACH registration filings, and FDA 21 CFR substrate guidance documents formed the secondary backbone, supplemented by primary interviews with label converter procurement directors, medical device OEM supply chain managers, silicone emulsion coating line engineers, and paper mill technical sales leads. Bottom-up volume estimates from coating line capacity utilization and top-down value triangulation against pulp-to-liner margin structures were cross-validated.
Historical trendline analysis of silicone emulsion pricing, glassine substrate trade volumes, and medical device adhesive import patterns established baseline trajectories across the analysis window. Segmentation modeling incorporated coating chemistry tier, end-use qualification intensity, geographic regulatory cluster, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements.
Inputs from ECHA, FDA, and CDSCO regulatory databases were available through the study window; gaps in real-time coating line utilization data from private paper mills introduce uncertainty bands around near-term supply estimates. Forecasts reflect assumptions regarding PFAS substitution timelines and India PLI scheme implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market