
 Machine Glazed Kraft Paper Market | 2026-2036
Machine Glazed Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Glazed Kraft Paper Market Outlook
The EU Green Deal is repositioning machine glazed kraft paper toward certified biodegradable packaging across European food retail. Mondi Group leverages integrated pulp-to-paper assets to secure fiber traceability for brand owners. Stora Enso anchors its competitive stance through sustained R&D into barrier-coated kraft grades that replace multilayer plastic films. Smurfit Kappa Group dominates corrugated-to-paperboard integration, extending its reach into specialty MG kraft for premium consumer goods.
Machine glazed kraft paper is an unbleached or semi-bleached sulfate pulp sheet calendered on one side to achieve a smooth, glossy surface with typical grammage ranging from 30 to 80 gsm, engineered for printability, heat sealability, and grease resistance in flexible packaging and laminations. Brown Kraft occupies the volume core in industrial wrapping and shipping sacks where cost efficiency outweighs aesthetic demands, while Specialty Kraft captures margin pools in confectionery twist-wrap and pharmaceutical overwrap where barrier performance commands premium positioning. Food Packaging leads application demand as quick-service chains and grocery private labels convert from plastic to fiber-based primary wraps.
EMA food contact material regulations, EU REACH chemical safety standards, and FSC chain-of-custody certification collectively govern substrate approval, migration limits, and forest sourcing claims across European supply chains. These frameworks elevate compliance costs for non-integrated converters while creating market access advantages for producers with certified fiber streams and in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility schemes and single-use plastic directive expansions to anticipate which packaging formats will face substitution mandates next.
Market Dynamics
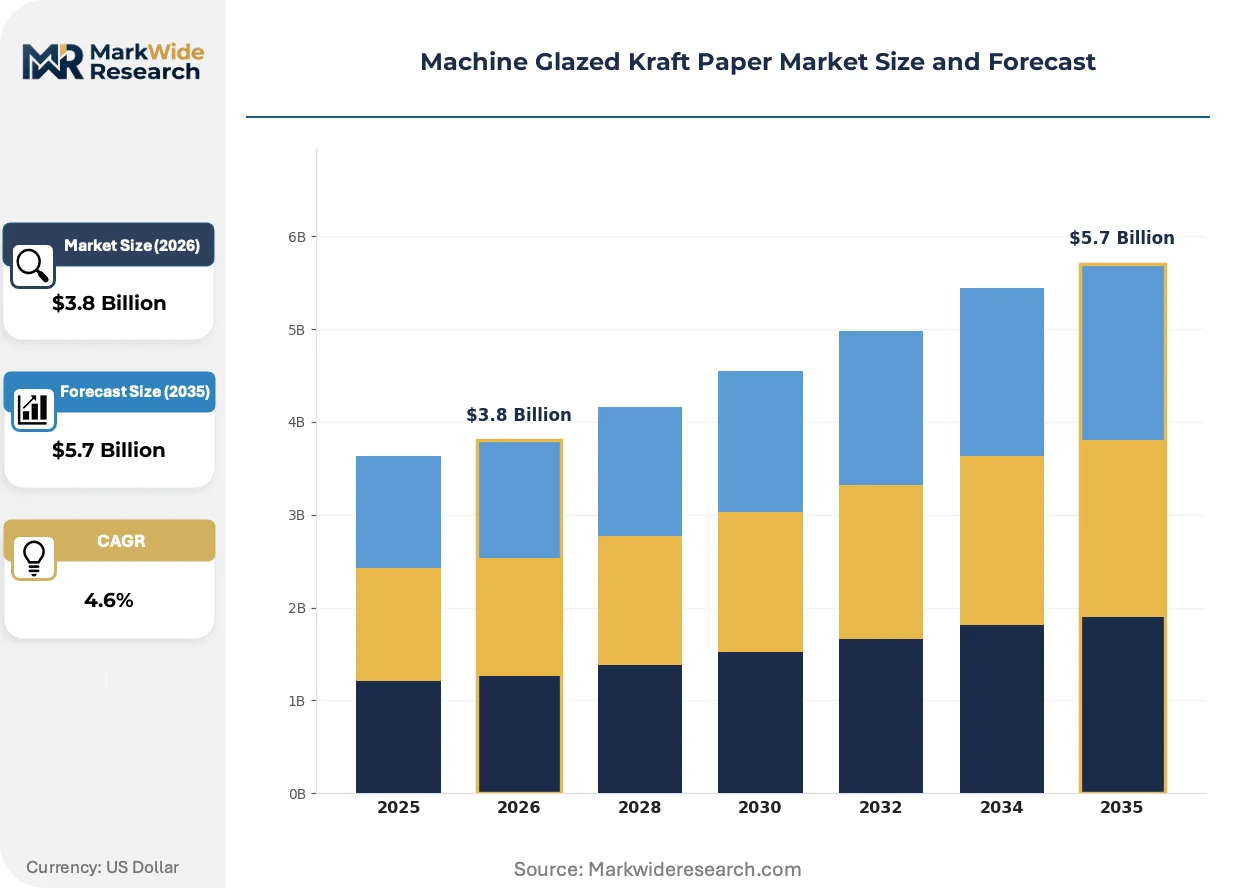
EU REACH chemical migration limits and the EU Green Deal are compressing substrate approval timelines while accelerating food retail conversion from plastic to fiber-based primary wraps. Integrated producers with captive pulp supplies and in-house testing laboratories capture market access advantages as compliance costs rise for non-integrated converters.
Growth Catalysts
- EU Green Deal packaging mandates:Certified biodegradable packaging requirements are forcing quick-service chains and grocery private labels to eliminate plastic wraps, redirecting volume toward machine glazed kraft paper with grease-resistant barrier coatings.
- Food contact material regulations:EMA migration limit standards are elevating substrate specifications for confectionery and bakery primary wraps, disqualifying lower-grade alternatives and concentrating demand on tested MG kraft grades.
- Germany's confectionery cluster:Major bakery and chocolate chains source grease-resistant MG kraft for twist-wrap applications, creating a concentrated demand anchor that pulls regional supply chain investment.
Market Restraints
- Pulp cost volatility:Unbleached sulfate pulp prices fluctuate with Nordic softwood supply cycles and energy costs, compressing margins for non-integrated converters without backward integration into fiber production.
- Barrier performance gaps:Uncoated MG kraft cannot match multilayer plastic films for moisture and oxygen transmission in extended shelf-life applications, limiting penetration into premium pharmaceutical overwrap segments.
- REACH compliance friction:Chemical safety testing and documentation requirements for food contact substrates extend product development cycles by 8-14 months for converters lacking in-house analytical capabilities.
Strategic Opportunities
- Barrier-coated kraft R&D convergence:Water-based coatings and bio-derived barrier layers are opening pharmaceutical and high-moisture food segments previously closed to fiber-based substrates.
- Extended producer responsibility schemes:Pending EU packaging waste directive expansions will mandate fiber-based alternatives in formats currently exempt, pre-positioning compliant suppliers for volume step-ups.
- Quick-service chain conversion:Burger and sandwich chains in France and Italy are piloting MG kraft primary wraps for hot food items, creating a new application vector beyond ambient confectionery.
Industry Challenges
- FSC chain-of-custody certification timelines:Brand owners now require documented fiber traceability from forest to finished reel, forcing converters to requalify supplier bases and rebuild inventory systems.
- Heat sealability engineering gaps:MG kraft's single-sided glaze creates asymmetric sealing behavior that frustrates automated packaging line integration, demanding custom jaw design and operator retraining.
- Legacy plastic film line conversion:Converters must retool forming and sealing equipment originally engineered for polypropylene and polyethylene to handle fiber-based substrates with different elongation and thermal properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Glazed Kraft Paper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Kraft, White Kraft, Specialty Kraft, Coated Kraft End User: Packaging Industry, Printing Industry, Food Industry, Textile Industry Application: Food Packaging, Durable Packaging, Decorative Applications, Industrial Use Grade: Standard Grade, High Strength Grade, Recycled Grade, Premium Grade |
| Companies Covered | Mondi Group, Stora Enso, International Paper, WestRock Company, Smurfit Kappa Group, Nippon Paper Industries, Sappi Limited, BillerudKorsnäs, Heinzel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Glazed Kraft Paper Market Strategic Shifts
Water-based barrier coatings and bio-derived polymers are rewriting the performance ceiling for unbleached kraft in applications previously reserved for plastic laminates. Three developments are compressing development cycles and reshaping competitive positioning.
Nano-fibrillated cellulose barrier layers are rewriting the moisture transmission performance of machine glazed kraft paper. Pharmaceutical overwrap manufacturers in Switzerland and Germany are qualifying these grades for blister pack backing applications. The technology is compressing the addressable market gap between fiber substrates and aluminum-plastic laminates.
EU F-Gas Regulation phase-down schedules are accelerating heat-seal adhesive chemistry shifts in MG kraft converting operations. Solvent-based systems face substitution mandates, pushing waterborne and hot-melt alternatives that demand modified calendering parameters. Confectionery twist-wrap producers in Belgium and the Netherlands are requalifying sealing jaw configurations to accommodate these adhesive transitions.
Private label procurement consolidation is compressing supplier qualification cycles across European grocery retail. Centralized packaging buying for discount and premium banners is displacing regional converter relationships with pan-European supply agreements. Germany's REWE and EDEKA sourcing structures exemplify this concentration, favoring MG kraft producers with multi-site certification and continent-wide logistics networks.
Machine Glazed Kraft Paper Market Segmentation
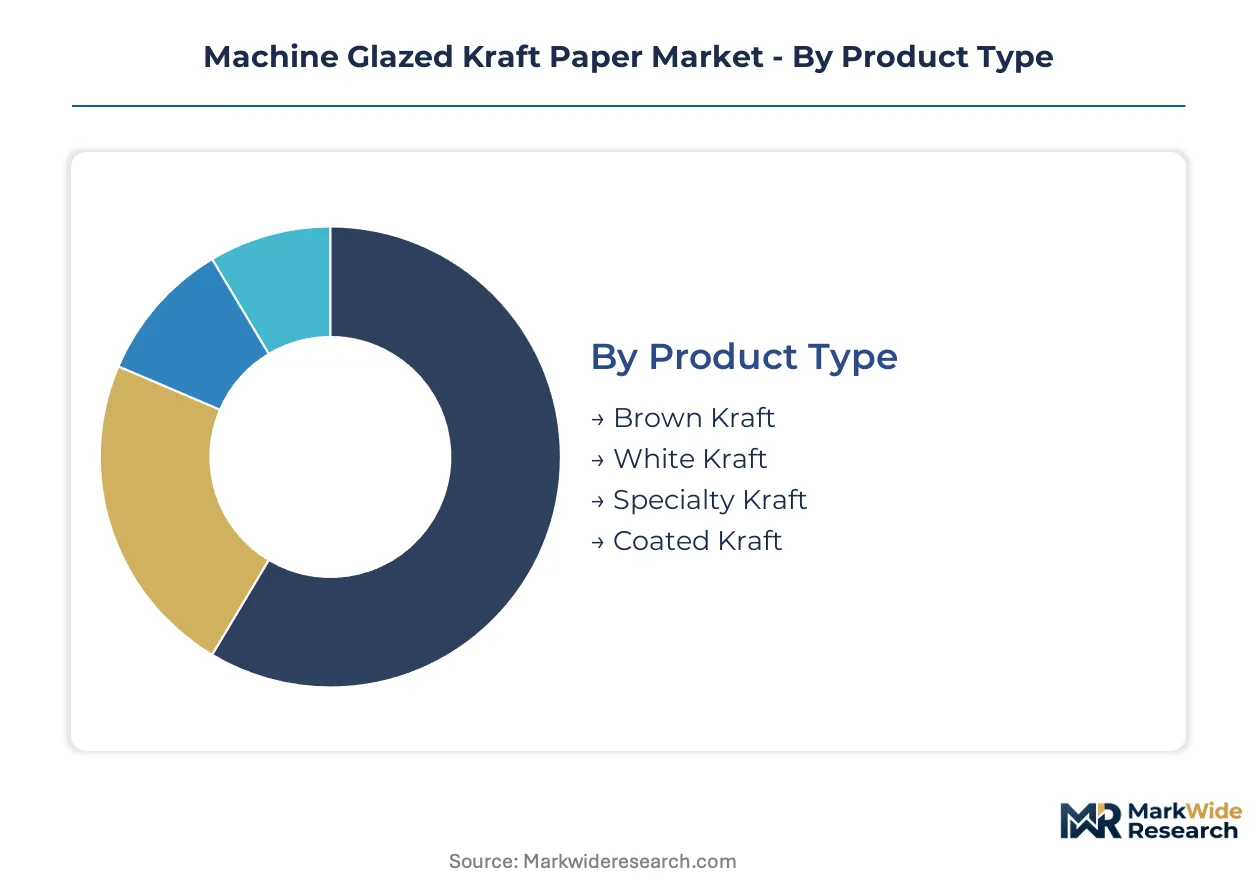
Machine glazed kraft paper segments diverge sharply between commodity-grade industrial wraps and precision-engineered food contact substrates. Understanding where value concentrates across product tiers, end-use verticals, and performance grades determines supplier positioning and capital allocation priorities.
Product Type:
Brown Kraft and White Kraft dominate standalone applications where substrate specifications remain standardized, while Specialty Kraft and Coated Kraft embed into complex multi-layer systems demanding barrier engineering.
- Brown Kraft:Unbleached sulfate pulp sheet with natural lignin content retains high tear strength and cost efficiency for shipping sacks and industrial wrapping. Demand anchors in German logistics networks and Nordic export packaging where EUDR deforestation compliance documentation now accompanies every reel.
- Specialty Kraft:Semi-bleached or pigment-coated grades engineered for grease resistance and heat sealability in confectionery twist-wrap and pharmaceutical overwrap. Swiss and Belgian chocolate manufacturers source these grades under EMA food contact migration limits that disqualify standard kraft alternatives.
- White Kraft:Bleached pulp achieves superior print contrast for retail-facing flexible packaging and label laminations. French quick-service chains specify white kraft for branded primary wraps where visual shelf impact overrides substrate cost.
- Coated Kraft:Polymer or bio-derived barrier layers extend moisture and oxygen protection into premium food and medical segments. Water-based coating chemistry advances are compressing qualification timelines for aluminum-plastic laminate replacement.
Volume placements concentrate in Brown Kraft; the faster expansion belongs to Specialty Kraft.
End User:
Cost tier stratification separates high-volume packaging converters from precision-oriented food and textile specialists where specification tolerance tightens.
- Packaging Industry:Corrugated box plants and flexible packaging converters consume MG kraft for linerboard facing, void fill, and laminated structures. German and Dutch integrated packaging groups backward into captive kraft production to secure fiber traceability under FSC chain-of-custody mandates.
- Food Industry:Bakeries, confectioners, and ready-meal processors specify grease-resistant and heat-sealable grades for direct food contact. EU single-use plastic directive expansions are redirecting volumes from polypropylene wraps toward fiber-based primary packaging.
- Printing Industry:Label stock and commercial print laminators demand calendered smoothness and dimensional stability for high-speed press runs. Italian and Spanish specialty printers source narrow reels for premium wine and cosmetics label applications.
- Textile Industry:Apparel manufacturers use MG kraft for pattern cutting, interleaving, and protective wrapping during garment finishing. Portuguese and Romanian textile clusters specify anti-corrosive treated grades for metallic button and zipper protection.
Margin capture stratifies across Food Industry premium specifications; Packaging Industry volume scales fastest.
Application:
Application maturity curves separate established industrial uses from emerging food service conversions where regulatory pressure reshapes substrate selection.
- Food Packaging:Primary wraps for bakery, confectionery, and quick-service items requiring grease resistance and heat sealability. French burger chains pilot MG kraft for hot food items under pending extended producer responsibility scheme expansions.
- Durable Packaging:Multi-wall shipping sacks, cement bags, and agricultural product containers where puncture resistance and moisture protection dominate. Nordic construction material distributors specify high-grammage grades for outdoor storage resilience.
- Industrial Use:Void fill, dunnage, and protective interleaving in manufacturing supply chains. Automotive component suppliers in Czech Republic and Poland source recycled-content grades for ESG reporting compliance.
- Decorative Applications:Gift wrap, craft paper, and premium retail bag stock where surface aesthetics and printability command positioning. Austrian and German stationery brands specify embossed and metallic-finish specialty grades.
Revenue concentration sits with Food Packaging; Durable Packaging climbs fastest on infrastructure investment cycles.
Grade:
Performance tier differentiation aligns with customer certification requirements and supply chain integration depth.
- Standard Grade:Base unbleached kraft meeting minimum burst and tear specifications for non-critical industrial wrapping. Commodity converters in Eastern Europe source these grades on spot pricing without long-term fiber traceability contracts.
- Premium Grade:Tight caliper tolerance, superior formation, and enhanced surface smoothness for high-resolution printing and precision converting. Swiss pharmaceutical overwrap manufacturers qualify these grades under EMA Annex I food contact substance approvals.
- High Strength Grade:Elevated burst index and tensile energy absorption for heavy-duty shipping sacks and demanding logistics applications. German cement and chemical producers specify these grades for automated filling line reliability.
- Recycled Grade:Post-consumer fiber content meeting FSC Recycled and EU Green Deal circular economy procurement criteria. Dutch and Belgian retail private labels mandate minimum recycled content for secondary packaging applications.
Shipment volumes cluster in Standard Grade; Premium Grade gains share fastest on pharmaceutical and luxury food qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Nordic and Central European pulp corridors while consumption concentrates in German, French, and Benelux food manufacturing belts. This geographic split shapes freight economics and certification requirements across supply chains.
Germany
Confectionery and bakery chains in Cologne and Hamburg source grease-resistant MG kraft for twist-wrap applications under tightened EMA food contact migration limits. The country's packaging waste act amendments are accelerating plastic-to-fiber conversions in quick-service retail. Bavarian integrated paper groups backward into certified fiber streams to secure FSC chain-of-custody documentation for export shipments.
France
Burger and sandwich chains in Paris and Lyon pilot MG kraft primary wraps for hot food items as extended producer responsibility schemes expand. ANSM pharmaceutical packaging standards are elevating barrier performance requirements for overwrap applications. The Île-de-France logistics corridor channels coated kraft grades toward North African export markets.
Netherlands
Rotterdam and Amsterdam serve as distribution hubs for MG kraft entering UK and Scandinavian markets post-Brexit customs realignment. Dutch retail private labels mandate minimum recycled content under EU Green Deal circular economy procurement criteria. Belgian converters in Antwerp qualify water-based barrier coatings for confectionery twist-wrap under REACH chemical safety documentation.
Sweden
Nordic softwood pulp supply cycles in Stockholm and Gothenburg determine raw material cost baselines for European MG kraft production. The country's environmental protection agency enforces stringent effluent standards on sulfate pulp mills. Swedish integrated producers leverage captive fiber assets to compress lead times for pharmaceutical overwrap qualifications.
Italy
Specialty printers in Milan and Bologna source narrow reels of white kraft for premium wine and cosmetics label applications. The country's national pharmaceutical regulator aligns with EMA Annex I substance approvals for blister pack backing materials. Emilia-Romagna packaging clusters retool forming equipment originally engineered for polypropylene to handle fiber-based substrates.
Machine Glazed Kraft Paper Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-paper groups with captive fiber supplies and in-house testing laboratories. Non-integrated converters face margin compression from rising compliance costs and raw material volatility. Three archetypes dominate: Nordic integrated producers with backward fiber control, Central European specialty converters with barrier-coating expertise, and North American volume players with continent-wide logistics networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for EU packaging waste directive expansions.
Within the integrated producer tier, Mondi Group exemplifies the archetype of fiber-traceable supply chains, while Stora Enso occupies a position emphasizing barrier-coated grade development. Smurfit Kappa Group represents corrugated-to-specialty extension strategies. These three anchors illustrate how certification depth and coating capabilities are separating premium positioning from commodity volume plays.
| Leading Market Players |
|---|
| Mondi Group |
| Stora Enso |
| International Paper |
| WestRock Company |
| Smurfit Kappa Group |
| Nippon Paper Industries |
| Sappi Limited |
| BillerudKorsnäs |
| Heinzel Group |
| Others |
Value Chain & Pricing Dynamics
Water-based barrier coating adoption is compressing cost economics for converters while concentrating supply power among integrated Nordic producers with captive coating development labs. This technology transition simultaneously elevates qualification barriers for non-integrated players and tightens pricing leverage for backward-integrated groups.
Pricing Analysis
Margin tightening in Specialty Kraft reflects EMA food contact migration testing costs and FSC chain-of-custody certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier-coated reels from industrial Brown Kraft volumes. Price differentiation hinges on certification depth and barrier performance tier. Pricing pressure stems from pulp cost volatility and REACH compliance documentation burdens. Packaging converters exhibit highest price sensitivity; pharmaceutical overwrap manufacturers accept premium positioning for tested grades.
Supply Chain Analysis
Single-source vulnerability sits with Nordic softwood pulp supply cycles in Sweden and Finland. Raw material dependencies draw from unbleached sulfate pulp, water-based coating polymers, and heat-seal adhesive chemistries. Supply chain risk centers on energy cost volatility at sulfate mills. Distribution runs through Rotterdam and Hamburg port hubs into German confectionery clusters and French quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained. Certified fiber traceability bottlenecks prop pricing for integrated producers with FSC chain-of-custody documentation.
For Market Incumbents: Cement backward integration into barrier coating R&D to defend against multilayer plastic film substitution threats. Expand captive pulp assets in Nordic corridors to secure fiber traceability leverage. Prioritize in-house EMA testing laboratory accreditation to compress qualification timelines for pharmaceutical overwrap customers. For New Entrants and Emerging Players: Begin with white kraft narrow reels for Italian and Spanish premium label printers where specification tolerance tightens but volume minimums remain accessible. Target quick-service chain pilot programs in France and Italy for hot food wrap applications. Lead with water-based coating partnerships rather than capital-intensive mill investments. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated pulp-to-paper groups with pharmaceutical qualification track records. Long-term viability favors producers with captive fiber supplies and barrier-coated grade portfolios. Watch for EU packaging waste directive expansion announcements as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Investment | Water-based and bio-derived layers open pharmaceutical segments previously closed to fiber substrates. |
| Backward Integration into Pulp | Captive Nordic softwood supply secures FSC traceability documentation for EU Green Deal compliance. |
| EMA Testing Laboratory Accreditation | In-house migration testing compresses 8-14 month qualification cycles for food contact grades. |
| Quick-Service Chain Pilot Programs | French and Italian burger chains pilot MG kraft for hot food wraps under extended producer responsibility schemes. |
| Multi-Site Certification Expansion | Pan-European FSC chain-of-custody documentation satisfies REWE and EDEKA centralized procurement structures. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with paper mill technical directors, flexible packaging procurement leads, confectionery quality managers, and pharmaceutical packaging engineers combined with secondary validation from EMA substance approvals, FSC certification databases, and EU REACH chemical safety documentation. Bottom-up volume modeling across grade tiers and end-use segments triangulated against top-down pulp consumption estimates.
Segment-level granularity modeled product type, end-user industry, application format, and performance grade across the projection horizon. CAGRs derived from trend extrapolation of plastic-to-fiber substitution rates, regulatory mandate implementation timelines, and barrier coating technology adoption curves. Forecast inputs incorporated EU single-use plastic directive expansion scenarios and extended producer responsibility scheme rollout patterns.
Underlying measurement precision varies by segment; pharmaceutical overwrap and food packaging carry tighter precision than industrial decorative applications. Forecasts reflect assumptions on regulatory enforcement intensity and coating technology qualification timelines. Pulp cost volatility, REACH documentation burden shifts, and F-Gas Regulation adhesive chemistry mandates represent primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
GCC Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market