
 GCC Paper Cup Market | 2026-2036
GCC Paper Cup Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Paper Cup Market Insights
Foodservice distribution across the Gulf is rewriting procurement relationships between packaging converters and national hospitality groups. Hotpack Global leverages integrated manufacturing facilities across the UAE to sustain same-day delivery commitments to hotel chains. Huhtamaki OYJ anchors its regional position through specialized beverage cup lines designed for Middle Eastern coffee consumption patterns. Golden Paper Cups Manufacturing LLC competes on proximity, operating production assets within Saudi Arabia's industrial zones to reduce cross-border freight exposure.
Paper cups are cylindrical liquid-holding containers fabricated from paperboard substrates laminated with polyethylene or polylactic acid barrier layers, typically featuring rolled rims and nested stacking geometry for foodservice dispensing. The primary commercial purpose centers on hygienic, portable beverage service without permanent dishware infrastructure. Double wall and insulated variants command premium positioning in the product type dimension, as Gulf consumers prioritize heat retention for specialty coffee and karak tea service. PLA coated material grades are gaining structural share against poly coated alternatives, driven by municipal procurement mandates in Dubai and Abu Dhabi that exclude conventional plastic linings from government-contracted food operations.
Saudi Food and Drug Authority standards govern food-contact material safety across the Kingdom, while UAE Ministry of Climate Change and Environment regulations enforce extended producer responsibility frameworks for disposable packaging. Dubai Municipality's technical guidelines specifically mandate compostability certifications for cups used in licensed outdoor events and food truck operations. Stakeholders must monitor how Bahrain and Oman adapt their national plastic reduction timelines, as harmonized Gulf-wide standards would reshape cross-border manufacturing economics and inventory pooling strategies.
Market Dynamics
Municipal plastic bans across Dubai and Abu Dhabi are compressing demand timelines for conventional poly-coated cups while accelerating converter investment in PLA barrier lines and compostable certification infrastructure.
Growth Catalysts
- Single-use plastic prohibitions:Dubai Municipality's technical guidelines for licensed outdoor events and food truck operations mandate compostable food-contact materials, eliminating conventional plastic-lined alternatives from government-contracted operations.
- Quick-service restaurant expansion:Saudi Arabia's QSR corridor linking Riyadh, Jeddah, and Dammam is driving systematic replacement of plastic serviceware with paper-based alternatives across national and international chain operations.
- PLA-coated barrier technology:Polylactic acid lamination advances are resolving heat-seal performance gaps for hot beverage applications, enabling functional parity with polyethylene barriers in specialty coffee and karak tea service.
Market Restraints
- Raw material cost volatility:Food-grade paperboard supply concentrates in Scandinavian and North American pulp mills, exposing GCC converters to freight cost swings and currency fluctuation risk on imported substrates.
- Composting infrastructure gaps:Industrial composting facility scarcity across Bahrain, Oman, and Kuwait limits end-of-life value realization for certified biodegradable cups, undermining premium pricing justification.
- Extended producer responsibility compliance:UAE Ministry of Climate Change and Environment frameworks impose collection and recycling obligations that increase operational overhead for smaller packaging converters without integrated waste management partnerships.
Strategic Opportunities
- Qatari hospitality procurement:FIFA World Cup legacy infrastructure and year-round event tourism are creating demand for certified compostable serviceware in stadium concessions, hotel catering, and exhibition centers.
- Extended shelf-life dairy packaging:Aseptic paper cup formats for laban and flavored milk products represent an emerging application beyond beverage service, leveraging existing converter extrusion and forming capabilities.
- Harmonized Gulf standards:Potential alignment of Bahrain and Oman plastic reduction timelines with UAE and Saudi frameworks would enable cross-border inventory pooling and centralized manufacturing economics for regional suppliers.
Industry Challenges
- Compostability certification timelines:Obtaining Dubai Municipality-recognized compostability credentials for PLA-coated cup lines requires 12-18 month testing cycles, delaying product commercialization and locking out opportunistic tenders.
- Barrier technology integration:Retrofitting existing polyethylene extrusion lines for PLA or aqueous coating application demands capital expenditure and process engineering expertise that mid-scale converters struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Paper Cup Market |
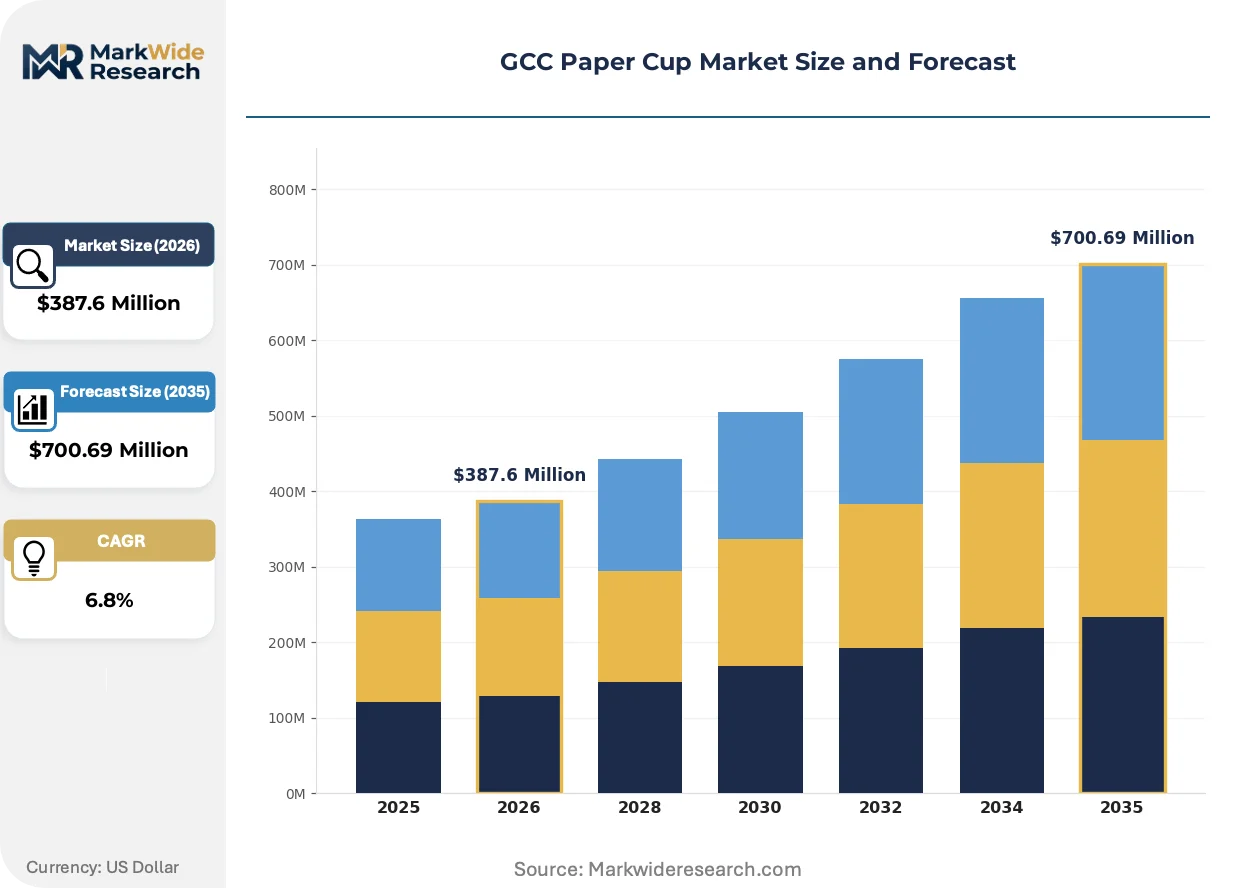
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Ripple Wall End User: Cafes, Restaurants, Events, Food Trucks Material: Recycled Paper, Virgin Paper, PLA Coated, Poly Coated Size: 8 oz, 12 oz, 16 oz, 20 oz |
| Companies Covered | Golden Paper Cups Manufacturing LLC, Hotpack Global, ENPI Group, Arkan Mfg Paper Cup Company, SAQR Pack, Huhtamaki OYJ, Maimoon Papers Industry LLC, Saham Group, Gulf East Paper & Plastic Industries LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Paper Cup Market Trends and Innovations
Barrier material chemistry and municipal procurement mandates are converging to restructure competitive positioning across GCC packaging converters, with certification speed and coating technology mastery replacing scale as the primary differentiation mechanism.
Water-based barrier coatings are collapsing the performance gap between conventional polyethylene linings and compostable alternatives for hot-fill applications. Specialty coffee chains across Dubai and Abu Dhabi are piloting these cups for Americano and flat white service, with heat retention metrics now matching double-wall poly-coated constructions. The technology is collapsing premium pricing power for imported European PLA-lined alternatives that previously commanded 40-60% markups in the Gulf market.
Dubai Municipality's technical guidelines for licensed outdoor events now explicitly exclude conventional plastic linings from government-contracted food operations. This regulatory architecture is forcing rapid certification investments among UAE-based converters seeking to maintain access to municipal tenders and festival catering contracts. Saudi Food and Drug Authority standards are following a similar trajectory, with draft food-contact material safety updates emphasizing biodegradability pathways for disposable serviceware.
Hotel chains and national hospitality groups are consolidating packaging procurement through integrated supply agreements with converters offering same-day delivery commitments. Hotpack Global's UAE manufacturing network and Golden Paper Cups' Saudi production assets are capturing volume through proximity-based service level guarantees rather than unit cost competition. This consolidation pattern is most visible in Dubai's hotel corridor, where procurement teams prioritize inventory flexibility and brand-consistent customization over per-unit savings.
GCC Paper Cup Market Segmentation
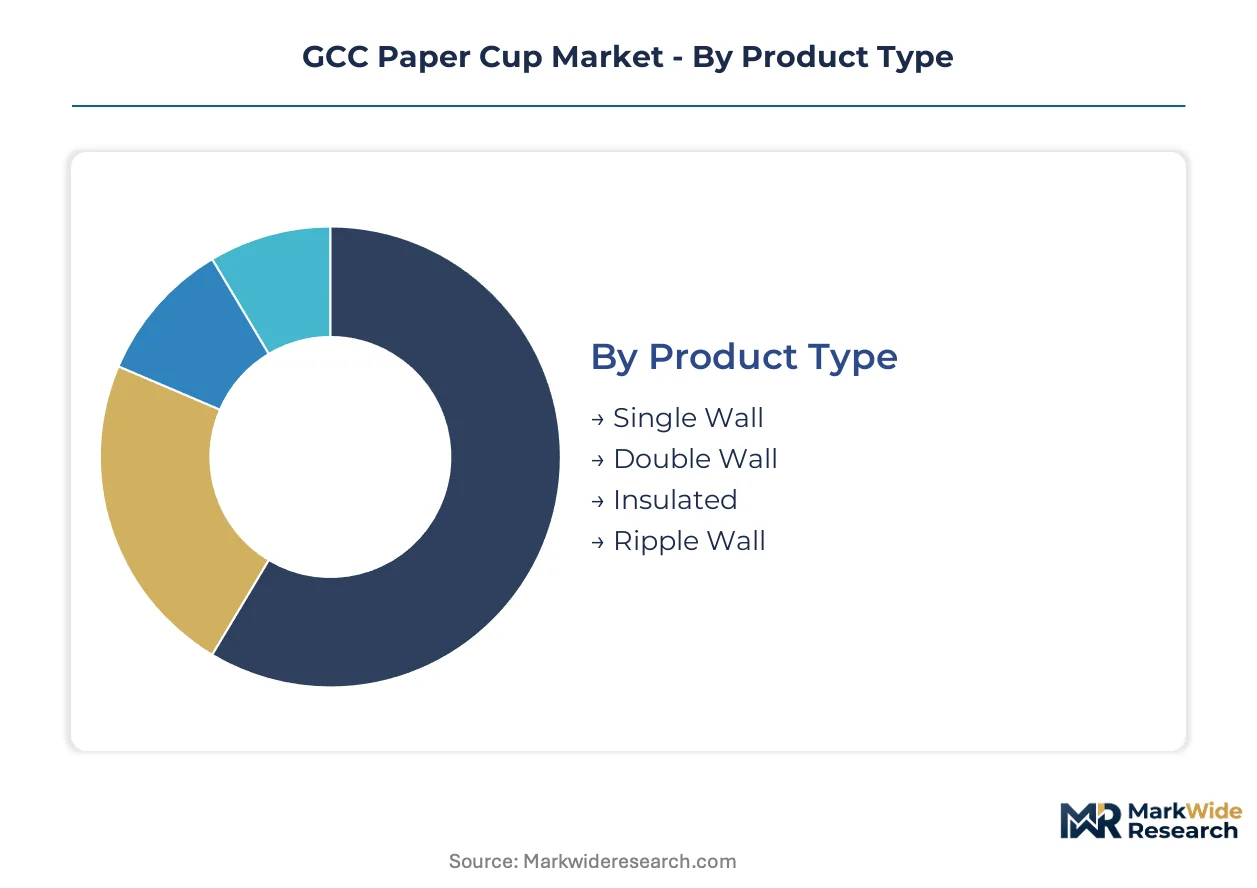
Paper cup procurement across the Gulf follows distinct velocity patterns by application and material specification. Understanding segment turnover rates enables converters to align inventory positioning with municipal certification deadlines and seasonal hospitality demand.
Product Type:
Single wall variants turn inventory fastest through high-volume QSR channels, while insulated formats sit longer in specialty coffee supply chains due to premium positioning and lower throughput.
- Single Wall:Lightweight single-ply construction with basic PE or PLA barrier lining. Saudi Arabia's QSR corridor linking Riyadh, Jeddah, and Dammam drives bulk procurement for karak tea and standard coffee service where cost minimization dominates.
- Double Wall:Dual-layer paperboard with trapped air insulation eliminating the need for cup sleeves. Dubai's specialty coffee chains prioritize these for Americano and flat white service, balancing heat retention with material efficiency against triple-wall alternatives.
- Insulated:Foam-integrated or advanced air-gap construction delivering maximum thermal performance for extended consumption periods.
- Ripple Wall:Textured outer layer providing grip friction and moderate insulation through corrugated geometry.
Single wall anchors the volume base while insulated formats gain share at the steepest rate.
End User:
Procurement scale and certification requirements diverge sharply across customer types, with institutional buyers imposing compostability mandates that casual vendors ignore.
- Cafes:Specialty coffee outlets across Dubai and Abu Dhabi specify PLA-coated or aqueous barrier cups for brand-aligned sustainability positioning, accepting 15-25% unit cost premiums for municipal compliance.
- Restaurants:Full-service and fast-casual dining operations in Saudi Arabia's hospitality clusters prioritize nested stacking efficiency and lid interoperability across multiple beverage formats.
- Events:Temporary foodservice operations face Dubai Municipality mandates for compostable serviceware at licensed outdoor gatherings.
- Food Trucks:Mobile vendors balance space constraints against durability requirements for transport and handling.
Restaurants dominate absolute procurement tonnage while events represent the most certification-sensitive growth channel.
Material:
Substrate selection determines regulatory compliance pathways and end-of-life economics across Gulf waste management infrastructures.
- Recycled Paper:Post-consumer fiber content ranging 50-100% with virgin pulp blending for food-contact safety. Dubai's government-contracted operations increasingly specify minimum recycled content thresholds alongside compostability certifications.
- PLA Coated:Polylactic acid barrier derived from corn starch or sugarcane providing compostable end-of-life pathways. SFDA draft standards and UAE Ministry of Climate Change frameworks are accelerating displacement of conventional polyethylene linings.
- Virgin Paper:Unbleached or bleached kraft pulp offering maximum fiber strength and printability for branded applications.
- Poly Coated:Conventional polyethylene extrusion lining facing phased exclusion from municipal tenders and outdoor event licensing.
Poly coated retains residual volume in price-sensitive segments while PLA coated climbs the fastest toward majority share.
Size:
Portion standardization follows international QSR formats with regional adaptation for traditional beverage service.
- 8 oz:Compact format for espresso-based drinks and children's portions. Saudi karak tea vendors favor this specification for single-serve pricing tiers.
- 12 oz:Standard specialty coffee capacity matching international chain formats. Dubai's independent cafes treat this as the default Americano and flat white vessel.
- 16 oz:Expanded capacity for iced beverages and extended consumption occasions.
- 20 oz:Maximum volume for shared servings and value-oriented QSR promotions.
12 oz specifications anchor procurement volumes while 8 oz formats expand most quickly through traditional beverage service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing leverage through captive pulp sourcing and integrated converter networks, while Bahrain and Oman absorb freight premiums on imported substrates that compress margin recovery for distributors serving price-sensitive QSR channels.
Saudi Arabia
Riyadh, Jeddah, and Dammam form the dominant QSR corridor where national and international chains are systematically replacing plastic serviceware with paper-based alternatives. SFDA standards govern food-contact material safety across the Kingdom, with draft updates emphasizing biodegradability pathways for disposable serviceware. Golden Paper Cups Manufacturing LLC operates production assets within Saudi industrial zones, reducing cross-border freight exposure and capturing volume through proximity-based service guarantees.
United Arab Emirates
Dubai's specialty coffee chains and Abu Dhabi's hotel hospitality clusters drive premium demand for PLA-coated and aqueous barrier cups with compostability certifications. Dubai Municipality's technical guidelines explicitly exclude conventional plastic linings from government-contracted food operations and licensed outdoor events. Hotpack Global leverages integrated manufacturing facilities across the UAE to sustain same-day delivery commitments to national hospitality groups and hotel chains.
Qatar
FIFA World Cup legacy infrastructure and year-round event tourism are creating concentrated demand for certified compostable serviceware in stadium concessions, hotel catering, and exhibition centers. The country's procurement frameworks increasingly specify compostability credentials for government-contracted hospitality operations. Doha's event corridor is emerging as a testing ground for aseptic paper cup formats beyond traditional beverage service.
Kuwait
Food truck operations and temporary outdoor foodservice are expanding rapidly, though industrial composting facility scarcity limits end-of-life value realization for certified biodegradable cups. Municipal regulations are tracking UAE frameworks with phased plastic reduction timelines under consideration. Kuwait City's hospitality cluster is prioritizing nested stacking efficiency and lid interoperability across multiple beverage formats for procurement standardization.
Bahrain
Cross-border manufacturing economics from Saudi Arabia and UAE suppliers dominate procurement, with local converters struggling to match freight-integrated pricing from regional scale players. The national plastic reduction timeline remains unaligned with UAE and Saudi frameworks, creating regulatory arbitrage opportunities. Manama's foodservice corridor is absorbing imported PLA-coated inventory while awaiting clarity on harmonized Gulf-wide standards that would reshape inventory pooling strategies.
GCC Paper Cup Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on barrier technology and substrate supply. The GCC converter base fragments across integrated multinational networks, regional scale players with captive manufacturing, and single-facility specialists serving local hospitality clusters. Three archetypes dominate: proximity-based logistics platforms, certification-integrated compliance specialists, and substrate-integrated cost leaders. Competitive intensity centers on municipal tender access and same-day delivery service level guarantees rather than unit price competition.
Among UAE-based integrated manufacturers, Hotpack Global exemplifies the logistics platform archetype through multi-facility networks enabling rapid fulfillment commitments. Finnish multinational Huhtamaki OYJ anchors the premium technology tier, representing specialized beverage cup design adapted to Middle Eastern consumption patterns. Saudi producer Golden Paper Cups Manufacturing LLC occupies the proximity-specialist position, leveraging in-Kingdom assets to reduce cross-border exposure and capture QSR corridor volume.
| Leading Market Players |
|---|
| Golden Paper Cups Manufacturing LLC |
| Hotpack Global |
| ENPI Group |
| Arkan Mfg Paper Cup Company |
| SAQR Pack |
| Huhtamaki OYJ |
| Maimoon Papers Industry LLC |
| Saham Group |
| Gulf East Paper & Plastic Industries LLC |
| Others |
Pricing and Supply Chain Analysis
The Jeddah-Dammam freight corridor compresses logistics costs for Saudi-based converters while amplifying price spreads between standard poly-coated inventory and certified PLA-lined alternatives. This corridor dynamic concentrates supply-side leverage among producers with in-Kingdom assets, enabling same-day delivery premiums that Dubai and Abu Dhabi buyers absorb for municipal compliance.
Pricing Analysis
The customization-premium spread separates configured-to-order branded cups from standard unprinted stock, with three-tier pricing structure across premium, standard, and economy levels dominating procurement frameworks. Price differentiation hinges on compostability certification grade and volume scale, with Dubai Municipality-mandated PLA coatings commanding substantial markups over conventional polyethylene barriers. Pricing pressure stems from Scandinavian and North American pulp mill freight volatility feeding into imported substrate costs. Quick-service restaurant chains exhibit highest price sensitivity, while hotel hospitality clusters prioritize service level guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock dependence draws from Scandinavian pulp mills, North American paperboard suppliers, and Asian PLA resin producers for barrier lamination. Food-grade paperboard concentrates in Sweden, Finland, and Canada, while polylactic acid barrier materials source primarily from Thailand and China. Raw material dependencies rest on bleached kraft pulp, extrusion-grade PLA pellets, and aqueous barrier coating chemicals. Single-source vulnerability runs through Scandinavian pulp supply contracted on quarterly pricing cycles. Distribution runs through converter-direct relationships with national hospitality groups and QSR procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as interoperability requirements between cup specifications and lid systems consolidate procurement around integrated suppliers. The emergence of harmonized Gulf-wide certification standards is accelerating this shift toward ecosystem-lock-in.
For Market Incumbents: Build certification-speed moats through pre-positioned Dubai Municipality compostability credentials before Bahrain and Oman align plastic reduction timelines. SFDA draft standards on biodegradability pathways threaten late movers with 12-18 month testing cycle lockouts. Incumbents should deepen backward integration into captive PLA extrusion capacity and secure long-term pulp offtake agreements to defend margin position against freight volatility. For New Entrants and Emerging Players: Establish a beachhead in Qatar's event tourism corridor where FIFA World Cup legacy infrastructure concentrates demand for certified compostable serviceware with limited local supply. The most penetrable segment sits in aseptic paper cup formats for laban and flavored milk beyond traditional beverage service. A go-to-market angle targeting stadium concession procurement with same-day Doha delivery commitments bypasses entrenched UAE logistics platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging parents seeking to divest non-core Gulf assets amid regional margin compression. Long-term viability favors converters with integrated manufacturing footprints across multiple emirates or Kingdom industrial zones, enabling cross-border inventory pooling if harmonized standards materialize. The signal to watch is Bahrain's national plastic reduction timeline announcement, which would trigger immediate certification investment spikes and consolidation pressure on single-facility operators.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Pre-Positioning | Secures Dubai Municipality tender access before regulatory deadlines eliminate poly-coated alternatives from licensed events. |
| Backward Integration into PLA Extrusion | Captures barrier technology margin and insulates converters from Asian resin price volatility. |
| Same-Day Delivery Network Expansion | Hotpack Global's multi-facility UAE footprint demonstrates proximity-based service level guarantees capture hospitality procurement consolidation. |
| Aseptic Format Diversification | Extends converter capabilities into extended shelf-life dairy packaging beyond commoditized beverage service. |
| Harmonized Standards Lobbying | Early engagement with Bahrain and Oman regulators positions incumbents to shape Gulf-wide certification reciprocity frameworks. |
Research Methodology
A standing panel of procurement directors at national hospitality groups, packaging converter operations managers, SFDA regulatory affairs specialists, and QSR supply chain executives provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from Saudi Food and Drug Authority draft standard filings, Dubai Municipality technical guideline releases, UAE Ministry of Climate Change and Environment framework documents, and customs trade data on paperboard imports. Bottom-up volume triangulation across product type, material specification, and end-user segments was cross-checked against top-down market sizing from pulp mill export disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeling spanning product type, barrier material chemistry, end-user procurement scale, and country-specific regulatory compliance tiers. CAGRs were derived from elasticity-adjusted demand projections incorporating QSR outlet expansion rates, municipal ban phase-in schedules, and PLA coating technology adoption curves. Industry-specific forecast inputs included karak tea consumption velocity patterns and specialty coffee outlet density metrics across Dubai and Riyadh corridors.
Sensitivities concentrate around Bahrain and Oman regulatory timeline announcements, Scandinavian pulp freight rate volatility, and industrial composting facility buildout delays that could undermine PLA-coated cup premium justification. Forecasts reflect documented assumptions on municipal enforcement consistency and hospitality procurement consolidation velocity. Cross-checking against UAE Ministry of Climate Change extended producer responsibility compliance filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market