
 Beverage Filter Paper Market | 2026-2036
Beverage Filter Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Filter Paper Market Insights
Plant-based fiber processing is fragmenting the traditional pulp supply base as manufacturers seek alternatives to conventional wood-derived inputs. Ahlstrom-Munksjö leverages its Nordic pulp integration to secure cost-advantaged raw material flows. Melitta Group anchors European retail distribution through decades of brand equity in drip brewing systems. Hario Co., Ltd differentiates via specialty-grade papers calibrated for pour-over extraction protocols in East Asian markets.
Beverage filter paper consists of porous sheet media engineered from cellulose, synthetic fibers, or cotton blends, typically manufactured through wet-laid nonwoven processes to achieve controlled porosity between 10 and 50 microns for liquid-solid separation. Its primary commercial purpose spans coffee extraction, tea infusion, juice clarification, and wine stabilization across foodservice and industrial processing environments. Wood pulp formulations occupy the dominant volume position due to cost scalability, though cellulose grades are gaining share among specialty tea producers seeking cleaner flavor profiles. Coffee brewing applications command the largest revenue pool, while juice clarification represents the fastest-expanding segment as cold-pressed beverage lines multiply.
FDA food-contact substance regulations govern migration limits for filter media used in US beverage manufacturing, while the EU F-Gas Regulation and REACH framework impose chemical disclosure and environmental compatibility standards on European suppliers. BIS certification requirements in India and GB standards administered by SAMR in China create divergent compliance pathways that fragment market access for multinational producers. Stakeholders must monitor evolving compostability certifications and regional single-use material restrictions to anticipate procurement specification shifts before they harden into mandatory compliance thresholds.
Market Dynamics
Single-serve brewing infrastructure expansion across specialty coffee chains is concentrating demand for precision-graded filter media, while regulatory pressure from the EU Single-Use Plastics Directive redirects procurement toward compostable cellulose alternatives. This dual force is compressing lead times and tightening specification windows for manufacturers.
Growth Catalysts
- Specialty coffee chain expansion:North American and European foodservice operators are installing single-serve brewing systems at scale, generating sustained pull for high-performance filter paper calibrated to exacting extraction protocols.
- EU Single-Use Plastics Directive:Mandatory reduction targets for plastic foodservice items are redirecting institutional procurement toward compostable cellulose filter alternatives certified under EN 13432.
- Artisanal coffee culture maturation:Germany's intersection of craft brewing sophistication and stringent packaging regulations is concentrating demand for specialty-grade filter specifications.
Market Restraints
- Pulp input cost volatility:Nordic wood pulp supply fluctuations and energy-intensive refining processes create margin compression for manufacturers dependent on conventional cellulose feedstocks.
- Supply concentration risk:Wet-laid nonwoven production capacity clusters in Western Europe and East Asia, exposing buyers to logistics disruption and currency exposure.
- Regulatory fragmentation:Divergent compliance pathways between FDA food-contact substance regulations, EU REACH frameworks, and China's GB standards administered by SAMR inflate certification costs for multinational suppliers.
Strategic Opportunities
- Cold-pressed juice clarification:Beverage processing lines multiplying in North American urban markets represent an underpenetrated application segment with faster volume expansion than traditional coffee brewing.
- Plant-based fiber convergence:Alternative pulp sources from agricultural residues and non-wood cellulose are opening specification differentiation for specialty tea producers seeking cleaner flavor profiles.
- Compostability certification premiums:TUV Austria and BPI certification standards are enabling pricing stratification for foodservice buyers with mandated sustainability procurement targets.
Industry Challenges
- Wet-laid process engineering talent scarcity:Specialized knowledge in porosity control between 10 and 50 microns resides with aging workforces in Nordic and Japanese manufacturing clusters.
- Multi-jurisdiction certification timelines:Sequential compliance with FDA migration limits, EU F-Gas Regulation chemical disclosure, and India's BIS requirements extends product launch cycles.
- Legacy brewing system integration:Pour-over and drip equipment installed bases constrain rapid format transitions, forcing parallel production runs during specification migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Filter Paper Market |
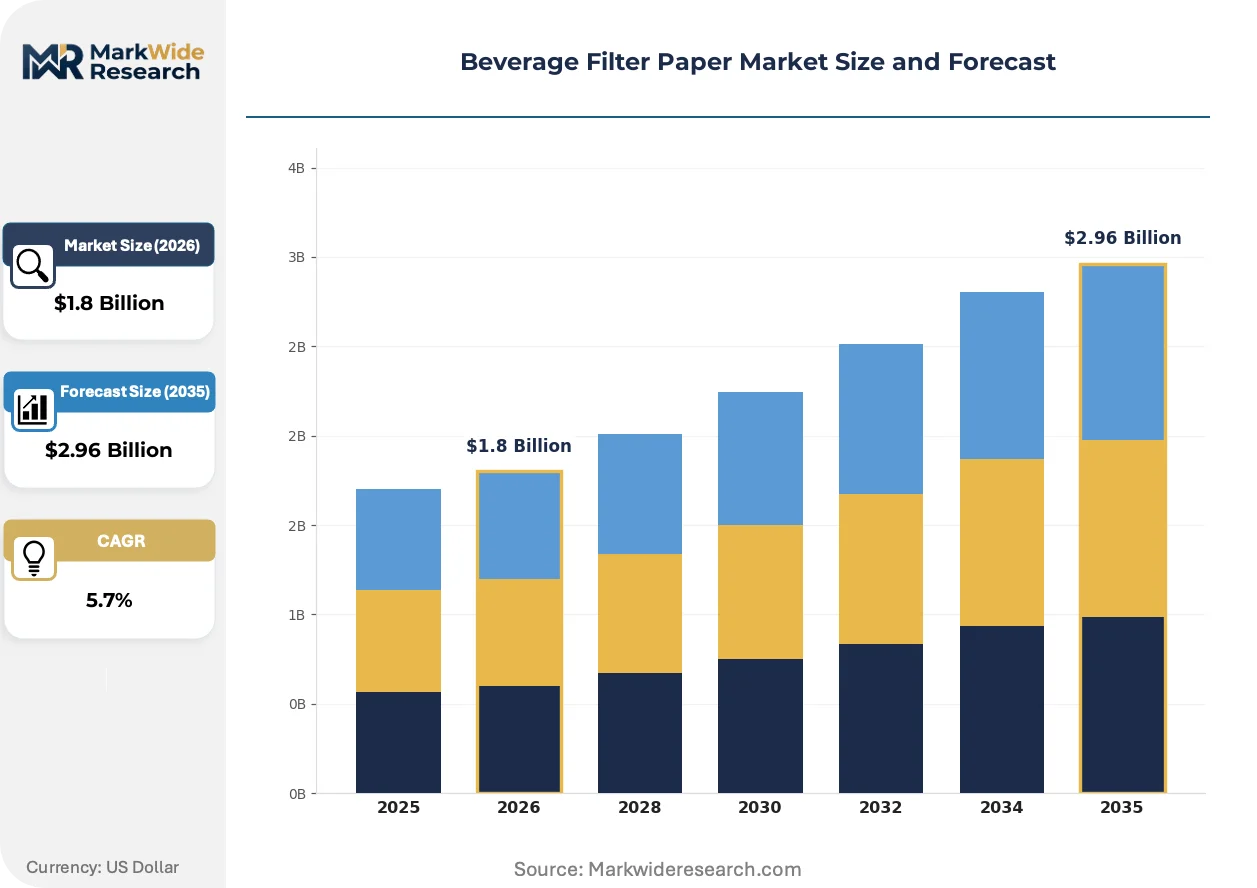
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pulp, Synthetic Fibers, Cotton, Cellulose, Glass Fiber Application: Coffee Brewing, Tea Filtration, Juice Clarification, Wine Filtration, Soft Drink Processing End User: Coffee Shops, Beverage Manufacturers, Specialty Tea Producers, Winemakers, Soft Drink Bottlers Packaging Type: Rolls, Sheets, Discs, Bags, Customized Cut Sizes |
| Companies Covered | Ahlstrom-Munksjö, Melitta Group, Hario Co., Ltd, Twin Rivers Paper Company, Rockline Industries, Purico Group, Finum GmbH, Terranova Papers, Glatfelter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Filter Paper Market Trends and Innovations
Digital specification tools and virtual quality assurance platforms are compressing the traditional sample-and-test cycle between filter manufacturers and beverage equipment OEMs. These innovations are redrawing competitive boundaries around speed-to-certification rather than scale alone.
Smart porosity control software is virtualizing the traditional laboratory-based quality verification process. Specialty coffee equipment manufacturers in Japan and South Korea are adopting cloud-based filtration performance modeling to pre-validate filter specifications before physical prototyping. This compression of the design-validation cycle is enabling faster private-label product launches and reducing minimum order quantities for regional filter suppliers.
REACH framework amendments on microplastic definition and the EU F-Gas Regulation's chemical disclosure mandates are tightening material traceability requirements. Filter manufacturers must now document synthetic fiber content and additive migration profiles through entire supply chains. Coffee and tea processing segments with direct export exposure to European markets are accelerating compliance investments ahead of mandatory enforcement windows.
Direct procurement relationships between roaster chains and filter manufacturers are disintermediating traditional distribution layers. Large specialty coffee operators in Germany and the United States are establishing volume commitments with specified performance tiers, bypassing wholesale paper merchants. This channel compression is most visible in urban markets where roasting equipment and filter media are bundled under single-source supply agreements with technical service integration.
Beverage Filter Paper Market Segmentation
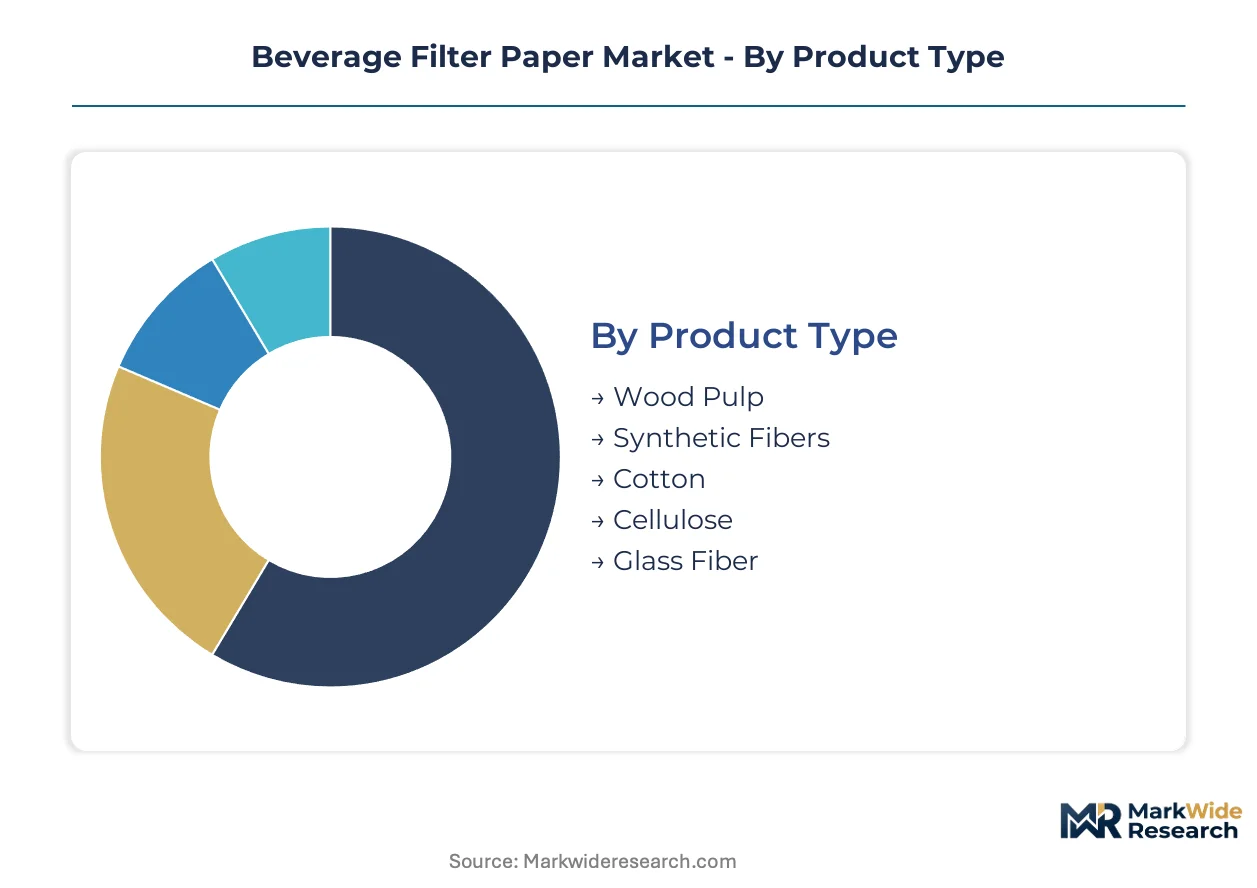
Filter paper specification varies dramatically across brewing methods and regulatory environments. Manufacturers must align porosity grades, compostability certifications, and format dimensions with distinct end-use protocols to secure procurement contracts.
Product Type:
Wood pulp formulations dominate mature volume positions while alternative cellulose sources are gaining specification share in premium segments.
- Wood Pulp:Conventional bleached and unbleached kraft pulps deliver cost-scalable porosity control between 10 and 50 microns. Nordic integrated producers leverage captive pulp supply to defend margin positions against energy cost volatility.
- Synthetic Fibers:Polypropylene and polyester blends enable heat-sealed bag construction for automated filling lines. Demand concentrates in soft drink bottling facilities requiring dimensional stability under high-temperature extraction protocols.
- Cotton:Long-staple cotton linters provide flavor-neutral filtration for specialty tea producers seeking minimal paper taste transfer. Japanese and Taiwanese Oolong processors specify cotton for premium loose-leaf applications.
- Cellulose:Purified cellulose grades certified under EN 13432 compostability standards are displacing plastic alternatives in EU foodservice procurement. German coffee chains mandate cellulose for single-serve pod compliance.
- Glass Fiber:Borosilicate microfiber layers achieve sub-10 micron retention for wine stabilization and microbial reduction. Champagne houses in France specify glass fiber for pre-bottling clarification stages.
Wood pulp retains volume leadership; cellulose holds the steepest expansion curve.
Application:
Revenue concentration follows beverage consumption patterns with emerging processing formats opening adjacent specification opportunities.
- Coffee Brewing:Drip, pour-over, and immersion methods each demand calibrated porosity profiles. Hario V60 and Chemex protocols in Japan and the United States specify 20-30 micron grades for optimal extraction timing.
- Tea Filtration:Heat-sealed bag papers must balance infusion rate with fiber migration limits. Indian and Sri Lankan black tea exporters favor double-chamber bag construction for foodservice distribution.
- Juice Clarification:Cold-pressed beverage lines in California and New York City are multiplying filtration stages for extended shelf stability. This segment is expanding most quickly among all beverage applications.
- Wine Filtration:Depth filtration and surface filtration sequences protect aromatic compound integrity. Bordeaux and Napa Valley winemakers specify sequential grades for pre-bottling polish.
- Soft Drink Processing:Carbonated beverage lines require inert media for syrup clarification and CO2 retention. Mexican and Brazilian bottlers drive volume for roll-format supply.
Coffee brewing commands revenue concentration; juice clarification shows the fastest volume acceleration.
End User:
Procurement sophistication varies from artisanal specification to industrial scale with diverging certification requirements.
- Coffee Shops:Third-wave roasting chains in Portland and Melbourne specify origin-traceable filter papers matched to grinding profiles. Direct manufacturer relationships are compressing distribution margins.
- Beverage Manufacturers:Multi-format producers integrate filtration into aseptic processing lines. FDA food-contact substance compliance is mandatory for US market access.
- Specialty Tea Producers:Darjeeling and Uji-based processors prioritize flavor neutrality and compostability credentials for European export positioning.
- Winemakers:Appellation-controlled producers in Champagne and Barossa Valley demand batch-consistent porosity for vintage integrity.
- Soft Drink Bottlers:High-volume automated lines specify roll formats with splice detection for continuous operation. Mexican bottlers represent the largest regional contract value.
Beverage manufacturers dominate procurement scale; specialty tea producers are gaining specification influence fastest.
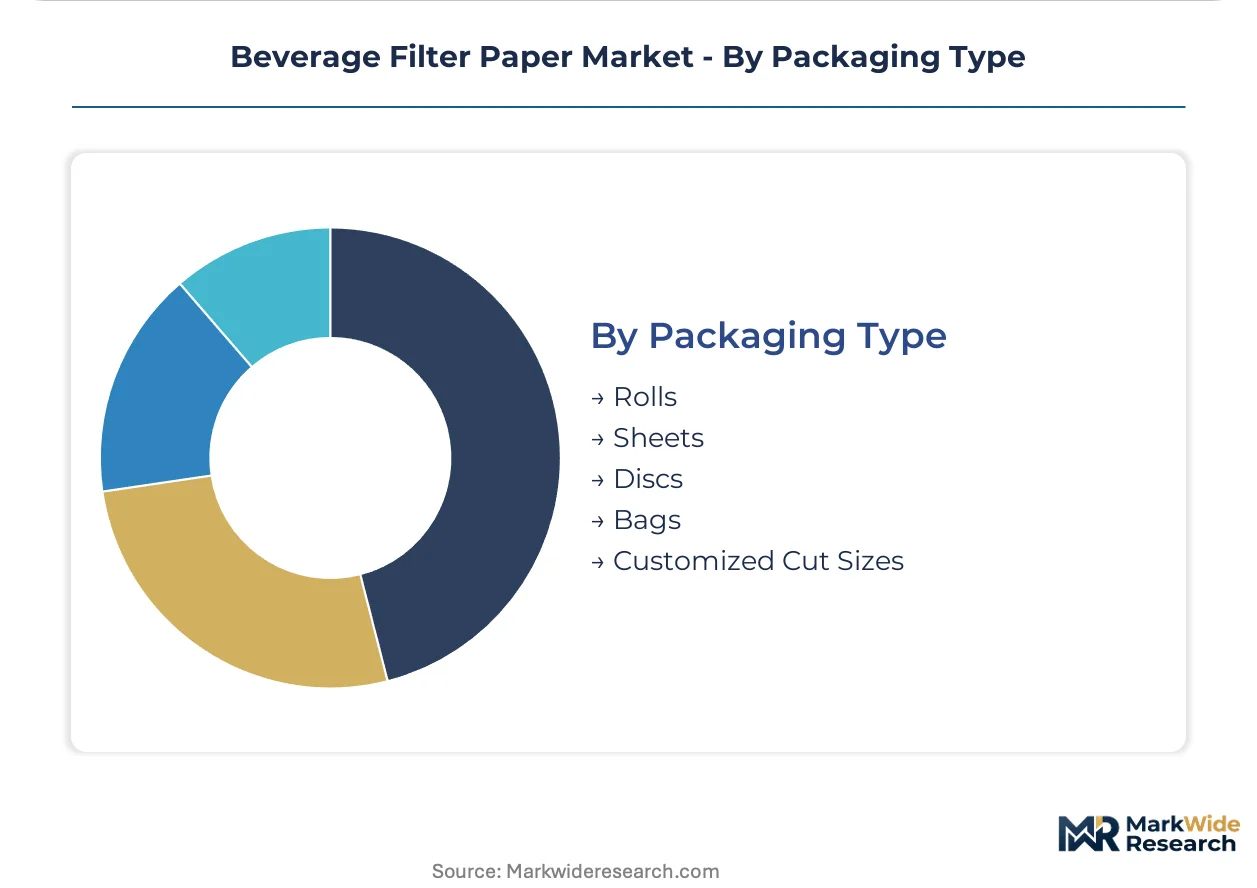
Packaging Type:
Format selection reflects equipment integration requirements and supply chain handling constraints across distribution channels.
- Rolls:Continuous web supply for automated cutting and forming equipment. Industrial beverage processors in Germany and Brazil specify 1000-meter master rolls for line efficiency.
- Sheets:Pre-cut dimensions for manual brewing equipment and foodservice portion control. Japanese pour-over cafes specify 100-sheet retail packs.
- Discs:Die-cut circles for pour-over cones and AeroPress compatibility. North American specialty retailers stock multiple diameter SKUs.
- Bags:Heat-sealed envelopes for single-serve tea and coffee infusion. EU compostability mandates are reshaping material specifications.
- Customized Cut Sizes:OEM-matched dimensions for proprietary brewing equipment. South Korean appliance manufacturers specify exclusive formats.
Rolls retain industrial volume leadership; bags are climbing fastest on single-serve format proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany as a net importer of specialty-grade filter media while Japan and the United States maintain trade surpluses in precision-manufactured segments. Nordic pulp availability shapes cost competitiveness across European supply chains.
Germany
Artisanal coffee culture and stringent packaging regulations intersect to concentrate demand for high-performance filter specifications. The EU Single-Use Plastics Directive mandates compostable cellulose alternatives for foodservice procurement. Berlin and Hamburg anchor roasting equipment clusters where direct manufacturer relationships compress traditional distribution layers.
United States
Specialty coffee chains expand single-serve brewing infrastructure across Portland and Seattle metropolitan areas. FDA food-contact substance regulations govern migration limits for filter media used in beverage manufacturing. California cold-pressed juice lines multiply filtration stages, creating adjacent specification opportunities beyond traditional coffee applications.
Japan
Pour-over extraction protocols in Tokyo and Osaka drive specification for 20-30 micron precision grades. METI oversees industrial standards alignment with export market requirements. Nagoya manufacturing clusters house specialized wet-laid process engineering capabilities for porosity control.
China
Domestic tea processors and international soft drink bottlers sustain dual demand tracks for bag construction and roll-format supply. SAMR-administered GB standards create compliance pathways distinct from Western regulatory frameworks. Guangdong and Zhejiang provinces concentrate automated filling line installations requiring heat-sealed media.
India
Black tea exporters in Assam and Darjeeling favor double-chamber bag construction for foodservice distribution. BIS certification requirements fragment market access for multinational producers seeking entry. Mumbai and Chennai processing facilities integrate filtration into aseptic packaging lines for export positioning.
Beverage Filter Paper Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pulp producers and specialized wet-laid nonwoven fabricators with captive technical expertise. Three strategic archetypes dominate: Nordic pulp-integrated manufacturers leveraging raw material cost advantages, Japanese precision-grade specialists serving pour-over equipment OEMs, and European retail-anchored brands controlling drip brewing system distribution. Competitive moves center on backward integration into pulp supply and direct procurement relationships with roasting chains that disintermediate wholesale merchants.
Within the pulp-integrated tier, Ahlstrom-Munksjö represents Nordic cost-advantaged positioning through captive raw material flows. Melitta Group occupies the retail-anchored archetype with decades of brand equity in European drip brewing distribution. Hario Co., Ltd exemplifies the precision-grade specialist model, calibrated for East Asian pour-over extraction protocols. These three anchors illustrate how geographic specialization and equipment integration create defensible competitive positions without scale dominance.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Melitta Group |
| Hario Co., Ltd |
| Twin Rivers Paper Company |
| Rockline Industries |
| Purico Group |
| Finum GmbH |
| Terranova Papers |
| Glatfelter |
| Others |
Pricing and Supply Chain Analysis
Nordic wood pulp supply volatility compresses margins across both premium cellulose grades and commodity kraft formulations, forcing manufacturers to stratify pricing tiers by certification level while reshaping procurement geography toward captive pulp integration and regional compostability mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-commitment discounts tied to EN 13432 compostability certification tiers. Price differentiation separates TUV Austria-certified premium grades from standard kraft pulps and economy synthetic blends. Pricing pressure stems from energy-intensive refining processes and Nordic pulp input cost swings. Beverage manufacturers with automated filling lines exhibit lowest price sensitivity; artisanal roasting chains with direct manufacturer relationships negotiate hardest on per-unit basis.
Supply Chain Analysis
EU REACH framework chemical disclosure mandates restrict synthetic fiber flows into European foodservice channels, concentrating compliant supply in Nordic integrated producers and Japanese precision-grade specialists. Wet-laid nonwoven capacity draws from bleached kraft pulp, cotton linters, and agricultural residue cellulose. Single-source vulnerability runs through Nordic pulp merchant supply to Western European fabricators. Distribution runs through direct procurement relationships with large roasting chains that disintermediate wholesale paper merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive enforcement window creates a high-growth disruption as compostable cellulose mandates eliminate plastic alternatives from institutional procurement channels.
For Market Incumbents: Pre-empt margin compression from pulp cost volatility by securing captive Nordic pulp supply or backward integration into agricultural residue processing. Invest in TUV Austria and BPI certification infrastructure ahead of mandatory compliance windows to defend specification share against emerging plant-fiber competitors. For New Entrants and Emerging Players: Establish a beachhead in cold-pressed juice clarification segments where filtration stage multiplication outpaces traditional coffee application growth. Target California and New York City beverage processing lines with compostable cellulose grades certified for extended shelf stability protocols. For Investors and Strategic Acquirers: REACH framework amendments on microplastic definition reshape the acquisition landscape toward wet-laid process engineering capabilities with documented synthetic fiber traceability. The five-to-ten year viability window favors precision-grade specialists serving pour-over equipment OEMs. Watch for EU F-Gas Regulation enforcement timing as inflection indicator for compostability certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic kraft pulp flows defend margin positions against energy cost volatility. |
| Compostability Certification Investment | TUV Austria and BPI standards enable pricing stratification for EU foodservice procurement. |
| Direct Roasting Chain Partnerships | Bypassing wholesale merchants compresses distribution layers and locks volume commitments. |
| Cold-Pressed Juice Segment Expansion | California and New York processing lines multiply filtration stages faster than coffee applications. |
| Wet-Laid Process Engineering Acquisition | Specialized porosity control knowledge resides with aging workforces in Nordic and Japanese clusters. |
Research Methodology
A standing panel of wet-laid process engineers, specialty coffee equipment procurement leads, foodservice sustainability officers, and compostability certification auditors provided ongoing calibration. Primary interviews with filter manufacturers and roasting chain technical buyers combined with secondary validation from EU ECHA substance registrations, FDA food-contact substance filings, customs trade flow data, and BIS certification records. Bottom-up segment volume builds triangulated against top-down pulp consumption estimates across the analysis window.
Scenario-bracketing framed low, base, and high cases across regulatory enforcement timing and pulp cost trajectories. Segmentation dimensions modeled include material formulation grade, brewing application protocol, compostability certification tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cold-pressed juice line expansion rates and single-serve brewing infrastructure installation pace as key industry-specific inputs.
Stress conditions across Nordic pulp supply disruption, EU Single-Use Plastics Directive accelerated enforcement, and REACH microplastic definition scope expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on substitution elasticity between cellulose and synthetic fiber grades. Material shifts in EU compostability mandate timing or Nordic pulp merchant consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Liquid Packaging Board Market