
 Paper Packaging Materials Market | 2026-2036
Paper Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Packaging Materials Market Intelligence
The shift towards high-strength, lightweight corrugated board is unwinding the traditional reliance on heavier, less sustainable packaging formats. This transition prioritizes material efficiency without compromising product protection during transit. International Paper leverages its extensive fiber sourcing and manufacturing scale to serve high-volume customers. Smurfit Kappa differentiates through its focus on circular economy-driven designs and packaging services, while WestRock Company specializes in innovative containerboard and folding carton solutions.
Paper packaging materials are cellulose-fiber-based products, derived from wood pulp or recycled paper, and formed into sheets of varying basis weights and strengths. Key materials include kraft paper and corrugated board, which are engineered for containment, protection, and transport of goods. Corrugated board represents the largest material type segment by volume, driven by its universal application in shipping boxes. Higher-margin opportunities exist in specialized paperboard and greaseproof paper for the food & beverage and pharmaceuticals end-use industries.
Regulatory frameworks are a primary influence on material specifications and design. The European Union's Packaging and Packaging Waste Regulation (PPWR) mandates increased recyclability, while the U.S. FDA sets strict standards for food-contact paper. These rules compel manufacturers to innovate in barrier coatings and fiber sourcing. Stakeholders must navigate the strategic trade-off between incorporating higher recycled content and maintaining the performance integrity required for demanding applications.
Market Dynamics
The central structural force shaping the paper packaging market is the regulatory drive for a circular economy. Mandates like the EU's Packaging and Packaging Waste Regulation are compelling a systemic shift away from single-use designs toward verifiable recyclability and higher recycled content.
Growth Catalysts
- E-commerce Expansion:Proliferation of online retail, particularly in the food and beverage sector, is boosting demand for lightweight, durable corrugated board and protective paper-based void fill solutions designed for direct-to-consumer shipping.
- Regulatory Mandates:The EU's Packaging and Packaging Waste Regulation (PPWR) incentivizes the use of paper and paperboard by setting ambitious recyclability targets, pressuring brands to transition away from less recyclable multi-material packaging formats.
- Manufacturing in Southeast Asia:Rapid industrialization and growth in consumer goods manufacturing across economies like Vietnam and Indonesia are creating concentrated demand for primary and secondary paper packaging materials.
Market Restraints
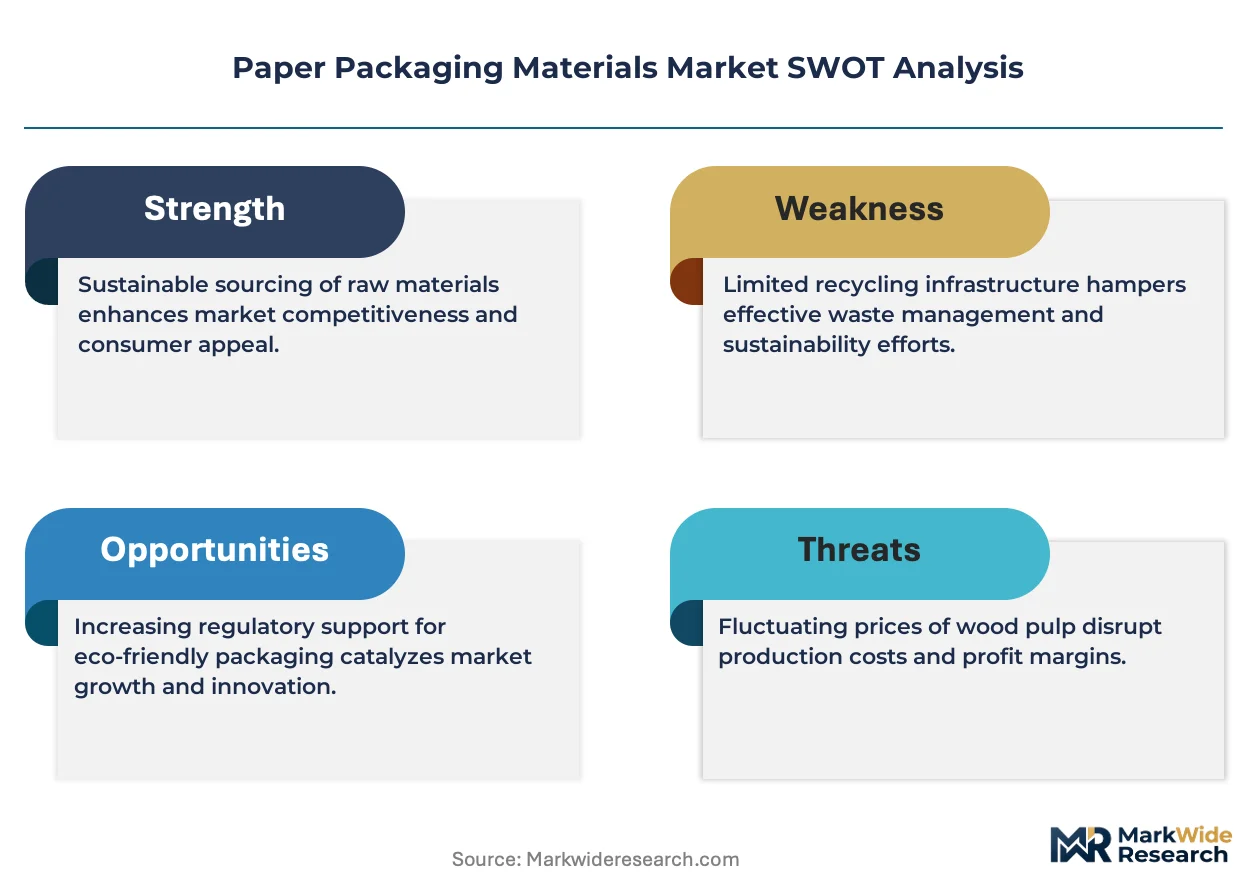
- Input Cost Volatility:Fluctuations in the price of key raw materials, specifically virgin wood pulp and recovered paper fiber, create significant margin pressure and unpredictability for packaging converters and manufacturers.
- Performance Limitations:Standard paper and paperboard lack the inherent barrier properties of plastics against moisture, oxygen, and grease, posing a technical hurdle for replacing flexible packaging in certain demanding food applications.
- Competition from Flexible Plastics:In cost-sensitive segments like snack foods and confectionery, lightweight flexible plastic packaging continues to present a strong substitution threat due to its lower cost and superior barrier performance.
Strategic Opportunities
- Bio-Based Barrier Coatings:Development and commercialization of compostable or fully recyclable bio-based coatings present a significant opportunity to penetrate high-value food packaging applications currently dominated by plastic-laminated papers.
- Pharmaceutical Packaging:The pharmaceuticals end-use segment represents a high-margin opportunity for specialized, tamper-evident paperboard cartons and inserts that meet stringent regulatory and supply chain security requirements.
- Latin American Market Entry:Expanding e-commerce and retail sectors in countries such as Brazil and Mexico offer underpenetrated markets for corrugated box and folding carton producers seeking geographic diversification.
Industry Challenges
- Food-Contact Certification:Navigating the complex and lengthy approval process for new food-contact materials with bodies like the U.S. FDA creates a significant barrier to entry and slows the commercialization of innovative papers and coatings.
- Recycled Fiber Quality:Increasing the proportion of recycled content in packaging while maintaining strength and printability is a major operational challenge, constrained by the quality and availability of sorted recovered paper.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Packaging Materials Market |
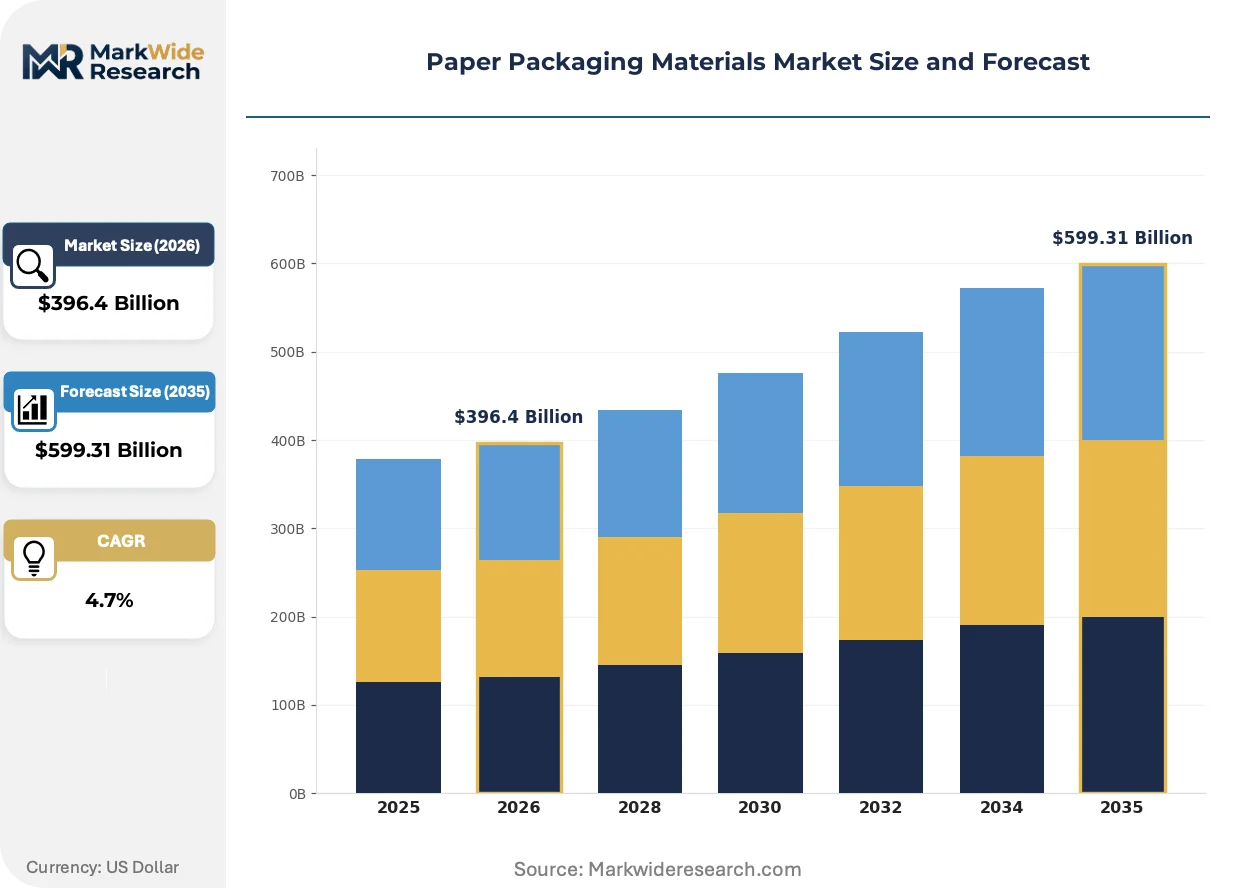
| Market Size in 2026 | $396.4 Billion |
| Market Size in 2035 | $599.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Corrugated Board, Paperboard, Recycled Paper, Greaseproof Paper End Use Industry: Food & Beverage, Personal Care, Electronics, Pharmaceuticals, Household Goods Packaging Format: Boxes, Bags, Wraps, Sleeves, Cartons Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | International Paper, WestRock Company, Smurfit Kappa, DS Smith Plc, Mondi, Stora Enso, Georgia-Pacific, Packaging Corporation of America, Tetra Pak International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Packaging Materials Market Strategic Shifts & Innovations
Material science innovation is focused on closing the performance gap with less sustainable alternatives. The primary effort involves engineering paper-based solutions that meet the functional requirements of demanding applications, like fresh food, without compromising the material's inherent recyclability.
High-performance barrier coatings for paperboard provide essential resistance to moisture, grease, and oxygen. Food and beverage brand owners are the primary adopters, seeking to replace plastic components in their packaging. This adoption pattern is bifurcating the market into premium, fully recyclable coated papers that command higher prices and lower-cost, conventional polyethylene-coated boards that face regulatory headwinds.
The European Union's Packaging and Packaging Waste Regulation (PPWR) establishes stringent design-for-recycling criteria and minimum recycled content targets. This directly impacts material choice, compelling manufacturers to innovate away from composite structures. The regulation most affects producers of packaging for liquids and greasy foods, pushing them to adopt mono-material paper solutions to ensure market access within the EU.
A demand-side shift toward right-sized packaging is accelerating in the e-commerce sector. This behavioral change away from standard stock box sizes is driven by logistics providers' dimensional weight pricing models. This trend is most prominent in North American and European fulfillment operations, where it is creating demand for on-demand box-making machinery and software-optimized package design.
Paper Packaging Materials Market Segmentation
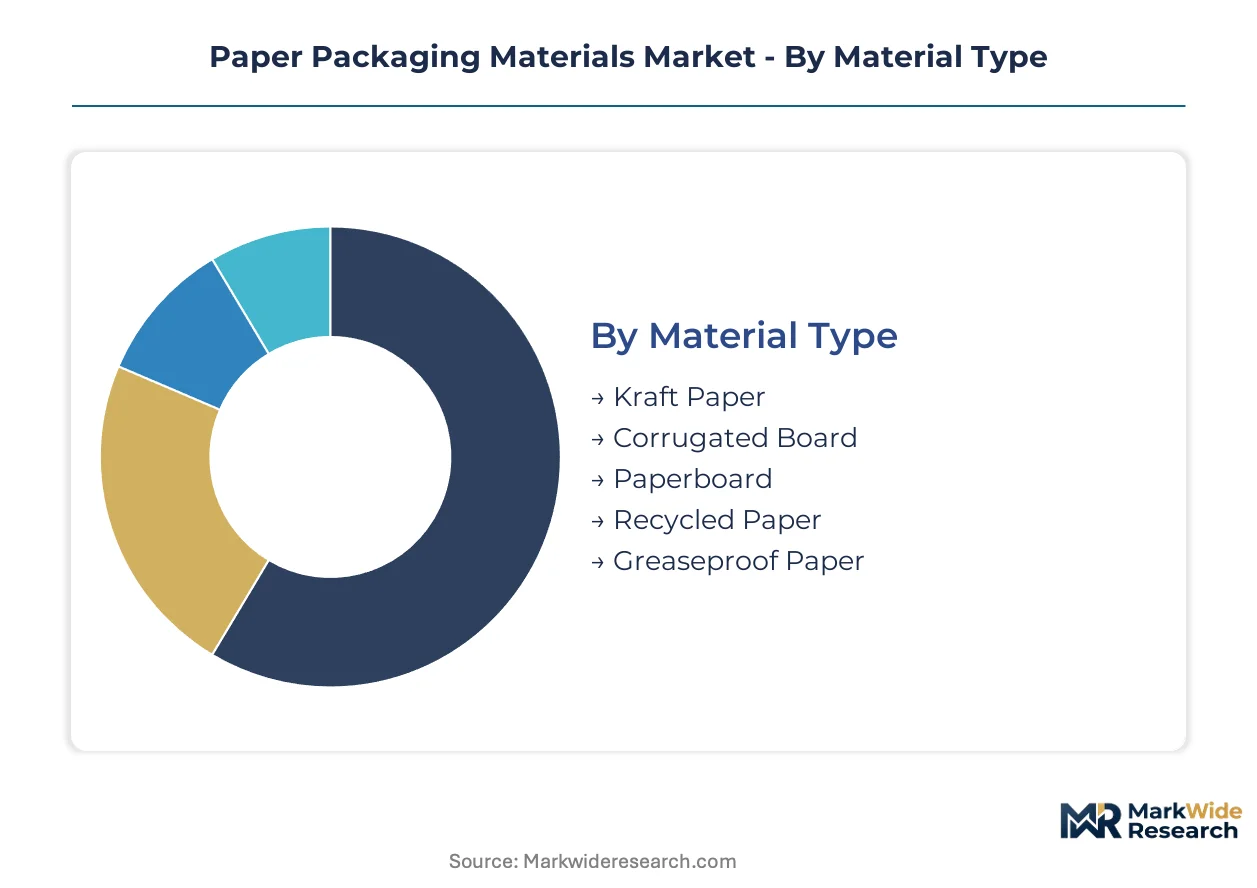
The paper packaging materials market segments across diverse material types, end-use industries, packaging formats, and distribution channels. Understanding these segments reveals specific growth pockets and areas where regulatory pressures or technological advancements are most impactful. Each segment presents unique performance requirements and commercial opportunities for manufacturers.
Material Type:
Margin pools for paper packaging materials concentrate in specialized applications requiring enhanced performance and material integrity.
- Corrugated Board:This material consists of fluted sheets glued between two flat linerboards, providing structural rigidity and cushioning for packaged goods. Demand is high for e-commerce applications, particularly in North America and Europe, driven by dimensional weight pricing models from logistics providers.
- Paperboard:Paperboard is a thick, multi-layered paper-based material engineered for stiffness and printability in folding cartons and displays. Pharmaceutical and food & beverage sectors drive demand for specialized paperboard in the EU, adapting to stringent recyclability mandates from the PPWR.
- Kraft Paper:Kraft paper offers high tensile strength and tear resistance, commonly used for bags, wraps, and protective interleaving.
- Recycled Paper:This segment utilizes post-consumer or post-industrial fiber as feedstock, driven by circular economy mandates and cost efficiencies.
- Greaseproof Paper:Greaseproof paper provides a barrier against oils and fats, primarily serving food service and confectionery packaging.
Corrugated Board holds installed capacity. Greaseproof Paper is rotating up the share rankings.
End Use Industry:
Application diversity defines the paper packaging market, with distinct material requirements across consumer sectors.
- Food & Beverage:This segment utilizes packaging for containment and preservation of consumables, ranging from dry goods to fresh produce. Demand is expanding fastest in Southeast Asian economies, driven by consumer goods manufacturing and e-commerce proliferation.
- Pharmaceuticals:Pharmaceutical packaging requires high-security and tamper-evident features for medicines and medical devices, often incorporating specialized paperboard inserts. Regulatory bodies like the U.S. FDA and EMA drive material specifications, focusing on product integrity and supply chain security.
- Personal Care:Personal care products use paper packaging for cosmetic boxes, tissue wraps, and hygiene product cartons, focusing on aesthetic appeal and brand presentation.
- Electronics:Electronics packaging protects delicate components during transit, often using custom-fit corrugated inserts and folding cartons.
- Household Goods:This category encompasses packaging for items like cleaning supplies, small appliances, and home textiles, prioritizing durability and cost-effectiveness.
Food & Beverage applications consume the largest volumes. Electronics packaging is gaining share fastest.
Packaging Format:
Packaging formats vary significantly in volume and design complexity, catering to diverse product protection and presentation needs.
- Boxes:Boxes provide primary and secondary packaging for shipping and retail display, manufactured primarily from corrugated board or folding carton stock. E-commerce expansion in Latin America fuels demand for custom-sized boxes, reducing shipping costs and material waste.
- Cartons:Cartons are typically folding paperboard containers, often used for consumer goods due to their printability and structural integrity. The EU's Packaging and Packaging Waste Regulation incentivizes mono-material cartons for liquids and greasy foods, ensuring market access and recyclability.
- Bags:Paper bags serve retail, grocery, and industrial purposes, emphasizing strength and eco-friendly attributes.
- Wraps:Paper wraps protect products during transit or storage, offering cushioning and surface protection.
- Sleeves:Sleeves provide secondary packaging or branding for products, often made from paperboard for visual appeal.
Boxes represent the largest format by volume. Sleeves are climbing the fastest in adoption.
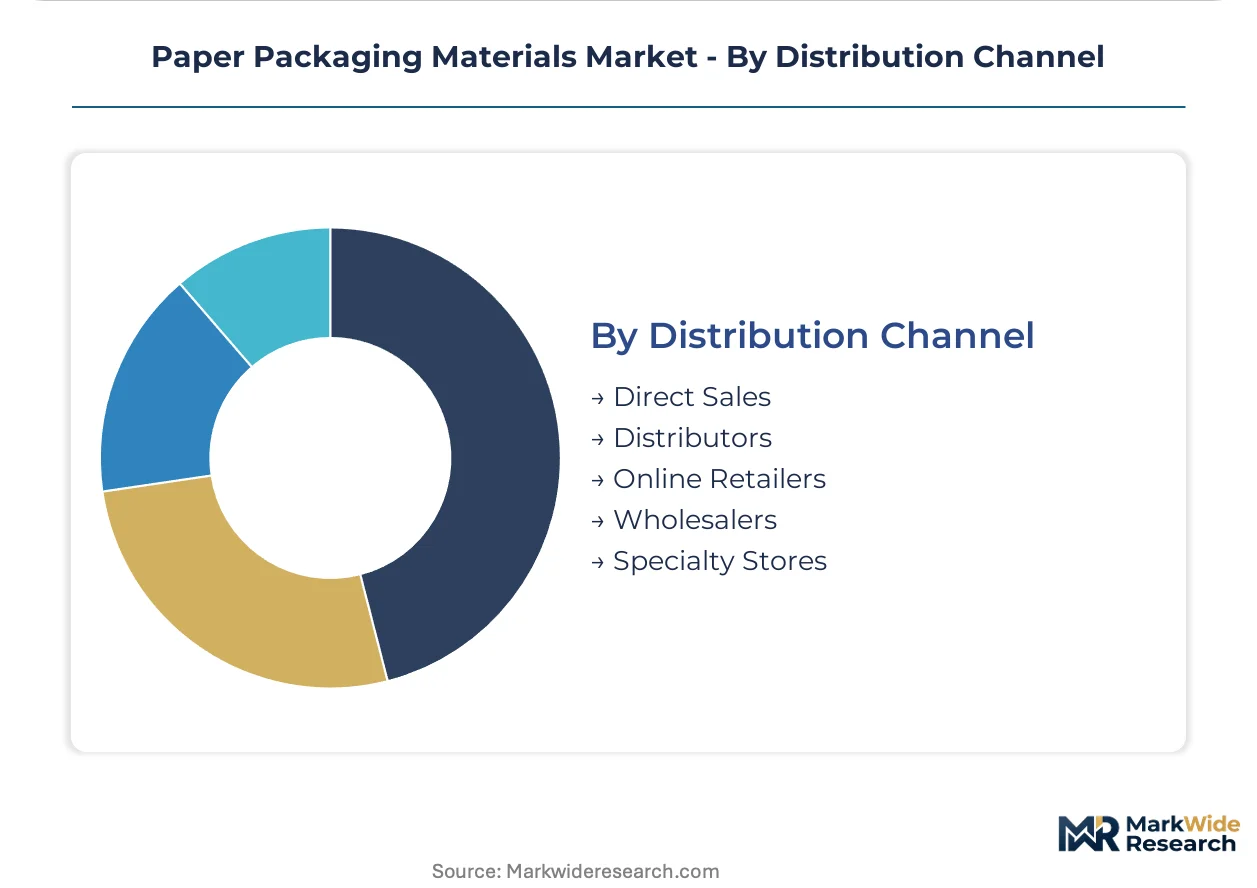
Distribution Channel:
Customer type influences distribution channel selection, impacting logistics and inventory management for paper packaging suppliers.
- Direct Sales:Direct sales involve manufacturers selling packaging materials directly to large-volume end-users, facilitating customized solutions and long-term contracts. International Paper leverages this channel to serve high-volume customers globally, ensuring supply chain efficiency and product consistency.
- Online Retailers:Online retailers facilitate the purchase of packaging supplies through digital platforms, catering to small and medium-sized businesses with convenience and broad product catalogs. E-commerce proliferation drives demand for these platforms, particularly for protective void fill solutions and standard shipping boxes.
- Distributors:Distributors act as intermediaries, stocking and reselling a variety of packaging materials to diverse customer bases.
- Wholesalers:Wholesalers purchase large quantities of packaging products for resale, often to smaller businesses or retailers.
- Specialty Stores:Specialty stores offer niche packaging solutions, often focusing on aesthetic or custom-designed paper products for specific industries.
Direct Sales channels handle the greatest transaction value. Online Retailers are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for paper packaging materials varies significantly across regions. Mature economies often prioritize sustainable attributes and performance, exhibiting less price sensitivity for specialized solutions. Emerging markets typically show higher price sensitivity, driving demand for cost-effective, high-volume corrugated board.
United States
E-commerce proliferation and a robust food and beverage sector drive significant demand for paper packaging in the United States. The U.S. FDA sets stringent standards for food-contact paper, compelling innovation in barrier solutions. California's tech and agricultural hubs require advanced corrugated and specialized paperboard.
Germany
Germany's advanced manufacturing base and commitment to sustainability generate consistent demand for high-quality paper packaging. The EU's Packaging and Packaging Waste Regulation heavily influences material choices, emphasizing recyclability. The Rhine-Ruhr region actively integrates mono-material paper solutions.
China
China's vast e-commerce market and expanding consumer goods manufacturing are primary drivers for paper packaging demand. Its dual carbon goals push manufacturers towards more sustainable and recyclable packaging solutions. The Yangtze River Delta, a critical hub, exhibits concentrated demand for high-volume corrugated board.
India
India's burgeoning middle class and rapid expansion of organized retail and e-commerce fuel a substantial need for paper packaging materials. BIS standards guide packaging specifications, while government initiatives support domestic production. The Delhi-NCR region shows high demand for consumer-facing packaging and e-commerce boxes.
Brazil
Brazil's expanding e-commerce sector and robust food and beverage industry drive demand for paper packaging solutions. ANVISA regulations specifically govern food contact materials, influencing barrier coating innovations. The São Paulo metropolitan area consistently requires folding cartons and corrugated solutions.
Paper Packaging Materials Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the paper packaging market. The market exhibits a tiered structure, with large integrated producers alongside specialized innovators. Global players with extensive fiber sourcing and manufacturing scale often dominate high-volume segments. Smaller, agile firms frequently focus on niche applications requiring advanced material science. Competitive moves center on strategic partnerships for sustainable material development and regional capacity expansion.
Global integrated giants like International Paper and WestRock Company exemplify the scale-driven end of the market, leveraging vast fiber resources and manufacturing networks. These companies often serve high-volume customers with a broad range of corrugated and paperboard solutions across multiple geographies. Smurfit Kappa occupies a position as a specialist in circular economy-driven designs, focusing on comprehensive packaging services and sustainable innovation. DS Smith Plc also represents a significant force in recycled packaging, emphasizing design for recyclability and supply chain efficiency. These firms collectively represent diverse strategic approaches to serving various end-use industries and customer segments.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Smurfit Kappa |
| DS Smith Plc |
| Mondi |
| Stora Enso |
| Georgia-Pacific |
| Packaging Corporation of America |
| Tetra Pak International S.A. |
| Others |
Cost & Logistics Intelligence
The European Union's Packaging and Packaging Waste Regulation (PPWR) gates supply qualification and price differentiation for paper packaging materials. This regulation compels innovation in sustainable formats, influencing material costs and market access.
Pricing Analysis
Packaging design services and technical support drive customer lifetime value in paper packaging. The dominant pricing model involves contract-based long-term offtake for high-volume customers, complemented by transactional pricing for standard items. Price differentiation stems from quality grade, specific regulatory certifications like U.S. FDA compliance, and the level of customization. Pricing softness affects commodity paperboard grades due to input cost volatility, making cost-sensitive segments like basic e-commerce boxes highly price-sensitive compared to pharmaceutical packaging.
Supply Chain Analysis
Container availability and port delays across key trans-Pacific trade lanes impact inbound logistics costs for paper packaging. Global supply of virgin wood pulp largely originates from North America and Nordic countries, while recovered paper fiber feedstock often draws from Europe. Raw material dependencies include virgin wood pulp, recycled fiber, and specialized barrier coating chemicals, creating commodity price volatility risk. Distribution runs through direct sales channels for major customers and via distributors and online retailers for smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper packaging market is experiencing a significant buyer-power shift, driven by the consolidation of large consumer goods manufacturers. These larger buyers exert increased influence over material specifications and pricing terms.
For Market Incumbents: Secure long-term supply agreements for high-quality recycled fiber, mitigating input cost volatility. Invest in advanced material science for bio-based barrier coatings to counter the performance limitations of standard paper against flexible plastics. Expand manufacturing presence in high-growth Southeast Asian economies to serve concentrated demand, leveraging existing fiber sourcing networks. Pursue certifications like the U.S. FDA for food-contact materials to maintain market access.
For New Entrants and Emerging Players: Differentiate on sustainable material innovation, particularly in fully recyclable bio-based barrier coatings for food and beverage applications. Target underpenetrated markets in Latin America, focusing on custom-sized corrugated boxes for expanding e-commerce operations. Specialize in high-margin pharmaceutical packaging, offering tamper-evident paperboard cartons that meet stringent regulatory requirements. Emphasize design-for-recyclability services to align with evolving regulatory frameworks like the EU's PPWR.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialized packaging converters focusing on sustainable solutions. The paper packaging market presents long-term viability, driven by secular tailwinds from e-commerce expansion and global sustainability mandates over the next decade. Target acquisition candidates include firms with proprietary bio-based barrier coating technologies or strong market positions in specialized pharmaceutical packaging. Watch for the successful commercialization of fully recyclable mono-material paper solutions as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Barrier Coating Development | Enables penetration into high-value food packaging applications currently dominated by plastics. |
| Southeast Asia Capacity Expansion | Captures concentrated demand from rapid consumer goods manufacturing growth in the region. |
| Recycled Fiber Sourcing Partnerships | Secures feedstock for circular economy mandates and mitigates input cost volatility. |
| Pharmaceutical Packaging Certification | Opens access to high-margin segments requiring stringent U.S. FDA and EMA compliance. |
| E-commerce Optimized Design Services | Addresses demand for right-sized packaging and reduces shipping costs for online retailers. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings of this study. The analysis involved in-depth discussions with packaging engineers, procurement leads, brand managers in consumer goods, and regulatory affairs specialists. Secondary data sources included industry association reports, company annual reports, and regulatory filings from bodies like the EU and U.S. FDA. This approach ensured robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis informed the forecast framework, assessing potential impacts of varying market conditions over the projection horizon. The quantitative model segmented the market by material type, end-use industry, packaging format, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included e-commerce growth rates and mandated recycled content targets.
Material uncertainties — such as significant geopolitical shifts or unforeseen technological breakthroughs in alternative materials — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and economic growth across the analysis window. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Disposable Paper Cups Market