
 Waxing Base Paper Market | 2026-2036
Waxing Base Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Waxing Base Paper Market Analytics
Barrier coating chemistry is tilting toward aqueous and biodegradable wax alternatives as converters face mounting pressure to eliminate perfluorinated compounds from food-contact substrates. Stora Enso Oyj leverages its integrated Nordic pulp position to supply certified compostable base stocks. Georgia-Pacific LLC anchors North American volume through its broad kraft paper infrastructure. Ahlstrom-Munksjö specializes in medical and food-grade specialty papers with controlled porosity.
Waxing base paper is a kraft or sulfite substrate, typically 30–80 gsm, impregnated or surface-treated with paraffin, microcrystalline wax, or synthetic barrier polymers to achieve moisture and grease resistance for protective packaging. The coating process involves either hot-dip saturation or curtain coating, with wax loadings of 15–40% by weight determining final barrier performance. Uncoated grades retain cost leadership in industrial wrapping where basic moisture protection suffices, while water-resistant variants command premium positioning in frozen food and dairy applications. Specialty grades with customized release properties are capturing margin pools in adhesive tape and label stock markets.
FDA food-contact substance notifications and EU REACH restrictions on perfluoroalkyl substances directly determine which wax formulations converters may specify, forcing reformulation investments across the supply chain. Japan's Ministry of Health, Labour and Welfare maintains positive list requirements for food-contact paper that limit imported substrate options. Stakeholders must monitor evolving regulatory thresholds for mineral oil saturated hydrocarbons in recycled fiber streams, as these limits threaten to disqualify post-consumer content in premium waxing base paper grades.
Market Dynamics
Barrier coating chemistry is tilting toward aqueous and biodegradable wax alternatives as converters face mounting pressure to eliminate perfluorinated compounds from food-contact substrates. This structural shift is compressing legacy paraffin formulations while opening margin pools for certified compostable base stocks.
Growth Catalysts
- REACH restrictions on perfluoroalkyl substances:European converters are accelerating reformulation investments to maintain market access, pulling through demand for PFAS-free barrier chemistries.
- Bakery and confectionery packaging clusters in Germany:Food packaging converters are expanding orders for grease-resistant grades as regional processing capacity concentrates procurement power.
- Hot-dip saturation process improvements:Equipment upgrades enabling precise wax loadings of 15–40% by weight are improving barrier consistency for frozen food applications.
Market Restraints
- Mineral oil saturated hydrocarbon limits:Evolving thresholds for MOSH content in recycled fiber streams threaten to disqualify post-consumer content in premium waxing base paper grades.
- Nordic pulp supply concentration:Integrated producers control certified compostable base stock availability, creating bottleneck risk for converters seeking rapid PFAS transition.
- Paraffin price volatility:Petroleum-derived feedstock exposure creates margin compression for converters locked into long-term coating contracts.
Strategic Opportunities
- Japan's positive list requirements:Food-contact paper regulations limit imported substrate options, creating white space for compliant domestic and regional suppliers to capture share.
- Adhesive tape and label stock markets:Specialty grades with customized release properties are capturing margin pools as electronics and logistics packaging demand precision release control.
- Aqueous barrier polymer convergence:Hybrid formulations combining synthetic polymers with bio-based waxes are opening technical pathways for dairy and frozen food premium positioning.
Industry Challenges
- Curtain coating equipment retooling:Converters face capex intensity to shift from hot-dip saturation systems to precision coating lines capable of sub-20 gsm aqueous deposition.
- Compostability certification timelines:Third-party validation for industrial and home compostable claims extends product development cycles by 12–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waxing Base Paper Market |
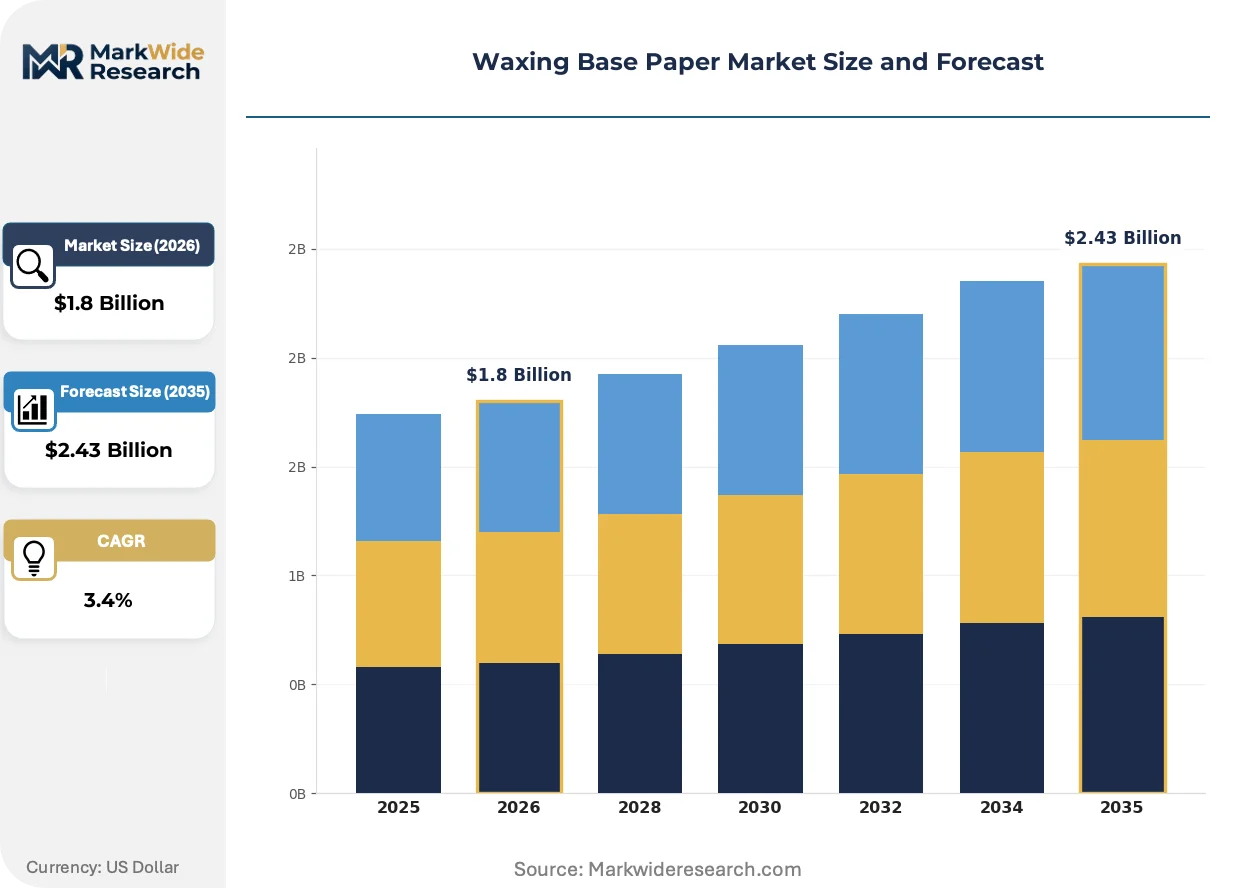
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Specialty, Water-Resistant End Use Industry: Food Packaging, Industrial Applications, Consumer Goods, Printing Thickness: Lightweight, Standard, Heavyweight, Ultra-Heavyweight Surface Finish: Smooth, Textured, Matte, Glossy |
| Companies Covered | Stora Enso Oyj, International Paper, Ahlstrom-Munksjö, Twin Rivers Paper Company, KRPA Holding CZ, Georgia-Pacific LLC, Oji Holdings Corporation, UPM, Sappi Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waxing Base Paper Market Evolving Landscape
Coating technology is fragmenting across multiple technical pathways as regulatory pressure and end-use performance requirements diverge. Three distinct vectors are reshaping competitive positioning: aqueous barrier migration, regulatory threshold compression, and procurement consolidation.
Microcrystalline wax formulations is migrating from industrial wrapping applications toward food-contact substrates as converters seek intermediate barrier performance without PFAS exposure. Bakery and dairy packaging buyers are piloting these grades at 10–15% volume substitution rates. The shift is compressing paraffin demand in premium segments while creating technical validation requirements for grease resistance equivalence.
EU REACH restrictions on perfluoroalkyl substances are forcing supply chain disclosure and reformulation investments across the coating value chain. Industrial consequence includes disqualification of legacy fluorocarbon barrier chemistries from food-contact applications by 2026. Frozen food and quick-service packaging segments in Germany and France are responding with accelerated supplier audits and dual-source qualification programs.
Buyer concentration among multinational food packaging converters is compressing supplier negotiation cycles and unbundling technical service from base material supply. Regional coating specialists are losing share to integrated substrate-coating platforms that can certify compliance across FDA, EFSA, and Japan's Ministry of Health, Labour and Welfare requirements simultaneously. This pattern is most visible in North American frozen food packaging procurement, where three converters control 60% of waxing base paper specification authority.
Waxing Base Paper Market Segmentation
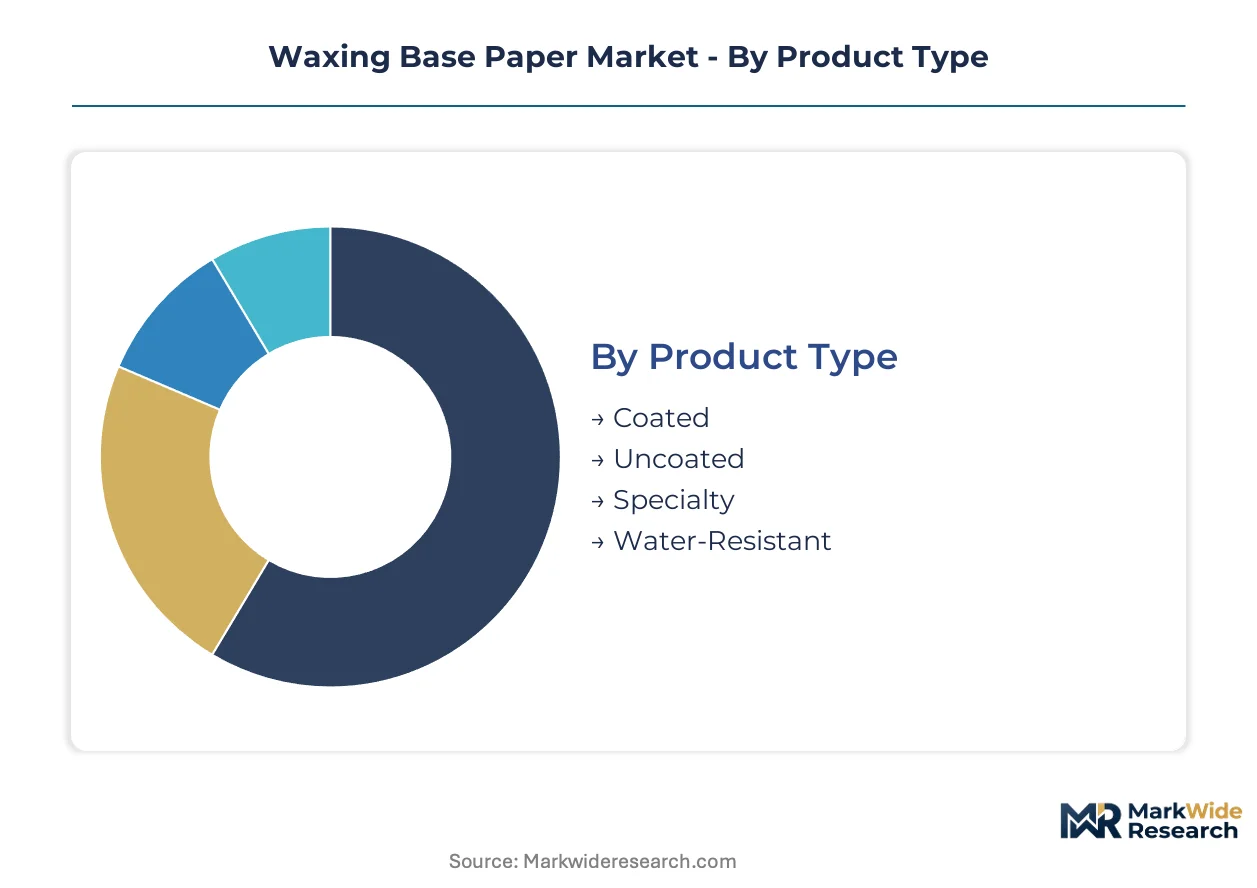
Waxing base paper segmentation reflects divergent technical requirements across barrier performance tiers and end-use specifications. Coating chemistry, substrate weight, and surface engineering create distinct procurement channels with limited substitutability between grades.
Product Type:
Mature paraffin-saturated grades dominate volume, while emerging aqueous and biodegradable alternatives reshape premium positioning.
- Coated:Saturated or surface-treated substrates carrying 15–40% wax loading by weight achieve moisture and grease resistance through hot-dip or curtain coating processes. Frozen food packaging converters in Germany and France are accelerating PFAS-free reformulation programs, pulling demand toward certified compostable coated stocks.
- Uncoated:Basic kraft or sulfite substrates without barrier treatment retain cost leadership in industrial wrapping where moisture protection requirements remain minimal. Bakery and confectionery clusters specify uncoated grades for short-cycle domestic consumption where grease migration risks stay contained.
- Specialty:Custom-engineered release properties serve adhesive tape and precision label stock markets demanding controlled delamination behavior.
- Water-Resistant:Hybrid synthetic-polymer barriers command premium positioning in dairy and frozen food applications requiring sub-zero durability.
Coated grades retain volume leadership; water-resistant formulations hold the steepest expansion curve.
End Use Industry:
Application-driven procurement separates food-contact compliance investments from industrial cost optimization.
- Food Packaging:Grease-resistant grades face REACH restrictions on perfluoroalkyl substances and FDA food-contact substance notification requirements. German bakery and confectionery packaging clusters concentrate specification authority, driving specialized waxing base paper procurement with dual-source qualification mandates.
- Industrial Applications:Basic moisture barriers serve machinery wrapping and corrosion protection where substrate purity thresholds remain relaxed. Paraffin price volatility creates margin compression for converters locked into long-term coating contracts.
- Consumer Goods:Premium presentation layers demand controlled surface aesthetics and consistent barrier performance.
- Printing:Smooth, dimensionally stable substrates enable high-fidelity graphic reproduction on specialty packaging.
Food packaging commands specification authority; industrial applications anchor baseline volume throughput.
Thickness:
Weight-class segmentation aligns equipment compatibility with barrier loading capacity across coating lines.
- Lightweight:Sub-40 gsm substrates enable material efficiency in single-use food wrapping and flexible pouch constructions. Japanese quick-service packaging buyers pilot these grades for regulatory compliance with positive list requirements.
- Standard:40–60 gsm specifications balance runnability on high-speed converting equipment with adequate wax absorption capacity.
- Heavyweight:60–80 gsm stocks support structural integrity in frozen food cartons and industrial protective wraps.
- Ultra-Heavyweight:Above-80 gsm grades serve heavy-duty corrosion inhibition and multi-layer barrier assemblies.
Standard weights dominate converter equipment compatibility; lightweight grades are gaining share fastest in regulatory-sensitive food applications.
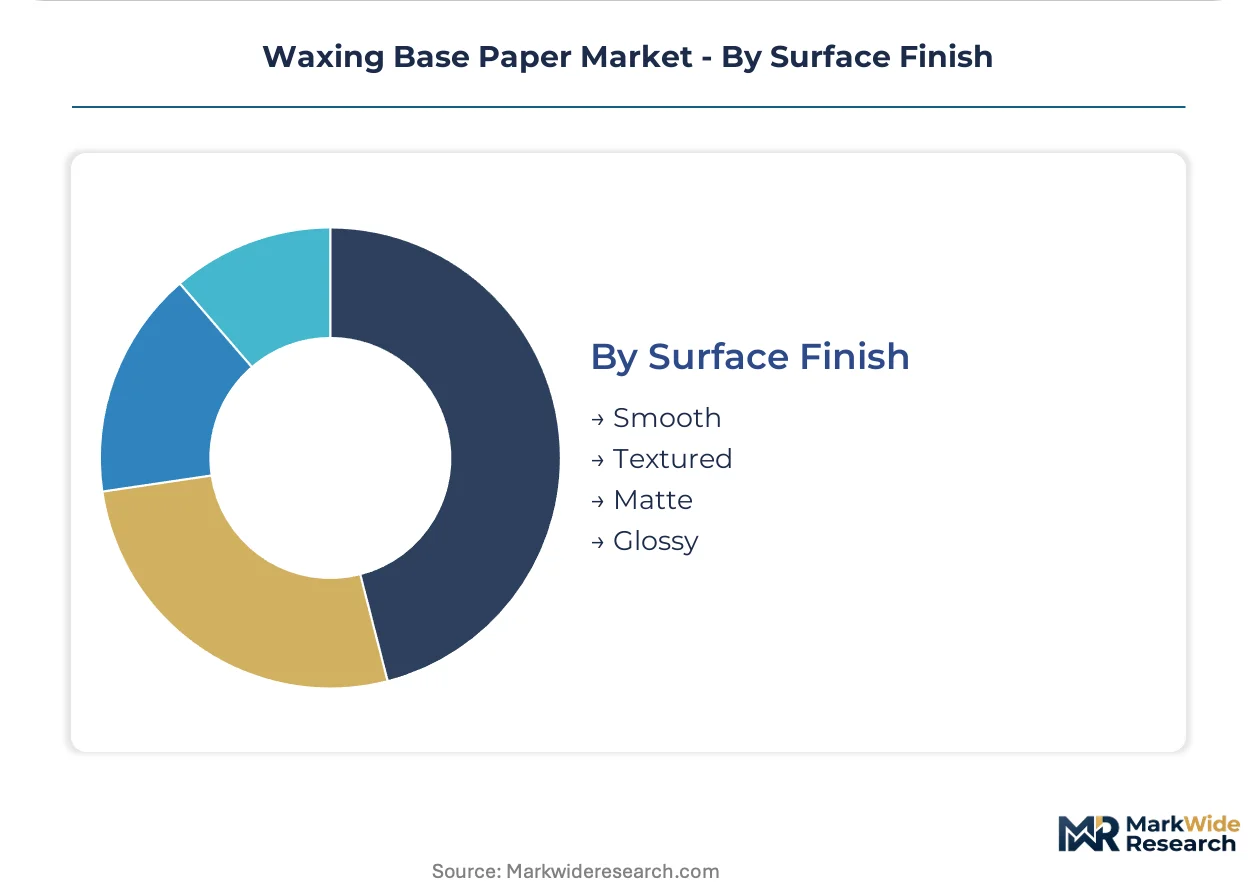
Surface Finish:
Finish engineering separates functional release properties from aesthetic presentation requirements.
- Smooth:Calendered surfaces enable precise coating weight control and consistent barrier film formation. Adhesive tape manufacturers specify smooth finishes for uniform pressure-sensitive adhesive transfer.
- Textured:Embossed patterns enhance grip and visual differentiation in consumer-facing packaging.
- Matte:Low-gloss surfaces reduce glare and support premium food presentation aesthetics.
- Glossy:High-sheen finishes serve gift wrap and promotional packaging requiring visual impact.
Smooth finishes retain technical specification dominance; matte surfaces climb fastest in premium food positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish integrated pulp producers supply waxing base paper substrates to German food packaging converters facing REACH compliance deadlines. This trade corridor concentrates procurement power among Nordic suppliers while compressing delivery timelines for PFAS-free grade qualification.
Germany
Bakery and confectionery packaging clusters in Baden-Württemberg and Bavaria drive specialized waxing base paper procurement with grease-resistant specifications. ECHA REACH restrictions on perfluoroalkyl substances force converters in Stuttgart and Munich to dual-source PFAS-free barrier chemistries ahead of 2026 disqualification deadlines.
United States
Frozen food packaging converters in the Midwest and Southeast specify water-resistant waxing base paper grades for sub-zero durability requirements. FDA food-contact substance notifications govern which wax formulations converters may deploy, with Chicago and Atlanta procurement offices auditing supplier compliance documentation quarterly.
Japan
Quick-service packaging buyers in Tokyo and Osaka pilot lightweight waxing base paper grades below 40 gsm for material efficiency gains. METI and the Ministry of Health, Labour and Welfare maintain positive list requirements for food-contact paper that limit imported substrate options, creating compliance barriers for non-domestic suppliers.
China
Industrial wrapping applications in the Yangtze River Delta and Pearl River Delta absorb uncoated waxing base paper volumes where basic moisture protection suffices. GB standards for food-contact materials are tightening substrate purity thresholds, forcing Shandong and Jiangsu converters to upgrade coating line specifications.
France
Dairy packaging converters in Île-de-France and Auvergne-Rhône-Alpes specify hybrid synthetic-polymer barriers for premium frozen food positioning. EU REACH alignment with EFSA guidance on mineral oil saturated hydrocarbons threatens post-consumer recycled fiber content in waxing base paper grades, pressuring Lyon and Paris procurement teams to validate virgin fiber sourcing.
Waxing Base Paper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated Nordic pulp producers anchor premium positioning through certified compostable base stock availability, while regional coating specialists defend volume share in industrial wrapping segments. Three archetypes dominate: integrated substrate-coating platforms, standalone base paper manufacturers, and toll coating service providers. Strategic moves concentrate on PFAS-free formulation partnerships and hot-dip saturation equipment upgrades enabling precise wax loading control.
Among Nordic integrated producers, Stora Enso Oyj and UPM exemplify the substrate-coating platform archetype with captive pulp supply chains. Ahlstrom-Munksjö occupies a specialist position serving medical and food-grade segments requiring controlled porosity specifications. Georgia-Pacific LLC anchors North American volume throughput through broad kraft paper infrastructure. These three companies represent distinct competitive vectors: Nordic sustainability certification, specialty paper engineering, and continental scale manufacturing.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| International Paper |
| Ahlstrom-Munksjö |
| Twin Rivers Paper Company |
| KRPA Holding CZ |
| Georgia-Pacific LLC |
| Oji Holdings Corporation |
| UPM |
| Sappi Europe |
| Others |
Value Network & Pricing Analysis
Nordic pulp integration in Finland and Sweden concentrates certified compostable base stock availability, pushing margin pools downstream toward converters with dual-source qualification capabilities and PFAS-free formulation partnerships. This upstream concentration lets integrated producers capture premium positioning while regional coating specialists compete on volume throughput in industrial wrapping segments.
Pricing Analysis
Legacy paraffin-saturated formulations, aqueous barrier alternatives, and next-generation biodegradable coatings occupy distinct price tiers. Three-tier pricing structure across premium, standard, and economy levels separates water-resistant hybrid polymers from basic uncoated krafts. Price differentiation centers on compostability certification grade and REACH compliance documentation depth. Cost compression in paraffin-based tiers is intensifying because petroleum feedstock volatility exposes converters locked into long-term coating contracts. Industrial wrapping buyers show highest price sensitivity, while frozen food packaging converters prioritize barrier performance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Nordic integrated producers supplying German food packaging clusters. Geographic supply concentration rests on Finland, Sweden, and Germany for certified compostable base stocks, with North American volume anchored in Georgia-Pacific's kraft paper infrastructure. Raw material dependencies draw from Nordic softwood pulp, petroleum-derived paraffin, and bio-based wax feedstocks. Single-source vulnerability around PFAS-free coating chemistry creates bottleneck risk for converters seeking rapid reformulation. Distribution runs through direct mill relationships for large converters and regional paper distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, ECHA REACH, and Japan's positive list requirements creates niche opportunities for compliance-specialized suppliers. This demand-side shift rewards players who can certify simultaneously across multiple jurisdictions rather than optimize for single-market access.
For Market Incumbents: Entrench PFAS-free barrier chemistry leadership through captive Nordic pulp supply chains and accelerated hot-dip saturation equipment upgrades. Dual-source qualification mandates from German bakery and confectionery clusters threaten volume concentration for single-source suppliers. Backward integration into aqueous polymer formulation capabilities defends margin position against specialty chemical entrants.
For New Entrants and Emerging Players: Build out toll coating service capabilities targeting mid-tier converters lacking capex for curtain coating line retooling. Japan's positive list requirements create the most penetrable white space for compliant domestic and regional suppliers. Lead with regulatory documentation services bundled with substrate supply to differentiate from commodity base paper traders.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional coating specialists holding established industrial wrapping relationships but lacking food-contact certification infrastructure. Five-to-ten year viability hinges on successful PFAS transition execution rather than legacy paraffin volume preservation. Watch for compostability certification timeline compression as an inflection indicator for premium grade margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Partnership | ECHA REACH deadlines in Germany and France force converter qualification of alternative barrier chemistries by 2026. |
| Hot-Dip Saturation Equipment Upgrade | Precise wax loading control enables 15-40% weight consistency for frozen food barrier performance specifications. |
| Compostability Certification Investment | Third-party validation for industrial and home compostable claims extends product development cycles but captures premium positioning. |
| Dual-Source Qualification Program | German bakery and confectionery clusters mandate redundant supplier relationships to mitigate PFAS transition disruption risk. |
| Curtain Coating Line Retooling | Sub-20 gsm aqueous deposition capability opens technical pathways for dairy and frozen food premium applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across trade and regulatory sources. Conversations with coating line operators, food packaging procurement managers, pulp supply chain directors, and regulatory compliance officers captured operational dynamics. Secondary sources included ECHA REACH substance restriction databases, FDA food-contact substance notifications, Japan's Ministry of Health positive list documentation, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across coating chemistry segments.
Forecast inputs considered coating technology migration rates, regulatory disqualification timelines, and converter equipment replacement cycles across the analysis window. Segmentation dimensions modeled include product type tiers, end-use industry specifications, substrate weight classes, and surface finish engineering. CAGRs derived from weighted average of historical trajectory and structural shift intensity. Industry-specific inputs incorporated paraffin price volatility assumptions and compostability certification adoption curves.
Practitioners should monitor ECHA restriction threshold revisions and mineral oil saturated hydrocarbon limit evolution for early signals of recycled fiber content disqualification. Forecasts reflect assumptions about regulatory implementation pace and converter capex deployment timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Paperboard Tray Market