
 Medical Packaging Paper Market | 2026-2036
Medical Packaging Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Packaging Paper Market Foresight
Polypropylene in medical pouches is hardening cost pressures on traditional paper substrates, particularly in high-moisture sterilization cycles. Billerud sustains Nordic pulp-to-paper integration that secures virgin fiber supply for pharmaceutical-grade kraft. Ahlstrom specializes in breathable barrier papers that meet steam and ethylene oxide sterilization protocols. Zhejiang Kaifeng New Material competes on coated paper formats for emerging Asian device manufacturers.
Medical packaging paper denotes sterilization-grade substrates engineered with controlled porosity, wet strength additives, and fiber purity levels that withstand steam, gamma, or ethylene oxide exposure without particulate shedding. Grammage typically ranges from 40 to 80 g/m², with porosity calibrated to permit sterilant penetration while blocking microbial ingress. Surgical wraps and pouches command the dominant share of product-type demand, as these formats face direct contact with Class II and III devices requiring validated sterile barriers. Composite material laminates represent the fastest-growing segment, combining paper substrates with polymer films to meet dual requirements for breathability and moisture resistance in extended shelf-life applications.
FDA sterilization validation guidelines and EU MDR technical documentation requirements compel manufacturers to demonstrate fiber stability and endotoxin limits across batch records. ISO 11607 standards for sterile barrier systems further constrain material selection, creating compliance moats for certified suppliers. REACH and RoHS frameworks in Europe restrict chemical additives in paper coatings, pushing reformulation toward bio-based wet-strength agents. Stakeholders must monitor evolving EPA and EMA guidance on per- and polyfluoroalkyl substance restrictions, as fluorinated coatings in grease-resistant medical papers face prospective phase-out timelines that will force material transitions and supplier requalification cycles.
Market Dynamics
Sterilization validation protocols from FDA and EU MDR are compressing supplier qualification timelines while hospitals accelerate sterile barrier procurement to match surgical volume normalization. Paper substrate manufacturers face simultaneous pressure to demonstrate fiber stability under gamma, steam, and ethylene oxide exposure without particulate shedding.
Growth Catalysts
- Surgical volume recovery:Hospital systems in Germany and the United States are expanding sterile packaging procurement to replenish depleted surgical wrap inventories and support backlog clearance in orthopedic and cardiovascular procedures.
- EU MDR technical documentation mandates:The Medical Device Regulation compels device manufacturers to source certified sterile barrier materials with validated batch records, creating compliance pull-through for qualified paper suppliers.
- Ethylene oxide sterilization persistence:Despite gamma and steam alternatives, ethylene oxide remains dominant for moisture-sensitive devices, sustaining demand for breathable barrier papers calibrated to specific porosity ranges.
Market Restraints
- Bleached softwood pulp cost volatility:Virgin fiber inputs for pharmaceutical-grade kraft face pricing pressure from competing tissue and specialty paper demand, squeezing margin structures for non-integrated converters.
- Polymer film substitution:Polypropylene laminates in high-moisture sterilization cycles are hardening competitive pressure on traditional paper substrates in extended shelf-life applications.
- REACH chemical additive restrictions:European frameworks constrain wet-strength agent formulations, forcing reformulation cycles that extend qualification timelines for existing product lines.
Strategic Opportunities
- Composite material laminates:Paper-polymer hybrid formats represent white space for shelf-life extension in implantable device packaging, combining breathability with moisture resistance.
- India medical device manufacturing clusters:CDSCO regulatory alignment with ISO 11607 creates entry pathways for certified suppliers as domestic device production scales under PLI scheme incentives.
- PFAS-free coating transitions:Prospective EPA and EMA phase-out timelines for fluorinated grease-resistant papers force material transitions that first-mover suppliers can capture through early qualification.
Industry Challenges
- ISO 11607-1 sterile barrier system certification:Validation protocols require extensive accelerated aging studies and seal strength documentation, extending time-to-revenue for new product introductions by 18-24 months.
- Endotoxin testing capacity constraints:Fiber purity verification at sub-0.5 EU/g limits demands specialized laboratory infrastructure that smaller converters struggle to maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Packaging Paper Market |
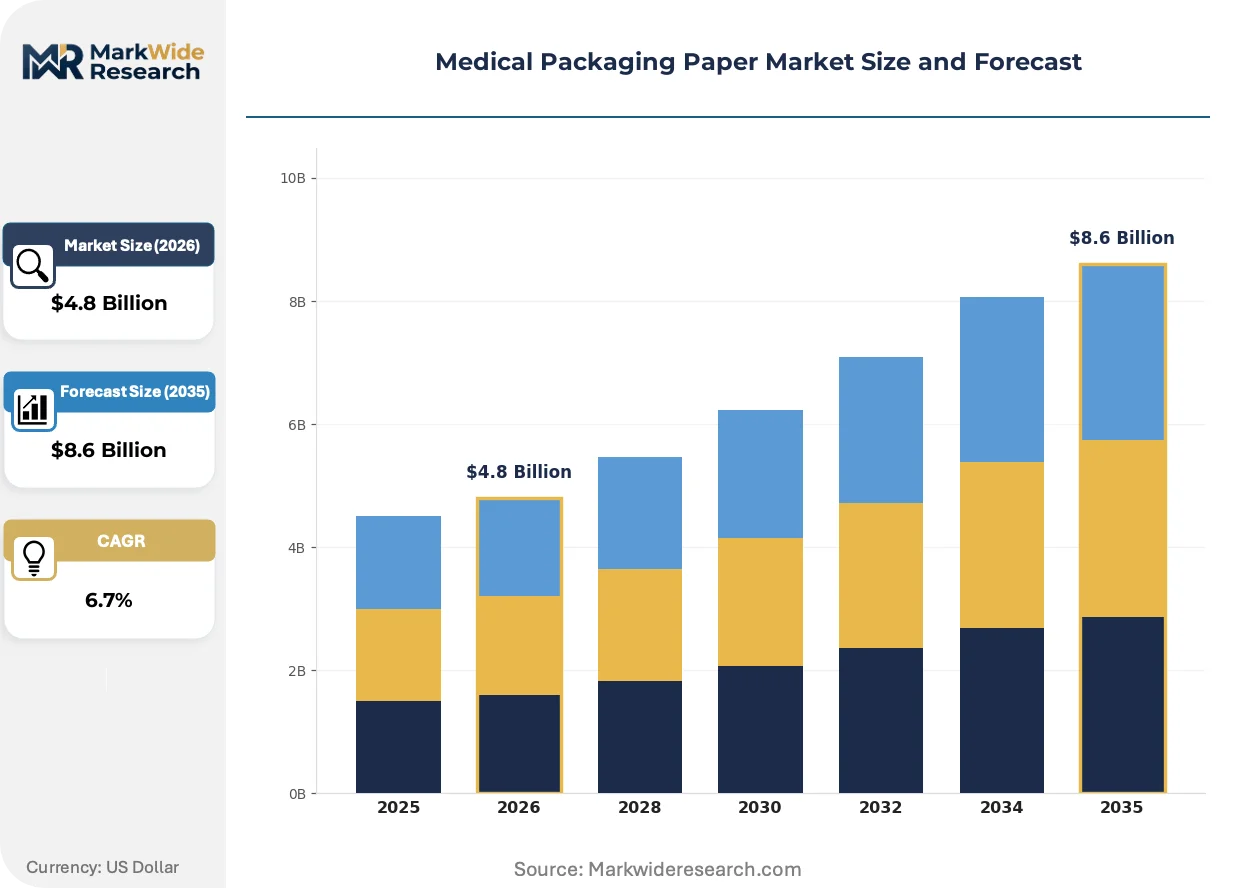
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Wraps, Pouches, Sheets, Bags Material: Paper, Plastic, Composite, Non-woven End User: Hospitals, Clinics, Laboratories, Pharmaceutical Companies Packaging Type: Rolls, Flat Sheets, Custom Shapes, Secondary Packaging |
| Companies Covered | Sterimed, Billerud, Monadnock Paper Mill, Mativ, Pelta Medical Papers, Ahlstrom, Xianhe, Zhejiang Kaifeng New Material, Zhejiang Hengda New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Packaging Paper Market Shifts & Advancements
Material science convergence and regulatory chemistry restrictions are forcing simultaneous innovation in substrate engineering and coating formulations. Suppliers must solve for sterilant permeability, moisture resistance, and biocompatibility within tightening additive constraints.
Biodegradable polymer coatings are absorbing moisture barrier functions previously served by fluorinated chemistries in steam sterilization applications. German device manufacturers are piloting these formats for orthopedic implant pouches where extended shelf life meets sustainability procurement criteria. The structural consequence is compressing traditional grease-resistant paper volumes while expanding qualified supplier lists for bio-based alternatives.
REACH and RoHS frameworks in Europe are restricting chemical additives in paper coatings, pushing reformulation toward bio-based wet-strength agents derived from chitosan or modified starches. This industrial consequence extends qualification timelines as manufacturers resubmit technical documentation for modified formulations. Steam sterilization pouches for Class III devices face the most acute reformulation pressure, with suppliers in Sweden and Finland advancing pilot-scale production of compliant alternatives.
Hospital procurement departments are consolidating sterile barrier suppliers to reduce qualification overhead and secure volume pricing through multi-year agreements. Group purchasing organizations in the United States are displacing spot-market purchasing for surgical wraps and pouches, concentrating contract awards among ISO 11607-certified manufacturers with demonstrated batch consistency. This consolidation is most visible in cardiovascular and neurosurgical device sterilization, where supply assurance outweighs unit cost minimization in vendor selection criteria.
Medical Packaging Paper Market Segmentation
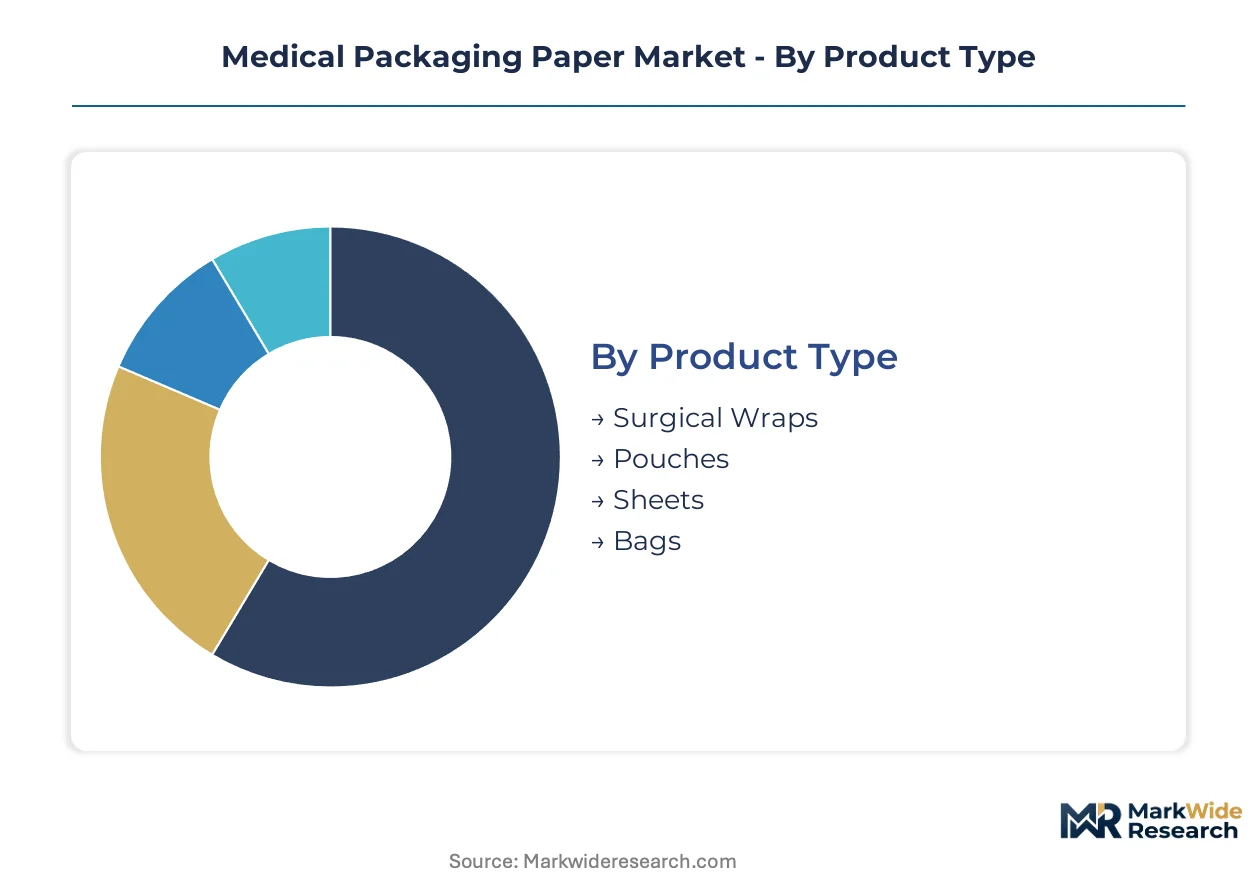
Segmentation in medical packaging paper reflects divergent sterilization protocols, device sensitivity thresholds, and procurement scale economies. Material selection and format specifications vary sharply between high-volume surgical departments and specialized implant manufacturers.
Product Type:
Hospital procurement teams prioritize format flexibility against sterilization method compatibility and inventory turnover velocity.
- Surgical Wraps:These large-format substrates, typically 40-60 g/m² with calibrated porosity for steam and ethylene oxide penetration, dominate sterile processing department consumption. German hospital systems and US academic medical centers drive volume through centralized sterilization facilities handling orthopedic and cardiovascular instrument trays.
- Pouches:Pre-formed or heat-sealable formats with self-seal adhesive strips serve individual device packaging for implantables and single-use instruments. Demand concentrates among cardiovascular and neurosurgical device manufacturers in Germany and the United States where FDA and EU MDR validation requirements favor qualified barrier systems with documented seal strength.
- Sheets:Flat-cut substrates for custom folding applications in smaller surgical centers and specialty clinics.
- Bags:Gusseted or lay-flat configurations for bulk instrument sets and procedural kits.
Surgical wraps lead on scale; pouches lead on momentum as device manufacturers shift toward pre-validated sterile barrier systems.
Material:
Raw material selection hinges on moisture resistance requirements, sterilization modality, and regulatory compliance cost structures.
- Paper:Virgin kraft and sulfate pulp substrates with wet-strength additives remain the cost baseline for steam and ethylene oxide cycles. REACH chemical restrictions in Europe and prospective EPA PFAS phase-outs are forcing reformulation toward bio-based wet-strength agents, extending qualification timelines for Swedish and Finnish suppliers.
- Plastic:Polypropylene and polyethylene films absorb moisture barrier functions in high-humidity sterilization environments. German device manufacturers pilot these formats for extended shelf-life orthopedic implants where moisture resistance outweighs breathability requirements.
- Composite:Paper-polymer laminates combine sterilant permeability with moisture protection. These hybrid formats are expanding most quickly in implantable device packaging where dual requirements for breathability and shelf-life extension create specification premiums.
- Non-woven:Spunbond-meltblown-spunbond polypropylene alternatives compete in heavy-duty surgical wrap applications requiring tear resistance beyond paper limits.
Paper leads on installed base; composite formats lead on specification value as device shelf-life requirements extend.
End User:
Procurement scale and validation burden separate institutional buyers from specialized manufacturing customers.
- Hospitals:Health systems with centralized sterile processing departments drive roll-format surgical wrap consumption. US group purchasing organizations and German hospital procurement alliances concentrate contract awards among ISO 11607-certified suppliers with demonstrated batch consistency.
- Clinics:Ambulatory surgical centers and specialty practices favor pre-formed pouches and smaller-format sheets.
- Laboratories:Diagnostic and research facilities require low-particulate substrates for sterile media and reagent packaging.
- Pharmaceutical Companies:Drug-device combination products and biologic packaging demand the highest fiber purity grades with endotoxin limits below 0.5 EU/g.
Hospitals lead on volume throughput; pharmaceutical companies lead on margin extraction through purity-grade premiums.
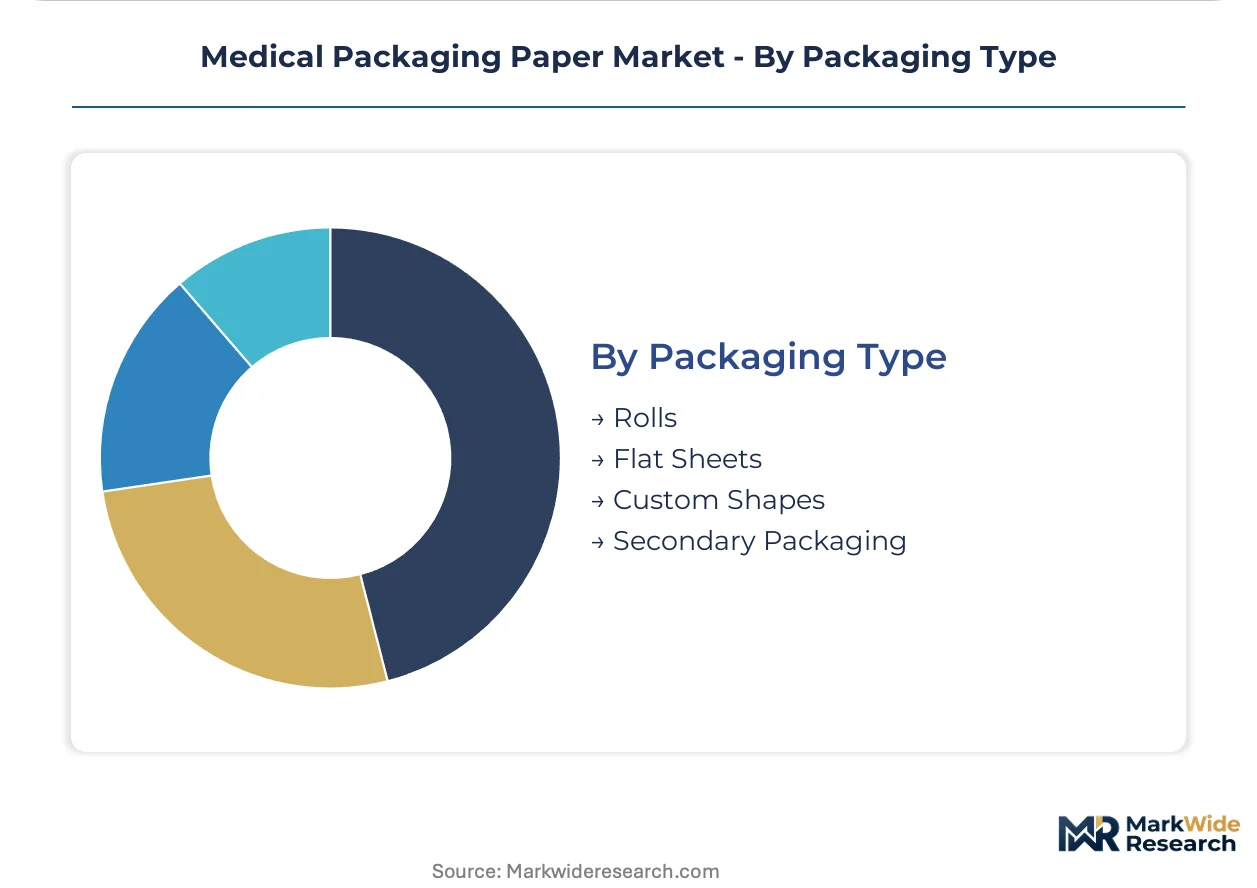
Packaging Type:
Format configuration determines converter equipment investment and logistics efficiency across the supply chain.
- Rolls:Continuous web formats maximize converter yield and support just-in-time cutting operations for high-volume surgical wrap production.
- Flat Sheets:Pre-cut dimensions reduce downstream processing for mid-size sterile processing departments.
- Custom Shapes:Die-cut or laser-processed formats serve irregular device geometries and robotic surgical instrument sets.
- Secondary Packaging:Outer cartons, labels, and sterilization indicators complete sterile barrier systems for regulatory submission.
Rolls lead on manufacturing efficiency; custom shapes lead on differentiation value for complex device geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German advanced sterilization infrastructure and medical device manufacturing clusters anchor premium-grade medical packaging paper consumption across the analysis window.
United States
Academic medical centers and group purchasing organizations drive surgical wrap procurement as surgical volumes normalize. FDA sterilization validation guidelines compel device manufacturers to maintain validated batch records for sterile barrier materials. The Greater Boston and Minneapolis-St. Paul corridors concentrate orthopedic and cardiovascular device manufacturing, sustaining demand for ISO 11607-certified paper substrates.
Germany
Hospital procurement alliances expand sterile packaging inventories to support backlog clearance in elective procedures. EU MDR technical documentation mandates create compliance pull-through for qualified suppliers with demonstrated fiber stability. The Baden-Württemberg and Bavaria regions host dense clusters of implantable device manufacturers piloting composite paper-polymer laminates for extended shelf-life applications.
China
Domestic device manufacturers scale production under NMPA regulatory alignment with international sterile barrier standards. GB standards for medical packaging materials are tightening fiber purity and endotoxin limit requirements. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate coated paper converters serving emerging medical device exporters.
India
CDSCO regulatory harmonization with ISO 11607 creates entry pathways for certified suppliers as domestic device production accelerates. PLI scheme incentives attract medical device manufacturing investment, expanding sterile packaging demand. The Maharashtra and Karnataka industrial corridors host sterilization service providers and contract manufacturers requiring qualified barrier materials.
Sweden
Nordic pulp-to-paper integration secures virgin fiber supply for pharmaceutical-grade kraft amid REACH chemical additive restrictions. Bio-based wet-strength agent reformulation extends qualification timelines for steam sterilization pouch suppliers. The Värmland and Norrland forest product regions sustain specialty paper production for export to German and US device manufacturers.
Medical Packaging Paper Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated pulp producers and specialty paper converters respond to EU MDR and FDA validation requirements. The vendor base separates into three tiers: Nordic integrated producers with captive fiber supply, European specialty converters with sterilization protocol expertise, and Asian coated paper specialists serving cost-sensitive device manufacturers. Strategic archetypes include backward-integrated pulp producers, barrier technology specialists, and regional coating converters. M&A activity and geographic expansion represent the dominant competitive moves as suppliers seek ISO 11607 certification breadth.
Among Nordic integrated producers, Billerud exemplifies the captive fiber supply archetype through sustained pulp-to-paper integration. Ahlstrom occupies a position within the breathable barrier technology tier, representing specialization in steam and ethylene oxide sterilization protocols. Zhejiang Kaifeng New Material anchors the Asian coated paper segment, exemplifying regional competition on format flexibility for emerging device manufacturers.
| Leading Market Players |
|---|
| Sterimed |
| Billerud |
| Monadnock Paper Mill |
| Mativ |
| Pelta Medical Papers |
| Ahlstrom |
| Xianhe |
| Zhejiang Kaifeng New Material |
| Zhejiang Hengda New Material |
| Others |
Supply & Pricing Matrix
Bleached softwood pulp futures on the NBSK index cascade through converter cost structures into three distinct pricing tiers for pharmaceutical-grade kraft, with integrated Nordic producers capturing margin premiums while Asian coating specialists compete on format flexibility for emerging device manufacturers.
Pricing Analysis
Input-cost pass-through from virgin fiber markets stratifies pricing across premium, standard, and economy tiers. ISO 11607-certified suppliers with validated batch records command premium positioning against uncertified converters. Cost compression in standard-grade surgical wraps intensifies as polypropylene laminates displace paper substrates in extended shelf-life applications. Hospital procurement departments exhibit lowest price sensitivity in cardiovascular and neurosurgical segments where supply assurance dominates vendor selection.
Supply Chain Analysis
Freight cost differentials between Nordic pulp producers and Asian coating converters shape competitive positioning across Atlantic and Pacific trade lanes. Manufacturing gravity centers on Sweden, Finland, and Germany for virgin fiber kraft, while China and India host downstream coating and converting operations. Raw material dependencies span NBSK pulp, bio-based wet-strength agents, and polymer film laminates. Single-source vulnerability concentrates in pharmaceutical-grade fiber supply from Värmland and Norrland forest regions. Distribution runs through GPO contracts in the United States and hospital procurement alliances in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in composite laminate formats and PFAS-free coating transitions, with bio-based wet-strength agent reformulation enabling premium-tier positioning ahead of regulatory phase-out timelines.
For Market Incumbents: Acquire sterilization validation infrastructure to compress 18-24 month ISO 11607-1 certification timelines. Secure captive pulp supply through Nordic forest asset purchases before REACH additive restrictions tighten. Polypropylene substitution in high-moisture cycles threatens traditional kraft volumes; respond with paper-polymer hybrid capacity in Baden-Württemberg device manufacturing clusters. For New Entrants and Emerging Players: Begin with CDSCO-aligned ISO 11607 certification to access Maharashtra and Karnataka sterilization service providers under India's PLI scheme. Target pharmaceutical company segment for endotoxin-grade purity premiums above 0.5 EU/g thresholds. Pursue coating specialization for Class III implantable device pouches where dual breathability-moisture requirements create specification moats. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic integrated producers possessing captive fiber supply and bio-based wet-strength agent pilot capacity. Long-term viability hinges on EPA and EMA PFAS phase-out execution timelines. Monitor CDSCO regulatory harmonization progress as inflection signal for Indian manufacturing cluster expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Transition | EMA and EPA phase-out timelines force material requalification cycles that first-movers capture. |
| Composite Laminate Capacity Expansion | Paper-polymer hybrids meet dual breathability-moisture requirements for implantable orthopedic devices. |
| Backward Integration into Pulp Supply | Nordic forest asset control secures virgin fiber access amid competing tissue and specialty paper demand. |
| ISO 11607-1 Certification Investment | Validated sterile barrier systems create compliance moats against uncertified Asian converters. |
| India Manufacturing Cluster Entry | CDSCO alignment with international standards opens pathways as PLI scheme accelerates domestic device production. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down pulp-to-paper supply tracking forms the analytical core of this study. Primary interviews with sterile processing department managers, GPO contract directors, biomedical engineers, and regulatory affairs leads at device manufacturers were validated against secondary sources including FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and forest product industry trade data. Triangulation between demand-side surgical volume recovery patterns and supply-side capacity expansion announcements ensures cross-verified output integrity.
Historical trendline analysis across surgical wrap and pouch consumption volumes established baseline growth patterns over the projection horizon. Segmentation modeling incorporated sterilization modality, device classification tier, material format, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth assumptions across these segments, with specific inputs including orthopedic and cardiovascular procedure backlog clearance rates, EU MDR compliance transition timelines, and ethylene oxide sterilization persistence in moisture-sensitive device categories.
Several conditions sit outside the modeled scope, including unforeseen REACH additive restriction accelerations, abrupt EPA PFAS phase-out timeline revisions, and surgical volume disruptions from pandemic resurgence or healthcare labor shortages. Forecasts reflect assumptions about regulatory harmonization progress and fiber cost stabilization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market