
 Safety Bottle Tote Carriers Packaging Market | 2026-2036
Safety Bottle Tote Carriers Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Bottle Tote Carriers Packaging Market Analytics
North American specialty packaging converters is consolidating around pharmaceutical and laboratory supply chains. Thermo Fisher Scientific leverages its cold-chain infrastructure to dominate temperature-validated tote systems. Eagle Thermoplastic sustains its position through precision-molded plastic carriers designed for corrosive chemical transport. Smurfit Kappa competes with fiber-based composite totes that target sustainability-sensitive institutional buyers.
Safety bottle tote carriers packaging denotes engineered transport enclosures—typically constructed from HDPE, polypropylene, corrugated fiberboard, or aluminum-reinforced composites—designed to secure glass or plastic reagent bottles against impact, thermal excursion, and leakage during handling. These systems incorporate internal retention straps, absorbent liners, and UN-certified cushioning to maintain container integrity across distribution networks. Plastic totes lead unit volumes due to chemical resistance and washability, while composite formats command premium positioning where lightweight strength and recyclability converge. The six-bottle capacity tier is expanding fastest as bulk sample collection and multi-SKU distributor restocking gain traction among clinical laboratories and industrial chemical suppliers.
US FDA Title 21 CFR Part 211 governs container closure systems for pharmaceutical distribution, while OSHA 29 CFR 1910.1200 mandates hazard communication labeling that directly shapes tote carrier marking requirements. The EPA's Resource Conservation and Recovery Act provisions for hazardous waste transport further dictate material specifications and secondary containment features in chemical-handling applications. Stakeholders must monitor evolving state-level extended producer responsibility legislation and pharmaceutical track-and-trace mandates to anticipate redesign cycles and compliance-driven replacement demand.
Market Dynamics
FDA serialization mandates for pharmaceutical distribution are forcing tote carrier redesigns toward tamper-evident architectures, compressing product lifecycles and concentrating converter capabilities around compliance-engineered formats.
Growth Catalysts
- Cold-chain biologics expansion:Temperature-sensitive biosimilar volumes are climbing across United States distribution networks, validating demand for thermal-insulated HDPE totes with phase-change lining systems.
- OSHA 29 CFR 1910.1200:Hazard communication labeling requirements for chemical transport are institutionalizing secondary containment specifications, pulling composite-format totes into industrial laboratory procurement.
- Multi-SKU restocking:Clinical laboratories are consolidating sample collection workflows around six-bottle capacity tiers, driving standardization in distributor replenishment cycles.
Market Restraints
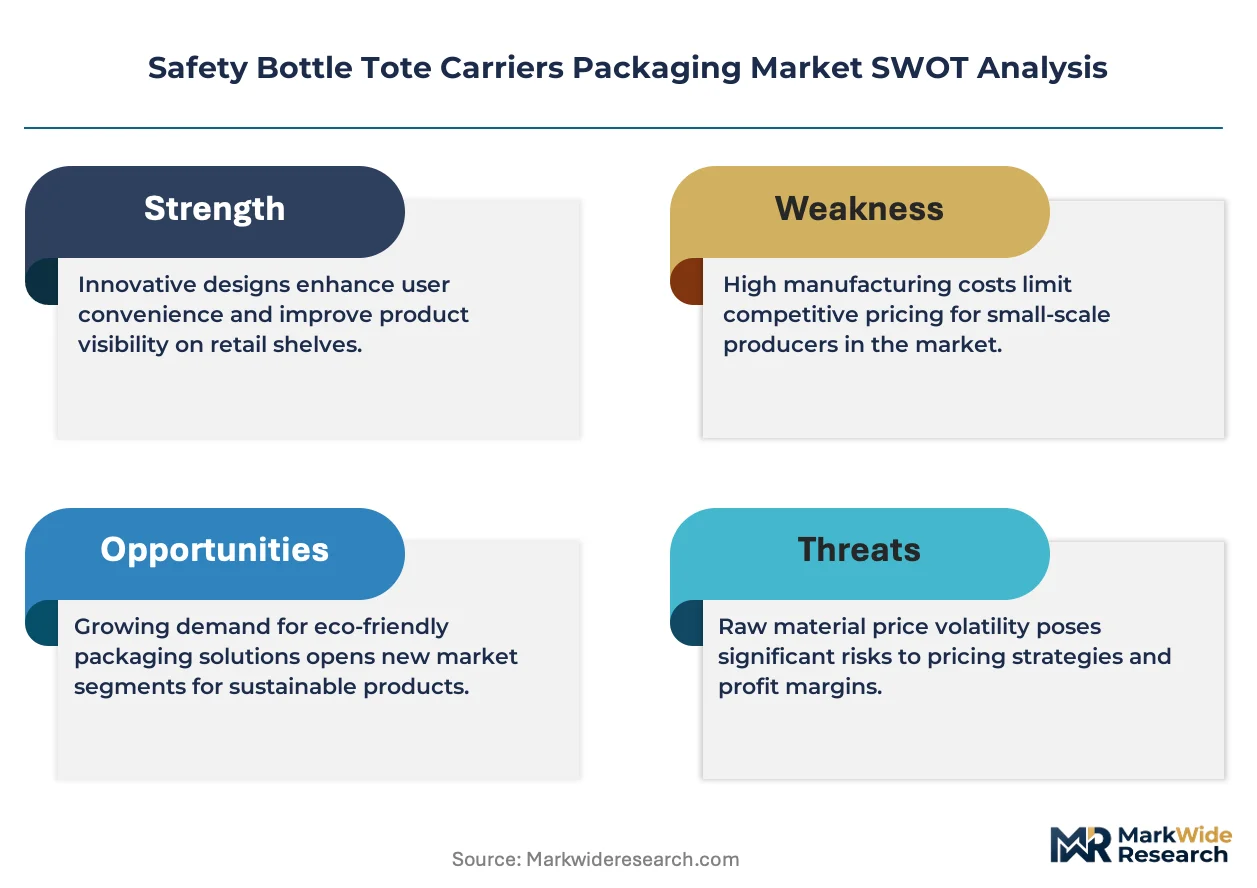
- Resin cost volatility:Polypropylene and HDPE feedstock prices swing with petrochemical cracking margins, squeezing converter margins on long-distributor contracts.
- Aluminum-reinforced composite supply:Lightweight fiberboard-aluminum laminates depend on concentrated European specialty paper mills, exposing buyers to transatlantic freight disruptions.
- UN-certified cushioning lead times:Third-party validation for hazardous material transport adds 8-14 weeks to new product qualification, freezing rapid format innovation.
Strategic Opportunities
- Extended producer responsibility legislation:State-level packaging waste laws in California and New York are creating first-mover advantage for closed-loop recyclable tote programs.
- Cell and gene therapy logistics:Ultra-low temperature cryogenic transport requirements are opening specification space for vacuum-insulated panel totes in biopharma cold chains.
- Direct-to-laboratory e-commerce:Thermo Fisher Scientific and VWR International are building digital procurement platforms that disintermediate distributor inventory holding.
Industry Challenges
- Thermal validation engineering talent:Qualified professionals who can execute ISTA 7E temperature profile testing remain scarce, extending product development timelines.
- Legacy ERP integration:Pharmaceutical distributors running SAP or Oracle systems require custom API development to track serialized tote-level traceability data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Bottle Tote Carriers Packaging Market |
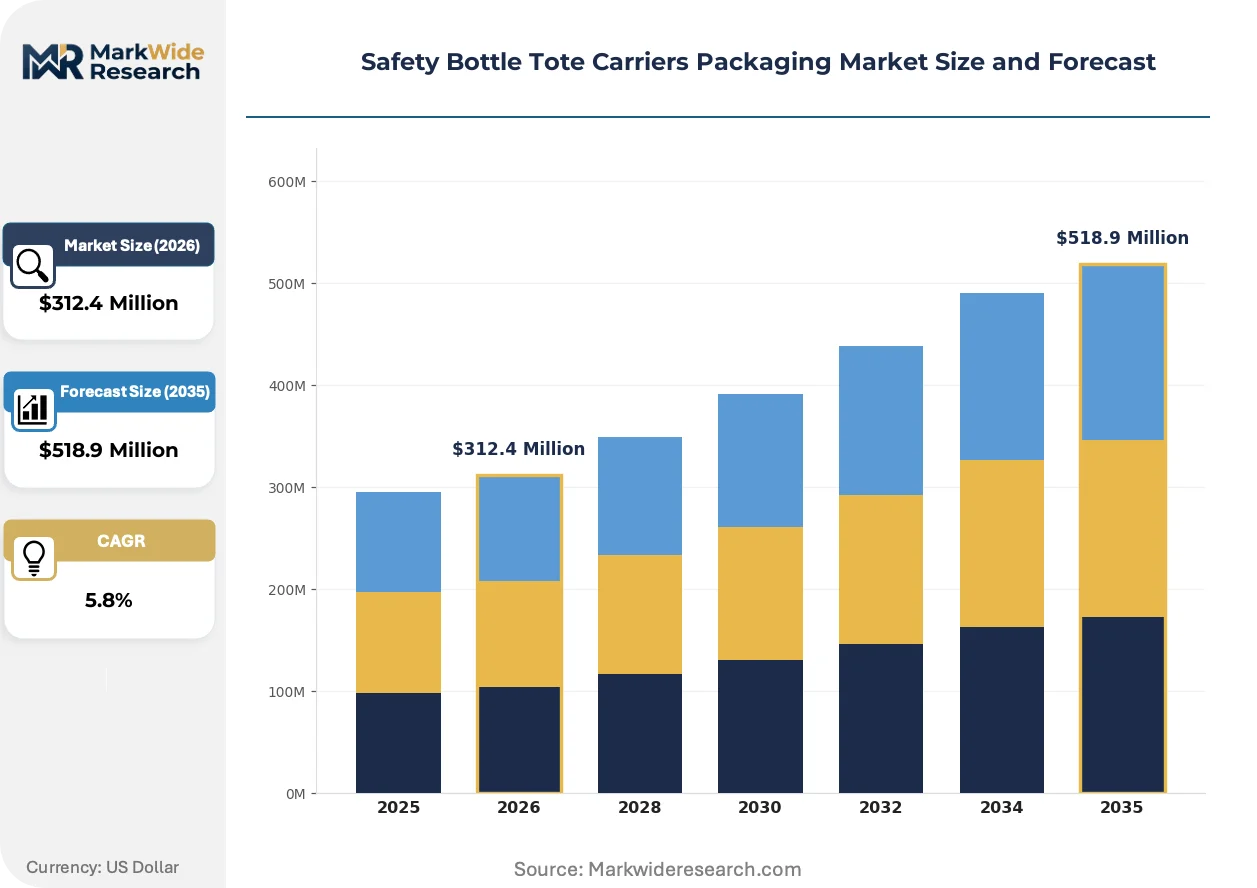
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Fabric, Composite End User: Retailers, Distributors, Consumers, Wholesalers Capacity: 1 Bottle, 2 Bottles, 4 Bottles, 6 Bottles Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Thermo Fisher Scientific, Eagle Thermoplastic, Spectrum Chemical Manufacturing, Merck, ULINE, Qorpak, Smurfit Kappa, Daigger, Heathrow Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Bottle Tote Carriers Packaging Market Evolving Landscape
Material science convergence with digital traceability is compressing the traditional tote carrier value chain, collapsing distinctions between protective packaging and active monitoring systems.
Aluminum-reinforced corrugated composites are consolidating market position in sustainability-sensitive institutional procurement. University laboratory systems and government research facilities are specifying these formats for chemical transport at accelerating rates. The technology is consolidating demand around lightweight strength-to-weight ratios that HDPE cannot match in bulk shipment economics.
REACH Annex XVII restrictions on persistent organic pollutants are tightening material disclosure requirements for European pharmaceutical logistics. Converters serving EU distribution corridors must now document full substance inventories in SCIP database entries. Smurfit Kappa and fiber-based competitors are responding with expanded recycled-content certifications to preempt compliance-driven sourcing switches.
Consolidated distributor purchasing is compressing supplier bases toward single-source tote programs with integrated temperature monitoring. Large clinical laboratory networks are abandoning multi-vendor catalog approaches in favor of enterprise agreements covering bottles, carriers, and data loggers. This pattern is most visible in United States hospital system procurement, where Premier and Vizient group purchasing organizations are driving format standardization.
Safety Bottle Tote Carriers Packaging Market Segmentation
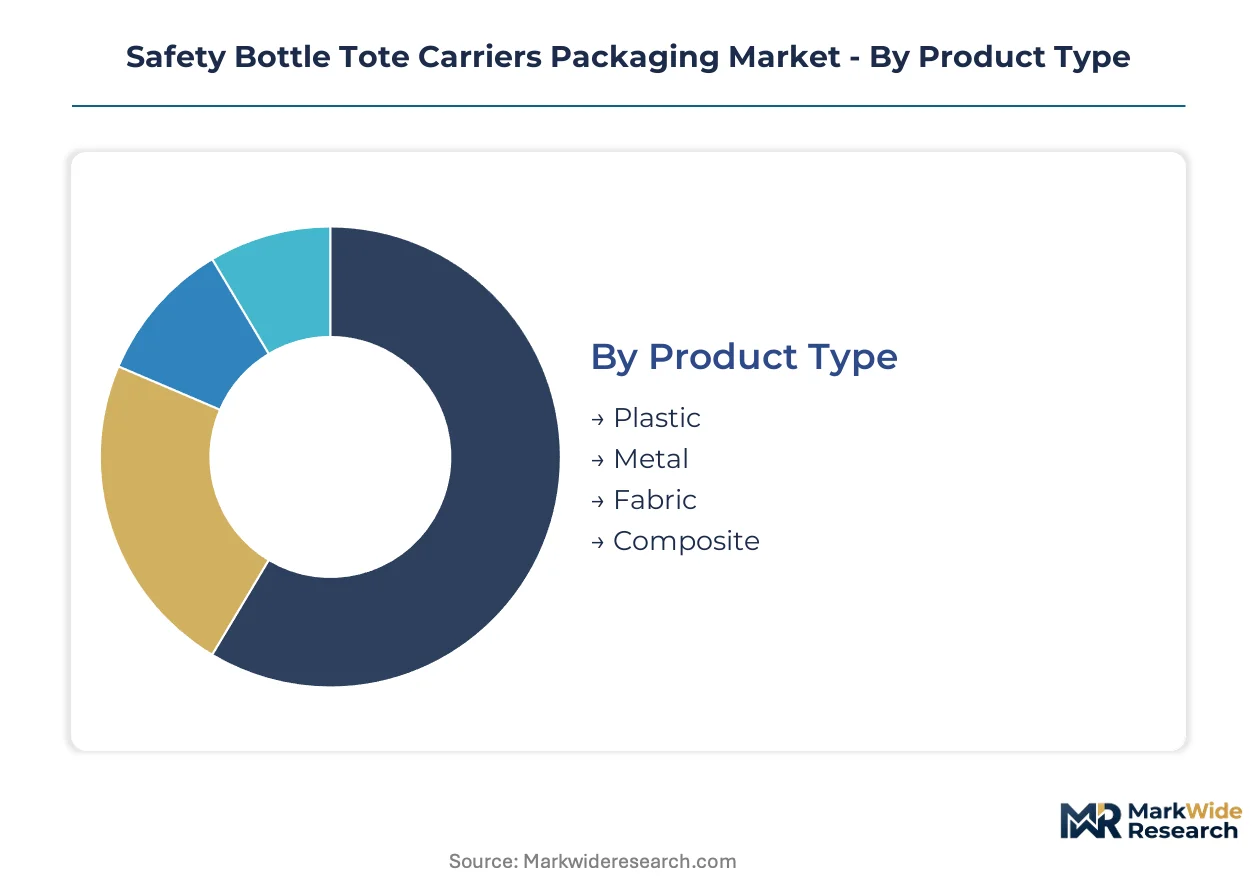
Segmentation in safety bottle tote carriers packaging reveals how material specifications, capacity tiers, and channel economics create distinct competitive battlegrounds. Each dimension governs procurement criteria differently—laboratory buyers prioritize chemical resistance while distributor networks optimize for logistics density.
Product Type:
Supply concentration in resin processing and specialty metal fabrication directly shapes converter margin structures across material categories.
- Plastic:HDPE and polypropylene formulations dominate clinical laboratory procurement due to washability and chemical inertness. United States pharmaceutical distributors specify these for temperature-validated cold-chain biologics transport. Phase-change lining integration is accelerating in this segment.
- Composite:Aluminum-reinforced fiberboard laminates command sustainability-sensitive institutional procurement from university laboratory systems and government research facilities. European specialty paper mill concentration creates supply vulnerability for North American buyers.
- Metal:Stainless steel and aluminum carriers serve corrosive chemical transport with superior impact resistance. Industrial chemical suppliers specify UN-certified metal formats for hazardous material compliance.
- Fabric:Nylon and polyester tote systems target lightweight, collapsible applications in field sampling and temporary transport. Environmental monitoring agencies and mobile laboratory services drive niche demand.
Plastic absorbs the bulk of installed capacity; composite is expanding most quickly.
End User:
Cost tier stratification separates enterprise-scale procurement from fragmented spot purchasing across stakeholder categories.
- Distributors:Pharmaceutical and laboratory supply distributors operate as specification gatekeepers, consolidating multi-SKU tote programs with integrated temperature monitoring. Premier and Vizient group purchasing organizations in the United States drive format standardization through enterprise agreements.
- Retailers:Clinical laboratory networks and hospital systems procure through direct contracts, prioritizing serialized traceability compliance with FDA mandates. SAP and Oracle ERP integration requirements complicate vendor qualification.
- Wholesalers:Industrial chemical suppliers manage bulk replenishment cycles with secondary containment specifications under OSHA 29 CFR 1910.1200 hazard communication rules.
- Consumers:Individual researchers and small laboratory operations purchase through e-commerce platforms, with Thermo Fisher Scientific and VWR International building digital procurement channels that disintermediate inventory holding.
Distributors absorb the bulk of installed capacity; retailers are expanding most quickly.
Capacity:
Volume economics in logistics networks favor specific bottle-count configurations that optimize pallet density and handling efficiency.
- 6 Bottles:The six-bottle tier is gaining share fastest as clinical laboratories consolidate sample collection workflows and distributors streamline multi-SKU restocking cycles. Bulk sample collection protocols in United States hospital systems validate this format.
- 4 Bottles:Mid-range capacity serves routine distributor replenishment and standard laboratory restocking with balanced portability. Industrial chemical suppliers specify this tier for common reagent transport.
- 2 Bottles:Compact dual-bottle carriers target field sampling applications and mobile laboratory services where space constraints dominate.
- 1 Bottle:Single-bottle formats address specialized high-value transport of temperature-sensitive biologics and cryogenic materials in cell and gene therapy logistics.
Four-bottle configurations absorb the bulk of installed capacity; six-bottle tiers show the steepest expansion trajectory.
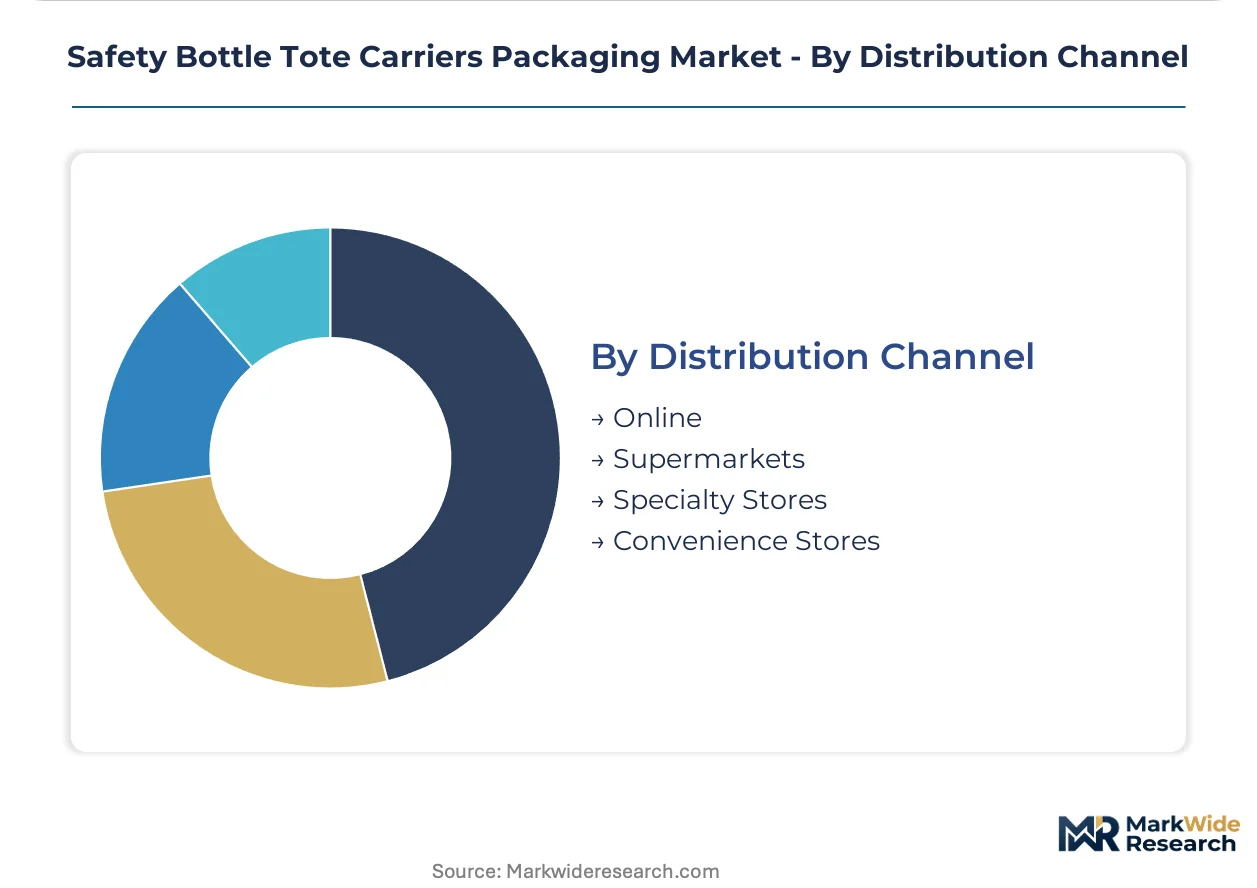
Distribution Channel:
Customer type and procurement urgency differentiate channel performance, with digital platforms reshaping traditional supply relationships.
- Online:Direct-to-laboratory e-commerce is displacing catalog-based procurement as Thermo Fisher Scientific and VWR International invest in digital platforms. Custom API development for ERP integration remains a qualification barrier.
- Specialty Stores:Laboratory supply distributors maintain physical presence for urgent replacement and technical consultation. United States metropolitan clusters concentrate specialty store density.
- Supermarkets:Mass retail channels serve consumer-grade and light industrial applications with limited technical specification support.
- Convenience Stores:Minimal penetration in this market due to lack of temperature validation and compliance certification capabilities.
Specialty stores absorb the bulk of installed capacity; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene and HDPE feedstock availability clusters near Gulf Coast petrochemical corridors anchor regional supply configurations across key pharmaceutical distribution networks.
United States
Cold-chain biologics distribution volumes are climbing fastest through Memphis and Louisville logistics hubs. FDA Title 21 CFR Part 211 serialization mandates are compressing product lifecycles toward tamper-evident tote architectures. The Boston-Cambridge biotech corridor is validating demand for six-bottle capacity tiers in multi-SKU restocking workflows.
Germany
REACH Annex XVII substance disclosure requirements are tightening material documentation for pharmaceutical logistics serving EU distribution corridors. ECHA database entries now govern converter qualification for cross-border chemical transport. The Rhine-Ruhr industrial belt is consolidating procurement around aluminum-reinforced composite formats for sustainability-sensitive institutional buyers.
China
NMPA serialization mandates for pharmaceutical track-and-trace are accelerating domestic converter investment in tamper-evident tote systems. The Yangtze River Delta pharmaceutical manufacturing cluster is expanding cold-chain infrastructure for temperature-sensitive biologics export. Shanghai-based distributors are standardizing on HDPE formats with phase-change lining integration.
India
CDSCO pharmaceutical packaging regulations are aligning with international traceability standards for export-oriented biologics distribution. The Mumbai-Pune pharmaceutical corridor is driving demand for UN-certified cushioning systems in hazardous chemical transport. Gujarat's specialty chemical manufacturing belt is procuring composite-format totes for corrosive reagent handling compliance.
Japan
PMDA quality management standards for pharmaceutical distribution are institutionalizing secondary containment specifications in clinical laboratory supply chains. The Kansai region's precision chemical industry is specifying stainless steel carriers for ultra-high-purity reagent transport. Osaka-based distributors are consolidating around enterprise agreements covering integrated temperature monitoring systems.
Safety Bottle Tote Carriers Packaging Market Competitive Landscape
Global majors compete with regional champions across cold-chain infrastructure and sustainability certification vectors. The market structure concentrates around three capability tiers: integrated laboratory supply conglomerates, specialty packaging converters, and precision-molded plastics fabricators. Strategic moves cluster on M&A-driven cold-chain capability acquisition and geographic expansion through distributor partnership networks.
Within the integrated laboratory supply tier, Thermo Fisher Scientific and Merck exemplify archetypes that leverage captive distribution channels to standardize format specifications across hospital system procurement. Eagle Thermoplastic occupies a position among precision-molded specialists serving corrosive chemical transport requirements. Smurfit Kappa anchors the fiber-based composite segment where sustainability certifications drive institutional purchasing decisions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eagle Thermoplastic |
| Spectrum Chemical Manufacturing |
| Merck |
| ULINE |
| Qorpak |
| Smurfit Kappa |
| Daigger |
| Heathrow Scientific |
| Others |
Value Network & Pricing Analysis
Polypropylene and HDPE resin indices on the US Gulf Coast cascade through converter pricing tiers, compressing margins on long-distributor contracts while forcing tiered pricing stratification across plastic, composite, and metal formats.
Pricing Analysis
Warranty and thermal validation bundling separates premium from standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects UN-certified cushioning inclusion, phase-change lining integration, and ERP API compatibility. Price differentiation hinges on FDA serialization compliance and ISTA 7E validation documentation. Margins are tightening due to resin cost volatility, with pharmaceutical distributors least price-sensitive and small laboratory e-commerce buyers most responsive to spot pricing.
Supply Chain Analysis
Transatlantic freight costs for aluminum-reinforced fiberboard laminates expose North American buyers to European specialty paper mill concentration. Raw material sourcing draws from Gulf Coast petrochemical corridors for HDPE and polypropylene, European mills for composite substrates, and domestic stainless steel fabricators for metal formats. Single-source vulnerability concentrates in UN-certified cushioning validation, which adds qualification lead times. Distribution runs through pharmaceutical and laboratory supply distributors with group purchasing organization consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-engineered formats, with FDA serialization mandates forcing weaker converters out of pharmaceutical qualification pipelines.
For Market Incumbents: Extend cold-chain infrastructure investments into cryogenic vacuum-insulated panel formats for cell and gene therapy logistics. Acquire thermal validation engineering talent to compress ISTA 7E testing timelines. Backward integration into phase-change lining production defends margin position against resin volatility.
For New Entrants and Emerging Players: Group purchasing organization partnerships offer the most penetrable channel for six-bottle capacity tier standardization. Target California and New York extended producer responsibility legislation for closed-loop recyclable tote program launches. Digital procurement platform API development serves as the critical go-to-market differentiator.
For Investors and Strategic Acquirers: The window for entry favors precision-molded plastics fabricators with existing UN certification capabilities. Long-term viability rests on captive cold-chain infrastructure and pharmaceutical distributor relationships. Watch state-level pharmaceutical track-and-trace mandate acceleration as the inflection signal for compliance-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phase-Change Lining Production | Captive supply of thermal materials insulates margins from petrochemical price swings. |
| Acquisition of Thermal Validation Engineering Capabilities | ISTA 7E testing talent scarcity compresses product development timelines for qualified converters. |
| Long-term Supply Agreement with Group Purchasing Organizations | Premier and Vizient enterprise agreements lock in format standardization across hospital systems. |
| Geographic Expansion through Distributor Partnership Networks | Memphis and Louisville logistics hub access validates temperature-controlled distribution reach. |
| Sustainability Repositioning with Recycled-Content Certifications | REACH Annex XVII and state EPR laws preempt compliance-driven sourcing switches. |
Research Methodology
Document review covered FDA Title 21 CFR Part 211 guidance documents, EPA RCRA hazardous waste transport provisions, OSHA 29 CFR 1910.1200 hazard communication standards, and customs trade data, complemented by interviews with pharmaceutical packaging engineers, cold-chain logistics directors, laboratory procurement managers, and specialty packaging converter executives. Secondary validation drew from SEC 10-K filings, pharmaceutical distributor annual reports, and petrochemical feedstock price indices. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing.
Segmentation outputs across material type, capacity tier, end-user category, and distribution channel fed into growth projections throughout the forecast period. CAGRs derived from weighted average of historical shipment trends, regulatory mandate implementation timelines, and cold-chain infrastructure investment patterns. Industry-specific inputs included biosimilar distribution volume trajectories, serialization compliance deadlines, and group purchasing organization contract renewal cycles.
Caveats apply where resin cost volatility, transatlantic freight disruptions, or thermal validation talent scarcity could materially shift the outlook. Forecasts reflect documented assumptions about regulatory implementation pace and distributor consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Hinged Lid Tins Market
Containers
Twist Up Stick Container Market
Containers
Tottle Containers Market
Containers
Laminated Bulk Bins Market
Containers
Steel Containers Market
Containers
Essential Oil Containers Market
Containers
Snap-Lock Container Market
Containers
PET Hinged Containers Market
Containers
Dispensing Jug Market
Containers
Thermoformed Shallow Trays Market
Containers
EPS Container Market
Containers
Child-Resistant Containers Market
Containers
Stack and Nest Containers Market
Containers
Sandwich Containers Market
Containers
Global Food Storage Container Market
Containers
Stock Clamshell Packaging Market