
 Nutraceutical Rigid Packaging Market | 2026-2036
Nutraceutical Rigid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Rigid Packaging Market Analytics
The gap between pharmaceutical-grade and standard nutraceutical packaging is repositioning procurement criteria across the supply chain. Amcor plc leverages its pharmaceutical-certified extrusion capacity to anchor premium vitamin bottle contracts in regulated markets. Berry Global Inc. competes through high-volume HDPE operations that dominate cost-sensitive supplement segments in North America.
Nutraceutical rigid packaging encompasses primary containers engineered from plastics, glass, metals, or composites with specified moisture-vapor transmission rates, light-blocking properties, and closure integrity systems designed to preserve bioactive compound stability through shelf life. Plastic bottles sustain the largest volume position due to resin cost efficiency and blow-molding throughput, while glass jars command margin pools in premium herbal and functional food applications where inertness and perceived purity drive selection. Child-resistant caps represent the fastest-growing closure segment as poison-prevention regulations tighten across jurisdictions with aging supplement-consuming populations.
The FDA enforces cGMP standards that mandate container-closure system qualification for dietary supplements, directly elevating testing documentation requirements for packaging suppliers seeking market access. EMA and national European regulators apply pharmaceutical-style migration testing to borderline nutraceutical products, compressing margins for converters lacking in-house analytical capabilities. Stakeholders must monitor how dual-use food-pharma regulatory overlap reshapes certification costs and customer qualification timelines.
Market Dynamics
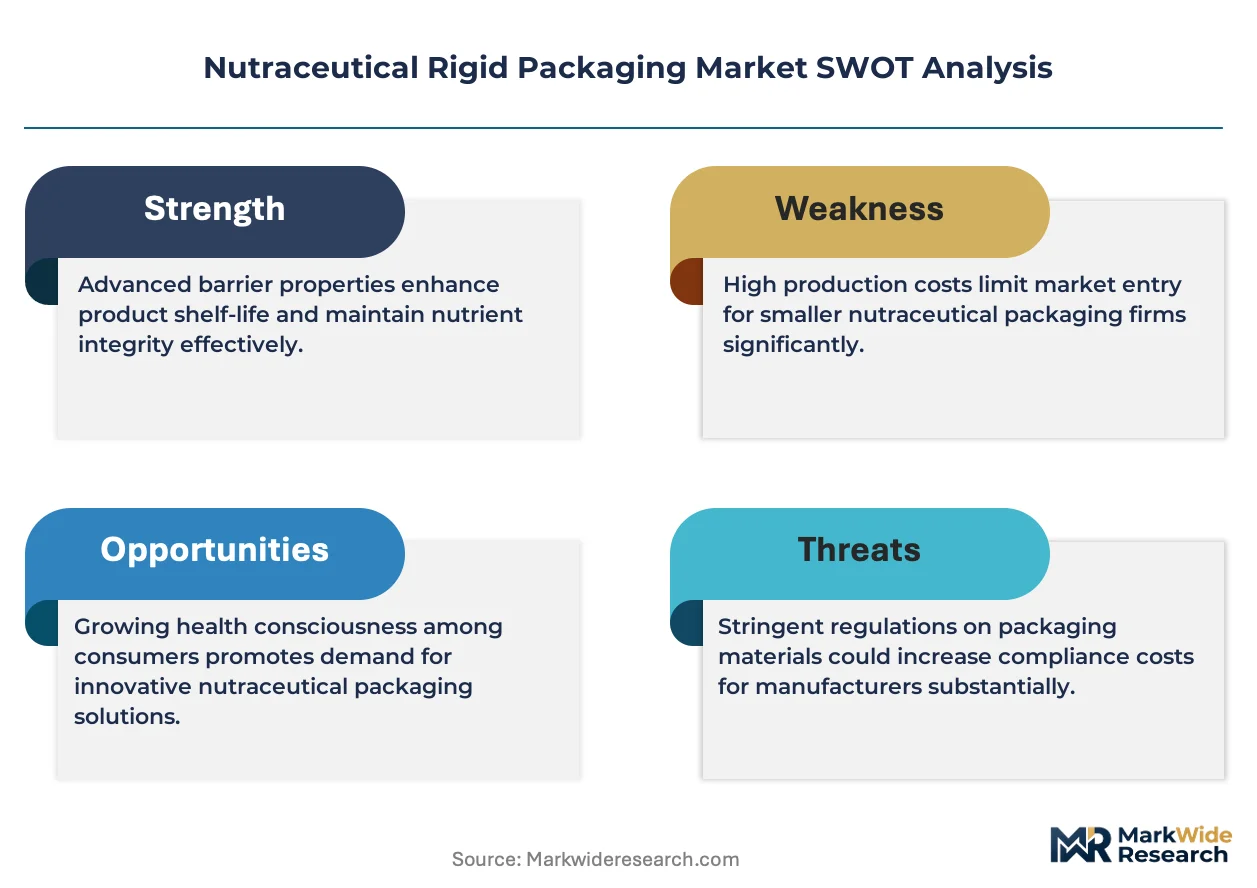
FDA cGMP enforcement is compressing supplier qualification timelines while elevating barrier-property specifications for HDPE and PET containers across the dietary supplement supply chain.
Growth Catalysts
- EMA Migration Testing Expansion:Borderline nutraceutical products in Europe now face pharmaceutical-style analytical requirements, forcing converters to invest in in-house testing capabilities that lock in premium customer relationships.
- Child-Resistant Closure Mandates:Poison-prevention regulations across aging populations in Germany, Japan, and the United States are accelerating demand for certified CR caps as a compliance-driven replacement cycle.
- Cologne-Frankfurt Manufacturing Cluster:Supplement contract manufacturers concentrated in western Germany generate dense localized demand for compliant primary packaging with shortened logistics loops.
Market Restraints
- Resin Cost Volatility:HDPE and PET feedstock prices tied to crude oil and natural gas markets create margin compression for converters locked into annual supply contracts with brand owners.
- Analytical Capability Concentration:Migration testing and container-closure qualification services cluster in Germany, Switzerland, and the United States, creating geographic bottlenecks for Asian and Latin American converters seeking market access.
- Glass Substitution Threat:Premium herbal and functional food segments increasingly specify glass jars for perceived purity, limiting plastic bottle penetration in high-margin applications.
Strategic Opportunities
- India PLI Scheme Alignment:Domestic supplement manufacturing incentives under India's production-linked incentive framework create localized packaging demand that bypasses import duty structures.
- Post-Consumer Recycled Resin Integration:FDA guidance on recycled plastics in food-contact applications is opening pathways for rPET and rHDPE qualification in dietary supplement containers.
- Direct-to-Consumer Channel Expansion:Subscription-based supplement brands require specialized bottle formats with enhanced shelf appeal and e-commerce durability specifications.
Industry Challenges
- Dual-Use Regulatory Overlap:Packaging suppliers must maintain parallel certification systems for food-contact and pharmaceutical-grade specifications, extending qualification timelines.
- Blow-Molding Technical Workforce Scarcity:Specialized operators capable of calibrating high-speed extrusion blow-molding lines for tight barrier tolerances are concentrated in legacy manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Rigid Packaging Market |
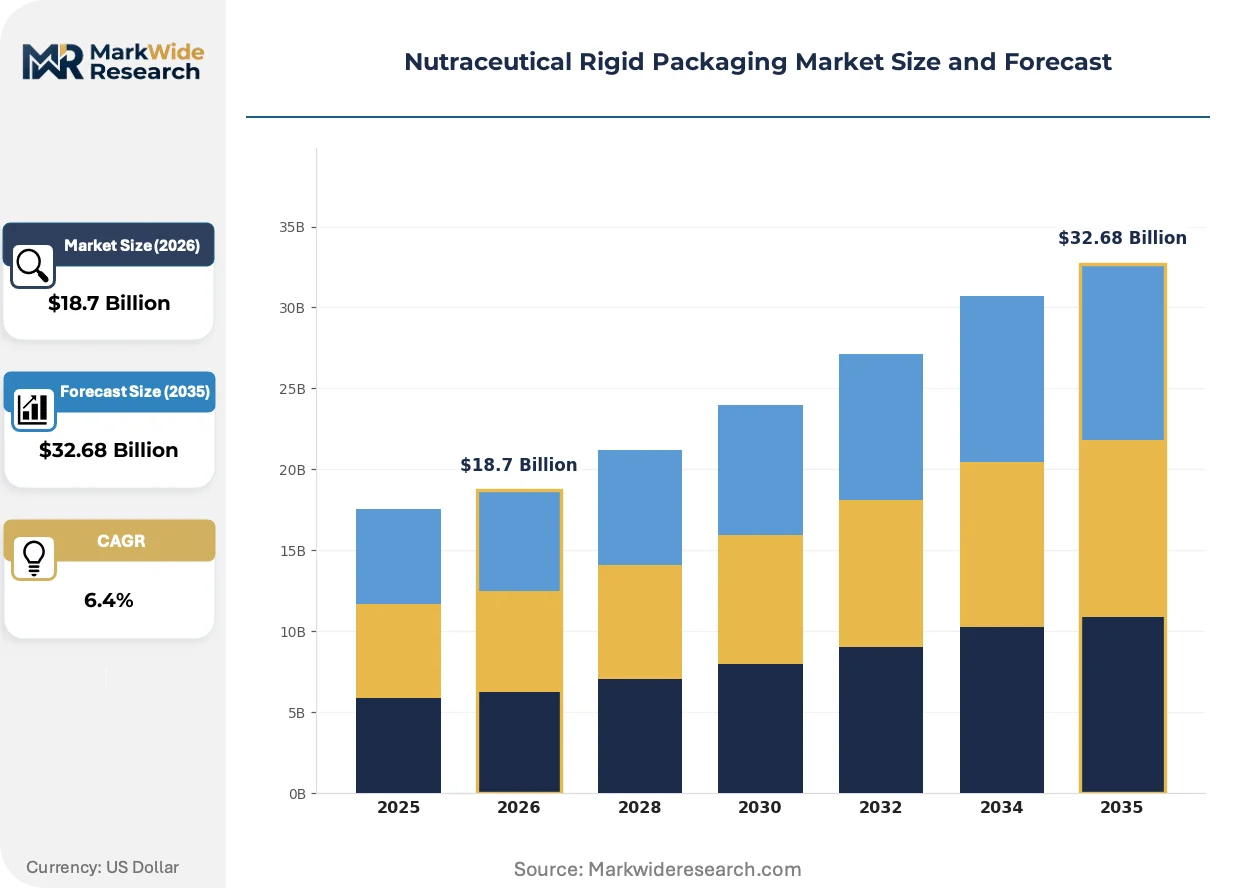
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Cans Material: Plastic, Glass, Metal, Composites Closure Type: Screw Caps, Snap-on Lids, Flip-top Caps, Child-resistant Caps Application: Vitamins, Supplements, Functional Foods, Herbal Products |
| Companies Covered | Amcor plc, Berry Global Inc., Gerresheimer AG, Alpla Group, Stoelzle Glass Group, AptarGroup Inc., WestRock Company, Silgan Holdings Inc., Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Rigid Packaging Market Evolving Landscape
Active and intelligent packaging systems are penetrating nutraceutical applications as brands seek differentiation through shelf-life transparency and consumer engagement features.
Multilayer coextrusion technology is absorbing moisture-barrier and oxygen-scavenging functions into single-structure bottles, eliminating secondary packaging components. Premium probiotic and omega-3 brands in Germany and the United States are specifying these structures to extend stability claims. The technology is absorbing margin from traditional foil-laminate sachet formats by consolidating protection into primary containers.
REACH SVHC disclosure requirements are forcing converters to document full material compositions down to 0.1% weight thresholds for plastic additives and colorants. Suppliers lacking supply chain traceability systems face exclusion from European brand owner procurement lists. Small and mid-sized converters in eastern Europe are responding by consolidating supplier bases to reduce documentation burden.
Brand owners are consolidating supplier panels from fifteen-plus vendors to three-to-five strategic partners capable of integrated design, testing, and logistics services. This concentration is displacing transactional spot purchasing in North American vitamin and mineral segments. The shift is most visible among mid-sized supplement brands seeking to internalize packaging expertise without expanding procurement headcount.
Nutraceutical Rigid Packaging Market Segmentation
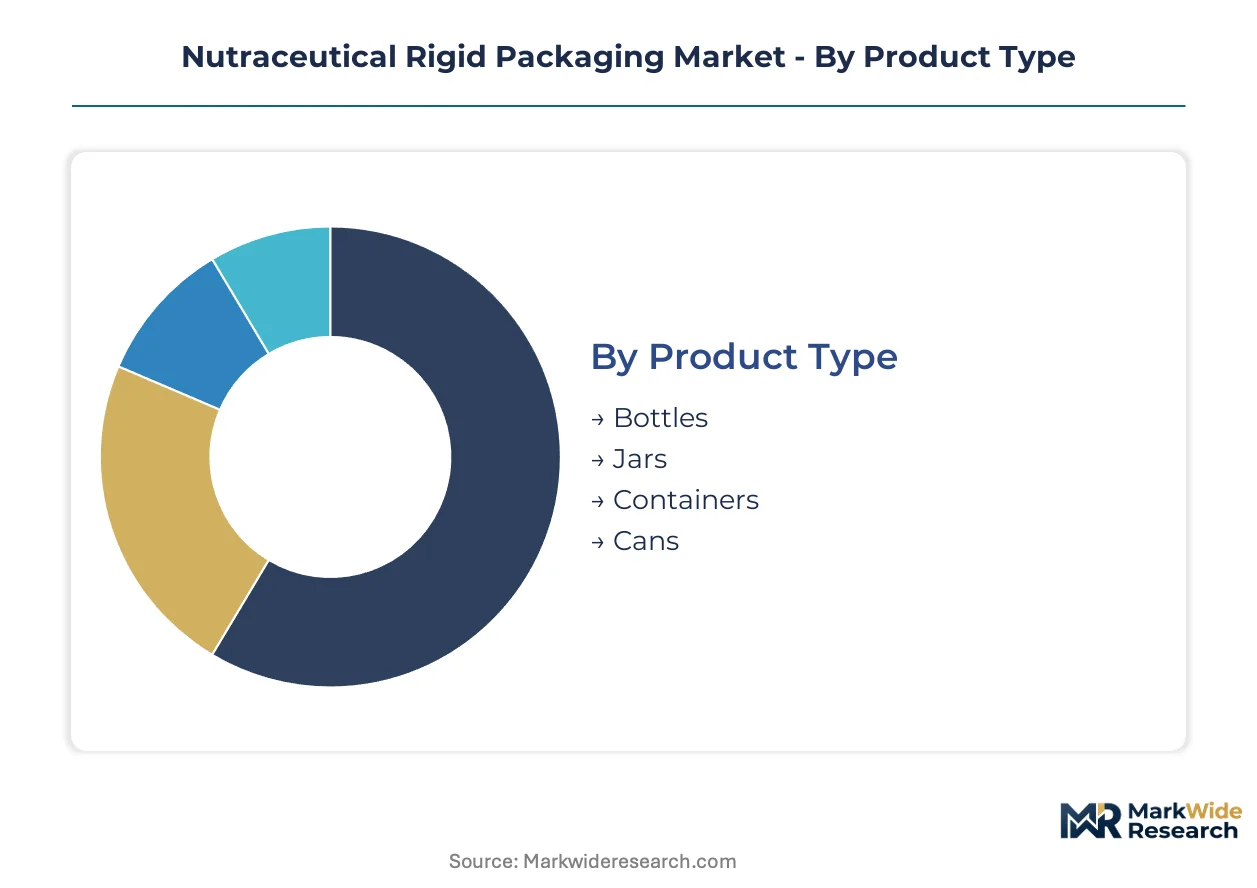
Segmentation in nutraceutical rigid packaging reveals how procurement criteria diverge across regulatory exposure, barrier requirements, and end-use stability demands. Buyers prioritize different performance specifications depending on whether they supply probiotic formulations, herbal extracts, or mineral supplements.
Product Type:
Bottle buyers emphasize blow-molding throughput and resin cost efficiency, while jar purchasers prioritize inertness and premium shelf presence.
- Bottles:HDPE and PET extrusion blow-molding dominates volume production for vitamin and mineral supplements. German contract manufacturers around Cologne specify multilayer coextrusion structures with oxygen-scavenging layers to extend probiotic stability claims without secondary foil sachets.
- Jars:Wide-mouth glass and thick-walled PET containers serve premium herbal and functional food segments where perceived purity drives selection. The United States and Germany account for concentrated demand as direct-to-consumer brands seek differentiation through tactile packaging experiences.
- Containers:Rectangular and oval formats optimize pallet density for bulk powder supplements and meal-replacement products.
- Cans:Metal and composite cans retain niche positions for effervescent tablet formats requiring absolute moisture exclusion.
Bottles lead volumes today; jars are gaining share fastest in premium applications.
Material:
Material selection hinges on migration testing burdens, barrier property requirements, and brand positioning against plastic aversion.
- Plastic:HDPE and PET sustain the largest volume position due to resin cost efficiency, blow-molding scalability, and established recycling infrastructure. FDA cGMP enforcement is elevating documentation requirements for container-closure system qualification, compressing margins for converters lacking in-house analytical capabilities.
- Glass:Soda-lime and borosilicate jars command margin pools in herbal and functional food applications where inertness and premium perception justify higher unit costs. EMA pharmaceutical-style migration testing for borderline nutraceutical products reinforces glass specification in regulated European markets.
- Metal:Tinplate and aluminum cans serve effervescent and hygroscopic formulations demanding absolute moisture barriers.
- Composites:Multilayer cartons and paperboard cans with barrier coatings target sustainability-positioned brands seeking plastic reduction.
Plastic dominates absolute tonnage; glass is expanding most quickly in high-margin segments.
Closure Type:
Closure procurement increasingly centers on poison-prevention compliance and senior-friendly accessibility tensions.
- Child-resistant Caps:Certified CR closures represent the steepest expansion trajectory as poison-prevention regulations tighten across aging populations in Germany, Japan, and the United States. Supplement brands face replacement cycles driven by state-level mandates and liability exposure.
- Screw Caps:Continuous-thread HDPE and PP closures remain the default for cost-sensitive vitamin segments where regulatory exposure is lowest.
- Snap-on Lids:Press-fit closures serve powder containers and gummy supplement jars requiring frequent access.
- Flip-top Caps:Hinged dispensing closures dominate tablet and capsule formats in pharmacy and convenience retail channels.
Screw caps retain volume leadership; child-resistant caps are climbing the fastest on regulatory compulsion.
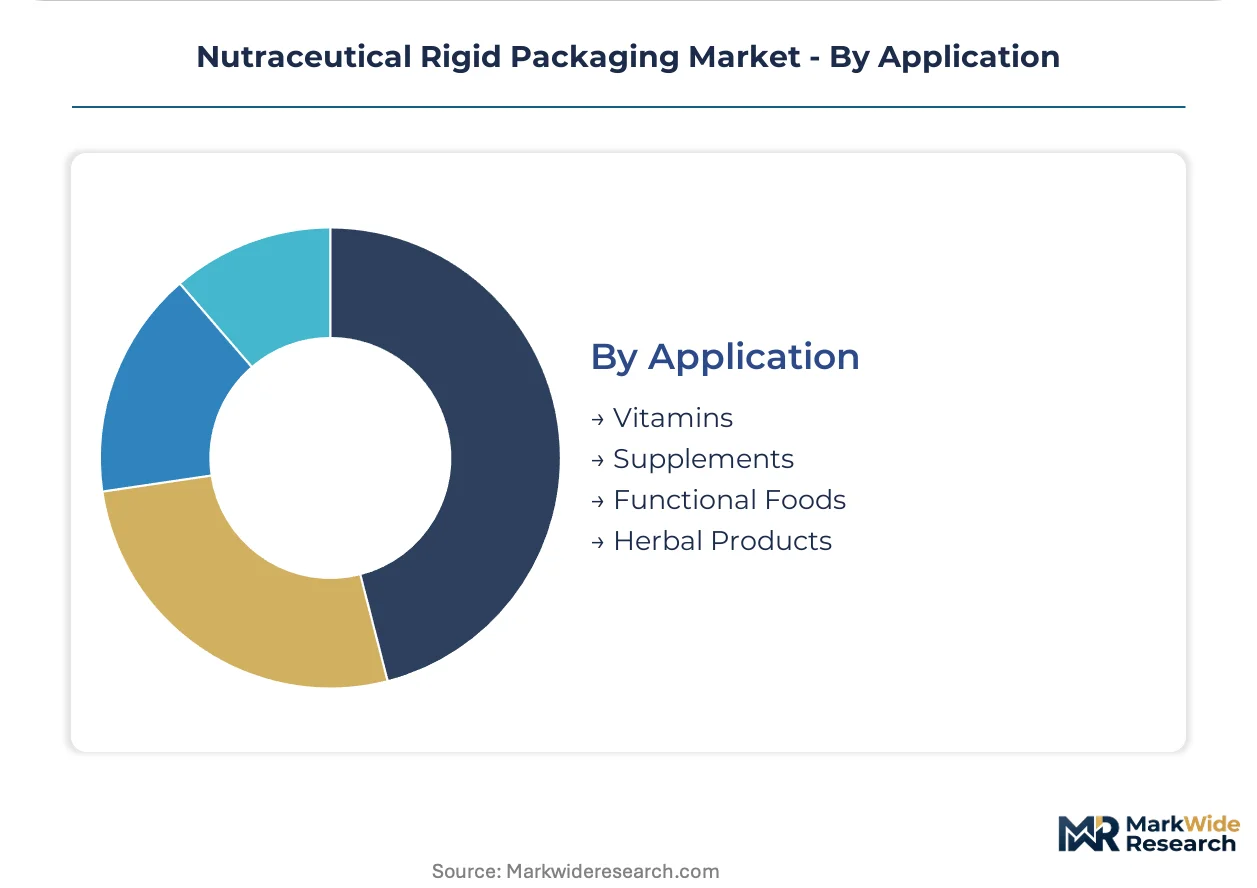
Application:
Application segmentation tracks how stability requirements and regulatory scrutiny vary across bioactive compound categories.
- Vitamins:Multivitamin and single-nutrient formulations in tablet, capsule, and gummy formats drive standardized HDPE bottle demand. North American brands accelerate orders for compliant primary packaging as FDA cGMP enforcement intensifies.
- Supplements:Probiotic, omega-3, and protein powder segments specify advanced barrier structures including multilayer coextrusion and nitrogen flushing. German and United States brands lead specification of integrated moisture-oxygen protection.
- Functional Foods:Meal replacements, fortified beverages, and nutraceutical bars require specialized formats spanning bottles, cups, and composite cans.
- Herbal Products:Traditional medicine and botanical extract segments favor glass jars and amber PET for light-blocking properties and perceived natural authenticity.
Vitamins command the largest volume base; supplements are gaining share fastest through premium barrier specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized blow-molding technicians and container-closure qualification specialists concentrate in legacy manufacturing regions, anchoring procurement decisions and supplier selection criteria across major nutraceutical packaging demand centers.
United States
Dietary supplement brands accelerate orders for FDA-compliant primary packaging as cGMP enforcement intensifies. The FDA mandates container-closure system qualification documentation that elevates barrier-property specifications for HDPE and PET containers. New Jersey and Pennsylvania host dense clusters of contract manufacturers generating localized demand for certified packaging with shortened logistics loops.
Germany
Supplement contract manufacturers cluster around Cologne and Frankfurt, creating concentrated demand for multilayer coextrusion structures with oxygen-scavenging layers. EMA pharmaceutical-style migration testing applies to borderline nutraceutical products, forcing converters to invest in in-house analytical capabilities. The Cologne-Frankfurt corridor generates dense localized demand for compliant primary packaging.
India
Domestic supplement manufacturing incentives under the PLI scheme create localized packaging demand that bypasses import duty structures. CDSCO and FSSAI regulations tighten quality documentation requirements for container-closure systems. Maharashtra and Gujarat host emerging contract manufacturing clusters driving specification of certified HDPE and PET bottles.
China
NMPA alignment with international pharmaceutical packaging standards elevates barrier-property documentation for dietary supplement containers. Dual carbon goals and plastic reduction mandates accelerate interest in post-consumer recycled resin integration. The Yangtze River Delta concentrates blow-molding capacity serving both domestic brands and export markets.
Japan
PMDA-enforced poison-prevention regulations tighten child-resistant closure specifications as the aging population expands supplement consumption. METI standards for food-contact materials extend to nutraceutical borderline products. The Kanto region around Tokyo anchors premium glass jar demand for herbal and functional food applications.
Nutraceutical Rigid Packaging Market Competitive Landscape
Top-tier vendors anchor premium certified segments, while mid-scale converters compete on volume throughput and resin cost efficiency. The market structure stratifies across pharmaceutical-grade qualification holders, high-volume commodity producers, and specialized glass and metal fabricators. Three archetypes dominate: integrated multinationals with in-house testing capabilities, regional blow-molding specialists serving contract manufacturers, and premium material providers targeting herbal and functional food segments. Competitive moves concentrate on M&A to acquire analytical capabilities and strategic partnerships to secure recycled resin supply.
Among integrated packaging multinationals, Amcor plc, Berry Global Inc., and Gerresheimer AG occupy distinct tier positions. Amcor exemplifies the pharmaceutical-certified extrusion archetype leveraging barrier-property expertise. Berry Global represents high-volume HDPE operations dominating cost-sensitive supplement segments. Gerresheimer anchors premium glass positioning for herbal applications requiring inertness and perceived purity. These three structures illustrate how qualification depth, scale efficiency, and material specialization segment competitive terrain.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Gerresheimer AG |
| Alpla Group |
| Stoelzle Glass Group |
| AptarGroup Inc. |
| WestRock Company |
| Silgan Holdings Inc. |
| Ardagh Group |
| Others |
Value Network & Pricing Analysis
FDA-mandated container-closure qualification documentation is forcing brand owners to consolidate supplier panels from transactional spot purchasing toward integrated design-testing-logistics partnerships, compressing margins for converters lacking in-house analytical capabilities while elevating pricing power for certified tier-one vendors.
Pricing Analysis
Bundled service contracts encompassing design, migration testing, and logistics command premium positioning against unbundled transactional resin supply. Three-tier pricing structure across pharmaceutical-certified, food-grade compliant, and commodity resin tiers separates Amcor plc and Berry Global Inc. from regional blow-molding specialists. Pricing pressure stems from resin cost volatility tied to crude oil feedstock markets, particularly squeezing converters locked into annual supply contracts. Cost-sensitive vitamin brands in North America exhibit highest price sensitivity, while German probiotic manufacturers prioritize barrier-performance over unit economics.
Supply Chain Analysis
Freight cost differentials between Asian resin suppliers and European converter networks are reshaping procurement geography for North American brand owners. Blow-molding capacity concentrates in Germany, the United States, and China, with specialized extrusion lines anchored in the Cologne-Frankfurt corridor and New Jersey-Pennsylvania clusters. Raw material flows draw from Saudi Arabian and Qatari petrochemical feedstock, Belgian colorant masterbatch specialists, and German closure-component fabricators. Single-source vulnerability around pharmaceutical-grade HDPE resin creates structural exposure for converters serving FDA-regulated supplement brands. Distribution runs through contract manufacturer direct delivery with minimized safety stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EMA pharmaceutical-style migration testing requirements and FDA cGMP enforcement timelines creates cost-structure advantages for converters with dual-qualification capabilities spanning both jurisdictions.
For Market Incumbents: Lock in multiyear supply agreements with German contract manufacturers around Cologne and Frankfurt before EMA testing requirements harden further. Acquire in-house migration testing capabilities to defend margin position against Asian converters facing analytical bottleneck exclusion from European procurement lists. Prioritize backward integration into post-consumer recycled resin qualification under FDA guidance to preempt sustainability-driven supplier switches. For New Entrants and Emerging Players: Capture localized packaging demand generated by India's PLI scheme incentives for domestic supplement manufacturing, bypassing import duty structures that disadvantage established multinational suppliers. Target Maharashtra and Gujarat contract manufacturing clusters with certified HDPE and PET bottle supply positioned against CDSCO documentation requirements. Lead with rapid container-closure qualification turnaround as the primary go-to-market wedge against incumbent lead times. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale European converters possessing EMA-certified testing laboratories but lacking global scale. Long-term viability across the analysis window favors acquisition targets with demonstrated dual food-pharma qualification systems and established relationships with aging-population supplement markets in Germany and Japan. Monitor FDA cGMP warning letter issuance rates as the inflection signal for accelerated brand owner supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Migration Testing Capability Acquisition | EMA pharmaceutical-style requirements for borderline nutraceuticals lock in premium customer relationships. |
| Post-Consumer Recycled Resin Qualification | FDA guidance on rPET and rHDPE opens pathways into sustainability-positioned supplement brand portfolios. |
| Multilayer Coextrusion Technology Deployment | Oxygen-scavenging structures absorb margin from traditional foil-laminate sachet formats in probiotic applications. |
| Child-Resistant Closure Certification Investment | PMDA and state-level poison-prevention mandates drive replacement cycles across aging supplement-consuming populations. |
| Direct-to-Consumer Format Development | Subscription-based brands require specialized e-commerce durability specifications and enhanced shelf appeal. |
Research Methodology
Bottom-up supplement brand procurement modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement directors at contract manufacturers, regulatory affairs leads at converters, blow-molding technical operators, and logistics coordinators at brand owners combined with secondary validation from FDA cGMP guidance documents, EMA borderline product classification rulings, FSSAI container-closure notifications, and customs trade data. Triangulation between demand-side order flow analysis and supply-side extrusion line utilization rates ensures cross-verified volume estimation.
Input-output matrices mapping resin feedstock costs, barrier-property testing burdens, and logistics configurations to end-use segment pricing generate volume and value outputs across the projection horizon. Segmentation dimensions encompass product type, material grade tier, closure certification level, application stability requirements, and regional regulatory cluster. CAGRs derive from trend-line extrapolation of procurement qualification timelines and brand owner supplier consolidation patterns. Industry-specific forecast inputs include FDA cGMP enforcement intensity indices and EMA borderline product reclassification probabilities.
Underlying measurement precision varies by segment; pharmaceutical-certified packaging carries tighter precision than commodity resin supply. Forecasts reflect documented assumptions regarding regulatory enforcement trajectories and resin price correlation with energy markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market