
 Anti-Slip Coated Paper Market | 2026-2036
Anti-Slip Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Slip Coated Paper Market Outlook
The capital-intensity divergence between integrated coating specialists and merchant converters is collapsing as multi-layer extrusion and inline coating systems become standard. W Bosch GmbH & Co. KG Papier-Und Folienwerke leverages captive pulp-to-coating operations across its German mills to sustain margin control. Sierra Coating Technologies LLC competes through regional toll-coating flexibility, while Dura-Fibre, LLC anchors its position with heat-resistant polymer formulations for industrial pallet applications.
Anti-slip coated paper consists of kraft or recycled paper substrates treated with polymer, wax, or silicone coatings to achieve controlled coefficients of friction, typically engineered to 0.5–0.8 static friction values for load stabilization. Its primary purpose is preventing palletized goods from shifting during transport and warehousing, thereby cutting stretch-wrap consumption and reducing damage claims. The polymer coating segment leads in revenue contribution due to durability requirements in cold-chain logistics, while wax-coated variants dominate food service tray liner applications where temporary grip and cost minimization matter. Custom sheet formats are gaining traction in automated packaging lines, whereas standard roll configurations remain the volume backbone for manual warehouse operations.
FDA food-contact regulations govern silicone and wax coating migration limits in US food service and retail packaging, while REACH restricts certain polymer additives in European coatings, forcing reformulation cycles among suppliers. OSHA warehouse safety guidelines indirectly drive specification upgrades by linking slip-related load failures to worker injury liability. Stakeholders must monitor how evolving PFAS restrictions in both jurisdictions reshape polymer coating availability and pricing.
Market Dynamics
Multi-layer extrusion and inline coating systems are collapsing the historical margin gap between integrated pulp-to-coating operators and merchant converters, forcing capital deployment decisions across the value chain.
Growth Catalysts
- REACH compliance cycles:ECHA restrictions on polymer additives in European coatings are accelerating reformulation investments, creating first-mover advantages for suppliers with certified alternative chemistries.
- Cold-chain logistics durability requirements:Pharmaceutical and fresh-food distributors specify polymer-coated grades for temperature-stable load securing, expanding specification premiums.
- German automotive parts distribution:Precision manufacturing clusters in Baden-Württemberg and Bavaria generate concentrated demand for high-friction interleaving sheets protecting machined components.
Market Restraints
- Pulp cost volatility:Kraft paper substrate prices fluctuate with Nordic softwood supply disruptions, compressing converter margins during input spikes.
- PFAS availability constraints:Evolving EPA and state-level restrictions on fluorinated polymer coatings threaten formulation continuity for US food-contact applications.
- Silicone coating migration limits:FDA 21 CFR 177.2600 compliance testing extends qualification timelines for tray liner suppliers serving quick-service restaurant chains.
Strategic Opportunities
- Automated packaging line integration:Custom sheet formats with machine-readable alignment marks capture share in e-commerce fulfillment centers replacing manual palletizing.
- EU Green Deal procurement mandates:Public sector logistics tenders increasingly specify recyclable coating systems, favoring water-based polymer formulations over wax alternatives.
- India pharmaceutical cold chain:CDSCO temperature-controlled distribution regulations create specification openings for anti-slip materials in vaccine and biologics transport.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise spanning paper substrates and polymer rheology concentrates among retiring specialists at German and Austrian mills.
- Inline system capex requirements:Multi-layer extrusion lines demand 18-24 month installation cycles, locking smaller converters into toll-coating dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Slip Coated Paper Market |
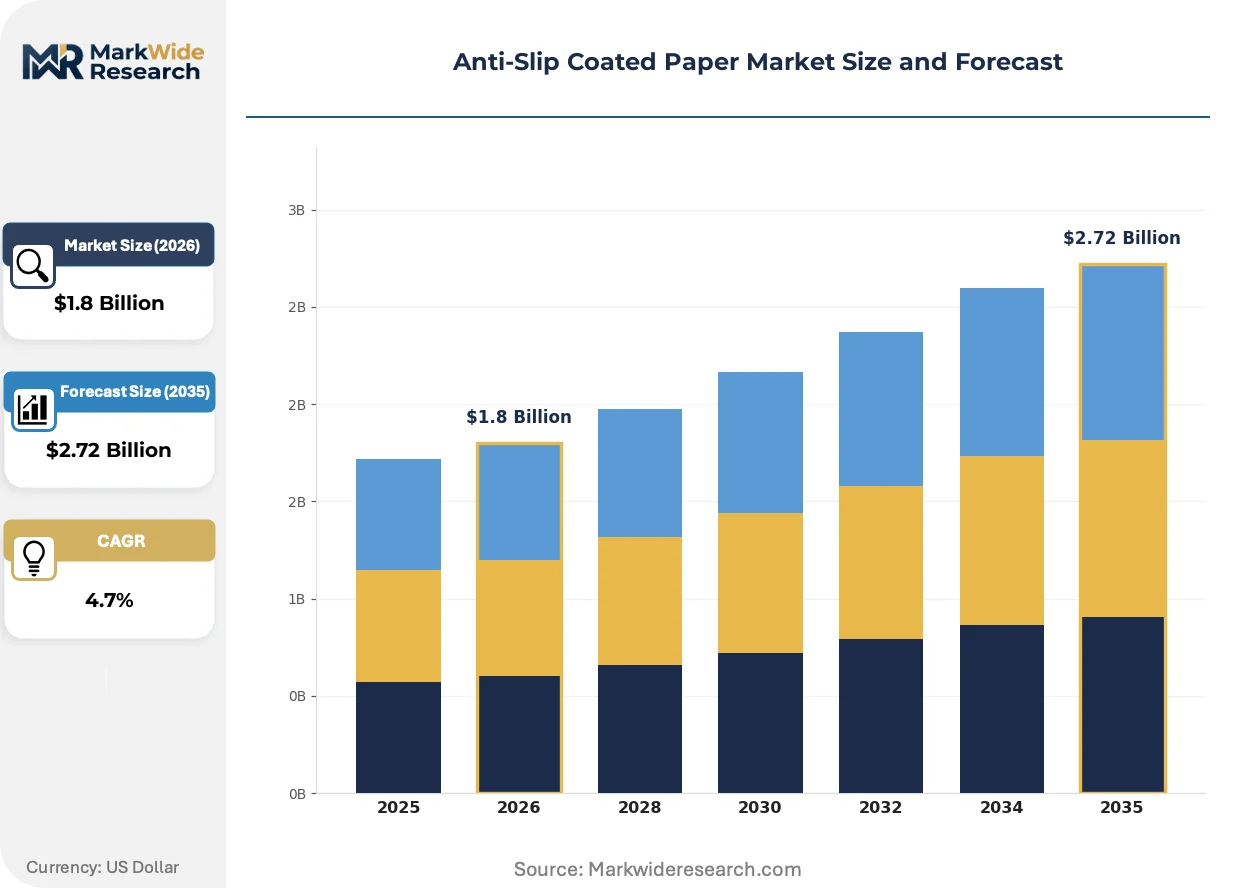
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Custom, Roll, Sheet Application: Packaging, Labels, Floor Graphics, Signage End User: Retail, Food Service, Healthcare, Logistics Coating Type: Polymer, Wax, Silicone, Others |
| Companies Covered | Specialty Coating & Laminating LLC, Continental Paper & Plastics Corp., CGP Inc., Falcon Packaging & Converting Ltd., Delta Paper Mills Limited, Dura-Fibre, LLC, W Bosch GmbH & Co. KG Papier-Und Folienwerke, PAL-Cut A/S, Sierra Coating Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Slip Coated Paper Market Strategic Shifts
Coating chemistry convergence with sustainability mandates and automation compatibility requirements is redefining product specifications faster than historical replacement cycles.
Water-based polymer emulsion technology is miniaturizing coating thickness while maintaining static friction coefficients above 0.6. Automated beverage and consumer goods bottling lines in the Netherlands and Belgium specify these reduced-caliper grades to minimize material weight per pallet. The technology is miniaturizing equipment footprints and enabling retrofit installations at mid-scale converters previously excluded from inline coating economics.
REACH Annex XVII restrictions on persistent organic pollutants in polymer additives are forcing coating reformulations across European suppliers. Industrial consequence includes extended qualification timelines for automotive and food-contact applications as migration testing protocols expand. German and French paper mills are responding by accelerating bio-based wax alternative development to preserve food-service tray liner market access.
Specification consolidation among third-party logistics providers is compressing supplier qualification cycles from multi-year frameworks to annual performance reviews. Large contract logistics operators in the US and Germany now mandate real-time friction coefficient documentation and lot-traceability systems. This behavioral shift concentrates procurement volumes with coating specialists possessing integrated quality management systems, marginalizing merchant converters lacking laboratory capabilities.
Anti-Slip Coated Paper Market Segmentation
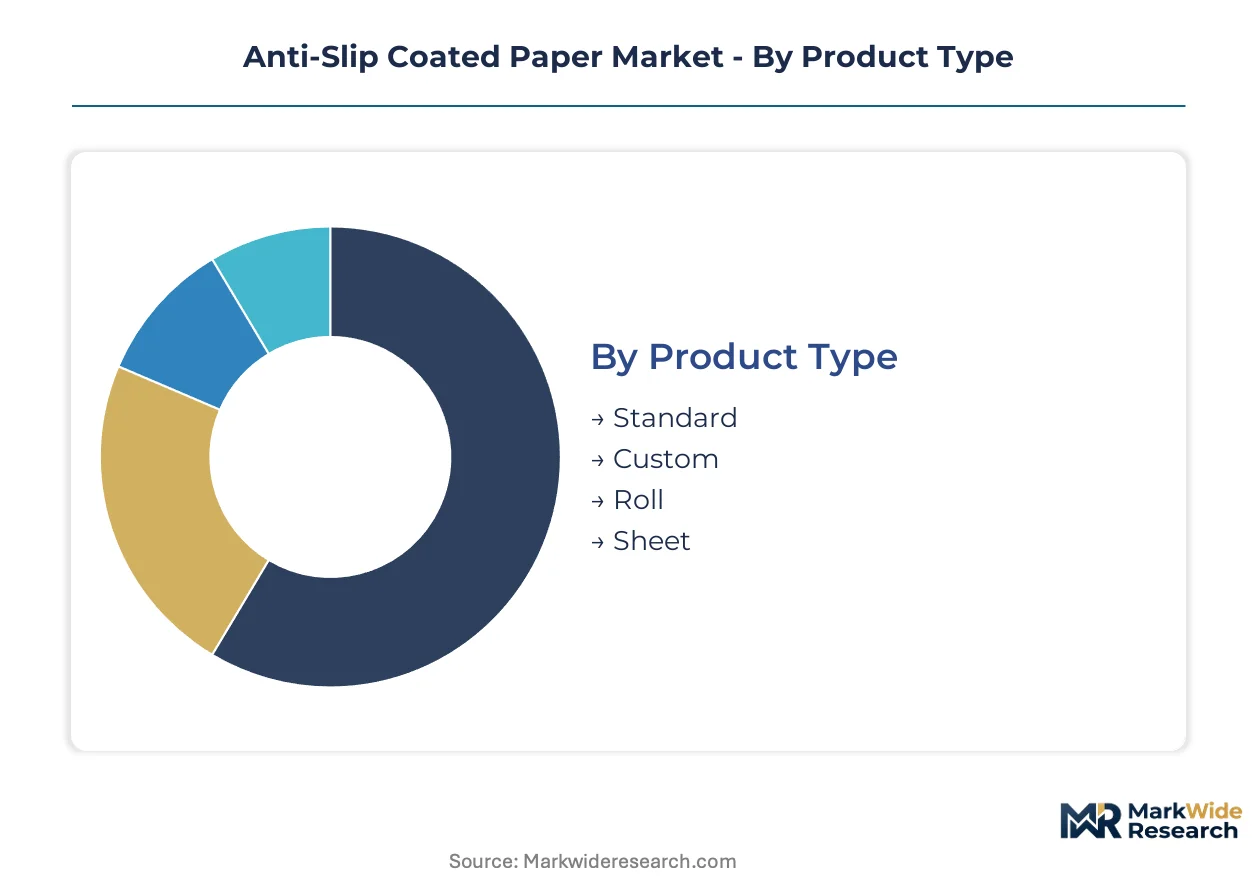
Anti-slip coated paper specifications diverge sharply across customer workflows, with coating chemistry and format dimensions determining qualification barriers. Procurement patterns cluster around load-securing performance in logistics versus food-contact compliance in service industries, fragmenting supplier specialization.
Product Type:
Margin pools concentrate in custom formats where automated line integration commands specification premiums over commodity rolls.
- Standard:Pre-dimensioned sheets and rolls for manual warehouse palletizing dominate volume throughput. Logistics operators in Germany specify these for automotive parts distribution where friction coefficients above 0.6 prevent machined component shifting during multimodal transit.
- Custom:Machine-readable alignment marks and precise caliper tolerances serve automated packaging lines in Netherlands beverage bottling facilities. E-commerce fulfillment centers specify these formats to reduce stretch-wrap consumption and accelerate palletizing cycle times.
- Roll:Continuous web configurations feed high-speed converting equipment at mid-scale merchant operations.
- Sheet:Discrete cut-to-size formats predominate in quick-service restaurant tray liner applications.
Standard holds installed capacity. Custom is rotating up the share rankings.
Application:
Application demand splits between protective logistics functions and communicative surface functions, with coating durability requirements diverging accordingly.
- Packaging:Pallet liners and interleaving sheets prevent load shifting in temperature-controlled pharmaceutical distribution. CDSCO cold-chain regulations in India specify polymer-coated grades for vaccine transport stability.
- Labels:High-friction backing materials secure adhesive labels to curved containers in automated labeling lines.
- Floor Graphics:Temporary slip-resistant signage for retail and event venues uses lower-durability wax coatings.
- Signage:Extended outdoor exposure applications specify silicone-enhanced weather resistance.
Packaging commands the volume base. Floor Graphics is climbing the fastest as experiential retail expands.
End User:
End-user procurement sophistication ranges from specification-heavy logistics tenders to price-sensitive food service spot buying.
- Logistics:Third-party operators in Germany and the US mandate real-time friction coefficient documentation and lot-traceability systems. Annual performance reviews now replace multi-year qualification frameworks, concentrating volumes with integrated coating specialists.
- Food Service:Quick-service restaurant chains drive tray liner demand where FDA 21 CFR 177.2600 silicone migration limits extend supplier qualification timelines.
- Retail:Private-label packaging programs specify anti-slip interleaving for premium electronics and glassware protection.
- Healthcare:Sterile supply chain applications require coatings compatible with gamma irradiation protocols.
Logistics anchors specification intensity. Healthcare is gaining share fastest as pharmaceutical cold-chain investment accelerates.
Coating Type:
Coating chemistry determines regulatory exposure and temperature performance, with polymer formulations commanding durability premiums over wax alternatives.
- Polymer:Multi-layer extrusion systems deposit water-based emulsions achieving sub-micron thickness with static friction above 0.6. Cold-chain pharmaceutical distributors specify these grades for temperature-stable load securing from Nordic distribution hubs to Indian vaccine storage facilities.
- Wax:Bio-based alternatives are accelerating development at German and French mills responding to REACH Annex XVII restrictions on persistent organic pollutants.
- Silicone:Food-contact applications face extended migration testing timelines under FDA and EFSA protocols.
- Others:Experimental bio-adhesive and mineral-based formulations target EU Green Deal recyclable coating mandates.
Polymer holds installed capacity. Wax is rotating up the share rankings as bio-based reformulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented paper mills in Germany and the Netherlands supply anti-slip coated grades to logistics operators across three continents, while import-dependent markets in India and Brazil build domestic converting capacity to reduce freight costs and customs exposure.
Germany
Automotive parts distributors in Baden-Württemberg and Bavaria specify high-friction interleaving sheets for machined component protection during multimodal transit. ECHA REACH Annex XVII restrictions on polymer additives force coating reformulations at mills in North Rhine-Westphalia. W Bosch GmbH & Co. KG Papier-Und Folienwerke leverages captive pulp-to-coating operations across its German facilities to sustain margin control against merchant converter competition.
United States
Third-party logistics operators mandate real-time friction coefficient documentation and lot-traceability systems, compressing supplier qualification cycles. FDA 21 CFR 177.2600 governs silicone migration limits in quick-service restaurant tray liner applications. Sierra Coating Technologies LLC competes through regional toll-coating flexibility serving e-commerce fulfillment centers in the Midwest and Southeast.
India
CDSCO temperature-controlled distribution regulations for vaccines and biologics create specification openings for polymer-coated grades in pharmaceutical cold chains. Domestic converters in Gujarat and Maharashtra expand capacity to serve export markets while reducing import dependence. Delta Paper Mills Limited anchors its position with heat-resistant formulations targeting industrial pallet applications in South Asian logistics networks.
Netherlands
Automated beverage bottling lines specify reduced-caliper water-based polymer grades to minimize material weight per pallet. EU Green Deal procurement mandates favor recyclable coating systems in public sector logistics tenders. Rotterdam-area converters supply custom sheet formats with machine-readable alignment marks to Benelux distribution hubs serving Northern European retail chains.
Brazil
Food service tray liner demand concentrates in São Paulo and Rio de Janeiro metropolitan areas where quick-service restaurant chains expand footprint. ANVISA food-contact material rules govern coating chemistry for domestic suppliers. Local converters develop wax-coated alternatives to serve price-sensitive institutional catering markets while imported polymer grades capture pharmaceutical logistics specifications.
Anti-Slip Coated Paper Market Competitive Environment
Concentration sits with integrated pulp-to-coating specialists who control substrate supply and formulation chemistry under one roof. Merchant converters compete on regional toll-coating flexibility but face margin compression as inline multi-layer extrusion systems become standard. Three archetypes define competitive positioning: captive integrated mills, regional toll-coating specialists, and heat-resistant formulation developers. Capacity expansion and strategic partnerships dominate competitive moves as players secure coating chemist talent and automate quality documentation systems.
Within the integrated mill tier, W Bosch GmbH & Co. KG Papier-Und Folienwerke exemplifies captive supply chain control from Nordic softwood pulp through finished coating operations. Sierra Coating Technologies LLC and Dura-Fibre, LLC occupy distinct positioning vectors—one representing regional toll-coating agility, the other anchoring heat-resistant polymer expertise for industrial durability requirements. Specialty Coating & Laminating LLC and Continental Paper & Plastics Corp. sit within the merchant converter segment where qualification speed and format flexibility determine procurement outcomes. Falcon Packaging & Converting Ltd., CGP Inc., and PAL-Cut A/S represent European and North American specialists whose geographic proximity to automotive and pharmaceutical clusters shapes competitive access.
| Leading Market Players |
|---|
| Specialty Coating & Laminating LLC |
| Continental Paper & Plastics Corp. |
| CGP Inc. |
| Falcon Packaging & Converting Ltd. |
| Delta Paper Mills Limited |
| Dura-Fibre, LLC |
| W Bosch GmbH & Co. KG Papier-Und Folienwerke |
| PAL-Cut A/S |
| Sierra Coating Technologies LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Nordic pulp suppliers and German integrated mills lock in substrate access while freezing coating chemistry costs against REACH-driven reformulation cycles. These arrangements let W Bosch GmbH & Co. KG Papier-Und Folienwerke and similar captives stabilize margin visibility even as kraft paper spot prices fluctuate with softwood supply disruptions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium polymer-coated grades, standard wax formulations, and economy recycled substrates. Price differentiation hinges on REACH certification tier and volume scale, with cold-chain pharmaceutical distributors showing lowest sensitivity due to temperature-stability requirements. Cost compression in standard roll formats is intensifying because merchant converters lack inline coating economies, while logistics operators with automated lines accept specification premiums for custom sheet formats with machine-readable alignment marks.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp trade lanes and container availability constraints on Asia-Europe routes inflate inbound logistics costs for Indian and Brazilian converters dependent on Nordic kraft pulp imports. Supply concentrates in Germany, the Netherlands, and the United States, where integrated mills draw from captive softwood pulp operations and regional chemical feedstocks. Raw material dependencies rest on Nordic softwood pulp, water-based polymer emulsions, and silicone resins. Single-source vulnerability sits with German coating chemist expertise concentrated among retiring specialists. Distribution runs through third-party logistics operators mandating real-time friction coefficient documentation and lot-traceability systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across automated packaging lines, cold-chain pharmaceutical distribution, and quick-service restaurant tray liners creates multiple niche entry points for specialists. E-commerce fulfillment center demand for custom formats with machine-readable alignment marks exemplifies how workflow-specific requirements splinter procurement volumes.
For Market Incumbents: Shield formulation expertise by accelerating bio-based wax alternative development at German and French mills before REACH Annex XVII restrictions harden. Deepen backward integration into Nordic softwood pulp supply through long-term offtake extensions, locking out merchant converters facing kraft price volatility. Capture coating chemist talent through targeted recruitment at Austrian technical universities as retirement waves thin specialist ranks.
For New Entrants and Emerging Players: Differentiate on water-based polymer emulsion miniaturization for reduced-caliper grades serving Netherlands beverage bottling automation. Target India pharmaceutical cold chain as the most penetrable geography, where CDSCO temperature-controlled distribution regulations create specification openings against import-dependent incumbents. Pursue toll-coating partnerships with Gujarat-based converters to bypass capital-intensive inline system requirements.
For Investors and Strategic Acquirers: Regional toll-coating specialists with automated quality documentation systems present attractive consolidation targets as third-party logistics procurement cycles compress to annual performance reviews. Long-term viability favors coating chemists capable of spanning paper substrate rheology and polymer formulation across the analysis window. Monitor PFAS restriction trajectories at EPA and state levels as the critical signal for polymer coating availability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Softwood Pulp | Captive substrate supply insulates German mills from kraft price volatility during supply disruptions. |
| Water-Based Polymer Emulsion Scale-Up | Reduced-caliper grades capture Netherlands beverage automation demand while meeting EU Green Deal mandates. |
| Coating Chemist Talent Acquisition Program | Specialist recruitment at Austrian technical universities addresses formulation expertise retirement gaps. |
| Real-Time Friction Coefficient Documentation System | Integrated quality management satisfies US third-party logistics annual performance review requirements. |
| Bio-Based Wax Alternative Development | German and French mill R&D preserves food-service tray liner market access under REACH Annex XVII. |
Study Parameters
Operator-level perspectives from coating chemists at integrated German mills, procurement managers at US third-party logistics operators, technical directors at Netherlands beverage bottling facilities, and regulatory affairs leads at quick-service restaurant chains anchored the qualitative base. These primary interviews combined with secondary validation from ECHA REACH restriction databases, FDA 21 CFR food-contact guidance documents, CDSCO cold-chain distribution circulars, and customs trade flow records. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Sensitivity analysis tested forecast robustness across alternative scenarios for pulp cost volatility, PFAS restriction timing, and automation adoption rates. The analytical framework modeled coating chemistry, product format, application, and end-user segmentation dimensions across the projection horizon. CAGRs derived from regression analysis against historical logistics automation investment patterns and pharmaceutical cold-chain infrastructure buildouts. Industry-specific inputs included REACH reformulation cycle timelines and CDSCO temperature-controlled distribution compliance deadlines.
Material uncertainties — Nordic softwood supply disruptions, evolving EPA PFAS restrictions, and coating chemist retirement waves — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and logistics operator procurement behavior shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
North America Paper Cups Market