
 Dunnage Paper Bags Market | 2026-2036
Dunnage Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Dunnage Paper Bags Market Foresight
Aftermarket protective packaging services is reconfiguring margin distribution across the dunnage value chain. DS Smith leverages captive paper sourcing to anchor cost positions in European automotive corridors. Nefab competes through modular packaging systems that integrate paper dunnage with returnable container programs. Cordstrap B.V. specializes in load-securing combinations that extend paper bag utility into heavy-goods transit.
Dunnage paper bags are multi-ply kraft paper containers engineered with burst strengths exceeding 200 lb/in² to absorb shock and prevent cargo migration during transit. Gusseted bags accommodate irregular automotive components while flat bags dominate electronics and appliance sectors. Kraft paper material leads volume owing to fiber strength and established recycling infrastructure. Food and beverage end users increasingly specify biodegradable paper grades to meet retailer sustainability mandates.
The EU F-Gas Regulation and REACH framework restrict synthetic filler alternatives, directly expanding addressable demand for paper-based void protection. EPA guidelines in the United States and China's MEE circular economy directives impose parallel pressure on plastic reduction across logistics networks. Stakeholders must monitor evolving extended producer responsibility schemes that shift compliance burden toward packaging originators.
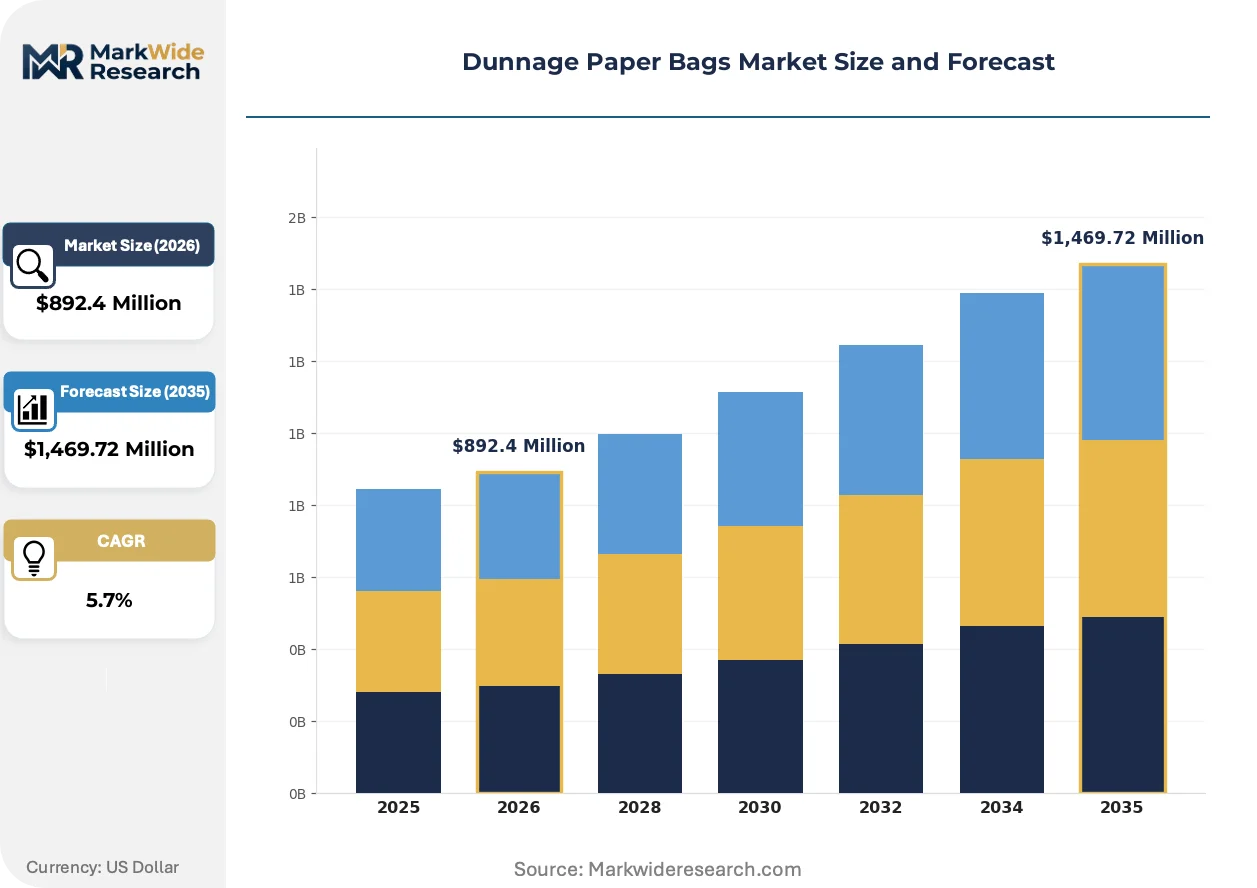
Market Dynamics
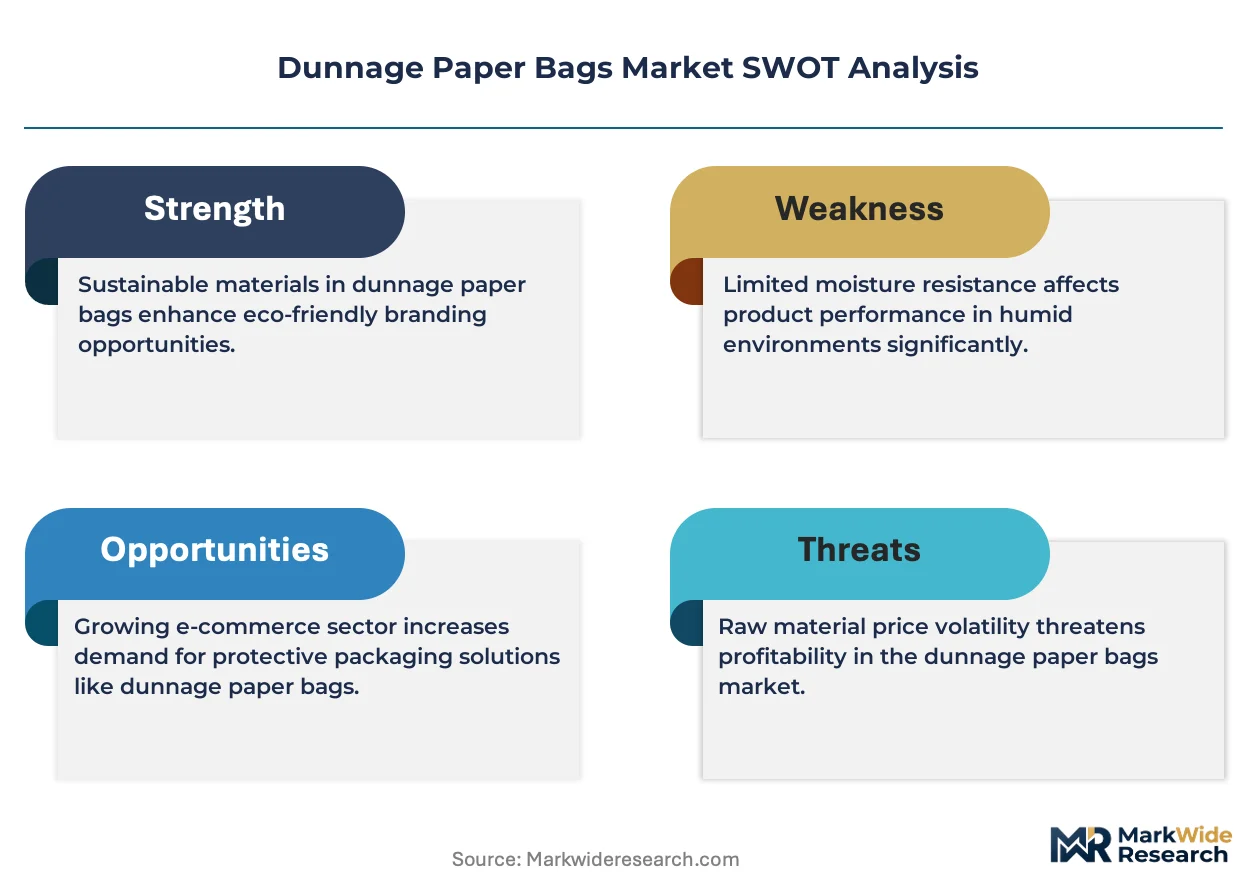
The EU Packaging and Packaging Waste Regulation is forcing automotive logistics networks to eliminate single-use plastic void fillers, redirecting capital toward recyclable paper-based protective systems and rewiring supplier relationships across European manufacturing corridors.
Growth Catalysts
- REACH and F-Gas Regulation:Synthetic filler alternatives face chemical restrictions across EU member states, expanding compliant paper dunnage demand in German and French automotive export channels.
- Kraft fiber strength:Multi-ply kraft paper with burst strengths exceeding 200 lb/in² now matches legacy plastic shock absorption at comparable unit economics for electronics and appliance manufacturers.
- China's MEE circular economy directives:Domestic logistics operators face plastic reduction mandates, creating import substitution opportunities for compliant paper dunnage suppliers.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp trades on commodity indexes, exposing converters to margin compression without long-term fiber supply contracts.
- Recycling infrastructure gaps:Biodegradable paper grades require industrial composting facilities absent in most North American and Asian secondary markets, limiting specification flexibility.
- Moisture sensitivity:Paper-based void protection degrades in high-humidity maritime routes, restricting adoption in Southeast Asian and Latin American export lanes without barrier coatings.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are building component clusters around Chennai and Pune, creating localized dunnage demand without import dependency.
- Returnable container convergence:Integration of paper dunnage with reusable automotive container programs reduces per-trip packaging waste and locks in multi-year service contracts.
- Extended producer responsibility expansion:France's CITEO and Germany's ZSVR schemes shift compliance costs toward packaging originators, favoring recyclable paper formats with established recovery pathways.
Industry Challenges
- Barrier coating certification:Food-contact and moisture-resistant paper grades require EFSA and FDA compliance timelines stretching 18-24 months, delaying product launches.
- Automotive specification fragmentation:OEMs maintain proprietary dunnage standards without harmonized ISO guidelines, forcing converters to maintain multiple product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dunnage Paper Bags Market |
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,469.72 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Sourced Paper Bags, Custom Sizes End User: Manufacturing, Retail, Food & Beverage, Transportation Material: Kraft Paper, Recycled Paper, Water-Resistant Paper, Biodegradable Paper Packaging Type: Retail Packaging, Bulk Packaging, Customized Packaging, Others |
| Companies Covered | Atlas Dunnage, Nefab, Cordstrap B.V., UFP Technologies, Myers Industries, Signode Industrial Group LLC, DS Smith, Menasha Corporation, Litco International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dunnage Paper Bags Market Shifts & Advancements
Active material science advances and regulatory compliance automation are compressing development cycles while expanding the functional envelope of paper-based protective packaging beyond traditional void-fill applications.
Multi-layer barrier coatings incorporating bio-based waxes and plant-derived polymers are collapsing the performance gap between paper dunnage and synthetic alternatives in moisture-prone transit environments. Tier 1 automotive suppliers in Germany and the Czech Republic are qualifying these grades for engine component exports to humid Asian markets. The technology is collapsing legacy assumptions about paper's environmental operating envelope, opening specification battles previously reserved for plastic foams.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents has eliminated a key input for expanded polystyrene void fillers. Automotive logistics coordinators in Stuttgart and Wolfsburg are now mandating paper-based alternatives in supplier packaging guidelines. Heavy-goods sectors including agricultural equipment and construction machinery are following this regulatory template, extending paper dunnage into load-securing applications previously dominated by synthetic strapping combinations.
Consolidated procurement functions at major appliance manufacturers are unbundling protective packaging from freight contracts, creating direct supplier relationships with specialized dunnage converters. This disintermediation eliminates forwarder markups but demands ISO 9001 and ISTA certification from paper bag vendors. The pattern is most visible in South Korean and Japanese electronics supply chains, where centralized sourcing teams now specify recyclable paper grades as non-negotiable vendor qualification criteria.
Dunnage Paper Bags Market Segmentation
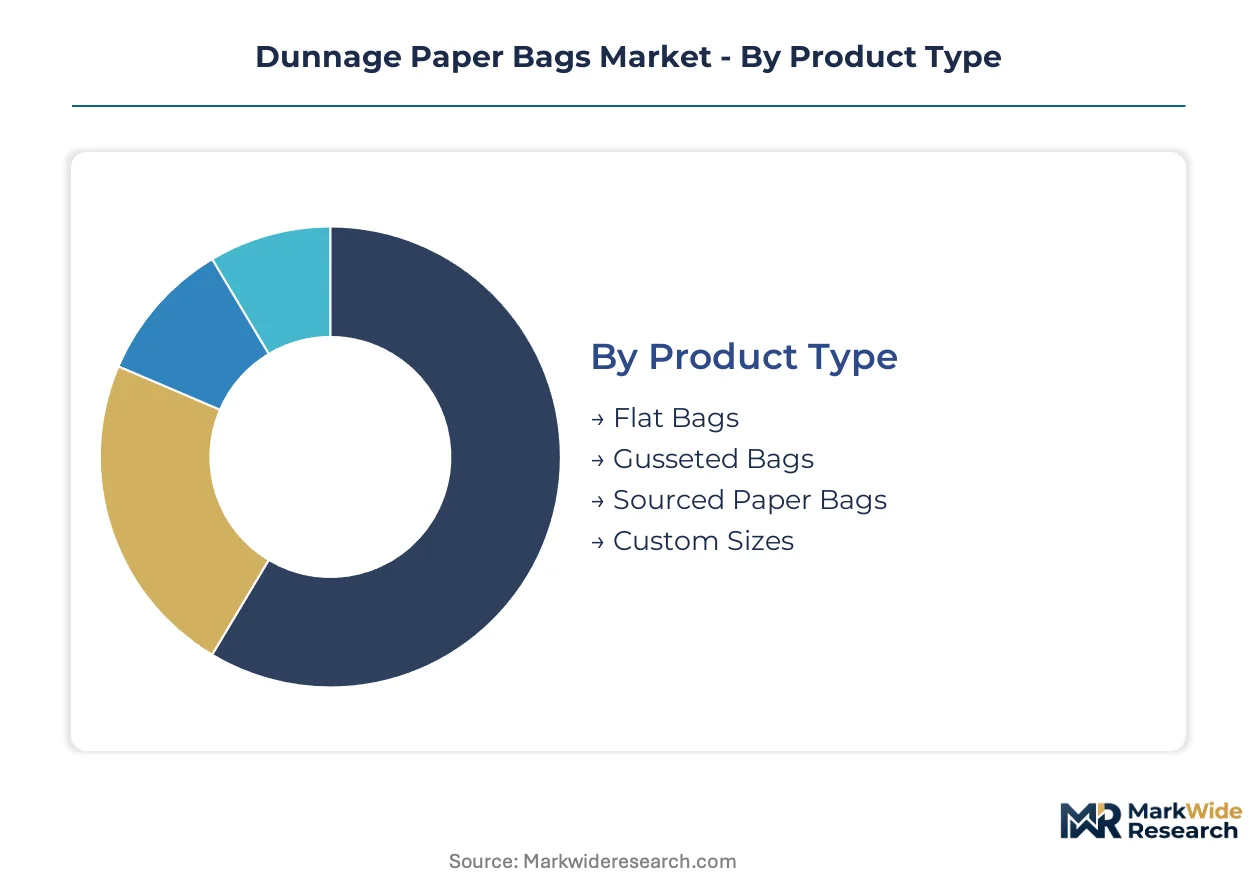
Dunnage paper bags serve divergent protection requirements across automotive logistics, electronics transit, and food-grade applications. Segmentation reveals how material specifications and bag geometries align with distinct shock-absorption and regulatory compliance demands.
Product Type:
Flat configurations dominate electronics and appliance sectors where uniform void fill suffices, while gusseted geometries expand into irregular automotive component cradling.
- Flat Bags:Two-ply kraft construction with burst ratings between 150-200 lb/in² protects flat-screen displays and small appliance shipments. German electronics manufacturers specify these for intra-European rail transit where humidity exposure remains minimal.
- Gusseted Bags:Expandable side panels accommodate camshafts, transmission housings, and irregular castings. Czech and Slovak automotive suppliers rely on these for engine component exports to Asian assembly plants.
- Sourced Paper Bags:Captive mill supply chains reduce fiber cost volatility for high-volume converters.
- Custom Sizes:Proprietary dimensions match OEM-specific component geometries without standardization overhead.
The dominant share belongs to Flat Bags, while Gusseted Bags is closing the gap fastest.
End User:
Cost tiers separate commodity protective packaging from specification-grade systems requiring extended certification timelines.
- Manufacturing:Automotive and electronics producers drive volume through multi-year container service contracts. Tier 1 suppliers in Stuttgart and Wolfsburg mandate recyclable paper void fillers under revised packaging guidelines.
- Transportation:Third-party logistics operators specify standardized bag formats across mixed freight networks. Maritime humidity constraints limit paper adoption on Southeast Asian lanes without barrier coatings.
- Retail:E-commerce fulfillment centers favor pre-inflated paper dunnage for automated packing lines.
- Food & Beverage:Biodegradable grades with EFSA compliance protect organic product shipments to French and German retail chains.
Manufacturing captures the volume concentration, yet Food & Beverage climbs fastest on sustainability mandates.
Material:
Supply concentration among Nordic pulp producers shapes converter sourcing strategies and margin structures.
- Kraft Paper:Northern bleached softwood fibers deliver tear resistance and established recycling pathways. German automotive corridors rely on multi-ply kraft for engine component transit under EU Packaging Waste Regulation compliance.
- Biodegradable Paper:Industrial composting certification meets French CITEO extended producer responsibility requirements. Food-contact approvals from EFSA extend development timelines to 18-24 months.
- Recycled Paper:Post-consumer fiber content satisfies retailer sustainability scorecards with reduced burst strength trade-offs.
- Water-Resistant Paper:Bio-based wax coatings expand operational envelopes into humid Asian export lanes.
Kraft Paper holds the structural advantage, though Biodegradable Paper gains specification momentum on regulatory pressure.
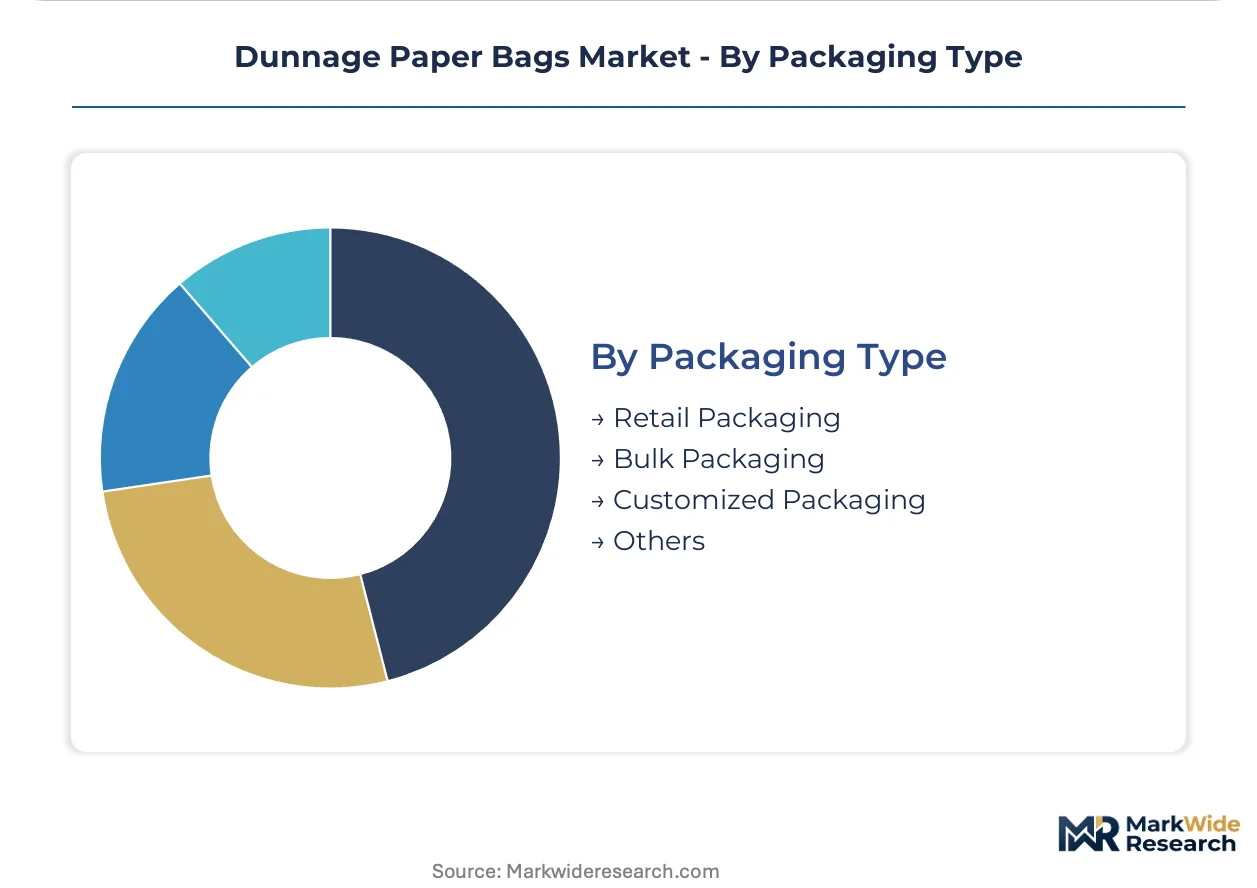
Packaging Type:
Customer type fragmentation separates spot purchasers from integrated service contracts with multi-year lock-ins.
- Bulk Packaging:Pallet-scale dunnage systems reduce per-unit labor for high-volume automotive parts distribution. Centralized procurement at South Korean electronics manufacturers unbundles protective packaging from freight contracts.
- Customized Packaging:Returnable container integration locks in multi-year service relationships with Tier 1 automotive suppliers. Modular systems from specialized converters combine paper dunnage with reusable automotive container programs.
- Retail Packaging:Shelf-ready formats serve boutique electronics and specialty food segments.
- Others:Niche specifications include anti-static grades for semiconductor transit.
Bulk Packaging commands the installed base, while Customized Packaging expands fastest on returnable container convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes dunnage paper bags primarily for automotive component exports, while India and China deploy them for domestic manufacturing protection and electronics transit respectively, revealing a consumption-mix split between export logistics and inbound supply chain security.
Germany
Automotive export corridors through Stuttgart and Wolfsburg drive specification-grade demand for gusseted kraft bags protecting engine components. The EU Packaging and Packaging Waste Regulation mandates elimination of single-use plastic void fillers by 2030, redirecting Tier 1 supplier procurement toward recyclable paper systems. Bavarian automotive clusters around Ingolstadt and Munich now require compliant dunnage in all supplier packaging guidelines.
United States
EPA guidelines on plastic reduction in logistics networks accelerate paper dunnage adoption across appliance and electronics manufacturers. The Inflation Reduction Act's domestic manufacturing incentives expand component production in Michigan and Ohio, creating localized protective packaging demand. Detroit-area automotive suppliers increasingly specify kraft paper void fillers to meet retailer sustainability scorecards.
China
MEE circular economy directives impose plastic reduction mandates on domestic logistics operators, opening substitution opportunities for compliant paper dunnage. Yangtze River Delta electronics manufacturers in Suzhou and Wuxi specify multi-ply kraft bags for semiconductor and display panel transit. Pearl River Delta appliance exporters face parallel pressure from EU-bound shipment compliance requirements.
India
PLI scheme incentives for auto component manufacturing build protective packaging demand around Chennai and Pune production clusters. BIS standards for sustainable packaging materials favor recyclable paper grades in government procurement tenders. Tamil Nadu automotive corridors now require dunnage converters to establish localized supply relationships reducing import dependency.
France
CITEO extended producer responsibility schemes shift compliance costs toward packaging originators, favoring paper formats with established recovery pathways. Food and beverage logistics around Paris and Lyon specify biodegradable dunnage grades for organic product shipments. Auvergne-Rhône-Alpes manufacturing hubs integrate paper void protection into returnable container service contracts.
Dunnage Paper Bags Market Competitive Landscape
Capability concentration sits with specialized converters mastering barrier coating certifications and automotive qualification protocols; scale advantage sits with integrated paper producers controlling captive fiber supply. The vendor base stratifies across three tiers: multinational packaging conglomerates with mill networks, regional specialists in automotive logistics integration, and niche converters serving food-grade certification requirements. Dominant competitive moves include backward integration into kraft pulp sourcing and strategic partnerships with returnable container program operators.
Within the integrated packaging tier, DS Smith exemplifies scale-driven positioning through European mill assets, while Nefab occupies the logistics integration specialist archetype with modular system capabilities. Cordstrap B.V. anchors the load-securing convergence segment, representing how paper dunnage extends into heavy-goods transit applications previously reserved for synthetic combinations.
| Leading Market Players |
|---|
| Atlas Dunnage |
| Nefab |
| Cordstrap B.V. |
| UFP Technologies |
| Myers Industries |
| Signode Industrial Group LLC |
| DS Smith |
| Menasha Corporation |
| Litco International, Inc. |
| Others |
Supply & Pricing Matrix
Nordic pulp mill clusters around Gothenburg and Oulu anchor fiber cost structures that cascade downstream to converter pricing power across European automotive corridors. Capacity utilization at these integrated kraft facilities directly shapes margin compression exposure for dunnage bag manufacturers without long-term fiber supply contracts.
Pricing Analysis
Long-term offtake agreements dominate high-volume automotive supply relationships, insulating Tier 1 suppliers from spot pulp volatility while spot transactions persist for smaller electronics and appliance converters. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified biodegradable grades from commodity kraft and recycled fiber alternatives. Cost compression in standard-grade kraft is intensifying because automotive OEMs are unbundling protective packaging from freight contracts and eliminating forwarder markups. Electronics manufacturers in South Korea and Japan exhibit the least price sensitivity due to non-negotiable sustainability scorecard requirements, while North American third-party logistics operators remain most price-sensitive on standardized bag formats.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated paper producers DS Smith and Menasha Corporation controlling captive Nordic pulp supply, while specialized converters Atlas Dunnage and Nefab hold logistics integration capacity. Geographic supply concentration centers on Sweden, Finland, and Germany for kraft fiber production, with secondary bag conversion clusters in the Czech Republic and Poland serving automotive export corridors. Raw material dependencies draw from northern bleached softwood kraft pulp, bio-based wax coatings for moisture resistance, and industrial composting certification services. Single-source vulnerability runs through Nordic pulp producers exposed to energy cost shocks and forestry labor disruptions. Distribution runs through Tier 1 automotive supplier procurement hubs in Stuttgart, Wolfsburg, and Ingolstadt with consolidated specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement functions at major appliance and electronics manufacturers, fragmenting the downstream customer base into fewer, larger specification gatekeepers with non-negotiable sustainability mandates.
For Market Incumbents: Insulate margin positions by deepening backward integration into Nordic kraft pulp sourcing through long-term fiber supply contracts that neutralize commodity index exposure. Prioritize EFSA and FDA barrier coating certification investments to capture specification-grade demand from food and beverage logistics operators facing CITEO extended producer responsibility compliance deadlines. Defensive capacity positioning in Czech and Slovak automotive clusters locks in multi-year container service relationships before regional competitors qualify alternative suppliers. For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra auto component corridors represent the most penetrable geographic white-space, where PLI scheme incentives are building manufacturing clusters without established dunnage supply relationships. Target water-resistant paper grades for Southeast Asian maritime export lanes, where moisture sensitivity has historically restricted paper adoption and barrier coating advances now enable specification displacement of synthetic void fillers. A direct sales model to centralized procurement teams at South Korean electronics manufacturers bypasses forwarder markups and accelerates vendor qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because EU Packaging and Packaging Waste Regulation mandates are structurally expanding addressable demand for recyclable paper formats while REACH and F-Gas restrictions eliminate synthetic alternatives. Acquisition targets should emphasize specialized converters with established automotive qualification protocols and active barrier coating certification pipelines rather than commodity kraft bag producers. The signal to watch is acceleration in returnable container program adoption, which locks in multi-year service contracts and reduces customer churn vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Sourcing | Captive Nordic fiber supply neutralizes commodity price volatility exposure for high-volume converters serving German automotive OEMs. |
| EFSA Barrier Coating Certification | Food-contact approval unlocks specification-grade demand from French and German organic product logistics operators under CITEO schemes. |
| Returnable Container Program Convergence | Integration with reusable automotive container systems locks in multi-year service contracts with Tier 1 suppliers in Stuttgart and Wolfsburg. |
| Regional Capacity Expansion in Czech Republic | Localized conversion capacity reduces lead times for engine component exports to Asian assembly plants from Slovak automotive suppliers. |
| Water-Resistant Grade Development | Bio-based wax coating advances enable paper dunnage specification in humid Southeast Asian maritime lanes previously reserved for synthetic foams. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers at Tier 1 automotive suppliers, dunnage converter operations directors, and logistics sustainability leads; and secondary validation against EU regulatory filings, SEC 10-K disclosures from integrated paper producers, and customs trade data on kraft pulp movements. Bottom-up triangulation across product type, material grade, and end-use segmentation dimensions reconciled with top-down market sizing from automotive export volume correlations and electronics shipment protective packaging intensity benchmarks.
Forecast inputs considered pulp price index trajectories, regulatory compliance timeline acceleration under EU Packaging and Packaging Waste Regulation implementation, and automotive production cluster geographic shifts across the analysis window. Segmentation modeling incorporated product type, material specification, end-use industry, and regional regulatory framework dimensions. CAGRs derived from regression analysis of historical protective packaging spend intensity against manufacturing output indices, cross-referenced with substitution elasticity estimates for paper versus synthetic void fillers.
Practitioners should monitor pulp commodity index volatility, EFSA certification backlog durations, and returnable container program adoption rates for early signals of forecast deviation. Quarterly review of Nordic mill capacity utilization, automotive OEM packaging guideline revisions, and extended producer responsibility scheme expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Corrugated Mailers Market