
 Paper Bubble Wrap Market | 2026-2036
Paper Bubble Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Bubble Wrap Market Analytics
E-commerce fulfillment is repositioning demand toward recyclable protective materials that satisfy unboxing expectations and sustainability mandates. Sealed Air Corporation leverages its global manufacturing footprint to supply fiber-based cushioning at scale for regional distribution centers. Papair specializes in molded paper bubble formats engineered for electronics OEMs requiring anti-static performance without plastic films. Storopack Hans Reichenecker GmbH anchors European supply through its biodegradable starch-paper hybrid lines.
Paper bubble wrap consists of kraft paper sheets embossed with air-cushioning cells through mechanical crimping or adhesive bonding, typically achieving burst strengths of 15-25 psi and grammages between 80-150 gsm to protect goods during transit. Bio-based bubble wrap segments are capturing premium positioning as brand owners seek compostable certifications for direct-to-consumer shipments. Anti-static bubble wrap occupies a defensible niche in electronics packaging where surface resistivity below 10^11 ohms prevents component damage. Standard bubble wrap retains volume leadership in shipping supplies for general merchandise.
The EU Green Deal and REACH frameworks restrict persistent plastic additives in packaging, while ECHA guidelines on recyclability shape material composition choices for suppliers accessing European markets. The US EPA promotes sustainable materials management that favors fiber-based alternatives in federal procurement. Stakeholders must monitor evolving extended producer responsibility schemes and certify compostability through ISO or home-composting standards before regional compliance deadlines harden.
Market Dynamics
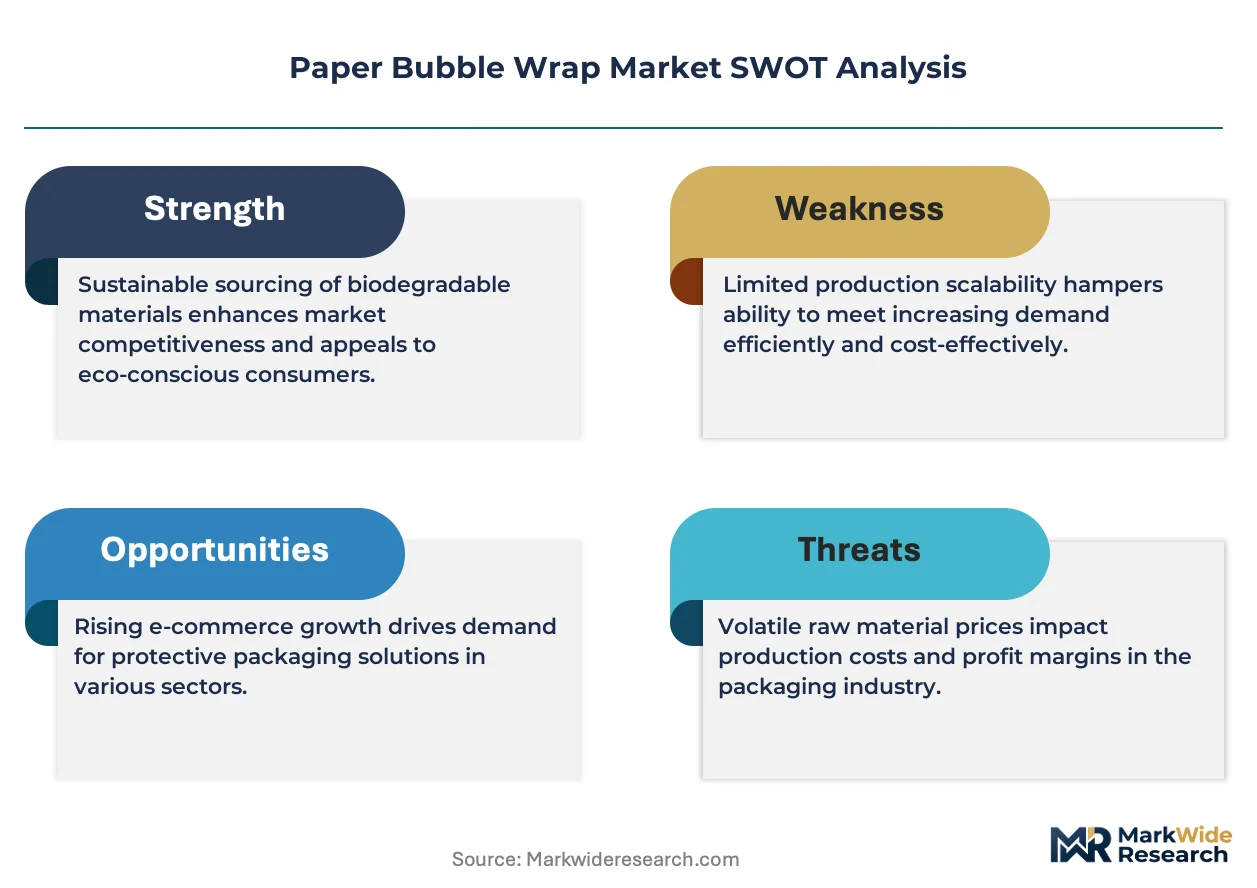
The EU Green Deal's single-use plastic restrictions are redirecting procurement decisions across European distribution networks, compressing demand timelines for fiber-based protective packaging alternatives.
Growth Catalysts
- E-commerce fulfillment expansion:Online retailers require certified curbside-recyclable cushioning to meet consumer unboxing expectations and sustainability commitments.
- REACH framework compliance:Persistent plastic additive bans under ECHA guidelines force logistics operators toward kraft-based alternatives with full material traceability.
- Automotive parts distribution:Germany's just-in-time component supply chains demand burst-resistant paper cushioning for high-value precision parts transit.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with Nordic softwood supply cycles, compressing converter margins during tight fiber markets.
- Performance ceiling:Paper bubble wrap achieves 15-25 psi burst strength versus 40+ psi for multi-layer plastic alternatives, limiting adoption in heavy-goods logistics.
- Moisture sensitivity:Cellulose-based cushioning loses structural integrity above 75% relative humidity, restricting cold-chain pharmaceutical applications without barrier coatings.
Strategic Opportunities
- Electronics anti-static niche:Surface resistivity below 10^11 ohms in molded fiber formats opens OEM supply contracts currently held by plastic film.
- Home-composting certification:ISO 17088 and OK Compost HOME standards unlock premium positioning for direct-to-consumer subscription box services.
- Starch-paper hybrid technology:Biodegradable adhesive bonding systems enable heat-sealed air cells without synthetic polymers, capturing green premium pricing.
Industry Challenges
- Extended producer responsibility timelines:EU member states implement divergent packaging fee structures, forcing suppliers to maintain multiple compliance certifications simultaneously.
- Embossing equipment retrofit costs:Converting legacy plastic bubble lines to mechanical crimping systems requires capital outlays that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Bubble Wrap Market |
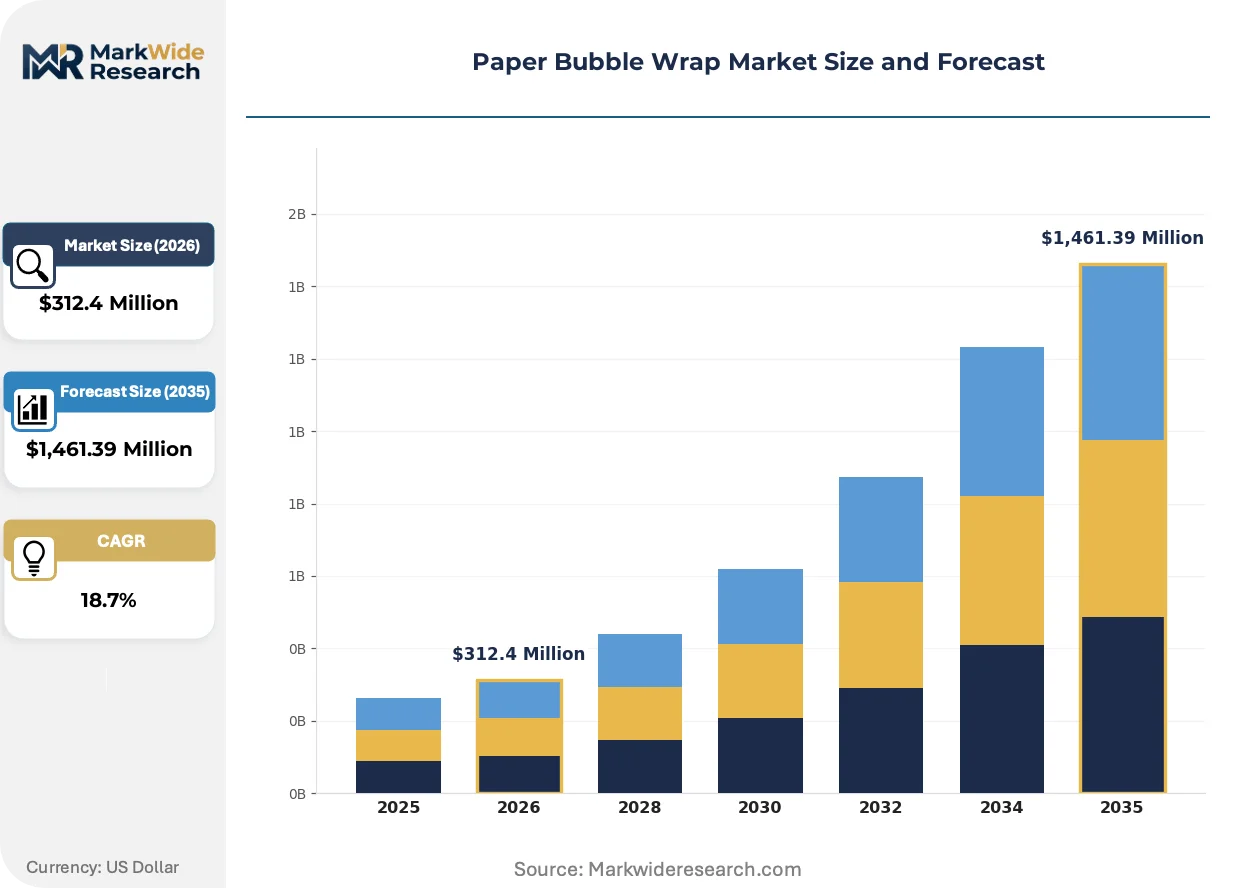
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bubble Wrap, Anti-Static Bubble Wrap, Bio-Based Bubble Wrap, Custom Size Bubble Wrap Application: Electronics Packaging, Fragile Goods Protection, Shipping Supplies, Retail Packaging End User: Manufacturers, E-Commerce, Retailers, Shipping Companies Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight |
| Companies Covered | Berry Global Group, Seaman Paper, Sealed Air Corporation, Intertape Polymer Group, LEIPA UK Ltd, Pregis LLC, Papair, Storopack Hans Reichenecker GmbH, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Bubble Wrap Market Evolving Landscape
Mechanical crimping and adhesive bonding technologies are advancing air-cell formation precision, while regulatory pressure accelerates material substitution timelines across protective packaging procurement.
Molded paper bubble formats with integrated anti-static properties are modularizing electronics packaging supply chains. Consumer electronics OEMs in South Korea and Taiwan specify these formats for semiconductor component shipments. The technology is modularizing supplier relationships by collapsing multi-material bills of materials into single-source fiber solutions.
ECHA guidelines on recyclability are hardening material composition requirements for suppliers accessing European markets. Persistent plastic additive restrictions now cover phthalate plasticizers and flame retardants common in legacy cushioning. Pharmaceutical logistics operators in the Netherlands and Belgium are responding by mandating fiber-only secondary packaging for temperature-controlled shipments.
Subscription commerce fulfillment centers are consolidating supplier relationships around certified home-compostable cushioning. Direct-to-consumer beauty and wellness brands specify OK Compost HOME-labeled protection to align with brand sustainability claims. This pattern concentrates most visibly in German and French urban distribution zones where municipal composting infrastructure supports consumer disposal behavior.
Paper Bubble Wrap Market Segmentation
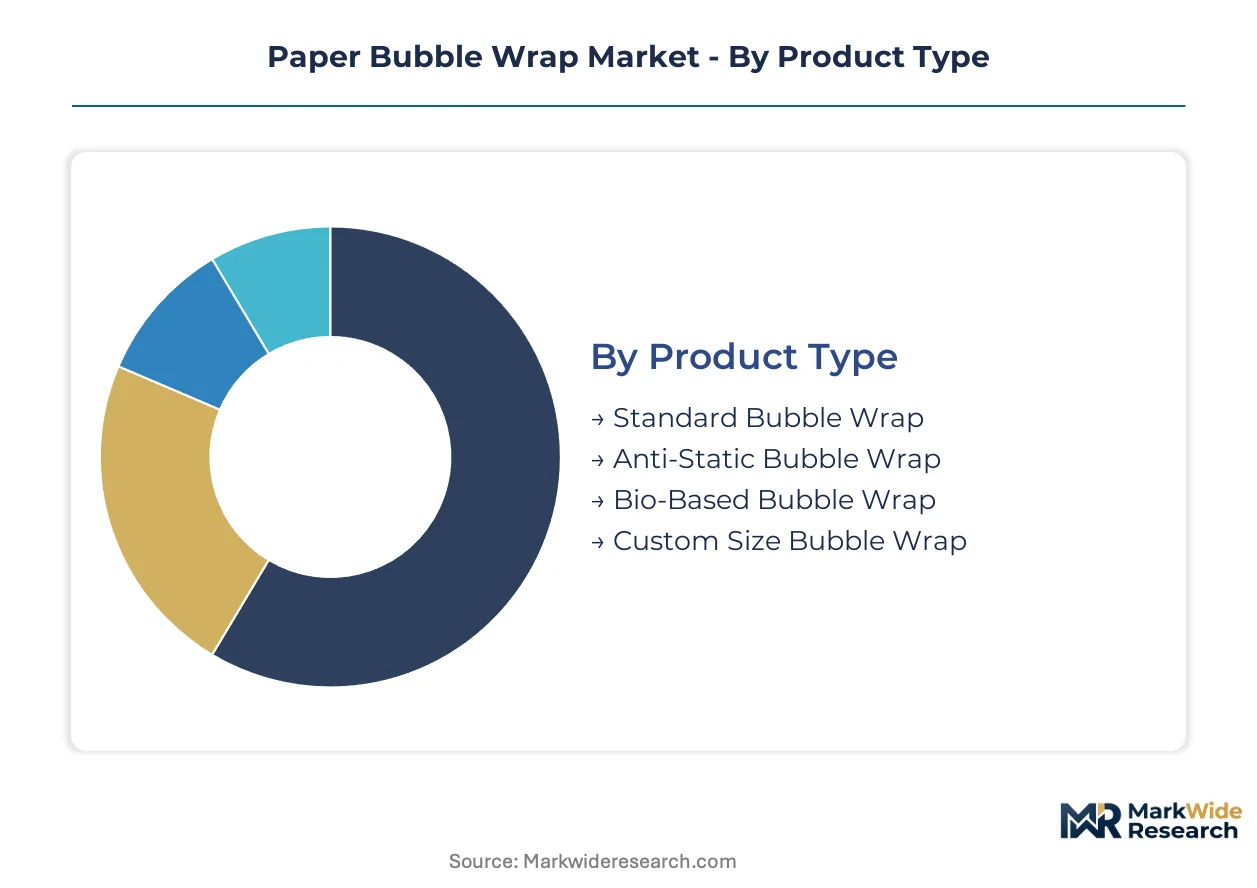
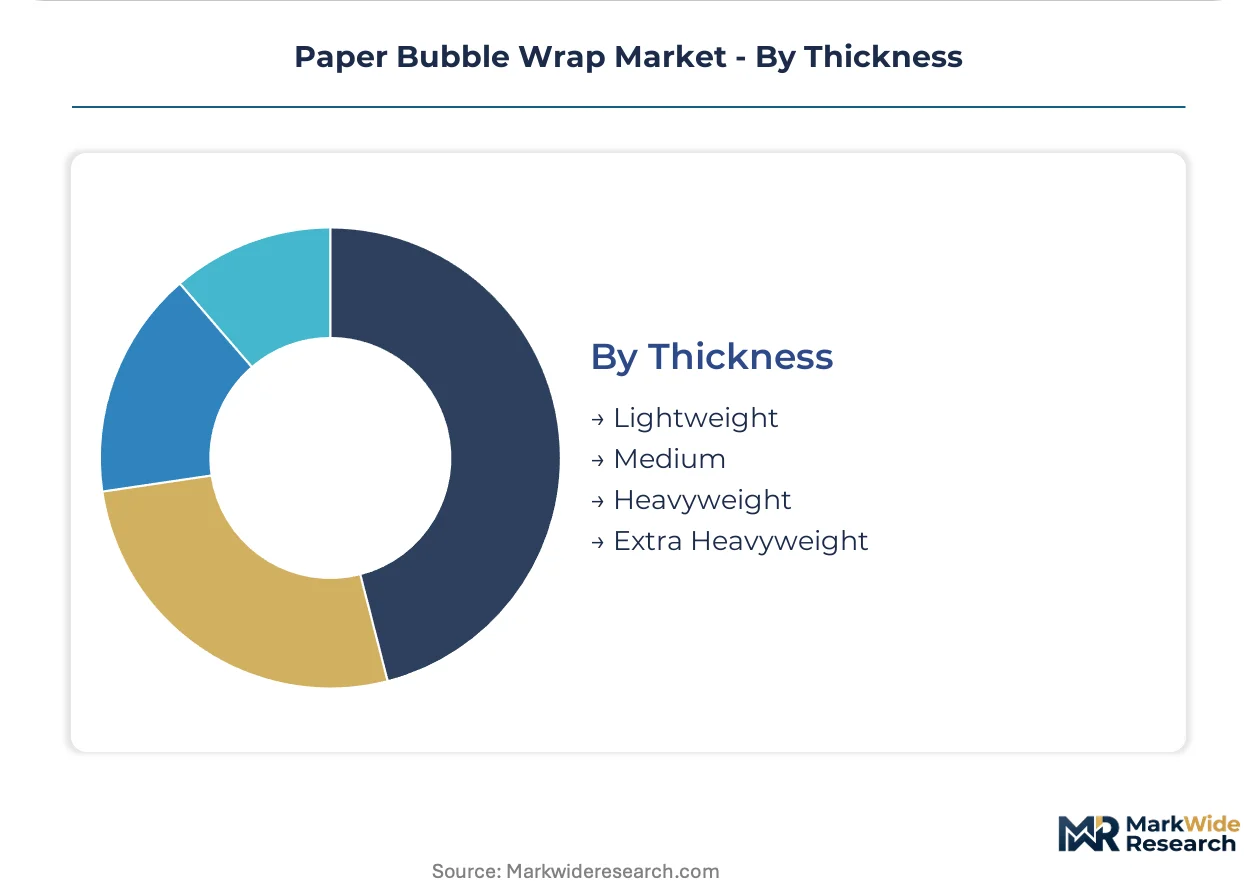
Segmentation in paper bubble wrap reveals how specification requirements diverge across protective packaging procurement. Material thickness, surface resistivity, and compostability certifications determine supplier selection criteria for distinct logistics applications.
Product Type:
Mechanical crimping and adhesive bonding technologies differentiate air-cell formation precision across material specifications.
- Standard Bubble Wrap:Kraft paper sheets embossed with air-cushioning cells achieve 15-25 psi burst strength through mechanical crimping or adhesive bonding. E-commerce fulfillment centers in Germany specify this format for general merchandise protection where curbside recyclability satisfies EU Green Deal compliance timelines.
- Anti-Static Bubble Wrap:Molded fiber formats integrate conductive additives achieving surface resistivity below 10^11 ohms. Electronics OEMs in Taiwan and South Korea specify these for semiconductor component shipments where electrostatic discharge protection prevents circuit damage.
- Bio-Based Bubble Wrap:Starch-paper hybrid constructions with biodegradable adhesive bonding systems target home-composting certification through ISO 17088 standards.
- Custom Size Bubble Wrap:Tailored dimensions address automotive parts distribution requirements for precision component fitment in just-in-time supply chains.
Mature deployment sits with Standard Bubble Wrap. Newer deployment is concentrated in Bio-Based Bubble Wrap.
Application:
End-use performance requirements shape material selection across protective packaging procurement decisions.
- Electronics Packaging:Anti-static specifications dominate OEM supply contracts where surface resistivity thresholds prevent component damage during transit. South Korean semiconductor manufacturers mandate fiber-based alternatives to plastic film cushioning.
- Fragile Goods Protection:Burst-resistant configurations protect high-value precision parts in pharmaceutical logistics where temperature-controlled shipments require structural integrity.
- Shipping Supplies:Volume procurement by distribution centers prioritizes certified curbside-recyclable formats meeting consumer unboxing expectations.
- Retail Packaging:Direct-to-consumer subscription services specify OK Compost HOME-labeled protection to align with brand sustainability claims in German and French urban zones.
Volume concentration remains in Shipping Supplies. Steepest expansion trajectory is visible in Electronics Packaging.
End User:
Procurement scale and certification requirements fragment demand across organizational buyer types.
- Manufacturers:Electronics and automotive producers specify anti-static and custom-fit formats for component protection in OEM supply chains.
- E-Commerce:Online retailers consolidate supplier relationships around certified home-compostable cushioning for direct-to-consumer fulfillment operations.
- Retailers:Brick-and-mortar and omnichannel operators require standard formats for in-store packaging and ship-from-store capabilities.
- Shipping Companies:Third-party logistics providers procure burst-resistant configurations for multi-client freight consolidation.
Procurement volume clusters with E-Commerce. Specification complexity is highest among Manufacturers.
Thickness:
Grammage and cell structure determine load-bearing capacity across weight-class protection requirements.
- Lightweight:80-100 gsm constructions suit document and small electronics protection where minimal material weight reduces freight costs.
- Medium:100-120 gsm formats balance protection density with material efficiency for general merchandise applications.
- Heavyweight:120-150 gsm configurations address automotive parts and industrial component distribution where burst resistance exceeds 20 psi.
- Extra Heavyweight:Above 150 gsm specifications target machinery and heavy-goods logistics, though adoption remains constrained by performance ceilings versus plastic alternatives.
Standard procurement concentrates in Medium thickness. Premium positioning is expanding in Heavyweight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany and the Netherlands accelerate fiber-based protective packaging concentration through EU Green Deal compliance incentives and automotive logistics clustering.
Germany
Automotive parts distribution and pharmaceutical logistics dominate procurement, with just-in-time supply chains demanding burst-resistant paper cushioning. ECHA REACH framework restrictions on persistent plastic additives redirect converters toward kraft-based alternatives with full material traceability. Stuttgart and Munich industrial corridors concentrate specification complexity among electronics and precision component manufacturers.
United States
E-commerce fulfillment centers drive volume procurement of certified curbside-recyclable formats for consumer unboxing expectations. EPA sustainable materials management guidelines favor fiber-based alternatives in federal procurement decisions. Chicago and Dallas distribution hubs anchor multi-client freight consolidation for subscription commerce operators.
China
Electronics OEMs in semiconductor and consumer device manufacturing specify molded fiber formats with anti-static properties. NMPA and GB standards on packaging recyclability shape material composition for export-oriented production. Yangtze River Delta manufacturing clusters, particularly Suzhou and Shanghai, concentrate demand for high-volume protective cushioning contracts.
Netherlands
Pharmaceutical logistics operators mandate fiber-only secondary packaging for temperature-controlled shipments under ECHA guidelines. Rotterdam and Amsterdam distribution zones serve as European entry points for compliant protective materials. Municipal composting infrastructure supports consumer disposal behavior for home-compostable certification requirements.
South Korea
Semiconductor manufacturers mandate fiber-based alternatives to plastic film cushioning for component protection during transit. MFDS pharmaceutical packaging regulations and corporate sustainability commitments accelerate material substitution timelines. Suwon and Hwaseong electronics corridors concentrate OEM supply contract specifications for anti-static surface resistivity below 10^11 ohms.
Paper Bubble Wrap Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational converters holding scale advantages in standardized formats while regional fabricators capture custom specifications. The vendor base organizes around three archetypes: global diversified packaging conglomerates with integrated fiber operations, European mid-cap specialists in molded paper technologies, and Asian contract manufacturers serving electronics OEM supply chains. Capacity expansion and portfolio diversification represent the dominant competitive moves as converters retrofit legacy plastic bubble lines and certify compostability through ISO standards.
Among diversified packaging conglomerates, Sealed Air Corporation and Berry Global Group exemplify scale-driven positioning through global manufacturing footprints and multi-material portfolio breadth. European specialists including Storopack Hans Reichenecker GmbH and Papair occupy positions anchored in biodegradable starch-paper hybrid technologies and anti-static molded fiber formats. Smurfit Kappa represents the integrated paperboard converter archetype, leveraging captive kraft supply and continental distribution infrastructure.
| Leading Market Players |
|---|
| Berry Global Group |
| Seaman Paper |
| Sealed Air Corporation |
| Intertape Polymer Group |
| LEIPA UK Ltd |
| Pregis LLC |
| Papair |
| Storopack Hans Reichenecker GmbH |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
Family-owned Nordic pulp converters anchor supply-side discipline through captive softwood fiber relationships, translating raw material cost transparency into contract pricing stability for downstream cushioning manufacturers. This ownership pattern concentrates bargaining power among kraft paper suppliers while forcing mid-tier converters to absorb margin compression during tight fiber cycles.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, while spot inventory commands discounted rates in oversupply conditions. Contract-based long-term offtake dominates procurement relationships, with price differentiation resting on ISO 17088 compostability certification tier and volume scale commitments. Cost compression in standard-grade formats is intensifying because e-commerce fulfillment centers consolidate purchasing around certified curbside-recyclable specifications. Third-party logistics providers exhibit highest price sensitivity due to multi-client freight consolidation pressures, whereas semiconductor OEMs prioritize anti-static performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for returned e-commerce shipments are expanding secondary fiber feedstock pools, reducing virgin kraft dependency for cushioning converters. Geographic supply concentration centers on Sweden, Finland, and Germany for Nordic softwood pulp, with specialty starch-paper hybrid formulations drawing from Netherlands and Belgian biopolymer developers. Raw material dependencies rest on bleached kraft pulp, biodegradable adhesive systems, and conductive additives for anti-static grades. Single-source vulnerability in conductive additive supply chains poses structural risk for electronics-focused converters. Distribution runs through Rotterdam and Hamburg port complexes into regional European distribution centers, with Yangtze River Delta manufacturing clusters serving Asian electronics OEM demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where backward control over Nordic pulp supply constitutes the decisive competitive lever. Players are pursuing captive fiber sourcing to insulate margins from commodity volatility.
For Market Incumbents: Acquire bleached kraft pulp mills in Finland or Sweden to secure fiber cost visibility and volume guarantees. Consolidate anti-static additive formulation capabilities through specialist technology acquisition, defending against emerging Asian contract manufacturers capturing semiconductor OEM contracts. Prioritize ISO 17088 certification investment to maintain premium positioning against biodegradable starch-paper hybrid entrants. For New Entrants and Emerging Players: Begin with home-compostable OK Compost HOME certification for direct-to-consumer subscription box services in German and French urban zones, the most penetrable white-space segment. Target automotive parts distribution in Stuttgart and Munich corridors where custom-fit precision requirements favor nimble regional fabricators over multinational conglomerates. Deploy modular embossing equipment with rapid changeover capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor European mid-cap specialists with biodegradable starch-paper hybrid technology in Netherlands and Belgium during pulp price spike periods. Long-term viability over the next decade rests on regulatory tailwinds from EU Green Deal implementation and REACH framework hardening. Monitor ECHA persistent plastic additive restriction enforcement timelines as the critical inflection signal for fiber-based substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive fiber sourcing from Swedish and Finnish softwood mills insulates margin compression during tight supply cycles. |
| Anti-Static Additive Formulation Acquisition | Conductive technology control secures semiconductor OEM contracts from South Korean and Taiwanese manufacturers. |
| Home-Composting Certification Program | OK Compost HOME labeling unlocks premium positioning for German and French direct-to-consumer subscription services. |
| Mechanical Crimping Equipment Retrofit | Legacy plastic bubble line conversion enables EU Green Deal compliance without greenfield capital deployment. |
| Long-Term Supply Agreement with E-Commerce Fulfillment Centers | Curbside-recyclable cushioning contracts with Chicago and Dallas distribution hubs anchor volume procurement. |
Research Methodology
Multi-period observation of pulp price indices, e-commerce shipment volumes, and regulatory compliance deadlines anchored the trend analysis, supplemented by interviews with plant managers at Nordic pulp mills, procurement leads at German automotive Tier 1 suppliers, technical R&D directors at cushioning converters, and distribution channel partners in Rotterdam and Hamburg port complexes. Secondary validation drew from ECHA REACH framework documentation, EU Green Deal implementation timelines, customs and trade data for kraft paper imports, and SEC filings of diversified packaging conglomerates. Bottom-up shipment data triangulated against top-down market sizing from production capacity assessments.
Input-output matrix modeling connected fiber supply volumes through converter capacity utilization to end-use demand segments across the projection horizon. Segmentation dimensions included product type, application end-use, thickness grade, and regional regulatory cluster. CAGRs were derived from elasticity-based demand projection calibrated against historical substitution rates from plastic to fiber-based cushioning. Industry-specific forecast inputs incorporated EU member state extended producer responsibility fee structure implementation and semiconductor manufacturing capacity expansion in South Korea and Taiwan.
Underlying measurement precision varies by segment; anti-static and bio-based categories carry tighter precision than standard-grade formats due to concentrated supplier populations and certification audit trails. Forecasts reflect assumptions on regulatory enforcement timelines and pulp price cycle normalization. Practitioners should monitor ECHA persistent plastic additive restriction announcements and Nordic softwood inventory reports for early signals of substitution acceleration or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Greyboard Market