
 China Rigid Plastic Packaging Market | 2026-2036
China Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Rigid Plastic Packaging Market Insights
Guangdong province is reshaping competitive dynamics through expanded PET preform and injection-molding capacity serving southern China's export-oriented manufacturing belt. Tianjin Wanhua Group leverages its northern China petrochemical integration to sustain cost advantages in polypropylene container supply. Zhuhai Zhongfu Enterprise Co. Ltd. anchors the Pearl River Delta's beverage packaging cluster with specialized two-stage stretch blow molding operations. Zhejiang Yinjie Holding Group differentiates through high-cavitation mold technology for thin-wall food containers.
China rigid plastic packaging comprises thermoformed or injection-molded structures manufactured from polyethylene, polypropylene, PET, or PVC with wall thickness typically exceeding 0.25 millimeters, engineered to protect contents from mechanical damage, moisture ingress, and gas permeation across distribution cycles. Polyethylene sustains dominant volume in pails and industrial containers where chemical resistance and impact strength command priority. PET bottles capture the fastest structural expansion, driven by carbonated soft drink and bottled water demand requiring clarity and barrier performance. Trays and clamshells occupy concentrated margin pools in fresh produce and electronics applications where dimensional precision and retail presentation justify premium positioning.
MEE enforcement of dual carbon goals and GB standards for recycled content are tightening material traceability requirements across the value chain, while SAMR food contact regulations govern additive migration limits in polyethylene and polypropylene food packaging. NMPA pharmaceutical packaging directives further constrain PVC blister specifications for solid oral dosage forms. Stakeholders must monitor regulatory calibration between carbon reduction mandates and food safety compliance as recycled feedstock integration accelerates.
Market Dynamics
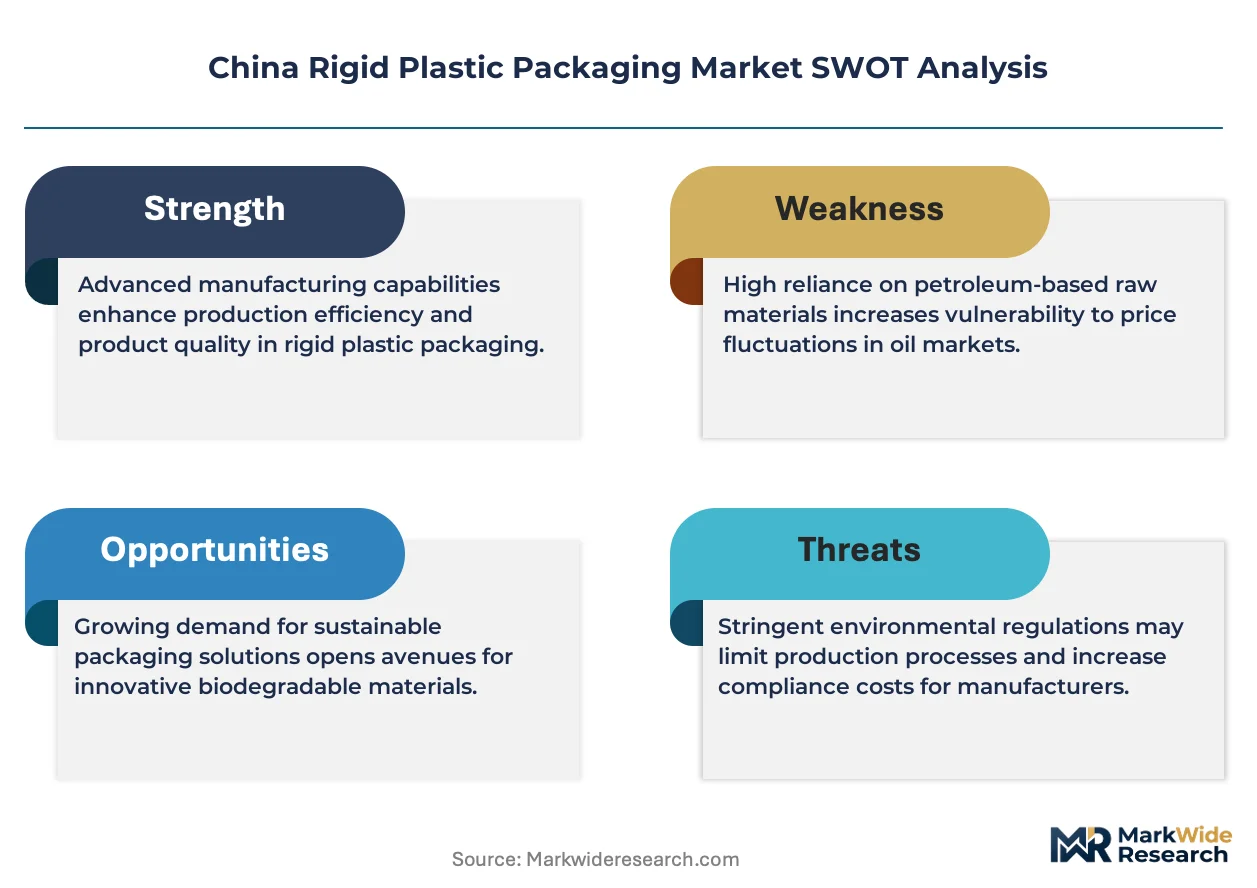
China's rigid plastic packaging sector faces a structural compression between MEE carbon enforcement and SAMR food contact mandates, forcing processors to reconfigure material flows while maintaining compliance across dual regulatory tracks.
Growth Catalysts
- Dual carbon targets:MEE-mandated carbon intensity reductions are accelerating plant retrofits for recycled PET integration in beverage bottling operations.
- Yangtze River Delta concentration:Shanghai-Jiangsu manufacturing clusters provide captive blow-molding infrastructure for domestic consumer brand expansion.
- Lightweighting technology:High-cavitation thin-wall injection systems are displacing conventional container weights in condiment and dairy applications.
Market Restraints
- Feedstock cost volatility:Polypropylene pricing ties to naphtha-cracker economics, exposing converters to petrochemical margin squeezes.
- Recycled content traceability gaps:GB standards for post-consumer rPET lack harmonized chain-of-custody verification, creating compliance uncertainty.
- Aluminum can substitution:Carbonated beverage brands are piloting metal alternatives for premium positioning and circularity claims.
Strategic Opportunities
- Western China penetration:Chengdu-Chongqing corridor offers underdeveloped cold-chain packaging demand for fresh produce distribution.
- Pharmaceutical barrier films:NMPA-compliant PVC-alternative blister materials for solid oral dosage forms represent technical white space.
- Digital printing convergence:Direct-to-object inkjet on rigid containers enables short-run customization for regional brand variants.
Industry Challenges
- Recycled feedstock purification:Food-grade rPET flake processing requires capital-intensive super-cleaning lines that strain mid-cap balance sheets.
- Cross-regional logistics reconfiguration:Migrating production inland to meet carbon targets disrupts established Yangtze Delta supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Rigid Plastic Packaging Market |
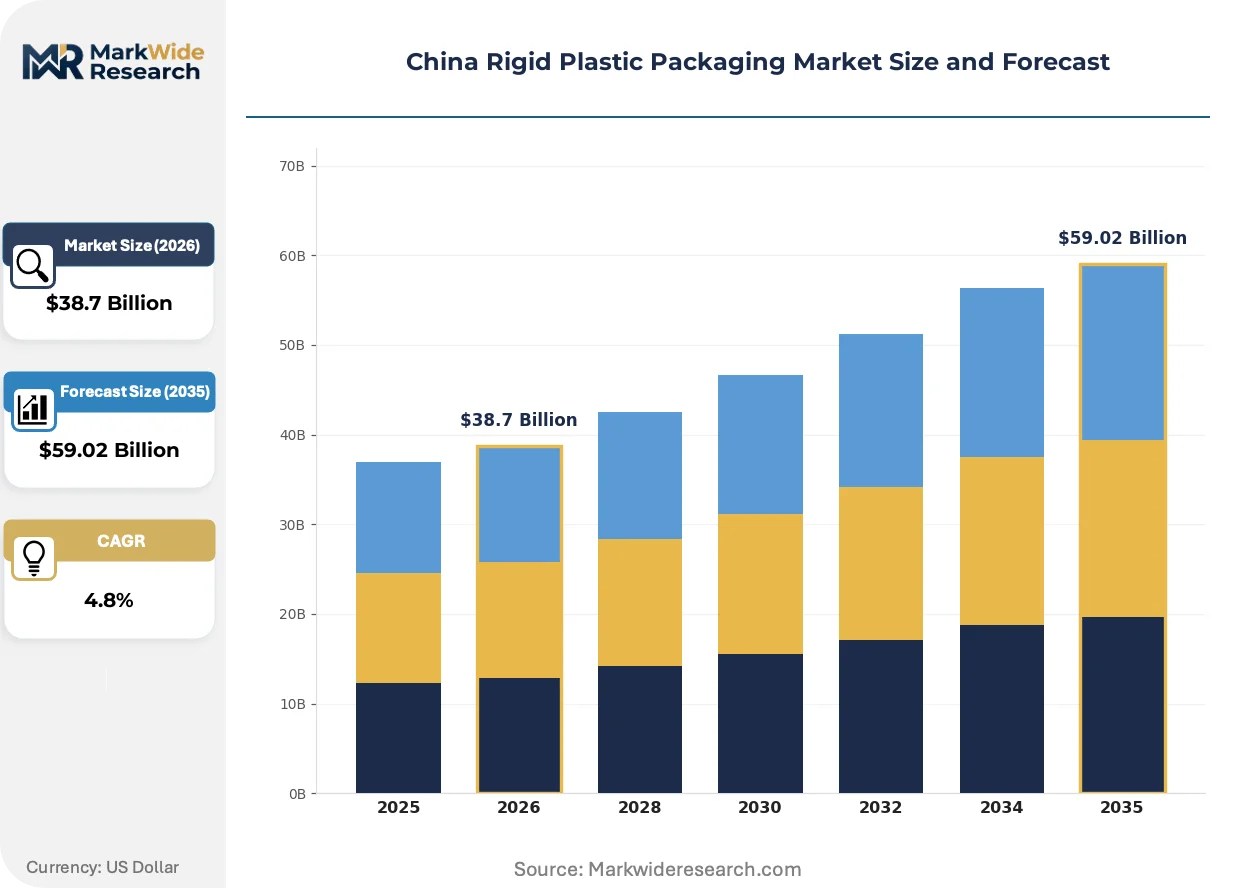
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Packaging Type: Rigid Boxes, Clamshells, Pails, Blisters |
| Companies Covered | Tianjin Wanhua Group, Sunglow Packaging, Zhejiang Yinjie Holding Group, Shanghai Muliang Packaging, Foshan Nanhai Shuangxing Packing, Southeast Plastic Company, Shanghai Jielong Packaging, Zhuhai Zhongfu Enterprise Co. Ltd., Hong Kong Huada Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Rigid Plastic Packaging Market Trends and Innovations
China's rigid packaging base is reengineering around carbon accounting transparency and material circularity, with technology investments prioritizing traceability infrastructure over capacity expansion.
Smart manufacturing systems are digitizing quality assurance workflows across blow-molding operations. Zhuhai-based beverage converters deploy machine-vision defect detection linked to real-time cavity-pressure monitoring. This sensor integration is digitizing scrap-rate tracking and enabling predictive maintenance schedules that compress unplanned downtime.
SAMR's tightened GB 4806 additive migration limits are forcing polypropylene food container reformulation. Processors must validate new antioxidant packages through extended extraction testing protocols. Dairy and condiment segments are responding by qualifying alternative nucleating agents that maintain clarity while meeting tightened specific migration limits for heavy metals.
Brand procurement teams are consolidating supplier panels around integrated carbon reporting capabilities. Domestic consumer packaged goods groups now require Scope 3 emissions disclosure from rigid packaging vendors. This accountability shift is most visible among Shanghai-headquartered beverage multinationals sourcing PET preforms from Jiangsu province molders.
China Rigid Plastic Packaging Market Segmentation
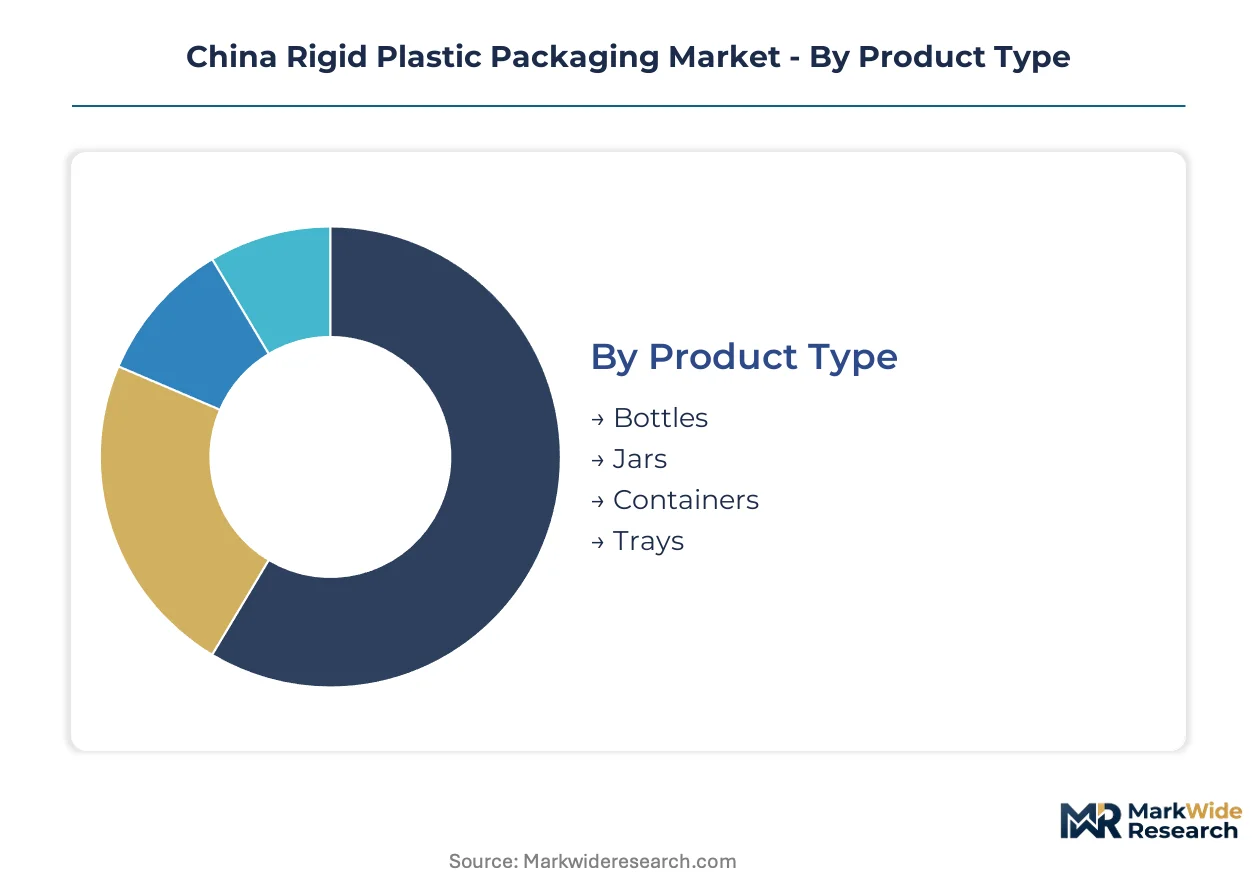
Segmentation in China's rigid plastic packaging market reveals distinct technical requirements and regulatory pressures across product formats. Each category carries unique carbon accounting obligations under MEE oversight and food contact compliance thresholds set by SAMR.
Product Type:
After-sales service intensity varies sharply across product categories, with bottles requiring the most intensive technical support for blow-molding calibration and defect resolution.
- Bottles:Two-stage stretch blow-molded structures dominate carbonated beverage and bottled water applications. Demand clusters in the Yangtze River Delta where Shanghai-based beverage brands source from Jiangsu province converters. MEE carbon intensity audits now mandate recycled PET integration rates that strain super-cleaning line capacity.
- Trays:Thermoformed PET and PP structures serve fresh produce and electronics retail presentation. Chengdu-Chongqing corridor cold-chain expansion is driving tray specification upgrades for temperature stability. SAMR food contact additive migration limits force reformulation of nucleating agent packages.
- Jars:Wide-mouth injection-molded containers carry condiment and dairy applications. Guangdong province converters specialize in high-clarity PP formulations.
- Containers:Industrial pails and drums leverage HDPE chemical resistance. Tianjin Wanhua Group's northern petrochemical integration supplies captive polypropylene.
By volume, bottles lead. By growth pace, trays are expanding most quickly.
Material:
Cost tier stratification separates commodity resins from performance grades requiring specialized compounding and additive packages.
- PET:Virgin and recycled grades command premium positioning in beverage clarity applications. Yangtze Delta blow-molders face capital strain from GB standard chain-of-custody verification requirements for post-consumer flake.
- Polypropylene:Random and impact copolymers dominate thin-wall food containers. Zhejiang Yinjie Holding Group differentiates through high-cavitation mold technology reducing unit weights.
- Polyethylene:HDPE sustains industrial pail dominance where chemical resistance and impact strength outweigh clarity requirements.
- PVC:Pharmaceutical blister applications face NMPA constraint pressure as solid oral dosage form specifications tighten.
Polyethylene holds volume leadership. PET climbs the fastest on carbon target alignment.
End User:
Application-specific compliance regimes create divergent margin structures across customer verticals.
- Food & Beverage:Carbonated soft drinks and bottled water drive PET bottle specification intensity. SAMR GB 4806 additive migration limits force antioxidant package revalidation across dairy and condiment segments.
- Pharmaceuticals:NMPA blister packaging directives constrain PVC specifications while creating technical white space for barrier film alternatives. Domestic generic drug manufacturers consolidate supplier panels around integrated carbon reporting.
- Personal Care:Premium positioning demands drive digital printing adoption for regional brand variant customization.
- Household Products:Industrial chemical resistance requirements favor HDPE pail specifications with lower recycled content tolerance.
Food and beverage commands volume concentration. Pharmaceuticals show steepest expansion trajectory on regulatory-driven material upgrades.
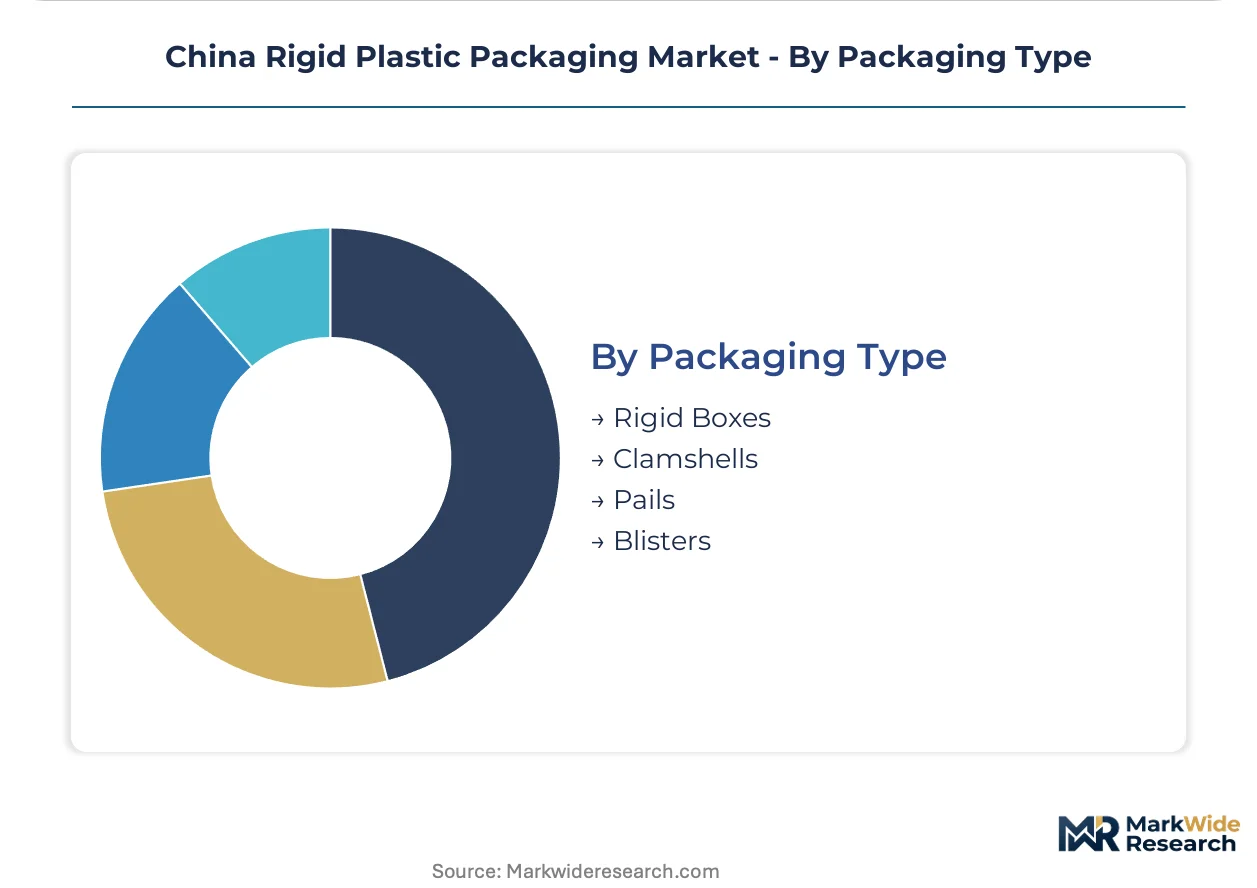
Packaging Type:
Supply concentration patterns align with regional manufacturing cluster specialization rather than end-user dispersion.
- Clamshells:Thermoformed PET structures serve fresh produce retail presentation. Pearl River Delta converters leverage export-oriented manufacturing belt proximity.
- Blisters:PVC and alternative barrier films package solid oral dosage forms under NMPA directive pressure. Technical qualification timelines extend supplier relationships.
- Pails:HDPE industrial containers tie to northern China petrochemical feedstock access. Tianjin-based integration sustains cost positioning.
- Rigid Boxes:Electronics and premium goods applications demand dimensional precision from injection-molding operations concentrated in Jiangsu province.
Clamshells lead by unit volume. Blisters gain share fastest on pharmaceutical packaging upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites eastern China's dominance in rigid plastic packaging, with Shanghai's container throughput anchoring PET resin import flows and finished goods export capacity.
Yangtze River Delta
Shanghai-headquartered beverage multinationals drive PET bottle specification intensity across carbonated soft drink and bottled water segments. MEE carbon intensity audits mandate recycled PET integration rates that strain super-cleaning line capacity in Jiangsu province. Suzhou and Wuxi host the densest concentration of two-stage stretch blow-molding operations serving domestic consumer brands.
Pearl River Delta
Guangdong province's export-oriented manufacturing belt sustains thermoformed clamshell demand for fresh produce retail presentation. SAMR food contact additive migration limits force reformulation of nucleating agent packages in thin-wall food containers. Zhuhai anchors specialized beverage packaging clusters with proximity to Hong Kong logistics corridors.
Beijing-Tianjin-Hebei
Northern China's petrochemical integration supports polypropylene container supply for industrial pail applications. Tianjin Wanhua Group leverages captive feedstock access to sustain cost positioning in HDPE chemical-resistant packaging. The region's steel-aluminum industrial base creates competitive pressure for plastic substitution in carbonated beverage formats.
Sichuan-Chongqing
The Chengdu-Chongqing corridor offers underdeveloped cold-chain packaging demand for fresh produce distribution westward. GB standards for post-consumer rPET lack harmonized chain-of-custody verification, creating compliance uncertainty for inland processors. Chongqing's automotive manufacturing presence diverts polymer supply toward industrial applications.
Shandong Peninsula
Qingdao's port infrastructure supports PET resin import flows for northern beverage bottling operations. NMPA pharmaceutical packaging directives constrain PVC blister specifications, creating technical qualification timelines that extend supplier relationships. Yantai and Weihai host emerging thin-wall injection-molding capacity for condiment and dairy segments.
China Rigid Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and mold fabrication. The vendor base organizes around three strategic archetypes: petrochemical-integrated converters with captive resin access, high-cavitation mold technology specialists, and regional logistics-anchored fabricators serving brand procurement consolidation. Competitive moves concentrate on capacity relocation inland to meet carbon targets and supplier panel consolidation around integrated Scope 3 emissions disclosure.
Within the petrochemical-integrated tier, Tianjin Wanhua Group exemplifies northern China's feedstock-advantaged positioning. Among Yangtze Delta specialists, Zhejiang Yinjie Holding Group occupies a position representing high-cavitation mold technology for thin-wall applications. Zhuhai Zhongfu Enterprise Co. Ltd. anchors the Pearl River Delta's beverage packaging cluster.
| Leading Market Players |
|---|
| Tianjin Wanhua Group |
| Sunglow Packaging |
| Zhejiang Yinjie Holding Group |
| Shanghai Muliang Packaging |
| Foshan Nanhai Shuangxing Packing |
| Southeast Plastic Company |
| Shanghai Jielong Packaging |
| Zhuhai Zhongfu Enterprise Co. Ltd. |
| Hong Kong Huada Group |
| Others |
Pricing and Supply Chain Analysis
Feedstock cost volatility in polypropylene and PET resin determines both tiered pricing spreads and supply chain configuration across China's rigid plastic packaging sector. Naphtha-cracker economics expose converters to petrochemical margin squeezes that compress mid-tier pricing while reinforcing premium positioning for integrated producers with captive resin access.
Pricing Analysis
Volume-discount tiering structures separate multinational beverage brands securing long-term offtake contracts from regional condiment processors purchasing spot-market resin. Price differentiation hinges on recycled content certification grade under GB standards and blow-molding cavitation scale, with super-cleaning line investment separating food-grade rPET premiums from industrial-grade spreads. Cost compression in standard-tier containers intensifies as aluminum can substitution trials gain traction among carbonated beverage marketers. Domestic consumer packaged goods groups exhibit highest price sensitivity due to procurement consolidation mandates, while pharmaceutical blister specifications tolerate premium positioning for NMPA-compliant barrier alternatives.
Supply Chain Analysis
Contract-manufacturing concentration sits with Yangtze River Delta blow-molders and Pearl River Delta thermoformers serving export-oriented manufacturing belts. Geographic supply concentration centers on Jiangsu province PET preform operations, Guangdong clamshell fabricators, and Tianjin-anchored HDPE industrial pail production. Raw material dependencies draw from Sinopec and PetroChina virgin resin allocations, imported PTA feedstocks, and domestically sourced post-consumer flake collections. Single-source vulnerability runs through super-cleaning line equipment for food-grade rPET certification. Distribution runs through Shanghai port container throughput for resin imports and finished goods export positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's rigid plastic packaging sector operates as a substitution defense against aluminum can encroachment in carbonated beverages and fiber-based alternatives in fresh produce retail presentation. Incumbents must navigate material circularity mandates while preserving cost positioning against metal competitors.
For Market Incumbents: Harden barrier performance credentials in pharmaceutical blister applications where NMPA compliance creates technical moats against polymer substitution. Deepen backward integration into rPET flake purification to secure food-grade supply chains ahead of MEE-mandated recycled content thresholds. Consolidate supplier relationships around integrated carbon reporting to meet Scope 3 disclosure demands from Shanghai-headquartered beverage multinationals.
For New Entrants and Emerging Players: Western China cold-chain packaging gaps in the Chengdu-Chongqing corridor represent the most penetrable entry point for fresh produce tray specifications underserved by Yangtze Delta logistics networks. Digital printing convergence for short-run regional brand customization offers technical differentiation against incumbent scale economies. Target pharmaceutical barrier film alternatives to PVC as technical white space with extended qualification timelines that favor patient capital deployment.
For Investors and Strategic Acquirers: SAMR's tightened GB 4806 additive migration limits reshape the acquisition landscape toward processors with validated antioxidant reformulation capabilities and nucleating agent substitution track records. Five-to-ten-year viability favors high-cavitation mold technology specialists with thin-wall food container expertise over commodity blow-molders exposed to resin volatility. Monitor MEE carbon intensity audit enforcement cadence as the signal for accelerated plant retrofit requirements and super-cleaning line capacity shortages.
| Strategic Initiative | Industry Significance |
|---|---|
| Super-Cleaning Line Capacity Expansion | Food-grade rPET flake purification secures MEE compliance for beverage bottlers ahead of mandatory recycled content thresholds. |
| High-Cavitation Mold Technology Investment | Thin-wall injection systems displace unit weights in condiment applications while meeting SAMR additive migration limits. |
| Western China Manufacturing Relocation | Chengdu-Chongqing corridor positioning captures underdeveloped cold-chain demand while reducing carbon intensity audit exposure. |
| Digital Printing Convergence Partnership | Direct-to-object inkjet integration enables short-run customization for regional brand variants without mold changeover costs. |
| Pharmaceutical Barrier Film Qualification | NMPA-compliant PVC-alternative blister materials extend supplier relationships through technical qualification timelines. |
Research Methodology
Operator-level perspectives from blow-molding plant managers, PET resin procurement leads at beverage multinationals, SAMR regulatory affairs specialists, and cold-chain logistics coordinators anchored the qualitative base. Secondary validation drew from MEE carbon intensity audit disclosures, SAMR GB standard publication records, Sinopec resin pricing bulletins, and Shanghai port customs data. Bottom-up capacity assessments across Jiangsu and Guangdong manufacturing clusters triangulated against top-down demand modeling from beverage brand procurement consolidation patterns.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, material grade tier, end-use vertical compliance regime, and regional manufacturing hub concentration. CAGRs derived from resin demand elasticity modeling and substitution threat penetration curves. Industry-specific forecast inputs incorporated MEE dual carbon target enforcement trajectories and SAMR food contact additive package revalidation timelines.
Practitioners should monitor naphtha-cracker margin compression, aluminum can pilot program expansion, and GB standard chain-of-custody verification harmonization for early signals of forecast revision. Quarterly review of MEE audit enforcement cadence, SAMR additive migration limit calibration, and Yangtze Delta logistics cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market