
 Display Paper Box Market | 2026-2036
Display Paper Box Market Size, Share, and Industry Trends Forecast 2026-2036
Display Paper Box Market Analysis
Market Context
Retail shelf placement channels are rewriting how display paper box suppliers capture value in consumer-facing categories. DS Smith leverages its European corrugated network to control high-volume grocery display programs. Smurfit Kappa Group anchors Latin American retail expansion with localized pallet display manufacturing. Mondi Group differentiates through barrier-coated kraft solutions that extend shelf visibility for perishable goods.
Technical Definition and Segment Structure
Display paper boxes are engineered point-of-sale structures, typically fabricated from corrugated fiberboard or solid bleached sulfate board in calipers ranging from 18 pt to 48 pt, designed to present merchandise at eye level while withstanding 30-90 days of retail traffic. Corrugated fiberboard dominates material selection for floor displays and pallet displays due to stacking strength and printability, while solid bleached sulfate commands margin pools in cosmetics counter displays where surface smoothness enables high-fidelity lithographic branding. Custom designs represent the fastest-growing design type as retailers demand modular, campaign-specific structures that reduce obsolescence risk.
Regulatory Frame and Outlook
EU REACH and the F-Gas Regulation constrain adhesive and coating chemistries in European-manufactured display boxes, while FDA food-contact substance notifications govern board coatings for U.S. retail food applications. China's GB standards and SAMR packaging rules enforce recyclability labeling that shapes material selection for export-bound production. Stakeholders must monitor how extended producer responsibility schemes in multiple geographies reshape cost allocation between converters and retail brands.
Market Dynamics
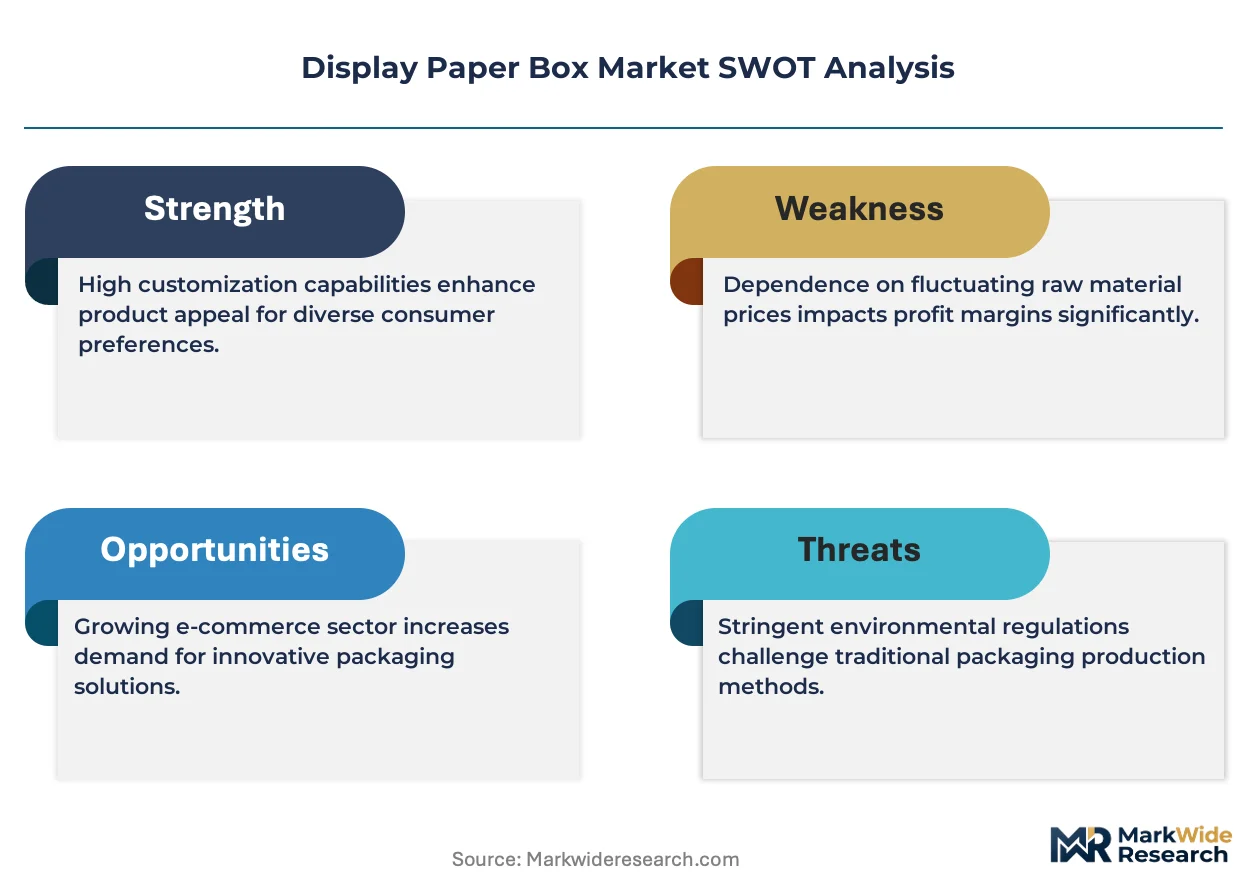
EU REACH and the F-Gas Regulation are compressing adhesive formulation options for European converters while China's GB standards mandate recyclability labeling that reshapes material sourcing for export-bound production.
Growth Catalysts
- EU Green Deal compliance mandates:Retail chains in Germany and France now require FSC-certified display structures for shelf placement, pulling premium rigid box demand from cosmetics brands.
- Digital printing convergence:UV inkjet systems enable campaign-specific graphics on corrugated fiberboard without plate costs, shortening production cycles for seasonal promotions.
- China:Domestic retail chains including Hema Fresh and 7Fresh are scaling in-store promotional infrastructure, concentrating pallet display demand in tier-one cities.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import restrictions on recovered paper, squeezing converter margins in North America and Europe.
- Structural limitation:Solid bleached sulfate board lacks the stacking strength for pallet displays, confining it to counter applications and capping volume in mass retail.
- Substitution pressure:Reusable plastic crates from Tosca and IFCO Systems displace one-trip corrugated displays in closed-loop grocery supply chains.
Strategic Opportunities
- India:Organized retail penetration remains below 10 percent, creating whitespace for point-of-sale infrastructure as Reliance Retail and D-Mart expand store networks.
- Barrier-coated kraft:Mondi Group's solutions extend shelf visibility for perishables, opening fresh produce and dairy applications previously closed to uncoated fiberboard.
- Extended producer responsibility schemes:France's CITEO and Germany's ZSVR shift disposal costs to brand owners, incentivizing design-for-recycling contracts with specialized converters.
Industry Challenges
- Structural engineering talent scarcity:Converters struggle to hire designers fluent in both CAD-based die-line development and retail traffic load modeling.
- Multi-jurisdiction certification lag:FDA food-contact notifications for board coatings add 90-180 days to product launches for U.S. grocery clients.
Report Scope
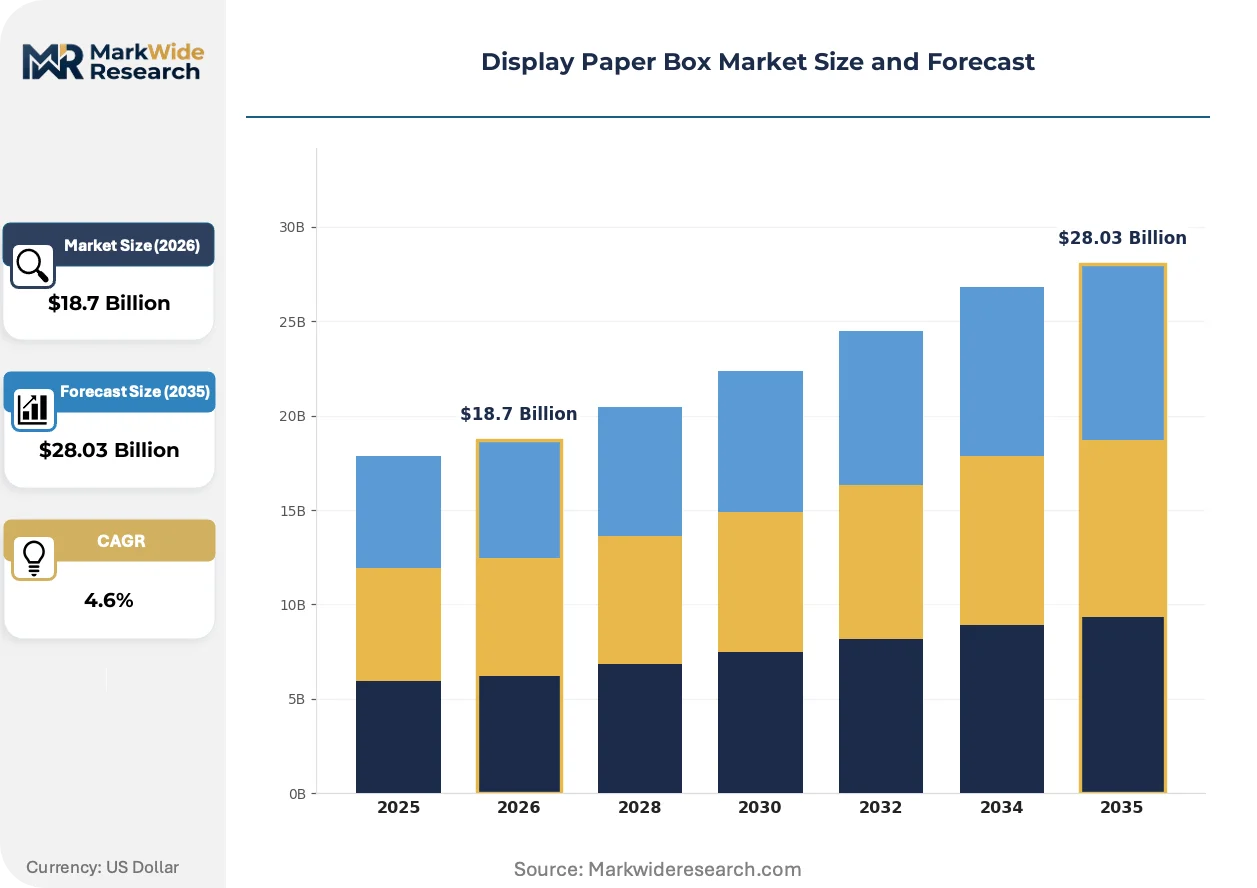
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Paper Box Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counter Displays, Floor Displays, Dump Bins, Pallet Displays Material: Recycled Paper, Corrugated Fiberboard, Solid Bleached Sulfate, Kraft Paper End User: Retail Stores, Supermarkets, Online Retailers, Exhibitions Design Type: Custom Designs, Standard Designs, Eco-Friendly Designs, Seasonal Designs |
| Companies Covered | DS Smith, International Paper, Smurfit Kappa Group, WestRock, Mondi Group, Sonoco, Menasha, Huhtamäki Oyj, VPK Packaging Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Paper Box Market Emerging Trajectories
Active reshaping of the display paper box market centers on three vectors: material science compression of functional trade-offs, regulatory chemistry constraints, and procurement model compression that favors modular campaign structures over permanent fixtures.
Water-based barrier coatings are collapsing the historical performance gap between coated kraft and plastic alternatives in moisture-sensitive applications. Fresh produce retailers in the Netherlands and Belgium are adopting these structures for misted vegetable displays. The technology is collapsing resistance to fiberboard in categories previously reserved for PET or PP trays.
REACH Annex XVII restrictions on perfluorinated compounds are forcing adhesive reformulation across European production networks. Converters serving L'Oréal and Estée Lauder must validate new chemistries through ECHA notification pathways. Luxury cosmetics counter displays face the steepest compliance timeline compression.
Retailers are compressing promotional cycles from quarterly to monthly refresh rates. Walmart's modular display specifications now require 48-hour turnaround on design variants. This behavioral shift favors converters with in-house digital print capacity and collapses the planning window for traditional offset-dependent suppliers.
Display Paper Box Market Segmentation
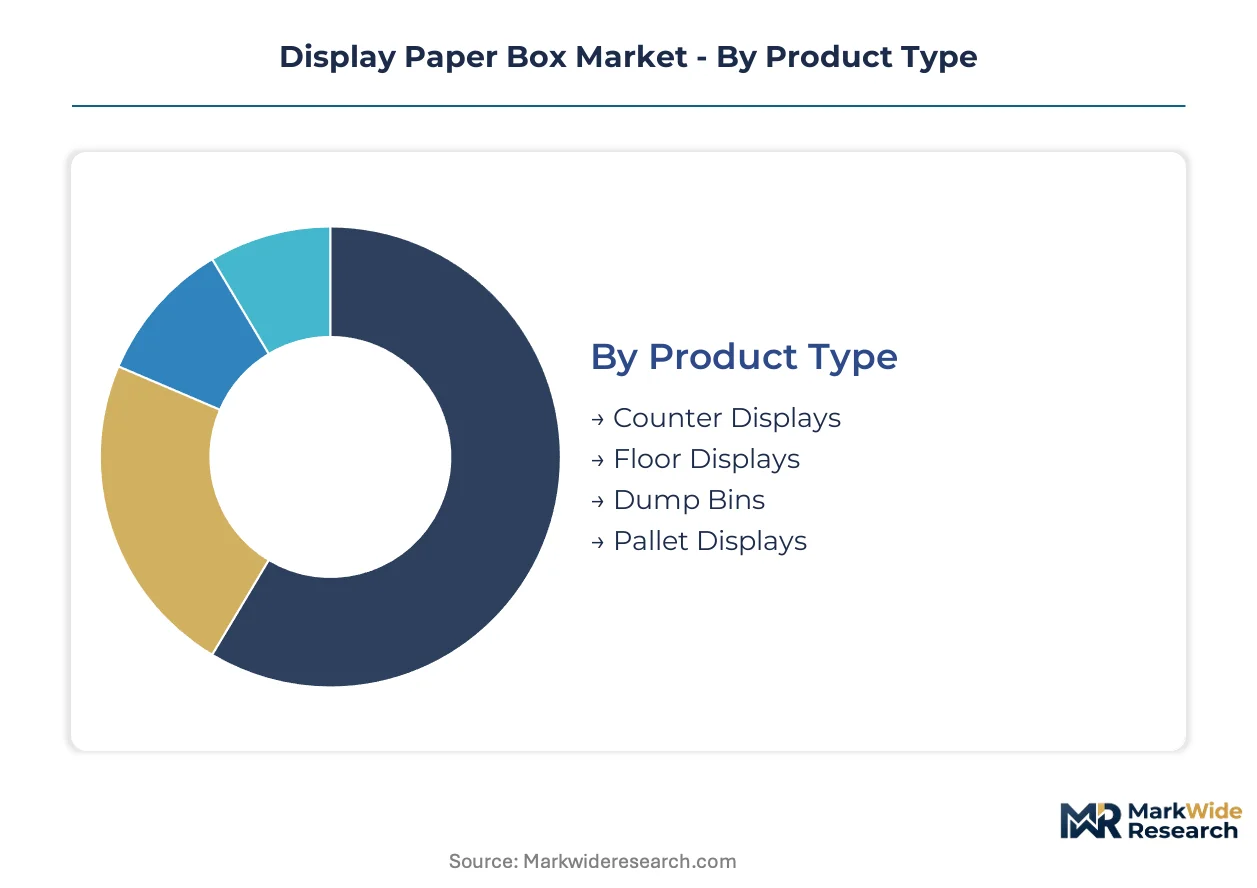
Display paper box procurement patterns diver sharply by retail environment and campaign velocity. Segmentation reveals how material selection, structural format, and design flexibility map to distinct margin pools across consumer-facing channels.
Product Type:
Use-case spectrum spans impulse-triggering countertop units to high-traffic floor installations and automated replenishment systems.
- Counter Displays:Compact structures fabricated from solid bleached sulfate board in 18-24 pt calipers, engineered for cosmetics and confectionery placement at checkout zones. L'Oréal and Estée Lauder procurement concentrates here, driven by EU REACH compliance mandates for adhesive chemistries in luxury retail environments.
- Floor Displays:Freestanding units constructed from double-wall corrugated fiberboard rated for 30-90 day retail traffic cycles. Walmart and Target specifications favor modular designs with 48-hour graphic turnaround capability, compressing production planning windows for seasonal campaigns.
- Dump Bins:Open-top gravity-fed containers for high-volume consumables and clearance merchandise. Bulk retail adoption in Germany and France requires FSC-certified substrates.
- Pallet Displays:Full-pallet structures integrating base pads, headers, and side panels for automated warehouse-to-floor deployment. Hema Fresh and 7Fresh in China are scaling procurement for fresh produce and dairy categories.
The dominant share belongs to Floor Displays, while Pallet Displays are closing the gap fastest.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered substrates with barrier functionality.
- Recycled Paper:Post-consumer fiber content ranging from 30% to 100%, primarily serving price-sensitive promotional campaigns with shorter display lifespans. Chinese GB standards mandate recyclability labeling that constrains export-bound sourcing.
- Corrugated Fiberboard:Fluted medium sandwiched between linerboards in E, B, or C-flute configurations, delivering stacking strength for pallet and floor applications. DS Smith and Smurfit Kappa manufacturing networks anchor European and Latin American supply.
- Solid Bleached Sulfate:Bleached virgin kraft pulp forming smooth, printable surfaces in 18-48 pt calipers. Surface smoothness enables high-fidelity lithography for cosmetics counter displays, though stacking limitations confine volume to non-pallet applications.
- Kraft Paper:Unbleached virgin or recycled fiber with natural aesthetic positioning. Mondi Group's barrier-coated variants extend shelf visibility for misted produce in Dutch and Belgian retail chains.
Corrugated Fiberboard commands volume leadership, with Kraft Paper expanding most quickly through barrier coating innovation.
End User:
Customer type determines structural specification, replenishment frequency, and compliance burden intensity.
- Retail Stores:Department stores and specialty chains requiring campaign-specific graphics with monthly refresh cycles. Digital print convergence enables UV inkjet production without plate costs.
- Supermarkets:High-velocity grocery networks with automated replenishment and closed-loop logistics. Tosca and IFCO reusable plastic crates displace one-trip corrugated in select supply chains.
- Online Retailers:E-commerce platforms deploying display boxes as unboxing experience elements and return-ready secondary packaging. Specifications prioritize dimensional efficiency for parcel network compatibility.
- Exhibitions:Trade show and event marketers with single-use, short-duration requirements. Demand concentrates in tier-one Chinese cities and European exhibition hubs.
Supermarkets generate the highest unit volumes, though Online Retailers are gaining share fastest through unboxing experience investment.
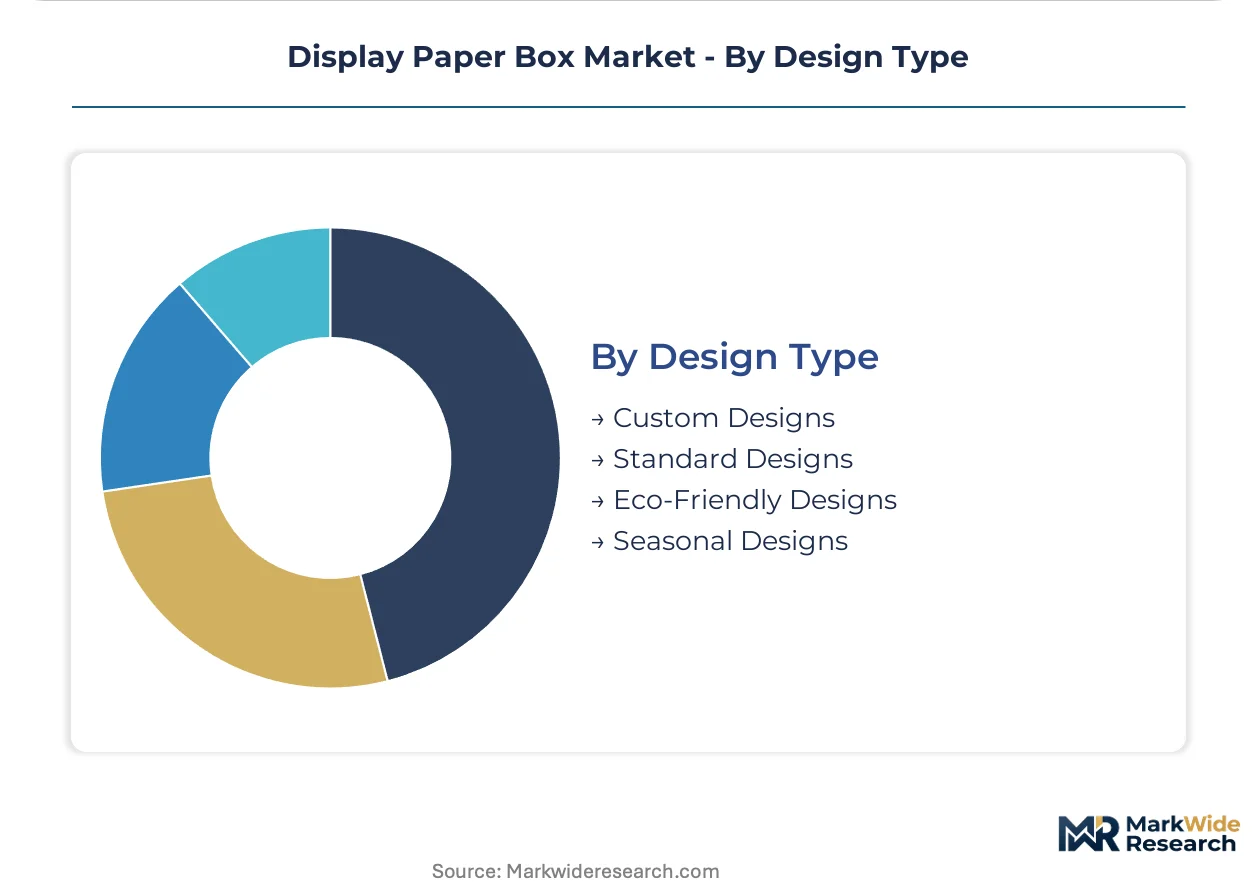
Design Type:
Maturity gradient separates established formats from emerging specifications shaped by regulatory and sustainability pressures.
- Custom Designs:Campaign-specific die-lines developed through CAD-based engineering for modular, reusable structural platforms. Talent scarcity in structural engineering constrains converter capacity.
- Standard Designs:Catalog-specified formats with minimal customization, serving cost-constrained promotional programs with predictable volume.
- Eco-Friendly Designs:Structures optimized for recyclability, reduced material weight, or biodegradable coatings. France's CITEO and Germany's ZSVR extended producer responsibility schemes incentivize design-for-recycling contracts.
- Seasonal Designs:Time-bound graphics and structural variants for holiday and event-driven retail cycles. Compressed promotional calendars now demand 48-hour turnaround on design variants.
Custom Designs hold the dominant position, with Eco-Friendly Designs climbing the fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR packaging rules and GB standards on recyclability labeling are reshaping material sourcing decisions across export-bound production networks. Germany's F-Gas Regulation and France's CITEO extended producer responsibility scheme compress formulation options for European converters serving luxury cosmetics brands.
China
Hema Fresh and 7Fresh are scaling in-store promotional infrastructure for fresh produce and dairy categories. SAMR's GB standards mandate recyclability labeling that constrains board coating selection for export-bound manufacturing. Shanghai and Beijing concentrate pallet display procurement as domestic retail chains expand tier-one city footprints.
Germany
Retail chains now require FSC-certified display structures for shelf placement, pulling premium rigid box demand from cosmetics brands. The F-Gas Regulation constrains adhesive chemistries for converters serving L'Oréal and Estée Lauder. The Rhine-Ruhr industrial corridor anchors high-volume corrugated manufacturing for grocery display programs.
United States
Walmart's modular display specifications demand 48-hour turnaround on design variants, compressing production planning windows. FDA food-contact substance notifications for board coatings add 90-180 days to product launches for grocery clients. The Chicago-Milwaukee corridor concentrates structural engineering talent for retail traffic load modeling.
India
Organized retail penetration below 10 percent creates whitespace for point-of-sale infrastructure as Reliance Retail and D-Mart expand store networks. BIS standards govern material specifications for domestic packaging applications. Mumbai and Delhi-NCR concentrate early procurement for campaign-specific display structures.
Netherlands
Fresh produce retailers are adopting water-based barrier-coated kraft structures for misted vegetable displays. REACH Annex XVII restrictions on perfluorinated compounds force adhesive reformulation across European production networks. The Rotterdam-Antwerp logistics cluster facilitates barrier-coated kraft distribution to Belgian retail chains.
Display Paper Box Market Vendor Landscape
Integrated paperboard producers and specialized display converters split the market between scale-driven supply security and campaign-velocity flexibility. The vendor base concentrates around corrugated fiberboard networks with digital print capacity and rigid box specialists serving cosmetics compliance requirements. Two strategic archetypes dominate: multinational paperboard giants controlling feedstock-to-display vertical chains, and regional converters leveraging proximity for rapid-turn promotional programs. Competitive moves center on digital print infrastructure deployment and ECHA-compliant adhesive formulation partnerships for EU-facing production.
Within the integrated paperboard tier, DS Smith and Smurfit Kappa Group exemplify scale-driven supply chain control across European and Latin American retail networks respectively. Mondi Group occupies a position on the barrier-coated specialty vector, representing the material science differentiation archetype for moisture-sensitive produce applications.
| Leading Market Players |
|---|
| DS Smith |
| International Paper |
| Smurfit Kappa Group |
| WestRock |
| Mondi Group |
| Sonoco |
| Menasha |
| Huhtamäki Oyj |
| VPK Packaging Group |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr industrial corridor anchors European corrugated fiberboard capacity, and its converter density translates into pricing leverage for grocery display programs serving German and French retail chains. OCC feedstock volatility propagates through this hub, compressing margins for North American converters while solid bleached sulfate specialists in the Chicago-Milwaukee corridor capture premium pricing from cosmetics brands.
Pricing Analysis
Geographic price spreads separate European FSC-certified rigid box premiums from Asian export-bound corrugated base grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and customization depth. Pricing pressure stems from reusable plastic crate substitution in closed-loop grocery logistics, with supermarket buyers exhibiting highest sensitivity to unit cost while luxury cosmetics procurement prioritizes REACH-compliant adhesive formulations.
Supply Chain Analysis
Contract manufacturing concentrates around DS Smith's European corrugated network, Smurfit Kappa's Latin American pallet display facilities, and Mondi Group's barrier-coated kraft specialty lines. Raw material sourcing draws from Swedish and Finnish pulp mills for virgin fiber, Chinese OCC recovery streams for recycled content, and German adhesive formulators for ECHA-compliant chemistries. Single-source vulnerability sits with water-based barrier coating resin suppliers serving Dutch produce retail chains. Distribution runs through Rotterdam-Antwerp logistics clusters into Belgian and German retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display paper box procurement is consolidating around digital print platform interoperability, as Walmart's 48-hour turnaround specifications and Hema Fresh's automated replenishment systems reward converters with modular campaign infrastructure.
For Market Incumbents: Entrench digital print capacity investments to defend against campaign-velocity specialists capturing seasonal promotional cycles. Backward integration into water-based barrier coating resin production secures supply continuity for Mondi Group-style produce applications. Prioritize ECHA-compliant adhesive formulation partnerships ahead of REACH Annex XVII enforcement timelines for perfluorinated compound restrictions. For New Entrants and Emerging Players: Pursue India's sub-10-percent organized retail penetration whitespace, where Reliance Retail and D-Mart expansion outpaces domestic converter capacity. Target eco-friendly design-for-recycling contracts under France's CITEO and Germany's ZSVR extended producer responsibility schemes. Position through rapid-turn CAD-based die-line development services addressing structural engineering talent scarcity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors barrier-coated kraft specialists with moisture-sensitive produce applications, as water-based coatings displace PET and PP trays in Dutch and Belgian retail chains. Long-term viability hinges on regulatory chemistry compliance capabilities across EU REACH, China's GB standards, and FDA food-contact notification pathways. Monitor quarterly OCC import restriction announcements from Chinese environmental regulators as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Infrastructure Deployment | UV inkjet systems enable 48-hour graphic turnaround for Walmart and Target seasonal campaigns. |
| Barrier-Coated Kraft Capacity Expansion | Mondi Group's moisture-resistant solutions open fresh produce categories previously closed to fiberboard. |
| ECHA-Compliant Adhesive Partnership | REACH Annex XVII reformulation secures L'Oréal and Estée Lauder luxury cosmetics procurement. |
| Extended Producer Responsibility Contracting | CITEO and ZSVR design-for-recycling agreements shift disposal cost allocation to brand owners. |
| India Market Entry Through Localized Manufacturing | Reliance Retail and D-Mart network expansion outpaces domestic point-of-sale infrastructure supply. |
Methodological Framework
The analysis maps corrugated fiberboard, solid bleached sulfate, and barrier-coated kraft sub-sectors, each validated through converter operations directors, retail category buyers, and adhesive formulation chemists. Primary interviews with structural engineering designers and digital print operations managers combined with secondary validation from EU REACH registration databases, FDA food-contact substance notifications, and Chinese SAMR GB standard filings. Bottom-up capacity modeling and top-down retail procurement surveys triangulate volume estimates.
Assumption sets held Chinese domestic retail expansion and EU Green Deal compliance timelines fixed while varying OCC feedstock cost trajectories and reusable plastic crate adoption rates. Segmentation dimensions span material type, display format, end-user channel, and design flexibility tier across the analysis window. CAGRs derive from retail square footage expansion rates, promotional cycle compression trends, and regulatory compliance cost pass-through elasticity. Industry-specific inputs include FSC certification penetration curves and water-based barrier coating technical adoption thresholds.
Macroeconomic conditions sit as an overlay; deviation in pulp fiber pricing, Chinese recovered paper import policies, or euro-dollar exchange rates would shift the trajectory. Forecasts reflect documented assumptions on retail promotional spend allocation and sustainability premium willingness-to-pay. Quarterly review of ECHA substance restriction announcements, SAMR packaging rule amendments, and major retail chain modular display specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Global Paper Bags Market