
 Postal Papers Market | 2026-2036
Postal Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Postal Papers Market Analytics
Modular envelope configurations is broadening buyer choice across the Postal Papers Market as standardized formats give way to size-optimized and window-adaptable designs. Smurfit Kappa Group leverages its integrated fiber supply to control cost positions in corrugated postal substrates. DS Smith Plc anchors European demand through recycled-content specialization aligned with retailer sustainability targets. Mondi Group Plc differentiates via kraft-based barrier technologies that extend product protection without plastic lamination.
Postal papers comprise machine-finished or machine-glazed paper grades, typically manufactured from bleached chemical pulp or recycled fiber with basis weights ranging from 40 to 150 gsm, engineered for addressability, printability, and machinability in high-speed sorting systems. Their primary commercial purpose centers on protective packaging, correspondence conveyance, and branded unboxing experiences across physical delivery networks. Envelopes retain the largest volume share within product type segmentation, though labels are gaining share as barcode-driven logistics expand. Kraft paper dominates material segmentation due to tear resistance and recyclability, while specialty paper commands margin concentration in premium gift and security applications. E-commerce end use is outpacing retail and personal segments as order frequency rises and return logistics multiply touchpoints.
EU REACH and F-Gas Regulation constrain chemical treatments in coated postal papers, while CE marking requirements shape product safety thresholds for child-resistant and tamper-evident formats. EPA guidelines in the United States limit certain bleaching effluents, pressuring mills toward elemental chlorine-free processes. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate certification schemes as procurement criteria harden across postal operators and platform retailers.
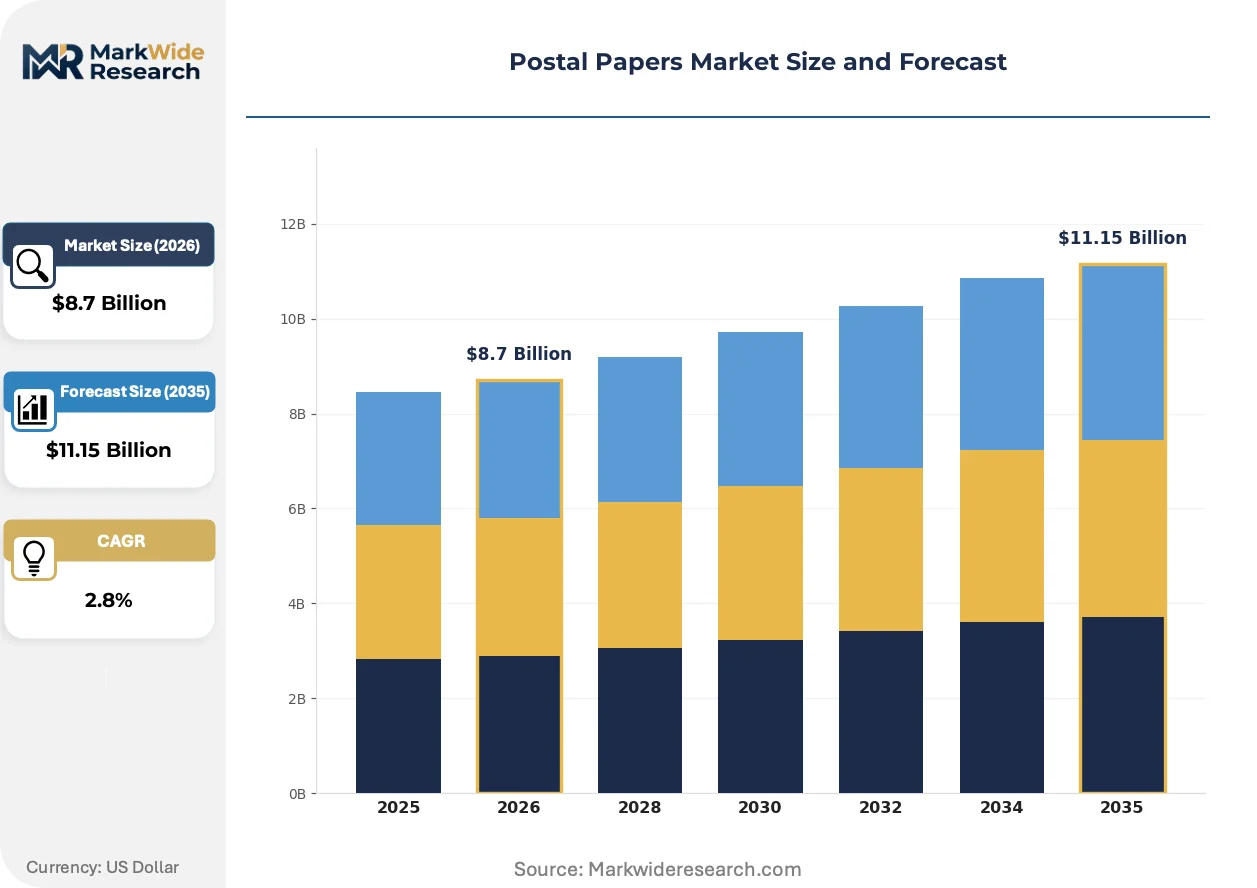
Market Dynamics
E-commerce parcel volumes are compressing format standardization as postal operators demand size-optimized substrates compatible with automated sortation systems. The EU Green Deal's packaging waste directives are accelerating substrate transitions toward recycled fiber grades.
Growth Catalysts
- E-commerce fulfillment expansion:Parcel carriers in Germany and the Netherlands are procuring higher volumes of machine-glazed papers compatible with high-speed barcode scanning and automated sortation infrastructure.
- REACH chemical restrictions:ECHA limitations on fluorinated coatings are redirecting demand toward bio-based barrier technologies that maintain grease resistance without persistent organic pollutants.
- Return logistics multiplication:Fashion and electronics retailers are sourcing dual-use postal formats that withstand multiple handling cycles, extending substrate durability specifications.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container availability fluctuates with retail inventory cycles, squeezing margin predictability for mills dependent on post-consumer furnish.
- Bleaching chemistry constraints:EPA effluent guidelines limit elemental chlorine processes in US mill operations, requiring capital-intensive conversions to elemental chlorine-free or totally chlorine-free systems.
- Plastic film substitution threat:Polyethylene mailers retain cost advantages in moisture-critical applications, particularly for cross-border shipments where dimensional weight pricing favors lighter substrates.
Strategic Opportunities
- Central European packaging hub expansion:Poland and Czech Republic postal networks are modernizing sortation infrastructure, creating procurement windows for compatible substrate suppliers.
- Extended producer responsibility frameworks:France and Italy are implementing fee-modulated EPR schemes that penalize non-recyclable formats, advantaging fiber-based postal papers in platform retailer sourcing.
- Smart packaging convergence:Integration of printed electronics with kraft substrates enables track-and-trace functionality without secondary label application, capturing value from logistics technology budgets.
Industry Challenges
- Barrier coating formulation expertise:Mills lack in-house R&D capacity to develop water-based coatings matching silicone release performance for pressure-sensitive label applications.
- Multi-certification timeline compression:Postal operators now require simultaneous FSC chain-of-custody, PEFC, and carbon footprint verification, extending qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postal Papers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
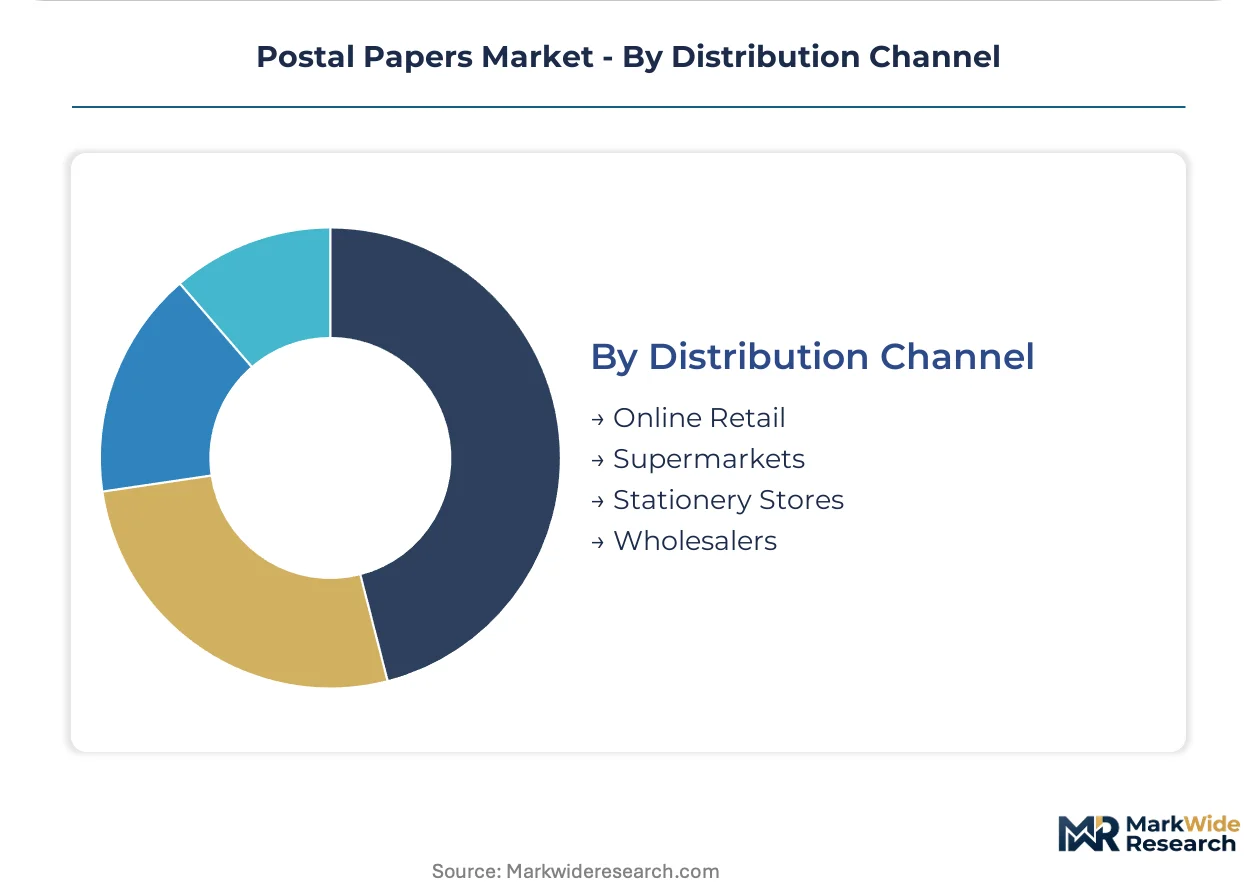
| Segmentation | Product Type: Postcards, Envelopes, Wrapping Paper, Labels Material: Recycled Paper, Kraft Paper, Coated Paper, Specialty Paper End Use: Retail, E-commerce, Personal, Business Distribution Channel: Online Retail, Supermarkets, Stationery Stores, Wholesalers |
| Companies Covered | Smurfit Kappa Group, DS Smith Plc, WestRock Company, Mondi Group Plc, Cenveo Corporation, Rengo Co. Ltd., Neenah, Inc., Bong Group, Papier-Mettler KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postal Papers Market Evolving Landscape
Substrate engineering is diverging from commodity grades toward performance-specified formats. Barrier technologies, regulatory chemistry constraints, and logistics automation compatibility are the three vectors reshaping product development priorities.
Water-based barrier coatings are rewriting the competitive hierarchy in protective postal applications. E-commerce fulfillment centers in Germany and France are qualifying these formats for apparel and cosmetics shipments previously dependent on polyethylene lamination. The technology is compressing the addressable market for plastic-lined envelopes while opening premium positioning for fiber-based alternatives.
EU F-Gas Regulation phase-down schedules are constraining solvent-based coating processes across European mill operations. Manufacturers are retrofitting drying sections to accommodate higher solids waterborne systems or investing in UV-curable alternatives. Kraft paper grades with inherent grease resistance are gaining preference in food-contact postal applications where fluorochemical treatments face substitution deadlines.
Platform retailers are consolidating postal paper specifications across private-label packaging programs. Amazon and Zalando procurement teams are pushing standardized envelope formats that reduce SKU complexity in fulfillment center operations. This concentration is visible most acutely in Germany, where centralized postal networks enable single-format deployment at national scale.
Postal Papers Market Segmentation
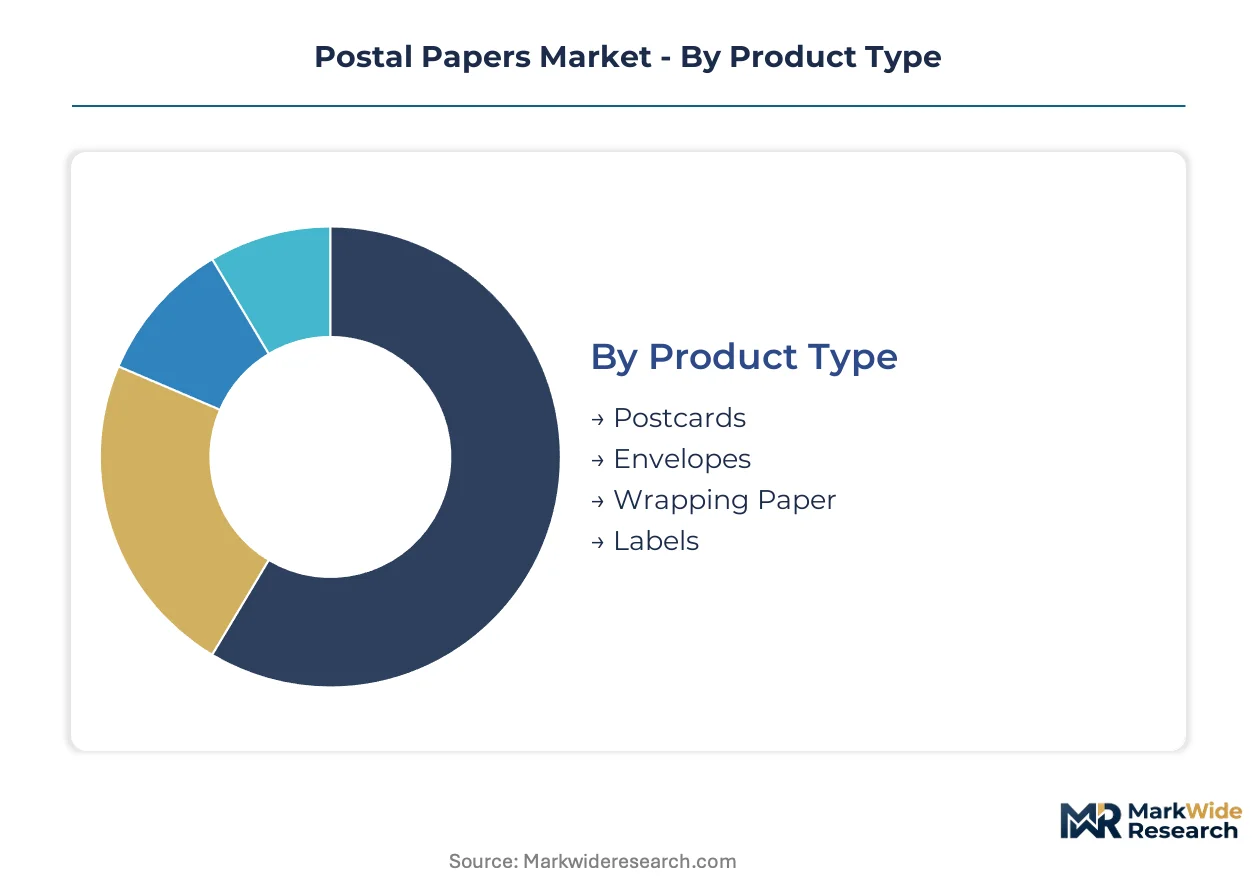
Postal paper procurement patterns diverge sharply across application contexts, with e-commerce fulfillment driving substrate specifications toward machinability and barcode compatibility while personal correspondence preserves premium finishing requirements. Understanding these segment boundaries enables suppliers to align capacity investments with contracting windows at major postal operators and platform retailers.
Product Type:
Supply concentration in envelope manufacturing centers on automated conversion lines capable of window patching and silicone strip application at speeds exceeding 300 units per minute.
- Envelopes:Machine-glazed kraft and bleached chemical pulp grades between 80-120 gsm dominate commercial production, with window-adaptable designs capturing procurement share from German postal operators modernizing sortation infrastructure. Dual-seal configurations are gaining preference among fashion retailers managing return logistics multiplication.
- Labels:Pressure-sensitive face stocks with direct thermal or thermal transfer coatings are engineered for high-speed barcode scanning compatibility, with demand concentrating at parcel carriers in the Netherlands expanding automated hub capacity. ECHA restrictions on fluorinated release coatings are redirecting formulation toward bio-based alternatives.
- Postcards:Rigid uncoated woodfree boards at 200-300 gsm serve direct mail and greeting card applications.
- Wrapping Paper:Thin machine-finished grades provide protective interleaving for e-commerce apparel shipments.
Today's leader: Envelopes. Tomorrow's challenger: Labels.
Material:
Cost tier stratification separates commodity kraft from premium specialty grades, with recycled fiber intermediates squeezing margin as old corrugated container availability fluctuates with retail inventory cycles.
- Kraft Paper:Unbleached sulfate pulp delivers tear resistance and dimensional stability critical for automated sortation compatibility, with procurement concentrating at centralized postal networks in Germany where national-scale deployment justifies format standardization. Natural lignin content provides inherent grease resistance for food-contact applications facing fluorochemical substitution deadlines.
- Recycled Paper:Post-consumer deinked pulp with controlled contaminant thresholds meets EU Green Deal packaging waste directives, with demand accelerating at French and Italian platform retailers responding to fee-modulated extended producer responsibility frameworks. Fiber sourcing volatility compresses margin predictability for mills without integrated collection infrastructure.
- Coated Paper:Clay or calcium carbonate surface treatments enhance print reproduction for branded unboxing experiences.
- Specialty Paper:Security threads, watermarks, and tamper-evident substrates command premium positioning in government and financial applications.
Kraft Paper anchors current volume. Recycled Paper climbs the fastest under regulatory pressure.
End Use:
Application requirements reshape substrate specifications, with e-commerce fulfillment demanding durability for multiple handling cycles while personal use preserves aesthetic finishing priorities.
- E-commerce:Dual-use postal formats withstand return logistics multiplication, with Amazon and Zalando procurement teams consolidating specifications across private-label packaging programs. Water-based barrier coatings are displacing polyethylene lamination for apparel and cosmetics shipments in German fulfillment centers.
- Retail:Branded unboxing experiences drive coated paper adoption for gift and premium positioning.
- Business:Standardized envelope formats reduce procurement complexity for corporate mailrooms.
- Personal:Premium finishing and specialty substrates persist in greeting card and correspondence applications.
E-commerce commands procurement volume concentration. Retail maintains margin premium.
Distribution Channel:
Customer type segmentation separates institutional procurement through wholesalers from fragmented consumer purchasing via stationery retail.
- Wholesalers:Volume contracting with postal operators and platform retailers drives substrate standardization, with qualification cycles extending 8-14 months under multi-certification requirements including FSC chain-of-custody and carbon footprint verification.
- Online Retail:Direct-to-consumer channels enable custom format configurations for small and medium e-commerce merchants.
- Stationery Stores:Premium and specialty grades target gift and personal correspondence segments.
- Supermarkets:Commodity envelope and label assortments serve incidental consumer demand.
Wholesalers dominate institutional flow. Online Retail expands fastest among emerging merchants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Postal paper manufacturing originated in European industrial centers during the 19th century mechanization of correspondence systems. German mills pioneered machine-glazed grades for high-speed sorting. Contemporary demand concentrates where e-commerce fulfillment density and regulatory pressure on substrate sustainability intersect.
Germany
Deutsche Post's centralized procurement drives format standardization across national postal networks. The EU Green Deal packaging waste directives accelerate recycled fiber adoption in fulfillment center operations. The Ruhr industrial corridor hosts integrated mills supplying kraft grades to automated sortation hubs in Duisburg and Dortmund.
United States
Parcel carriers operating from Memphis and Louisville air hubs demand machinable substrates compatible with barcode-driven logistics. EPA effluent guidelines constrain bleaching chemistry in southeastern mill operations. The Pacific Northwest pulp and paper cluster supplies elemental chlorine-free grades to West Coast e-commerce distribution centers.
France
Platform retailers responding to fee-modulated extended producer responsibility schemes favor fiber-based postal formats over plastic alternatives. ANSM guidelines shape food-contact barrier coating specifications. The Lyon-Grenoble corridor hosts specialty converters developing water-based grease-resistant technologies for cosmetics shipments.
China
Cross-border e-commerce expansion from Shenzhen and Hangzhou fulfillment centers multiplies demand for lightweight protective substrates. GB standards and MIIT regulations govern packaging material safety thresholds. The Yangtze River Delta paperboard cluster supplies machine-finished grades to automated sortation facilities in Shanghai and Ningbo.
Netherlands
Parcel carriers expanding Rotterdam and Eindhoven automated hub capacity procure pressure-sensitive label stocks engineered for thermal transfer printing. REACH restrictions on fluorinated coatings redirect formulation toward bio-based release technologies. The Randstad logistics corridor concentrates procurement for Benelux distribution networks.
Postal Papers Market Competitive Landscape
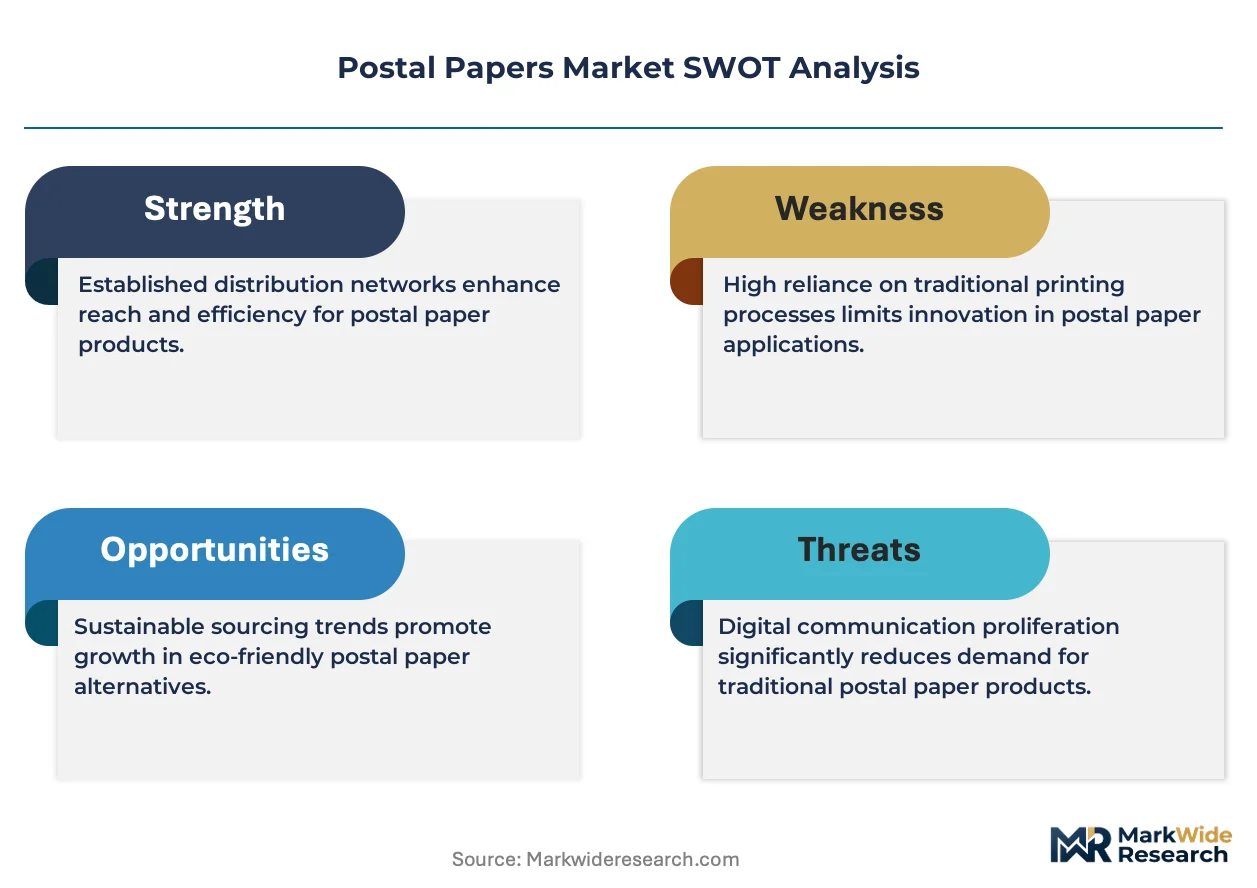
Premium-margin players sit above commodity-margin players across certification depth and barrier technology sophistication. The market structures around three tiers: integrated forest products groups controlling fiber supply, specialized packaging converters with recycled-content expertise, and regional envelope manufacturers serving fragmented postal procurement. Consolidation pressure intensifies as postal operators reduce supplier counts under multi-certification qualification requirements. Strategic moves center on backward integration into recycled fiber collection and capacity expansion in Central European packaging hubs.
Within the integrated fiber supply tier, Smurfit Kappa Group exemplifies upstream control over corrugated postal substrates. DS Smith Plc occupies a position aligned with retailer sustainability targets through recycled-content specialization. Mondi Group Plc anchors the barrier technology vector via kraft-based protection systems. These three represent distinct competitive archetypes: captive supply integration, circular material positioning, and performance-grade innovation.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith Plc |
| WestRock Company |
| Mondi Group Plc |
| Cenveo Corporation |
| Rengo Co. Ltd. |
| Neenah, Inc. |
| Bong Group |
| Papier-Mettler KG |
| Others |
Value Network & Pricing Analysis
Platform retailer consolidation of envelope specifications across private-label packaging programs is compressing supplier margins while forcing mills to absorb certification and barrier technology investments. This procurement concentration in Germany and France rewards integrated fiber suppliers with cost positions that regional converters cannot match.
Pricing Analysis
Contract-based long-term offtake agreements dominate institutional procurement between postal operators and integrated mills. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified barrier grades from commodity kraft and uncoated recycled fiber. Pricing pressure stems from old corrugated container cost volatility squeezing post-consumer furnish margins. Fashion and electronics retailers show highest price sensitivity due to return logistics multiplication, while government postal contracts demonstrate lowest sensitivity given machinability mandates.
Supply Chain Analysis
Regional distribution centers in the Ruhr corridor, Randstad logistics corridor, and Pacific Northwest pulp cluster anchor hub-and-spoke patterns for kraft grade fulfillment. Manufacturing concentrates in Germany, Netherlands, and United States where automated sortation infrastructure demands proximity. Raw material sourcing draws from sulfate pulp mills, deinked fiber collection networks, and water-based coating chemical suppliers. Single-source vulnerability runs through old corrugated container availability tied to retail inventory cycles. Distribution runs through wholesaler channels serving postal operators and platform retailers with 8-14 month qualification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Postal Papers Market compounds steadily as e-commerce parcel volumes institutionalize substrate specifications and extend contract durations. EU Green Deal packaging waste directives provide regulatory tailwinds for fiber-based formats.
For Market Incumbents: Acquire deinked fiber collection infrastructure to secure post-consumer furnish supply against retail inventory volatility. Expand barrier coating R&D capacity to match silicone release performance for pressure-sensitive label applications. Consolidation pressure from multi-certification requirements favors integrated mills with in-house FSC chain-of-custody and carbon footprint verification capabilities. For New Entrants and Emerging Players: Mid-sized e-commerce merchants in Central European packaging hubs represent underserved buyer archetypes seeking custom format configurations outside Amazon and Zalando procurement consolidation. Poland and Czech Republic postal network modernization creates procurement windows for compatible substrate suppliers. Direct-to-consumer online retail channels enable format specialization without wholesaler qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized packaging converters possessing recycled-content expertise and barrier technology sophistication. The 5-10 year viability window favors assets aligned with extended producer responsibility frameworks penalizing non-recyclable formats. Monitor fee-modulated EPR scheme implementation across France and Italy as inflection indicator for fiber-based postal paper procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Secures old corrugated container supply against retail inventory cycle volatility in German mill operations. |
| Water-Based Barrier Coating Scale-Up | Captures apparel and cosmetics shipments displacing polyethylene lamination in French fulfillment centers. |
| Central European Hub Capacity Expansion | Positions substrate supply for Poland and Czech Republic postal network modernization procurement windows. |
| Multi-Certification Qualification Investment | Compresses 8-14 month FSC and carbon footprint verification cycles to compete for Deutsche Post contracts. |
| Smart Packaging Convergence Partnership | Integrates printed electronics with kraft substrates for track-and-trace functionality in Dutch parcel carriers. |
Research Methodology
Direct dialogue with postal operator procurement directors, platform retailer packaging engineers, mill operations managers, and corrugated substrate technical specialists grounded qualitative findings. Secondary validation drew from EU REACH and F-Gas Regulation filings, EPA effluent guideline documentation, extended producer responsibility framework announcements, and trade flow data from paper industry associations. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmented outputs by product type, material grade, end-use application, and distribution channel informed the analytical framework. Modeled projections incorporated e-commerce parcel volume trajectories, recycled fiber availability cycles, and regulatory chemistry constraint timelines. CAGRs derived from historical correlation analysis with logistics automation investment and packaging waste directive implementation schedules.
Underlying measurement precision varies by segment; e-commerce end-use and kraft material grades carry tighter precision than personal correspondence and specialty paper applications. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and platform retailer consolidation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Paper Cup Machine Market