
 Paints and Coatings Additives Market | 2026-2036
Paints and Coatings Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Paints and Coatings Additives Market Intelligence
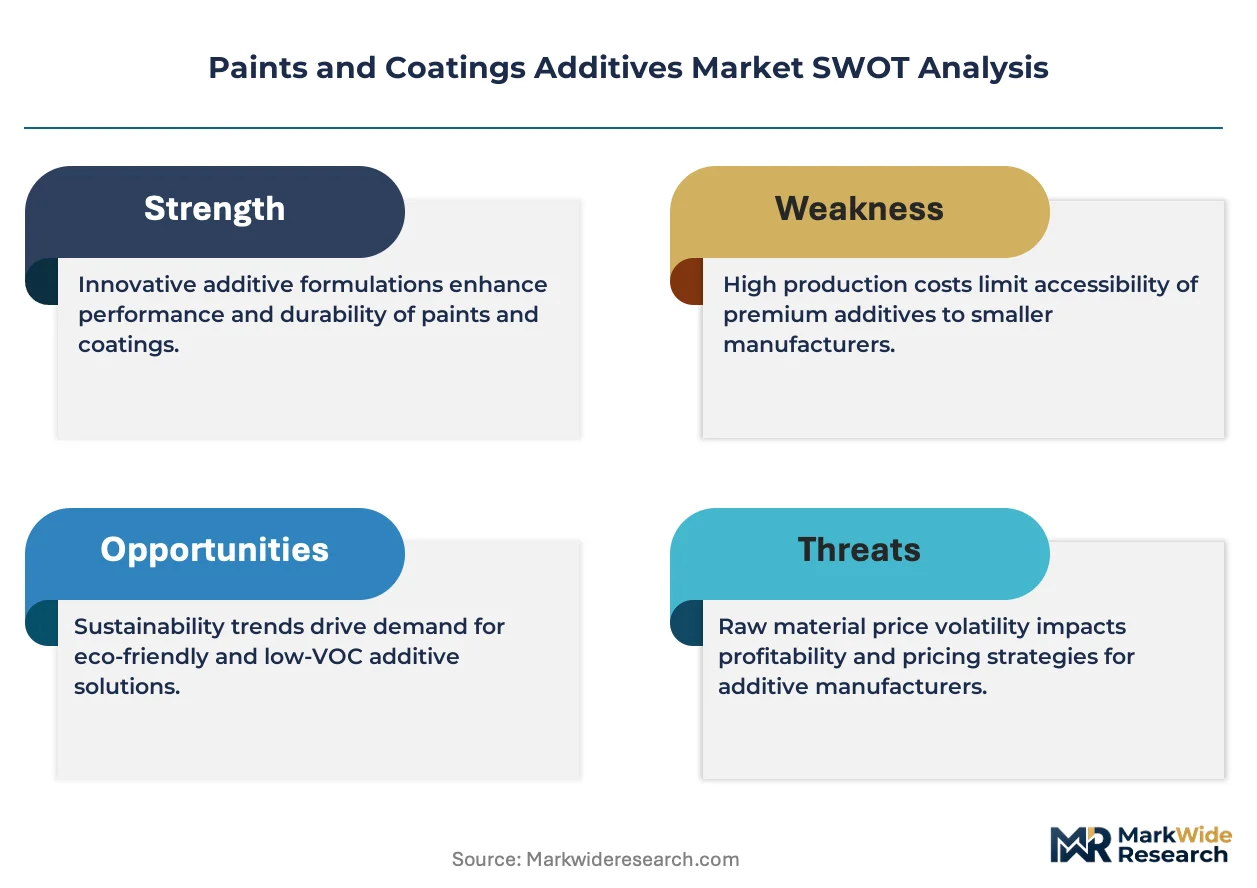
The capital-intensity divergence between integrated resin producers and specialty additive houses is unwinding competitive stability in the sector. BASF SE leverages captive petrochemical feedstocks to control raw material costs across dispersant and rheology modifier lines. BYK-Chemie GmbH differentiates through application-specific testing laboratories that anchor premium positioning in automotive surface treatments. Elementis plc competes on mining-linked rheology modifier supply, sustaining margin pools in industrial sealants where natural hectorite clays dominate performance specifications.
Paints and coatings additives encompass functional chemicals dosed at 0.1–5.0 weight percent to modify viscosity, surface tension, foam control, pigment stability, or film formation in liquid and powder coatings. These additives primarily enable formulators to meet application-specific performance thresholds—sprayability, sag resistance, gloss retention—while adapting to substrate and cure conditions. Dispersants command structural importance because pigment stabilization directly determines coating opacity and color consistency across waterborne and solvent-borne systems. Rheology modifiers represent the fastest-growing product category as high-build architectural finishes and thick-film industrial sealants demand precise sag control during vertical application. Waterborne systems are maturing in architectural applications but still expanding in automotive OEM coatings where humidity resistance and corrosion protection standards remain stringent.
REACH and the EU Green Deal constrain VOC content and mandate hazard communication across formulations sold in Europe, redirecting R&D investment toward bio-based dispersants and silicone-free defoamers. EPA regulations in the United States enforce parallel VOC limits under National Ambient Air Quality Standards, while China's MEE implements dual carbon goals that tighten emissions from solvent-borne coating operations. Formulators and additive suppliers must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment product portfolios and complicate scale economics.
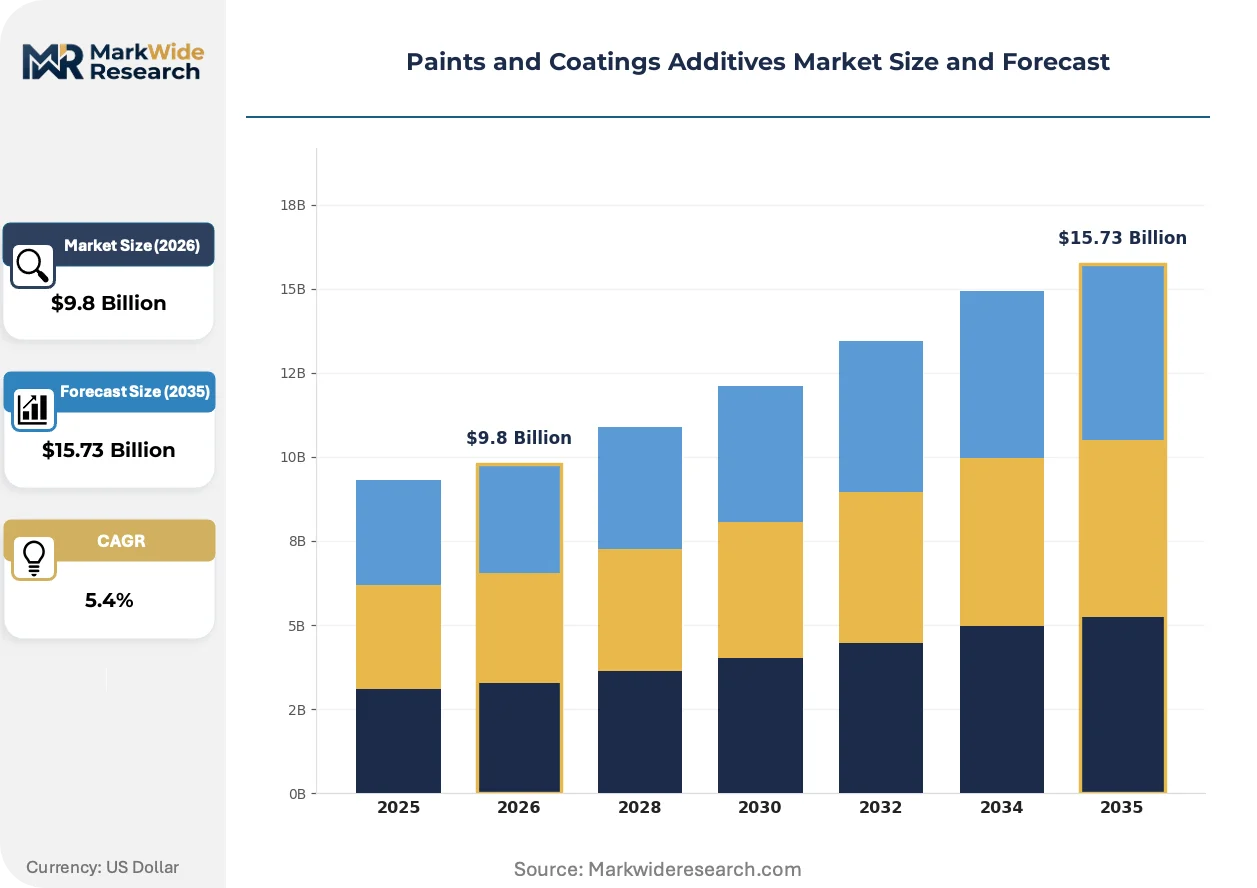
Market Dynamics
Automotive refinishers are accelerating additive adoption for high-performance surface treatments, while REACH compliance and the EU Green Deal force simultaneous reformulation toward waterborne systems with tighter VOC limits.
Growth Catalysts
- Automotive refinish demand:Collision repair networks and OEM refinish operations require advanced rheology modifiers and dispersants for color-matching precision and durability in high-build coatings.
- REACH and EU Green Deal mandates:Tightening VOC limits across European formulations redirect R&D investment toward bio-based dispersants and silicone-free defoamers, expanding addressable market for compliant additive suppliers.
- China domestic supply chain maturation:Local additive production scaling alongside paint manufacturing concentration reduces import dependency and accelerates formulator access to cost-competitive dispersant and defoamer grades.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings directly impact dispersant and rheology modifier input costs, compressing margin pools for non-integrated additive houses.
- Natural hectorite clay supply concentration:Mining-linked rheology modifier production clusters in specific geographies, creating single-source vulnerability for industrial sealant formulators dependent on thixotropic performance.
- Waterborne humidity resistance gap:Architectural waterborne systems mature while automotive OEM coatings face persistent corrosion protection and humidity resistance limitations versus solvent-borne benchmarks.
Strategic Opportunities
- India architectural coatings expansion:Urban construction acceleration and BIS standards alignment create demand for cost-optimized dispersant packages in decorative paint formulations.
- Bio-based dispersant platforms:Renewable feedstock-derived pigment stabilizers capture premium positioning as ESG procurement criteria harden across European and North American formulator specifications.
- Digital color-matching integration:Additive suppliers embedding spectrophotometry-compatible dispersant systems capture value from automotive refinish chain consolidation toward integrated body shop management platforms.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne-solvent-borne compatibility and cure-condition optimization concentrates at legacy additive houses, constraining new entrant scale-up velocity.
- Multi-jurisdiction compliance fragmentation:Divergent VOC limits between EPA National Ambient Air Quality Standards, REACH hazard communication, and China's MEE dual carbon goals force portfolio duplication that erodes scale economics.
- Application-specific testing infrastructure:Automotive surface treatment qualification requires dedicated spray booths and weathering chambers, locking smaller additive suppliers out of premium tier certification loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paints and Coatings Additives Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Enhancers, Dispersants, Defoamers, Rheology Modifiers, Wetting Agents, Anti-Settling Agents Application: Architectural Finishes, Protective Coverings, Automotive Surface Treatments, Industrial Sealants, Wood Coatings, Marine Finishes End User: Paint Manufacturers, OEMs, Automotive Refinishers, Shipbuilding Firms, Flooring Specialists, Woodworking Shops Technology: Waterborne Systems, Solvent-Borne Systems, Powder-Based Solutions, UV-Curable Products, Silicone-Based Additives, Acrylic Formulations |
| Companies Covered | BASF SE, Dow, Evonik Industries AG, BYK-Chemie GmbH, Clariant AG, The Lubrizol Corporation, Arkema, Altana AG, Elementis plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paints and Coatings Additives Market Strategic Shifts & Innovations
Formulation science is converging with digital color systems and bio-based feedstocks, restructuring how additive suppliers anchor value in automotive and architectural end-uses.
Polymeric dispersants with anchor-group density optimization are supplanting conventional surfactant-based pigment stabilizers in automotive refinish formulations. Tier-one refinish networks in Germany and the United States specify these advanced dispersants for metallic and pearl effect coatings where flop control determines color consistency. The shift is compressing commodity surfactant demand while elevating formulation service bundling as the primary competitive differentiator.
EPA enforcement of National Ambient Air Quality Standards is tightening VOC limits in parallel with REACH and EU Green Deal timelines, creating trans-Atlantic regulatory convergence. Industrial maintenance coating formulators face accelerated solvent-borne phase-out deadlines, redirecting procurement toward waterborne rheology modifiers with sag resistance matching high-build solvent benchmarks. The segment most affected—marine and protective coatings in the US Gulf Coast and Rotterdam-Antwerp corridor—is responding through joint formulator-additive supplier pilot programs.
Specification consolidation among automotive OEMs and tier-one refinish chains is compressing additive supplier qualification cycles from multi-year to eighteen-month windows. Traditional distributor-led technical service models lose share to direct additive supplier application laboratories co-located with major formulator R&D centers. This pattern concentrates most visibly in Stuttgart, Detroit, and Shanghai metropolitan clusters where collision repair network consolidation accelerates.
Paints and Coatings Additives Market Segmentation
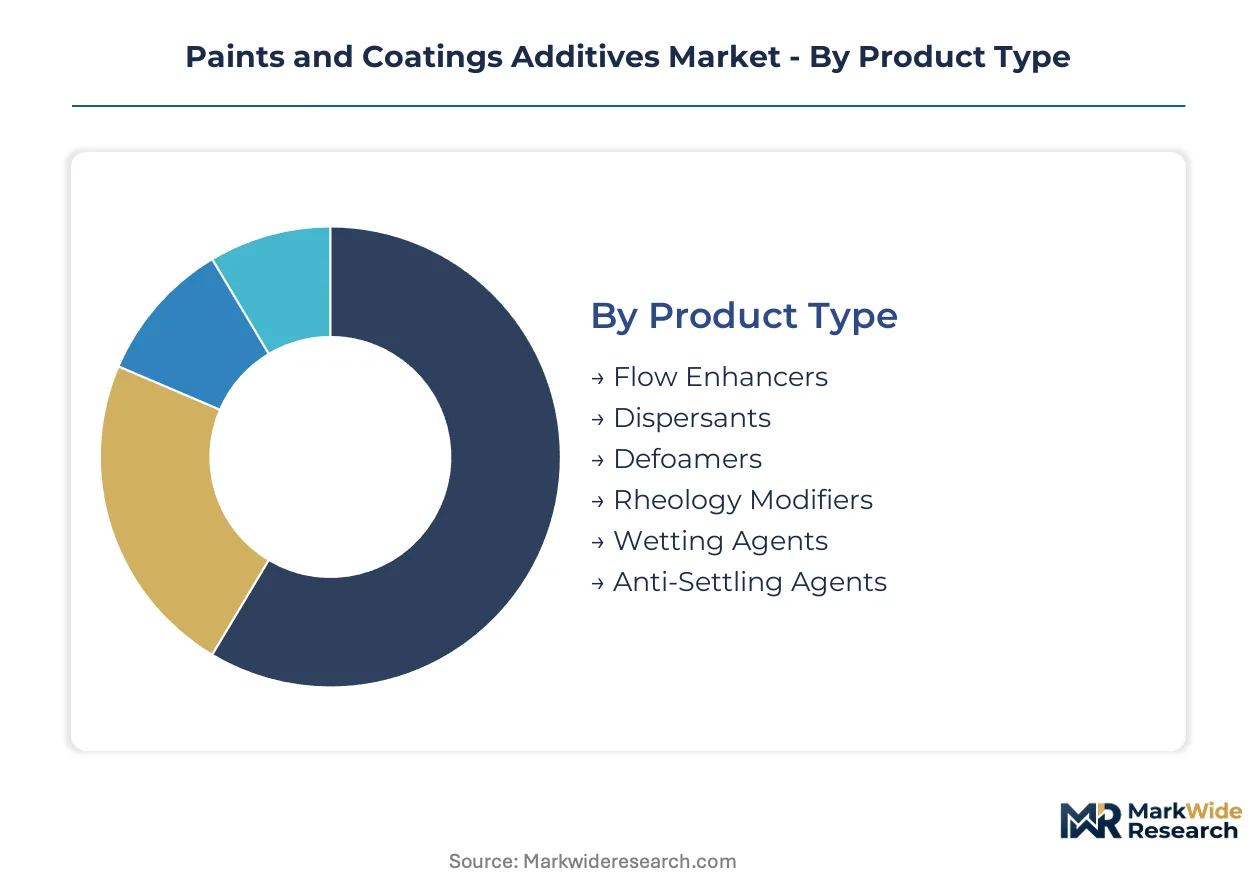
Additive suppliers structure product portfolios around formulation compatibility and end-use performance thresholds. Channel access varies sharply by segment—automotive refinish networks demand direct technical service relationships, while architectural formulators procure through distributor intermediaries.
Product Type:
Dispersants and rheology modifiers flow primarily through direct sales channels to large formulators, while defoamers and wetting agents distribute more heavily through regional chemical distributors serving mid-tier paint manufacturers.
- Dispersants:Polymeric pigment stabilizers with anchor-group density optimization control flocculation and color consistency in metallic and pearl effect coatings. Demand concentrates in automotive refinish networks in Germany and the United States where flop control determines tier-one supplier qualification.
- Rheology Modifiers:Thixotropic agents derived from natural hectorite clays or synthetic associative polymers manage sag resistance during vertical application. Industrial sealant formulators in the US Gulf Coast and Rotterdam-Antwerp corridor drive procurement as high-build solvent-borne phase-outs accelerate.
- Flow Enhancers:Surface tension reducers improve substrate wetting in spray-applied architectural finishes.
- Defoamers:Silicone-free variants capture share as REACH and EPA VOC constraints tighten across waterborne systems.
- Wetting Agents:Surfactant-based formulations enable pigment incorporation in high-speed dispersion equipment.
- Anti-Settling Agents:Post-addition stabilizers prevent hard settling in long-shelf-life industrial maintenance coatings.
By volume, rheology modifiers lead. By growth pace, dispersants are expanding most quickly.
Application:
Cost tier differentiation separates specification-grade automotive and marine applications from commodity architectural volumes, with protective coatings occupying a mid-tier position on performance-per-liter metrics.
- Automotive Surface Treatments:OEM and refinish coatings demand precise additive packages for humidity resistance, corrosion protection, and color-matching precision. Collision repair network consolidation in Stuttgart, Detroit, and Shanghai metropolitan clusters compresses supplier qualification cycles.
- Architectural Finishes:Decorative interior and exterior paints utilize cost-optimized dispersant and defoamer packages at high volume. Urban construction acceleration in India and domestic supply chain maturation in China reshape procurement patterns toward local additive grades.
- Protective Coverings:Industrial maintenance coatings balance durability and application efficiency in infrastructure and equipment applications.
- Industrial Sealants:Thick-film formulations for joint sealing and gap-filling require thixotropic control.
- Wood Coatings:Furniture and flooring finishes emphasize grain clarity and scratch resistance.
- Marine Finishes:Anti-corrosive and antifouling systems for ship hulls and offshore structures.
Architectural finishes dominate volume throughput. Automotive surface treatments command the steepest expansion trajectory.
End User:
Customer type determines service intensity—OEMs and automotive refinishers require embedded laboratory support, while woodworking shops and flooring specialists rely on distributor technical bulletins.
- Paint Manufacturers:Large formulators in waterborne architectural and industrial segments procure dispersants and rheology modifiers through multi-year supply agreements with technical service commitments.
- Automotive Refinishers:Tier-one collision repair networks specify additive packages for color-matching precision and durability in high-build coatings.
- OEMs:Original equipment manufacturers in automotive and industrial equipment integrate additive specifications into substrate preparation and coating application protocols.
- Shipbuilding Firms:Marine construction yards in South Korea and Japan specify anti-corrosive additive systems for new-build hull protection.
- Flooring Specialists:Industrial and decorative concrete coating applicators demand fast-cure rheology control.
- Woodworking Shops:Furniture manufacturers and cabinet makers utilize stain and lacquer additives for clarity and build.
Paint manufacturers lead by formulation volume. Automotive refinishers are gaining share fastest.
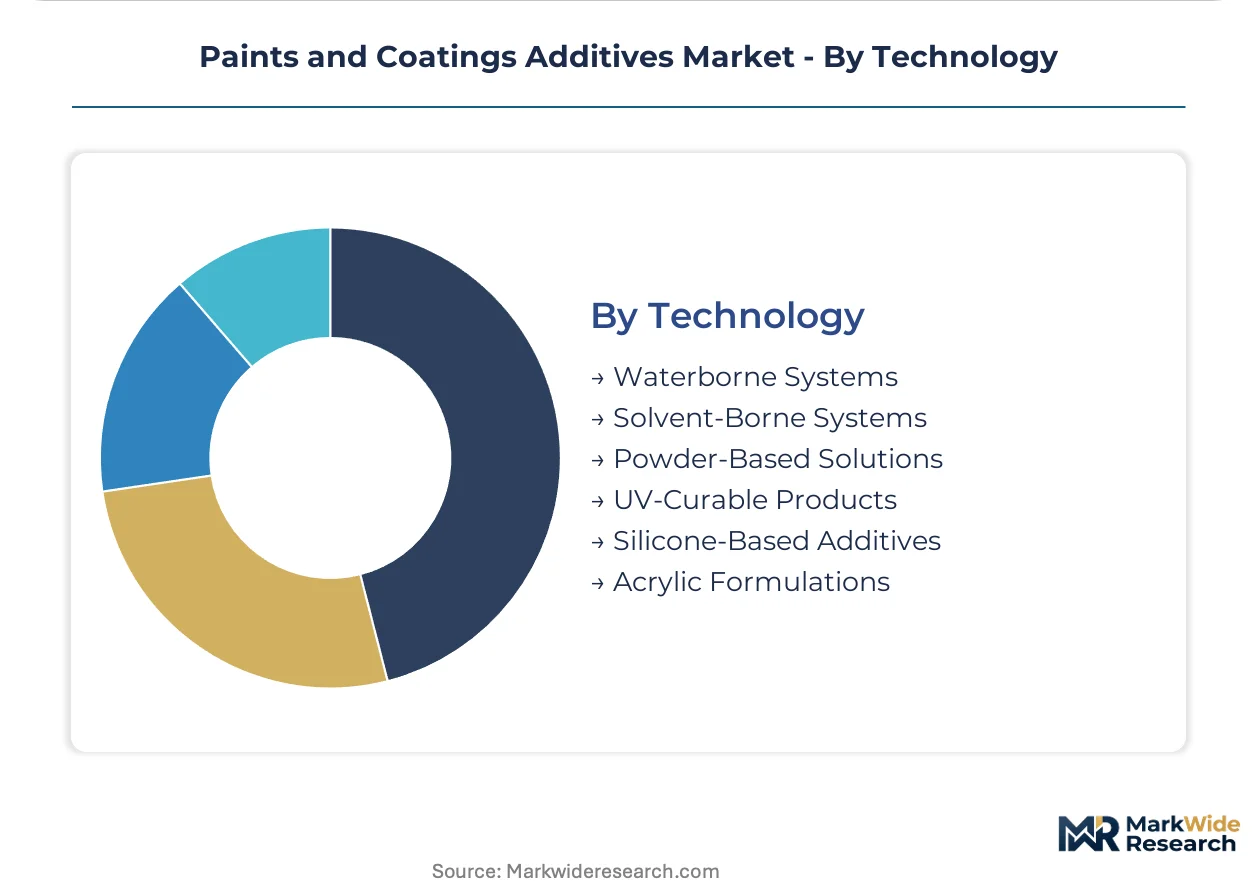
Technology:
Maturity curves diverge sharply—waterborne systems dominate architectural applications but face persistent performance gaps in automotive OEM humidity resistance, while UV-curable products remain niche despite rapid cure advantages.
- Waterborne Systems:Low-VOC formulations utilize bio-based dispersants and silicone-free defoamers to meet REACH, EPA National Ambient Air Quality Standards, and China's MEE dual carbon goals. Formulators in Europe and North America face accelerated solvent-borne phase-out deadlines.
- Solvent-Borne Systems:High-performance coatings for automotive OEM and marine applications retain share where humidity resistance and corrosion protection standards exceed current waterborne benchmarks.
- Powder-Based Solutions:Zero-VOC thermoset coatings for metal substrates in appliance and architectural metal applications.
- UV-Curable Products:Instant-cure formulations for wood coatings and graphic arts with limited penetration in heat-sensitive substrates.
- Silicone-Based Additives:Defoamers and slip agents facing substitution pressure from organic alternatives under ESG procurement criteria.
- Acrylic Formulations:Versatile binder systems compatible with multiple additive chemistries across architectural and industrial segments.
Solvent-borne systems lead by current volume. Waterborne systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums for REACH-compliant additive packages while Chinese domestic suppliers erode import margins through localized dispersant production. This asymmetry reshapes procurement patterns across automotive refinish and architectural segments.
United States
Automotive collision repair networks in Detroit and the Southeast drive dispersant demand for color-matching precision. EPA National Ambient Air Quality Standards enforce VOC limits that accelerate waterborne system adoption. The Gulf Coast industrial corridor sustains solvent-borne rheology modifier consumption where humidity resistance standards exceed current waterborne benchmarks.
Germany
Tier-one refinish chains in Stuttgart specify polymeric dispersants for metallic and pearl effect coatings. REACH compliance and the EU Green Deal mandate bio-based feedstocks and silicone-free defoamers across formulations. The Rhine-Ruhr chemical cluster anchors application-specific testing laboratories that compress supplier qualification cycles.
China
Domestic paint production scaling in the Yangtze River Delta and Pearl River Delta concentrates additive demand. MEE dual carbon goals tighten emissions from solvent-borne coating operations. Shanghai metropolitan clusters host co-located supplier laboratories serving consolidated collision repair networks.
India
Urban construction acceleration in Maharashtra and Gujarat generates dispersant demand for decorative paint formulations. BIS standards alignment creates procurement specifications for cost-optimized additive packages. The Delhi-NCR corridor attracts regional distributor networks serving mid-tier paint manufacturers.
Japan
Shipbuilding yards in Nagoya and Kyushu specify anti-corrosive additive systems for new-build hull protection. METI industrial standards govern coating performance in marine applications. The Kansai region maintains specialty defoamer demand for precision electronics coatings.
Paints and Coatings Additives Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Integrated petrochemical conglomerates leverage captive feedstock control across dispersant lines, while specialty additive houses anchor premium positioning through application-specific testing infrastructure. Three archetypes dominate: vertically integrated resin producers, independent specialty chemical suppliers, and mining-linked rheology modifier specialists. Competitive moves concentrate on backward integration into raw material supply and direct technical service relationships with tier-one formulators.
Among European-headquartered specialists, BASF SE and BYK-Chemie GmbH exemplify divergent strategic positions. BASF SE represents the integrated archetype with petrochemical feedstock control, while BYK-Chemie GmbH occupies the application-specific testing tier. Elementis plc anchors the mining-linked specialist category with natural hectorite clay supply positions.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Evonik Industries AG |
| BYK-Chemie GmbH |
| Clariant AG |
| The Lubrizol Corporation |
| Arkema |
| Altana AG |
| Elementis plc |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for natural hectorite clay rheology modifiers concentrate pricing power with mining-linked suppliers in the US Gulf Coast and Rotterdam-Antwerp corridor, while petrochemical feedstock volatility compresses margins for non-integrated additive houses dependent on spot propylene oxide and ethylene oxide purchases.
Pricing Analysis
The customization-premium spread between configured-to-order polymeric dispersants and standard surfactant-based pigment stabilizers runs wide in automotive refinish networks, where tier-one collision repair chains in Stuttgart and Detroit specify anchor-group density optimization for metallic flop control. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and technical service bundling, with REACH-compliant bio-based dispersants commanding the highest tier. Pricing pressure stems from Chinese domestic dispersant production scaling that erodes import margins in architectural segments. Mid-tier paint manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize performance consistency over unit cost.
Supply Chain Analysis
Germany and China anchor polymeric dispersant production, with the Rhine-Ruhr chemical cluster hosting application-specific testing laboratories and the Yangtze River Delta scaling cost-optimized grades for domestic paint manufacturers. Feedstock supply draws from captive petrochemical streams at integrated resin producers and mining-linked natural hectorite deposits concentrated in specific geographies. Single-source vulnerability for thixotropic rheology modifiers creates supply chain risk for industrial sealant formulators. Distribution runs through direct technical service relationships with tier-one automotive refinishers and regional chemical distributors serving mid-tier architectural formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as digital color-matching systems and integrated body shop management platforms create interoperability requirements that favor additive suppliers embedding spectrophotometry-compatible dispersant systems.
For Market Incumbents: Secure captive feedstock control through backward integration into propylene oxide and ethylene oxide supply, or through long-term offtake agreements with petrochemical producers. Lock in tier-one automotive refinish network relationships by co-locating application laboratories in Stuttgart, Detroit, and Shanghai metropolitan clusters before eighteen-month qualification windows compress further. Defend against Chinese domestic dispersant producers by accelerating REACH-compliant bio-based platform development.
For New Entrants and Emerging Players: REACH certification fast-track through partnership with established testing laboratories in Germany offers entry into European automotive refinish specifications. Target India's architectural coatings expansion in Maharashtra and Gujarat with cost-optimized dispersant packages aligned to BIS standards. Pursue distributor-led technical service models serving mid-tier paint manufacturers in Delhi-NCR corridor as lowest-friction go-to-market pathway.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core additive portfolios with stranded mining-linked rheology modifier assets. Long-term viability over the next decade hinges on waterborne system performance gaps closing in automotive OEM humidity resistance. Watch for MEE dual carbon goal enforcement tightening as signal of Chinese solvent-borne coating phase-out acceleration that would revalue waterborne additive specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive propylene oxide access insulates BASF SE from petrochemical volatility compressing specialty additive house margins. |
| Application Laboratory Co-location | Direct technical service relationships in Stuttgart and Detroit compress supplier qualification cycles for tier-one refinish networks. |
| Bio-based Dispersant Platform Development | Renewable feedstock-derived pigment stabilizers capture ESG procurement premiums across European formulator specifications. |
| Regional Distribution Network Expansion | Delhi-NCR corridor distributor partnerships unlock mid-tier paint manufacturer access in India's accelerating urban construction markets. |
| Digital Color-Matching System Integration | Spectrophotometry-compatible dispersant systems embed additive suppliers into consolidated collision repair management platforms. |
Research Approach
Desk research of customs trade data, SEC 10-K filings from petrochemical and specialty chemical companies, and REACH registration databases preceded structured interviews with plant managers at integrated resin producers, procurement leads at automotive OEM coating operations, distribution channel partners serving architectural formulator accounts, and technical R&D directors at specialty additive houses. Bottom-up volume modeling across dispersant, rheology modifier, defoamer, and wetting agent product categories triangulated against top-down paint production estimates from national industry associations.
Variance decomposition across product type, application end-use, technology platform, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory analysis incorporating regulatory phase-out timelines for solvent-borne systems, domestic supply chain maturation curves in China, and automotive refinish network consolidation patterns. Forecast inputs included MEE dual carbon goal enforcement intensity, REACH bio-based mandate progression, and collision repair platform standardization adoption rates.
Underlying assumptions cover sustained petrochemical feedstock availability, regulatory timeline adherence without major delays, and technology performance gap closure in waterborne automotive OEM coatings, with deviation risk concentrated in natural hectorite clay supply disruptions and multi-jurisdiction VOC limit divergence. Recalibration cycles align with material shifts in EPA National Ambient Air Quality Standards enforcement, EU Green Deal implementation milestones, and Chinese domestic additive production capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Road Marking Paints and Coatings Market