
 Resins in Paints and Coatings Market | 2026-2036
Resins in Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Resins in Paints and Coatings Market Analytics
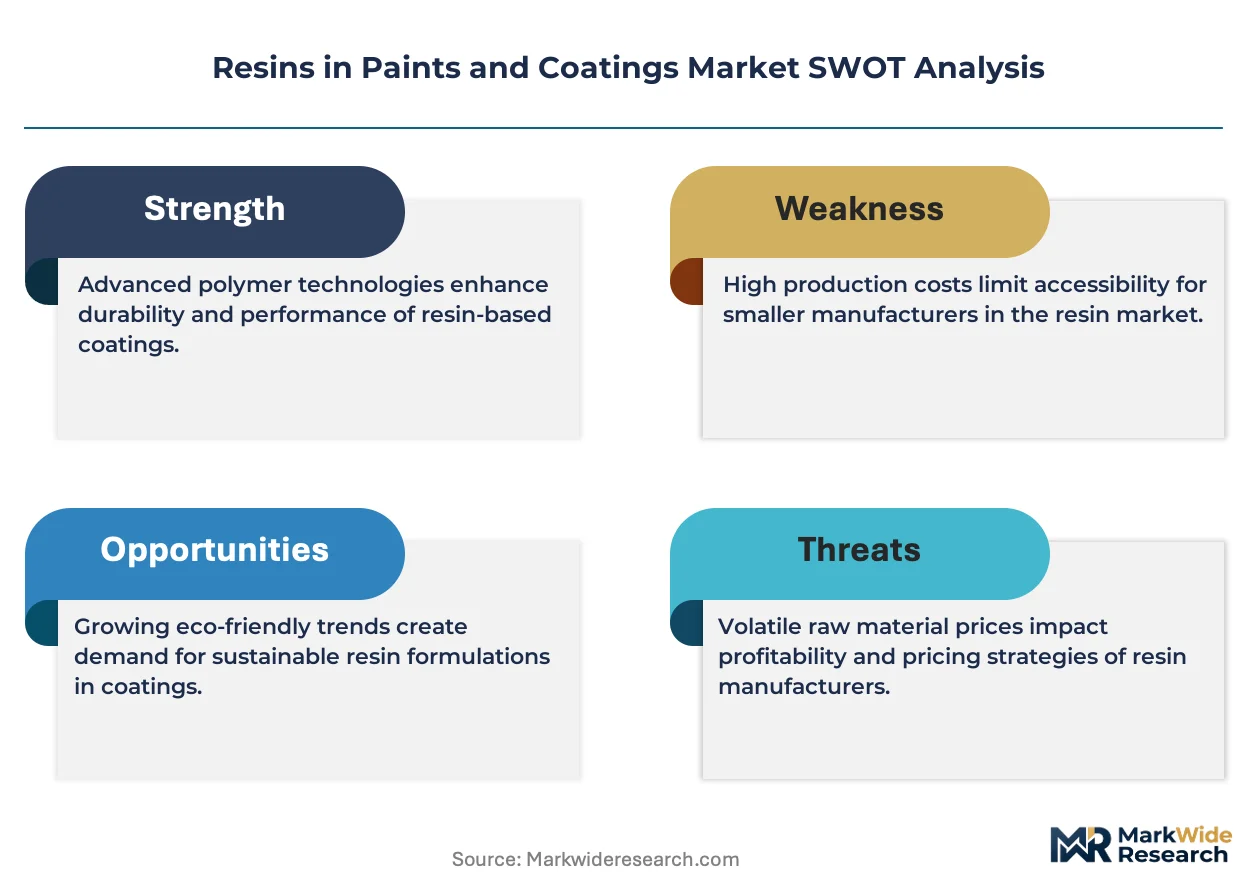
A shortage of polymer chemists and formulation scientists is redrawing competitive boundaries across the resins value chain. BASF SE leverages its integrated petrochemical backbone to secure captive supply of acrylic and polyurethane precursors. Dow Chemical Company anchors its position through R&D intensity in water-borne epoxy technologies. PPG Industries competes via specialized automotive coating resins tailored to OEM specification cycles.
Resins in paints and coatings constitute polymeric binders—typically alkyd, acrylic, epoxy, polyurethane, or polyester—synthesized through condensation or addition polymerization to form continuous films with defined gloss, adhesion, and chemical resistance. These binders determine coating durability, cure speed, and substrate compatibility across industrial, architectural, and transportation applications. Acrylic resins lead volume in architectural coatings due to their UV stability and water-borne compatibility, while polyurethane resins command premium positioning in automotive and industrial segments for abrasion resistance. Epoxy resins dominate marine and protective coatings where chemical resistance requirements are most severe.
EPA regulations on volatile organic compound emissions restrict solvent-based formulation sales in the United States, while REACH registration requirements in Europe impose substance-level disclosure burdens on importers. China's MEE enforces dual carbon goals that tighten industrial coating emissions standards nationwide. Stakeholders must monitor regulatory divergence between jurisdictions when allocating reformulation investments and qualifying alternative chemistries.
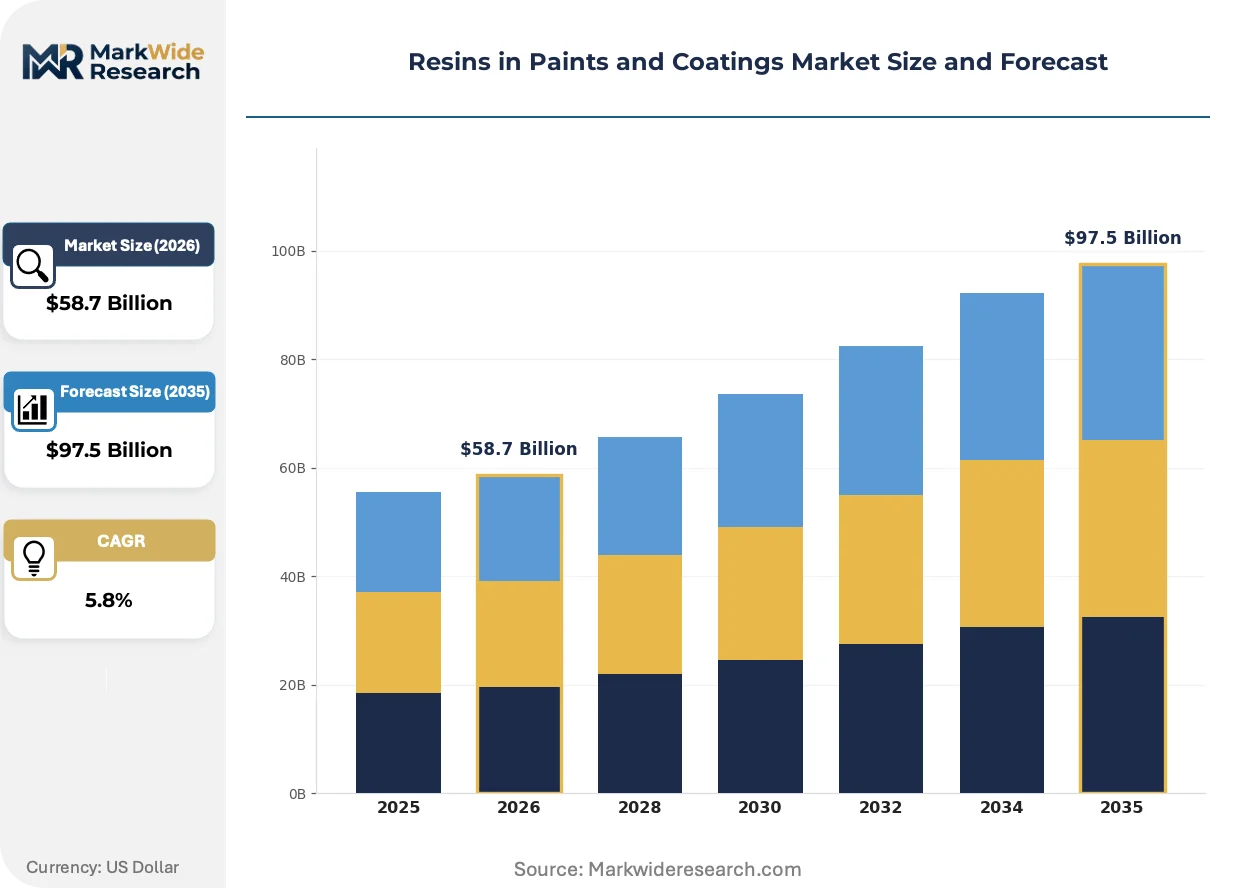
Market Dynamics
Water-borne resin technologies are compressing solvent-based formulation margins as automotive OEMs and architectural specifiers rewrite material standards. This transition redistributes value toward polymer chemists capable of matching performance parity at lower volatile organic compound loads.
Growth Catalysts
- REACH Registration Requirements:ECHA substance-level disclosure mandates force European importers toward pre-registered resin portfolios. This accelerates qualified supplier consolidation among compliant formulators.
- Construction Clusters:China's Yangtze River Delta and Pearl River Delta concentrate architectural coating demand. Local resin production scales to serve prefabricated building growth and infrastructure rehabilitation programs.
- UV-Curable Acrylics:Furniture and flooring manufacturers adopt radiation-cured systems for instant handling and reduced energy curing. This technology penetrates wood coating lines previously dominated by thermal-cure alkyds.
Market Restraints
- Propylene Oxide Volatility:Polyurethane resin costs fluctuate with propylene oxide supply interruptions from Gulf Coast petrochemical complexes. Formulators lack short-term hedging instruments for this captive feedstock.
- Epoxy Curing Agent Concentration:Aliphatic amine production concentrates among Asian specialty chemical producers. Western coating manufacturers face extended lead times and qualification bottlenecks for corrosion-resistant marine formulations.
- Performance Gap in High-Gloss Industrial:Water-borne polyurethanes still fall short of solvent-borne equivalents in humidity resistance for agricultural equipment finishes. OEM specification locks sustain solvent dependency in this sub-segment.
Strategic Opportunities
- India PLI Scheme for Chemicals:Production-linked incentives attract greenfield resin investments for domestic architectural and automotive coating supply. Early entrants capture import substitution premiums before local capacity saturates.
- Wind Turbine Blade Coatings:Epoxy and polyurethane formulations for offshore wind towers represent unserved specification demand. Resin suppliers can co-develop erosion-resistant topcoats with blade manufacturers.
- Digital Color Matching Integration:Cloud-based spectrophotometry platforms enable just-in-time tinted resin dispensing at distributor level. This compresses inventory carrying costs for mid-sized architectural coating retailers.
Industry Challenges
- Polymer Chemist Scarcity:Formulation science programs at technical universities produce insufficient graduates for water-borne resin adaptation. Incumbents poach talent rather than develop pipelines.
- Multijurisdictional Qualification Timelines:Automotive OEMs require 18-24 month resin validation cycles spanning EPA, REACH, and China MEE compliance. Parallel submission costs delay revenue recognition.
- Legacy Solvent System Stranding:Coatings manufacturers with sunk capital in thermal oxidizers and solvent recovery face write-down pressure. Asset-light competitors bypass this burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resins in Paints and Coatings Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Epoxy, Polyurethane, Acrylic Application: Industrial Coatings, Architectural Coatings, Automotive Coatings, Marine Coatings End User: Construction, Automotive, Aerospace, Furniture Formulation Type: Solvent-Based, Water-Based, Powder Coatings, High Solids |
| Companies Covered | BASF SE, Dow Chemical Company, The Sherwin-Williams Company, PPG Industries, Arkema, Akzo Nobel, Axalta Coating Systems, Allnex GmbH, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resins in Paints and Coatings Market Evolving Landscape
Bio-based feedstock substitution and digital formulation platforms are restructuring how resin suppliers engage specification holders. These shifts compress development cycles while raising transparency requirements across the value chain.
Water-borne polyurethane dispersions are supplanting solvent-borne two-component systems in automotive refinish and plastic substrate applications. Tier 1 suppliers to German and Japanese OEMs now specify aqueous basecoats for bumper and fascia production. This transition compresses emissions compliance costs while demanding reformulated isocyanate crosslinkers with extended pot life.
EPA National Emission Standards for Hazardous Air Pollutants tighten coating operation permits across metal furniture, automotive, and aerospace segments. Facilities must demonstrate maximum achievable control technology for organic hazardous air pollutants or face production caps. Southern US industrial coating clusters respond by consolidating thermal oxidizer investments across multi-tenant finishing parks.
Coatings procurement through integrated distributor platforms now captures specification influence previously held by raw material suppliers. Large architectural contractors in Australia and Canada aggregate resin volumes through digital tendering systems that reverse-engineer formulation costs. This disintermediation forces resin manufacturers to defend value through technical service rather than opaque pricing structures.
Resins in Paints and Coatings Market Segmentation
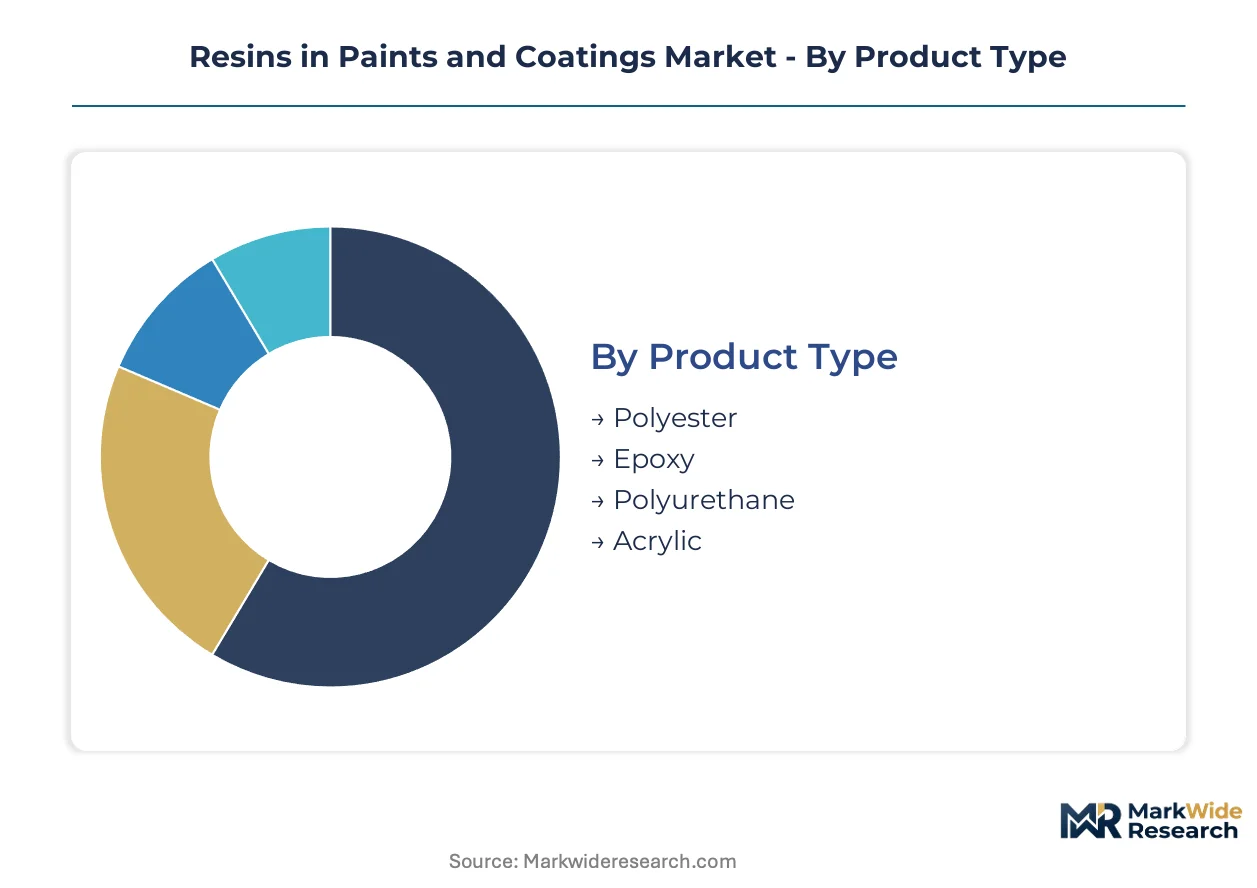
Resin selection dictates compliance pathways and performance specifications across coating formulations. Segmentation reveals where regulatory pressure and end-use requirements create divergent margin structures.
Product Type:
REACH substance registration thresholds and EPA hazardous air pollutant limits reshape competitive positioning by resin chemistry.
- Acrylic:UV-stable thermoplastic binders dominate architectural exterior finishes through water-borne compatibility. Construction clusters in China's Yangtze River Delta absorb volume for prefabricated building rehabilitation programs.
- Polyurethane:Isocyanate-crosslinked systems deliver abrasion resistance for automotive OEM clearcoats and industrial flooring. German and Japanese tier-1 suppliers now mandate aqueous basecoats for bumper production, compressing solvent-borne margins.
- Epoxy:Bisphenol-A and novolac variants anchor marine protective coatings where chemical resistance requirements are most severe.
- Polyester:Saturated and unsaturated formulations serve powder coating lines for agricultural equipment and appliance finishes.
Acrylic handles the majority of throughput; polyurethane is expanding most quickly on specification share.
Application:
Automotive OEM qualification cycles and marine classification society rules create divergent validation timelines by end-use.
- Architectural Coatings:Exterior wall and roof systems prioritize UV durability and VOC compliance. China's dual carbon goals under MEE tighten industrial coating emissions standards nationwide, favoring water-borne acrylic adoption.
- Industrial Coatings:Metal furniture, machinery, and agricultural equipment finishes balance corrosion protection with production throughput. EPA National Emission Standards for Hazardous Air Pollutants force thermal oxidizer investments across southern US finishing parks.
- Automotive Coatings:OEM clearcoats and refinish systems demand scratch resistance and appearance retention.
- Marine Coatings:Ballast tank and hull protection systems face extended qualification through classification societies.
Architectural coatings carry the volume base; automotive coatings are climbing the fastest on reformulation intensity.
End User:
Construction procurement consolidation and aerospace qualification rigidity segment resin specification authority.
- Construction:General contractors and prefabricated building manufacturers aggregate coating volumes through digital tendering platforms in Australia and Canada.
- Automotive:OEM specification cycles span 18-24 months across EPA, REACH, and China MEE compliance submissions.
- Furniture:Wood coating lines adopt UV-curable acrylics for instant handling and reduced energy curing.
- Aerospace:OEM and MRO coating specifications demand flame resistance and weight minimization.
Construction commands the demand base; automotive is gaining share fastest on water-borne transition mandates.
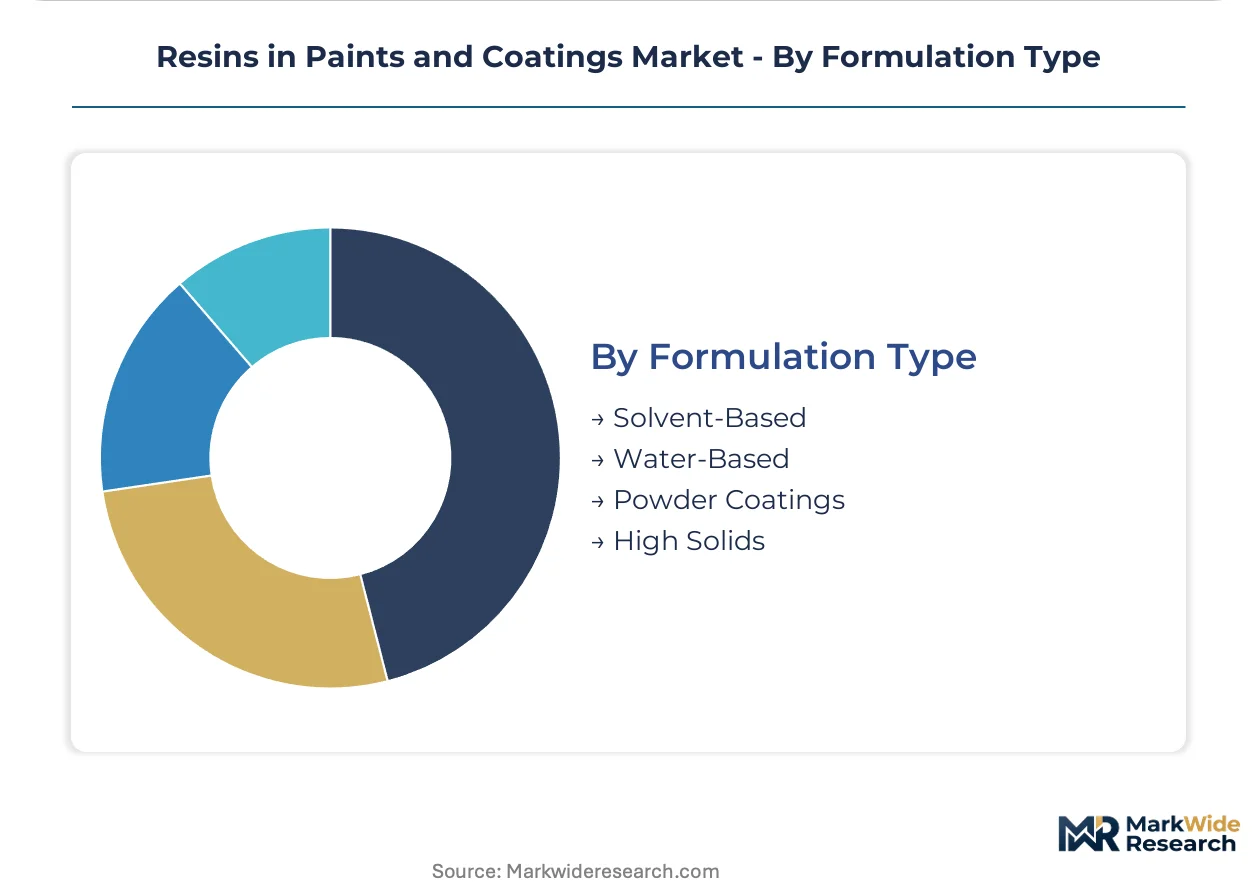
Formulation Type:
Emissions regulations and energy costs stratify margin structures by cure mechanism and carrier system.
- Water-Based:Dispersed polymer particles replace organic solvents in architectural and automotive refinish applications. EPA VOC restrictions and REACH registration burdens accelerate qualified supplier consolidation.
- Powder Coatings:Thermosetting resins cure without carriers, eliminating VOC emissions entirely. Energy costs for bake ovens concentrate adoption in high-throughput appliance and furniture lines.
- Solvent-Based:High-solids alkyds and two-component polyurethanes retain specification lock in high-gloss agricultural equipment finishes where humidity resistance gaps persist.
- High Solids:Reduced solvent load formulations bridge compliance and performance in industrial maintenance coatings.
Water-based formulations absorb the reformulation investment; powder coatings show the steepest expansion trajectory on energy cost arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. China's construction clusters absorb water-borne acrylics at scale. German automotive OEMs mandate aqueous polyurethane clearcoats. US industrial coaters face EPA thermal oxidizer investments. India's PLI scheme attracts greenfield resin capacity.
China
Prefabricated building rehabilitation and infrastructure renewal drive architectural coating demand. MEE dual carbon goals tighten industrial emissions standards nationwide. The Yangtze River Delta concentrates resin production to serve prefabricated construction clusters.
Germany
Tier-1 automotive suppliers specify aqueous basecoats for bumper and fascia production. REACH substance registration thresholds force qualified supplier consolidation. The Ruhr industrial corridor hosts specialized polyurethane resin formulation for OEM clearcoat applications.
United States
Metal furniture and agricultural equipment finishing sustains solvent-borne demand in humidity-critical segments. EPA National Emission Standards for Hazardous Air Pollutants mandate thermal oxidizer investments. Southern US finishing parks consolidate multi-tenant emissions control infrastructure.
India
Construction procurement digitization aggregates coating volumes through tendering platforms. PLI scheme production-linked incentives attract greenfield resin investments. Gujarat and Maharashtra industrial corridors scale domestic supply for import substitution.
Japan
Automotive refinish and plastic substrate coating specifications prioritize scratch resistance and appearance retention. METI industrial standards guide water-borne technology adoption. The Nagoya-Toyota industrial zone concentrates OEM specification development for aqueous polyurethane systems.
Resins in Paints and Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in resin supply. Petrochemical-backed players control captive feedstock for acrylic and polyurethane precursors. Formulation specialists compete on qualification speed and technical service. Capacity expansion and portfolio diversification toward water-borne technologies dominate competitive moves.
Among integrated chemical conglomerates, BASF SE and Dow Chemical Company exemplify upstream-controlled positioning through captive precursor supply. PPG Industries occupies a specialist tier focused on automotive OEM specification cycles. These three anchors represent divergent competitive archetypes: feedstock integration, technology licensing intensity, and end-use specification capture.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| The Sherwin-Williams Company |
| PPG Industries |
| Arkema |
| Akzo Nobel |
| Axalta Coating Systems |
| Allnex GmbH |
| RPM International |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Gulf Coast propylene oxide facilities shapes both supply concentration and price floors for polyurethane resin producers. Asian acrylic acid producers operate at tighter margins, compressing global pricing benchmarks for water-borne architectural binders.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated resin producers and automotive OEMs, while spot purchasing persists for small-batch architectural coating formulators. Price differentiation hinges on REACH registration status and ISO 14001 environmental certification tiers. Cost compression in standard-grade acrylics is intensifying because Chinese producers are expanding water-borne capacity. Tier 1 automotive suppliers demonstrate the lowest price sensitivity due to specification lock-in, whereas mid-sized architectural distributors negotiate aggressively on volume.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for epoxy curing agents sourced from Chinese specialty chemical producers. Manufacturing concentrates in China, Germany, and the United States for distinct resin chemistries. Formulation draws from propylene oxide, bisphenol-A, and aliphatic amine feedstocks. Single-source vulnerability concentrates in Asian aliphatic amine production for marine coating applications. Distribution runs through integrated distributor platforms that aggregate volumes for large architectural contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The resins market is entering a cyclical recovery phase as automotive production normalization and construction rehabilitation programs rebuild coating demand. Inventory destocking across European industrial coatings has largely concluded.
For Market Incumbents: Consolidate formulation science capabilities through targeted hiring of polymer chemists scarce in water-borne adaptation. Deepen backward integration into acrylic acid production to defend margin position against Chinese capacity expansion. Prioritize REACH pre-registration portfolios to accelerate qualified supplier status for European automotive OEMs.
For New Entrants and Emerging Players: Technical service gaps in just-in-time color matching represent the most penetrable white-space target for mid-sized architectural distributors. Geographic white space concentrates in India's Gujarat and Maharashtra corridors before local capacity saturates. Pursue co-development partnerships with wind turbine blade manufacturers for erosion-resistant epoxy topcoats as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among resin suppliers with locked automotive OEM qualification cycles spanning EPA, REACH, and China MEE compliance. Long-term viability favors targets with demonstrated water-borne polyurethane expertise and captive precursor supply. Monitor automotive OEM specification releases as the critical inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive precursor supply insulates margins from Chinese capacity-driven price volatility. |
| Water-Borne Polyurethane R&D Expansion | German and Japanese OEM mandates for aqueous basecoats create specification capture opportunities. |
| REACH Pre-Registration Portfolio Buildout | ECHA substance disclosure compliance accelerates qualified supplier consolidation among European formulators. |
| Wind Turbine Blade Coating Co-Development | Offshore wind tower specifications represent unserved demand for erosion-resistant epoxy formulations. |
| Digital Color Matching Platform Integration | Cloud-based spectrophotometry compresses inventory costs for architectural coating distributors. |
Research Methodology
Desk research of trade association publications, customs data, and regulatory filings preceded structured interviews with polymer chemists, automotive OEM procurement managers, architectural coating formulators, and distribution channel partners. Primary fieldwork combined plant-level capacity assessments with downstream demand validation. Secondary sources incorporated ACC and Cefic industry reports, SEC 10-K disclosures, and EPA enforcement databases. Bottom-up resin volume estimates triangulated against top-down coating consumption models.
Variance decomposition across product type, application, formulation technology, and regional production hub informed the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers. Modeled inputs included automotive OEM specification cycle timing, MEE dual carbon compliance trajectories, and propylene oxide feedstock cost indices.
Forecasts assume regulatory continuity in EPA hazardous air pollutant standards, REACH substance registration thresholds, and China MEE emissions frameworks; material policy shifts would require re-modeling of reformulation investment timelines and qualification bottlenecks. Recalibration cycles align with material shifts in automotive specification releases and construction procurement digitization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Radar Absorbing Paint Market