
 Europe UV Stabilizers Market | 2026-2036
Europe UV Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe UV Stabilizers Market Foresight
The capital-intensity divergence between integrated polymer-compounders and standalone additive suppliers is rotating competitive advantage toward firms with captive resin relationships. BASF SE leverages its Ludwigshafen Verbund structure to backward-integrate hindered amine synthesis with polyamide compounding. Evonik Industries AG sustains technology leadership through its specialty methacrylate backbone chemistry for high-performance UV absorbers. Clariant anchors its position via controlled distribution partnerships with Mediterranean masterbatch producers.
UV stabilizers comprise organic molecules—principally hindered amine light stabilizers, benzotriazole derivatives, and hydroxyphenyl triazine UV absorbers—that interrupt photodegradation pathways in polymers by scavenging free radicals or absorbing ultraviolet radiation in the 290–400 nm range. These additives extend service life of plastics, coatings, and textiles exposed to solar irradiation. Hindered amine light stabilizers command the largest volume share due to their regenerative stabilization mechanism and broad polyolefin compatibility. Benzotriazole UV absorbers concentrate margin pools in automotive clearcoat applications where color retention specifications are most stringent. The agriculture films segment within plastics end-use is gaining structural attention as greenhouse operators across Almería and the Netherlands adopt multi-season films requiring extended UV protection.
REACH registration requirements administered by ECHA mandate full toxicological dossiers for UV stabilizer substances above one tonne annual volume, elevating compliance costs for importers. The EU Green Deal's Circular Economy Action Plan and impending packaging waste regulations are pressing formulators to demonstrate additive recyclability and reduced migration into food-contact layers. The F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents indirectly affects stabilizer demand profiles in insulation foams. Stakeholders must monitor the CSRD's supply-chain disclosure mandates, which will require granular reporting on chemical additive sourcing from the 2026 reporting cycle onward.
Market Dynamics
REACH registration requirements administered by ECHA are compressing the supplier base by elevating compliance costs above one tonne annual volume thresholds, forcing smaller importers to exit while integrated compounders capture share through captive stabilizer synthesis.
Growth Catalysts
- Automotive Exterior Specifications:German and French component manufacturers are expanding procurement of hindered amine light stabilizers for polyamide and polypropylene bumper fascias, fender liners, and mirror housings requiring decade-long color retention.
- EU Green Deal Durability Mandates:The Circular Economy Action Plan's push for extended product lifecycles is tightening additive migration limits and rewarding stabilizer formulations that enable multi-use plastic recycling without performance degradation.
- Greenhouse Film Multi-Seasoning:Agriculture operators across Almería and the Netherlands are adopting UV-protected films lasting three to five growing seasons, replacing annual replacement cycles and expanding stabilizer loadings per hectare under cover.
Market Restraints
- Feedstock Concentration Risk:Key hindered amine precursors rely on concentrated C4 hydrocarbon supply from Northeast European crackers, exposing stabilizer producers to naphtha price volatility and force majeure disruptions.
- Substitution by Inorganic Alternatives:Nano-scale cerium oxide and zinc oxide UV blockers are capturing share in personal care packaging and cosmetic applications where organic additive migration faces EFSA scrutiny.
- REACH Dossier Cost Burden:Full toxicological registration for novel stabilizer substances requires two to four million euro investment per substance, freezing innovation pipelines for mid-tier specialty chemical houses.
Strategic Opportunities
- Poland and Czech Republic Manufacturing Expansion:Automotive supplier parks in Lower Silesia and Moravia are attracting compounder investments, creating demand for localized stabilizer blending and technical service capabilities.
- CSRD Supply-Chain Disclosure Tailwinds:The Corporate Sustainability Reporting Directive's 2026 implementation will require granular chemical additive sourcing transparency, advantaging stabilizer producers with certified mass-balance and bio-attributed product lines.
- Recyclate-Compatible Formulations:Stabilizer systems engineered for compatibilization with post-consumer polyolefin recyclate streams address the EU Packaging and Packaging Waste Regulation's recycled content mandates.
Industry Challenges
- Photochemistry Specialization Scarcity:Formulation chemists with expertise in radical scavenging kinetics and polymer photophysics command premium compensation, constraining R&D throughput at independent additive houses.
- Multi-Regulatory Compliance Parallelism:Simultaneous navigation of REACH substance restrictions, F-Gas Regulation indirect effects on foam applications, and emerging food-contact migration limits strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe UV Stabilizers Market |
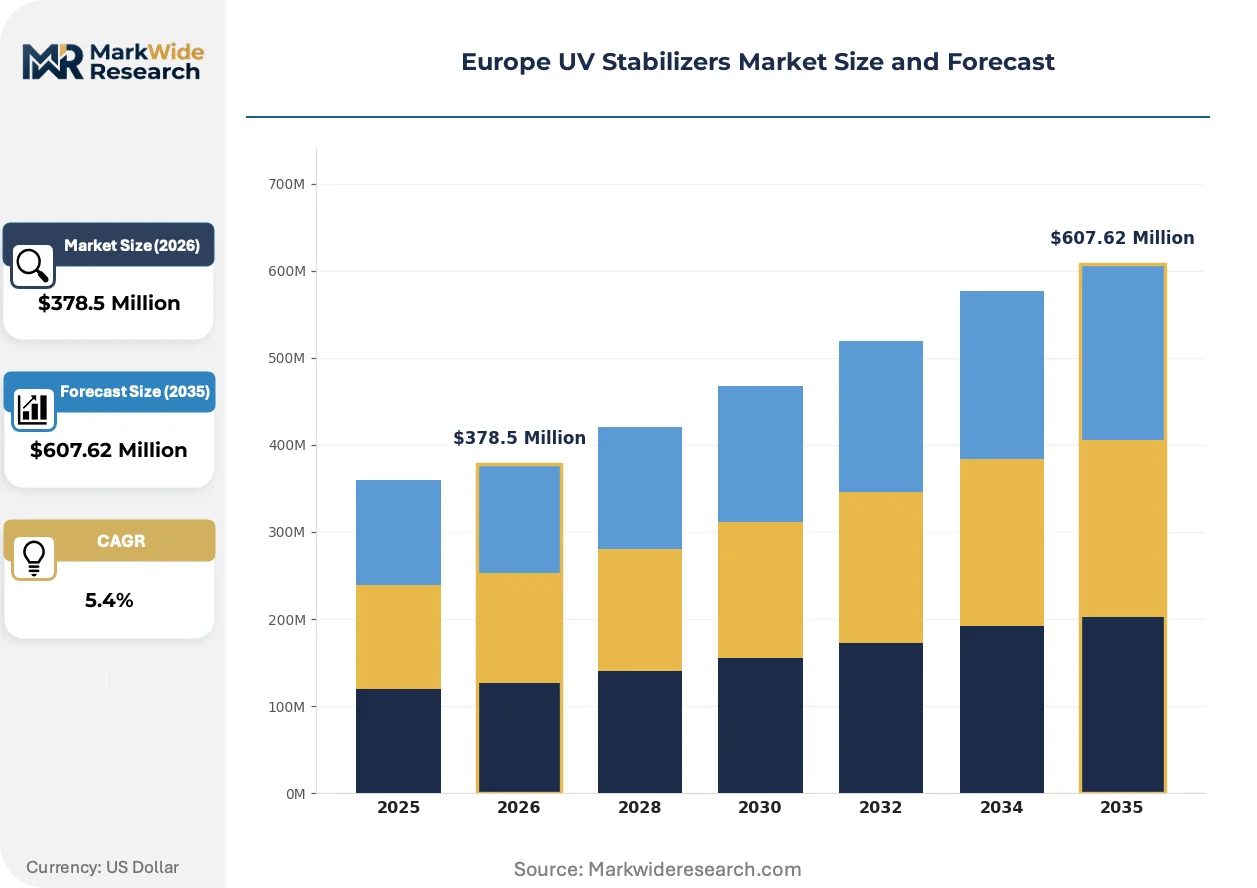
| Market Size in 2026 | $378.5 Million |
| Market Size in 2035 | $607.62 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Amine Light Stabilizers, Benzotriazole, UV Absorbers, Other Additives End User: Plastics Industry, Coatings Sector, Textiles, Adhesives Application: Agriculture Films, Automotive Components, Construction Materials, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, Clariant, Evonik Industries AG, Syensqo SA/NV, Songwon Industrial Co., Ltd., ADEKA CORP., SABO S.p.A., Arkema, Solvay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe UV Stabilizers Market Shifts & Advancements
Reactive UV stabilizer grafting onto polymer backbones is dissolving the boundary between additive and matrix, enabling permanent anchoring that eliminates migration risks and opens food-contact applications previously closed to conventional stabilizers.
Oligomeric hindered amine light stabilizers with molecular weights exceeding three thousand daltons are miniaturizing the migration profile of exterior automotive coatings while maintaining surface concentration through reduced volatility and extractability. Tier-one clearcoat formulators in Stuttgart and Turin are qualifying these macromolecular stabilizers for ten-year warranty programs. The technology is miniaturizing the performance gap between OEM specification and refinish market durability, compressing aftermarket stabilizer demand into premium segments.
The F-Gas Regulation's hydrofluorocarbon phase-down is redirecting stabilizer demand profiles in polyurethane insulation foams toward hydrofluoroolefin-blown systems requiring reformulated thermal-oxidative protection packages. Boardstock producers in the Benelux are retrofitting continuous lamination lines to accommodate these chemistry shifts. Construction segment procurement teams are now specifying stabilizer performance under accelerated aging protocols that simulate fifty-year building envelope lifecycles.
Masterbatch producers are consolidating direct distribution relationships with greenhouse operators and agricultural cooperatives, disintermediating traditional regional distributors in the Mediterranean horticulture belt. This channel compression is transferring technical advisory responsibilities from distributors to compounder field teams. Spanish and Italian growers now expect on-site photostability testing and season-extension calculations as standard pre-sale services.
Europe UV Stabilizers Market Segmentation
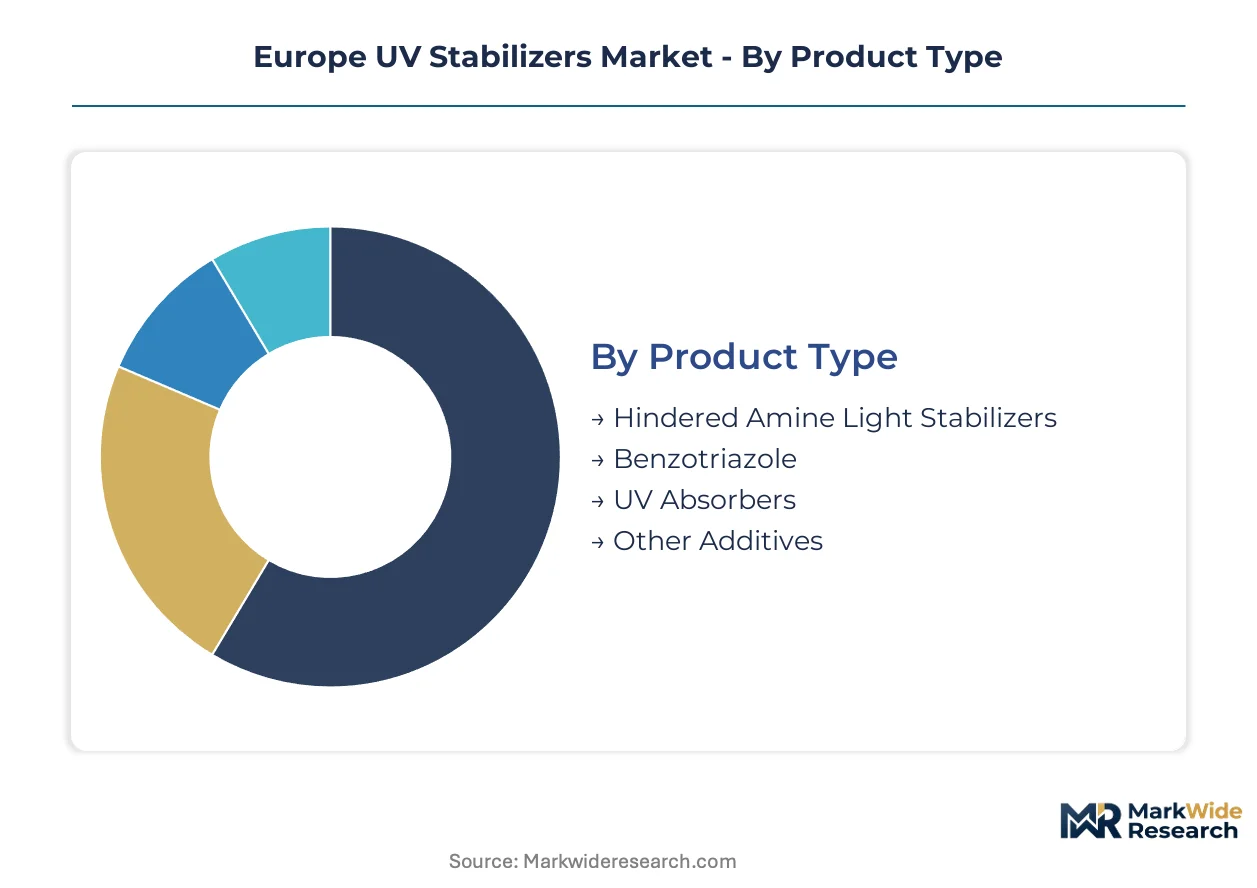
UV stabilizer procurement patterns diverge sharply across product chemistries and end-use specifications. Formulators must align additive selection with polymer matrix compatibility, regulatory exposure limits, and durability requirements specific to each application environment.
Product Type:
Margin pools concentrate in high-performance stabilizer chemistries where synthesis complexity and regulatory dossier investments erect barriers to commoditization.
- Hindered Amine Light Stabilizers:These regenerative radical scavengers operate through a cyclic mechanism that consumes and regenerates the active nitroxyl radical during photodegradation cycles. German and French automotive component manufacturers specify these for exterior polyamide and polypropylene applications requiring decade-long service life under solar exposure.
- Benzotriazole:UV absorbers in this class deliver precise absorption in the 290-350 nm range with minimal color contribution to transparent substrates. Stuttgart and Turin clearcoat formulators specify these for automotive OEM warranty programs demanding ten-year color retention guarantees.
- UV Absorbers:Hydroxyphenyl triazine derivatives dominate high-temperature processing applications where benzotriazole volatility limits performance.
- Other Additives:Nickel quenchers and benzoate photostabilizers serve niche applications in agricultural films and specialty fibers.
The dominant share belongs to Hindered Amine Light Stabilizers, while Benzotriazole is closing the gap fastest through automotive clearcoat specification upgrades.
End User:
Volume throughput scales with polymer processing intensity and outdoor exposure requirements across manufacturing sectors.
- Plastics Industry:Polyolefin processors in Northern Italy's packaging corridor and Germany's automotive belt consume stabilizer masterbatches for films, injection molded components, and extruded profiles. REACH migration limits and EU Green Deal recyclability mandates are forcing reformulation toward oligomeric, non-migrating stabilizer architectures.
- Coatings Sector:Automotive OEM and refinish clearcoats, industrial metal coatings, and wood finishes require UV absorber-HALS synergist packages tailored to substrate-specific degradation mechanisms.
- Textiles:Technical fibers for outdoor upholstery and automotive interiors specify stabilizers resistant to dye bath conditions and thermal fixation processes.
- Adhesives:Construction sealants and automotive bonding tapes incorporate stabilizers to prevent embrittlement at bond lines exposed to joint movement and weathering.
Plastics Industry commands the largest volume position, though Coatings Sector applications are expanding most quickly through automotive specification tightening.
Application:
Service life requirements and climatic exposure severity determine stabilizer loading rates and chemistry selection across end-use environments.
- Agriculture Films:Greenhouse operators across Almería and the Netherlands are adopting multi-season films lasting three to five growing cycles, replacing annual replacement and expanding stabilizer loadings per hectare under cover. Masterbatch producers now deliver on-site photostability testing as standard pre-sale service.
- Automotive Components:Exterior applications including bumper fascias, fender liners, mirror housings, and lighting lenses specify decade-long color and impact retention under aggressive UV, thermal, and chemical exposure.
- Construction Materials:Roofing membranes, window profiles, and insulation foams require stabilizer packages validated under accelerated aging protocols simulating fifty-year building envelope lifecycles.
- Consumer Goods:Personal care packaging and cosmetic applications face EFSA scrutiny on organic additive migration, opening share capture opportunities for nano-scale inorganic UV blockers.
Agriculture Films holds the steepest expansion trajectory, while Automotive Components maintains the highest value per kilogram specification density.
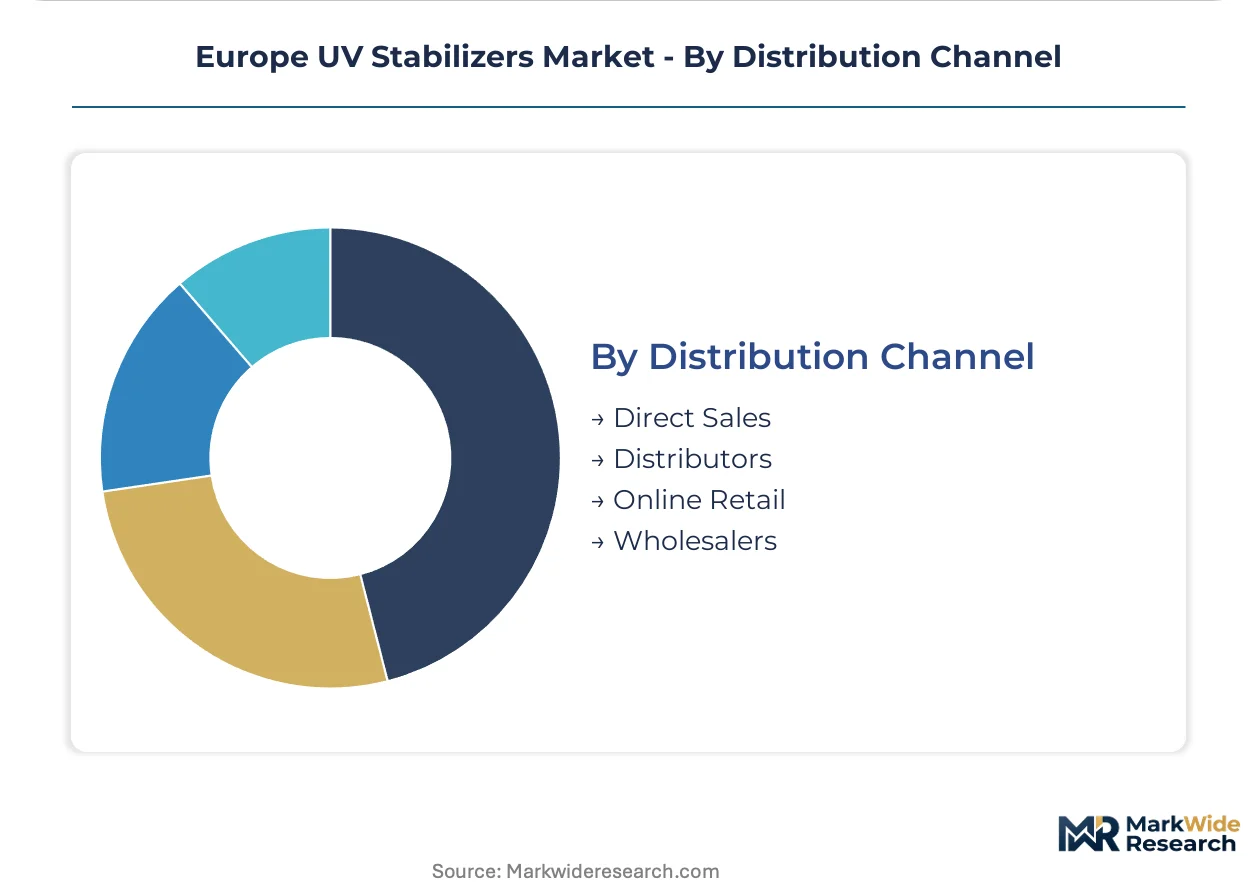
Distribution Channel:
Technical service intensity and order fragmentation shape channel economics across customer segments.
- Direct Sales:Integrated polymer compounders and large automotive Tier-1s procure stabilizer packages through direct technical partnerships with producers like BASF and Evonik, leveraging captive synthesis and formulation support.
- Distributors:Regional additive distributors serve mid-tier processors with inventory buffering and blending services, though channel compression is transferring technical advisory responsibilities to compounder field teams.
- Online Retail:Standardized stabilizer grades for small-volume processors and maintenance repair operations are migrating to digital procurement platforms.
- Wholesalers:Commodity masterbatch producers in Mediterranean horticulture belts source through consolidated wholesale relationships disintermediating traditional regional distributors.
Direct Sales captures the premium specification tier, while Distributors are gaining share fastest through localized technical service investments in Poland and Czech Republic manufacturing expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southern Europe's horticulture belt exhibit acute price sensitivity toward standard stabilizer grades, while German automotive compounders absorb premium pricing for decade-warranty specifications without volume elasticity.
Germany
Automotive component manufacturers in Stuttgart and Munich specify hindered amine light stabilizers for polyamide bumper fascias and mirror housings requiring ten-year color retention. ECHA REACH dossier requirements elevate compliance costs for imported additives, favoring domestic compounders with captive synthesis capabilities. The Ludwigshafen chemical cluster anchors backward-integrated stabilizer production serving both automotive OEMs and construction boardstock producers.
France
Clearcoat formulators in Paris and Lyon procure benzotriazole UV absorbers for automotive refinish and OEM warranty programs demanding precise 290-350 nm absorption profiles. The EU Green Deal's Circular Economy Action Plan tightens additive migration limits for recyclable plastics, pressuring reformulation toward oligomeric architectures. The Auvergne-Rhône-Alpes region concentrates specialty coatings R&D facilities qualifying next-generation stabilizer packages.
Italy
Masterbatch producers in Lombardy and Emilia-Romagna supply UV-protected films to greenhouse operators adopting multi-season replacement cycles across the Po Valley. EFSA scrutiny of organic additive migration in food-contact applications accelerates substitution toward inorganic nano-blockers in cosmetic packaging. Northern Italy's packaging corridor drives volume demand for polyolefin-compatible stabilizer systems.
Spain
Agricultural cooperatives in Almería and Valencia source extended-life greenhouse films requiring stabilizer loadings for three to five growing seasons versus annual replacement. The F-Gas Regulation's hydrofluorocarbon phase-down redirects insulation foam stabilizer demand toward hydrofluoroolefin-compatible thermal protection packages. Mediterranean horticulture clusters now expect on-site photostability testing as standard pre-sale technical service.
Netherlands
Greenhouse operators in Westland and Aalsmeer deploy UV-protected films maximizing light transmission while blocking degradation-inducing wavelengths for year-round tomato and flower cultivation. CSRD supply-chain disclosure mandates from 2026 advantage stabilizer producers with certified mass-balance and bio-attributed product lines. The Rotterdam-Antwerp petrochemical corridor enables integrated stabilizer synthesis with captive polyolefin compounding operations.
Europe UV Stabilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding specification-setting relationships with automotive OEMs and construction material producers while specialists capture margin in agricultural and textile niches. The market structure reflects capital-intensity divergence between polymer compounders with captive additive synthesis and standalone suppliers dependent on merchant resin relationships. Three archetypes dominate: integrated chemical conglomerates with Verbund-site advantages, specialty additive houses with proprietary backbone chemistries, and regional masterbatch formulators with localized technical service networks. Competitive moves concentrate on backward integration into hindered amine precursors and direct distribution partnerships disintermediating traditional regional distributors.
Within the integrated conglomerate tier, BASF SE and Evonik Industries AG exemplify firms leveraging captive synthesis capabilities and specialty methacrylate chemistry respectively to anchor premium specification positions. Clariant occupies a position bridging integrated production and controlled distribution partnerships with Mediterranean compounders. These three firms represent the archetype of producers capturing share through REACH-compliant dossier investments and technical advisory capabilities transferred directly to end-use processors.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Evonik Industries AG |
| Syensqo SA/NV |
| Songwon Industrial Co., Ltd. |
| ADEKA CORP. |
| SABO S.p.A. |
| Arkema |
| Solvay |
| Others |
Supply & Pricing Matrix
Capacity utilization at Northeast European C4 crackers determines feedstock availability for hindered amine precursors, concentrating price-setting power among integrated compounders with captive naphtha cracking while forcing standalone additive suppliers into spot market exposure. This scale asymmetry elevates price floors for specialty UV absorbers and compresses margins for commodity benzotriazole grades.
Pricing Analysis
After-sales technical service contracts and decade-long warranty backing drive lifetime value for automotive-grade stabilizer packages. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant oligomeric HALS with full dossier support from basic hindered amine grades and unregistered import alternatives. Pricing pressure stems from nano-scale cerium oxide substitution in personal care packaging where EFSA migration limits tighten. Southern European greenhouse cooperatives exhibit acute price sensitivity toward standard agricultural film grades, while German automotive compounders absorb premium positioning without volume elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate among Northern Italian packaging processors, while strategic stockpiling of hindered amine precursors characterizes German automotive compounders exposed to C4 supply volatility. Production concentrates in Germany, Belgium, and the Netherlands where Ludwigshafen, Antwerp, and Rotterdam petrochemical corridors anchor integrated stabilizer synthesis. Raw material flows draw from Northeast European naphtha crackers, Chinese benzotriazole intermediates, and Saudi methanol feedstocks. Single-source vulnerability concentrates in C4 hydrocarbon supply from a narrow corridor of crackers. Distribution runs through direct technical partnerships with Tier-1 automotive suppliers and controlled masterbatch relationships in Mediterranean horticulture belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized photochemistry expertise in radical scavenging kinetics and polymer photophysics has become the constraining asset, with formulation chemists commanding premium compensation and limiting R&D throughput at independent additive houses. This capability scarcity rotates competitive advantage toward firms with captive talent pipelines and backward-integrated synthesis infrastructure.
For Market Incumbents: Secure REACH dossier investments for novel oligomeric architectures before compliance cost escalation freezes mid-tier innovation pipelines. Anchor specification-setting relationships with Stuttgart and Turin automotive OEMs through ten-year warranty backing, while building captive hindered amine precursor capacity to neutralize C4 supply concentration risk from Northeast European crackers. For New Entrants and Emerging Players: Lead with recyclate-compatible stabilizer formulations addressing EU Packaging and Packaging Waste Regulation mandates as the most penetrable white-space segment. Target Poland and Czech Republic automotive supplier parks where localized blending capabilities and technical service presence remain underdeveloped. Establish direct distribution partnerships with Mediterranean masterbatch producers to bypass traditional channel intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty additive houses with proprietary methacrylate backbone chemistry and established ECHA registration portfolios over commodity benzotriazole producers facing price compression. Long-term viability hinges on differentiation durability through regulatory moats rather than scale economies. The signal to watch is CSRD supply-chain disclosure implementation advantaging certified mass-balance and bio-attributed product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HALS Precursors | Captive C4 supply from Ludwigshafen crackers neutralizes force majeure exposure and secures margin control. |
| REACH Dossier Investment for Oligomeric Architectures | Full toxicological registration erects barriers to commoditization and opens food-contact applications. |
| Direct Distribution Partnerships with Mediterranean Compounders | Channel compression transfers technical advisory responsibilities and captures greenhouse operator relationships. |
| Recyclate-Compatible Formulation Development | Compatibilization with post-consumer polyolefin streams addresses EU circular economy mandates. |
| CSRD-Certified Mass-Balance Product Lines | Granular supply-chain disclosure advantages position producers for 2026 reporting cycle requirements. |
Research Methodology
Desk research of ECHA registration databases, Cefic chemical industry statistics, and customs trade flow records preceded structured interviews with polymer compounding plant managers, automotive Tier-1 procurement leads, agricultural film masterbatch producers, and REACH regulatory affairs directors. Primary fieldwork captured formulation specifications, warranty requirements, and channel economics across Germany, France, Italy, Spain, and the Netherlands. Secondary validation drew from SEC filings of listed chemical conglomerates, EU F-Gas Regulation implementation reports, and greenhouse operator cooperative procurement records. Bottom-up volume estimates triangulated against top-down polymer consumption forecasts.
Variance decomposition across product chemistry, end-use application, and regional production hub dimensions shaped the analytical framework throughout the forecast period. Segmentation modeling incorporated grade tier differentiation, polymer matrix compatibility, regulatory compliance status, and channel structure intensity. CAGRs derived from weighted average of historical volume trajectories and demand elasticity coefficients by end-use segment. Industry-specific inputs included automotive OEM warranty specification timelines, agriculture film replacement cycle extensions, and construction material accelerated aging protocol adoption rates.
Forecasts assume regulatory continuity in REACH substance restrictions, EU Green Deal circular economy implementation, and F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling of substitution dynamics and demand profile redirections. Revision becomes warranted when nano-scale inorganic UV blocker cost-performance ratios cross thresholds enabling mass-market penetration or when C4 supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tire Additives Market
Additives
Polyols and Sorbitols Products Market
Additives
Feedstuff Additives Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Micronized Powder Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Sorbitan Esters Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Sodium Citrate Dihydrate Market
Additives
North America Potassium Nitrate Market
Additives
Viscosity Reducing Agents Market
Additives
Plastics Modifiers Market
Additives
Phthalate Plasticizer Market
Additives
Additives for Metalworking Fluids Market
Additives
Grinding Aids Market