
 Egypt Paints and Coatings Market | 2026-2036
Egypt Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Paints and Coatings Market Foresight
Real estate developers are redrawing procurement priorities across Egypt's paints and coatings sector, shifting volume toward large-scale residential and infrastructure contractors. Jotun leverages its marine and protective coatings heritage to anchor premium industrial segments along the Suez Canal Economic Zone. PPG Industries sustains technology leadership through waterborne platform investments targeted at Egyptian automotive OEM supply chains. National Paints Factories Co Ltd dominates local distribution networks, extending its reach into Upper Egypt through wholesale channel control.
Paints and coatings comprise liquid, powder, or UV-curable film-forming compositions applied to substrates for protection, decoration, or functional modification, typically specified by solids content, VOC levels, and dry-film thickness measured in microns. Architectural coatings lead absolute volume as Egypt's construction permit issuances accelerate across desert satellite cities. Waterborne technology captures the fastest expansion trajectory, driven by contractor preferences for lower odor and faster recoat intervals in high-rise residential applications. Powder coatings occupy a specialized niche serving Egyptian appliance and furniture manufacturers seeking zero-VOC compliance with export-market specifications.
Egypt's General Authority for Construction and Housing regulates building material quality through mandatory product registration, while the Egyptian Organization for Standardization and Quality enforces VOC thresholds aligned with evolving environmental codes. The Ministry of Environment's industrial emissions framework is tightening solventborne formulation allowances, redirecting manufacturer R&D budgets toward compliant waterborne and UV-cured platforms. Stakeholders must monitor regulatory harmonization timelines between domestic standards and Gulf Cooperation Council export requirements to anticipate formulation investment cycles.

Market Dynamics
Egypt's paints and coatings sector is restructuring around waterborne technology migration, as Egyptian Organization for Standardization and Quality enforcement of VOC thresholds forces solventborne formulation phaseouts across Greater Cairo manufacturing zones.
Growth Catalysts
- Affordable Housing Programs:Government-backed residential construction initiatives in New Administrative City and Alexandria are accelerating contractor-grade coating procurement volumes through state-linked developers.
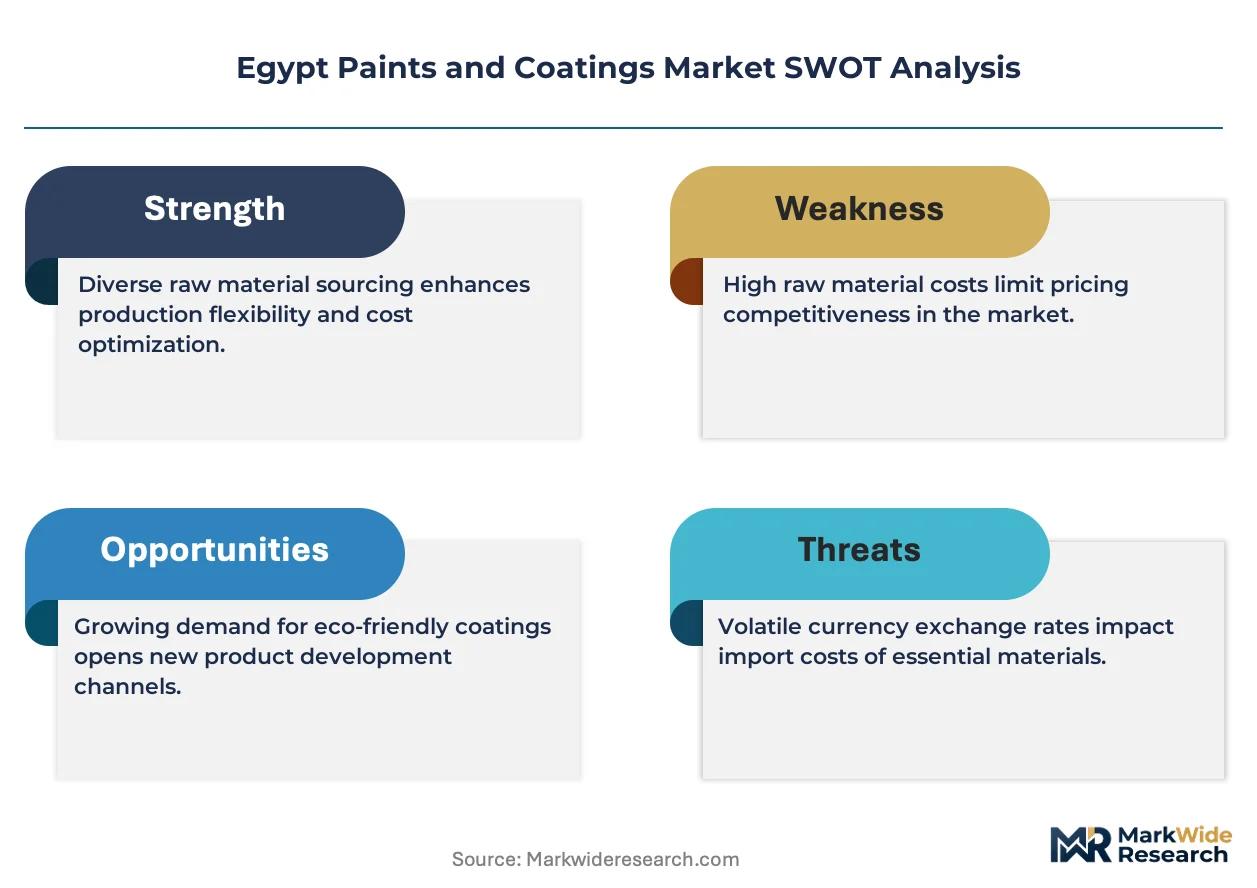
- REACH Alignment:Egyptian manufacturers adapting formulations to Gulf Cooperation Council export specifications are capturing premium positioning in Saudi and UAE distribution channels.
- UV-Cured Platforms:Furniture and appliance exporters in Damietta and 10th of Ramadan industrial zones are adopting zero-VOC powder coatings to meet EU market entry requirements.
Market Restraints
- Titanium Dioxide Concentration:Egyptian formulators remain dependent on Chinese and Ukrainian TiO2 feedstock, exposing margins to Black Sea shipping disruptions and currency volatility.
- Solventborne Stranded Assets:Ministry of Environment industrial emissions frameworks are rendering legacy high-VOC production lines economically unviable before depreciation cycles complete.
- Epoxy Resin Import Dependency:Protective coatings segment faces structural input cost pressure from concentrated Middle Eastern petrochemical supplier bases.
Strategic Opportunities
- Upper Egypt Distribution Gap:Wholesale channel penetration in Sohag, Qena, and Aswan governorates remains underdeveloped relative to Nile Delta saturation, creating first-mover consolidation potential.
- Automotive OEM Integration:Suez Canal Economic Zone assembly plant expansions are generating specification opportunities for locally blended primers and basecoats previously imported from Europe.
- BIS Certification Arbitrage:Egyptian producers achieving Bureau of Indian Standards alignment can access Indian subcontinent export markets with preferential duty treatment under COMESA arrangements.
Industry Challenges
- Formulation Chemist Scarcity:Egyptian universities produce insufficient polymer chemistry specialists trained in waterborne resin synthesis, forcing manufacturers to recruit from expatriate talent pools.
- Product Registration Timelines:General Authority for Construction and Housing mandatory registration protocols create six-to-nine month launch delays for reformulated SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Paints and Coatings Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural, Industrial, Protective, Decorative Application: Construction, Automotive, Marine, Furniture End User: Contractors, OEMs, Retailers, Wholesalers Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured |
| Companies Covered | BASF, PPG Industries, MIDO Coatings, National Paints Factories Co Ltd, KAPCI Coatings, Jotun, Asian Paints, PACHIN, Akzo Nobel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Paints and Coatings Market Shifts & Advancements
Technology substitution and regulatory harmonization are compressing traditional formulation cycles while opening specification pathways for compliant waterborne and UV-cured alternatives across Egyptian industrial zones.
Hybrid waterborne-alkyd technology is fragmenting the mid-tier architectural segment by enabling high-gloss finishes with solventborne performance characteristics at reduced VOC levels. Contractors in high-rise residential towers across 6th of October City and Sheikh Zayed are specifying these systems for faster recoat intervals. The technology is fragmenting procurement patterns by allowing smaller regional blenders to compete with multinational incumbents on specification-grade projects.
Egyptian Organization for Standardization and Quality VOC threshold enforcement is accelerating R&D budget reallocation toward compliant platform development. Manufacturers with legacy solventborne capacity are facing accelerated obsolescence timelines as Ministry of Environment inspections intensify. The protective coatings segment serving Suez Canal infrastructure is most affected, with specification engineers now mandating waterborne epoxy alternatives for marine applications.
Developer-direct procurement models are compressing traditional distributor markups as New Administrative City megaproject consortiums negotiate volume contracts with formulation plants. Wholesale channels serving smaller contractors in Alexandria and Mansoura are losing share to manufacturer-owned specification teams. This disintermediation is most visible in the premium architectural segment, where branded specification drives project-level purchasing authority consolidation.
Egypt Paints and Coatings Market Segmentation
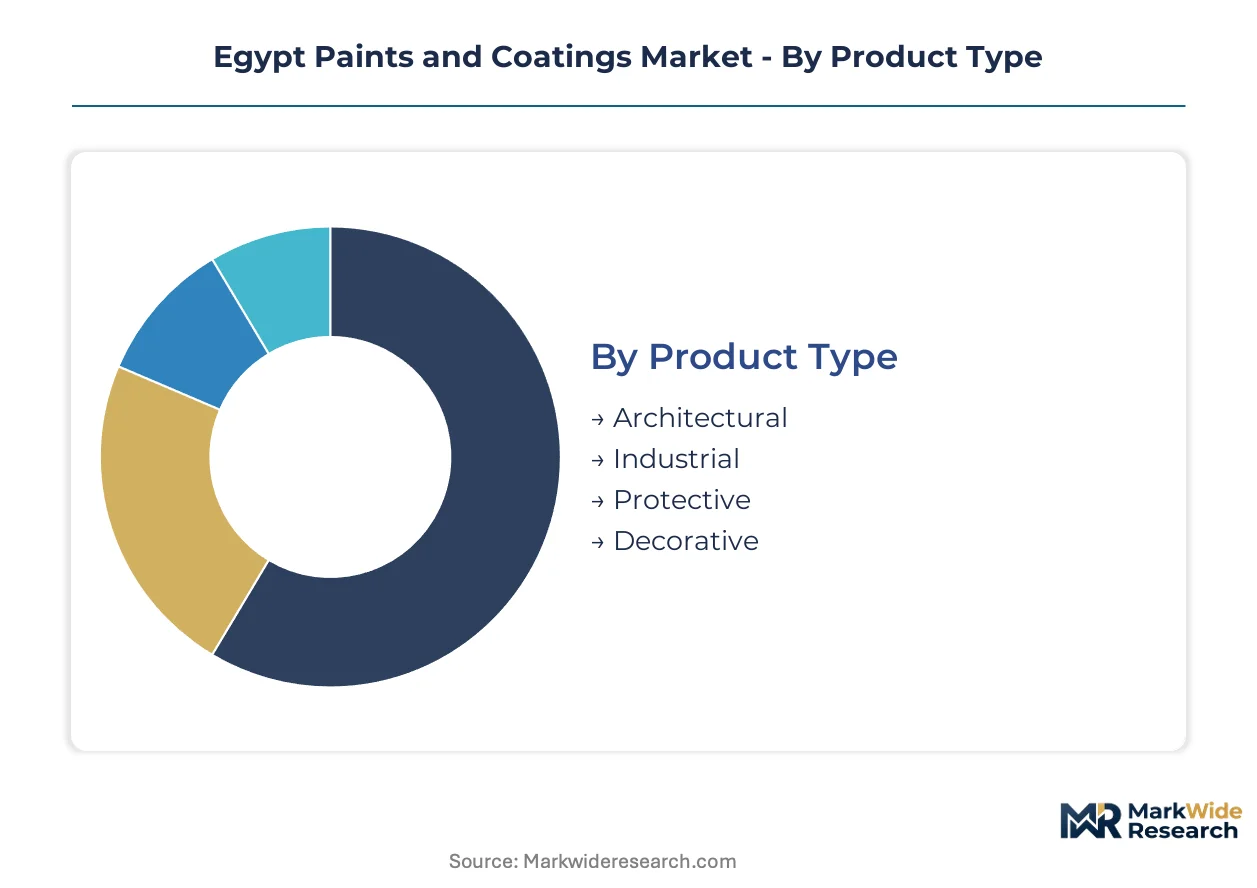
Egypt's paints and coatings segmentation reveals how regulatory pressure and construction economics are reallocating volume across formulation types and customer channels. Substitution dynamics between waterborne and solventborne platforms are restructuring competitive positions within each category.
Product Type:
Waterborne migration is forcing the fastest reformulation cycles in segments with the highest residential exposure, while industrial coatings face longer asset turnover timelines.
- Architectural:Acrylic and alkyd emulsions formulated for exterior durability and interior washability. Demand concentrates in New Administrative City and 6th of October City residential towers where contractor specifications favor low-odor application. Egyptian Organization for Standardization and Quality VOC thresholds are accelerating solventborne displacement in this segment.
- Industrial:High-performance coatings specified for manufacturing equipment and factory infrastructure across 10th of Ramadan and Sadat City industrial zones. Automotive OEM procurement from Suez Canal Economic Zone assembly plants is driving specification-grade volume toward locally blended primers.
- Protective:Epoxy and polyurethane systems engineered for corrosion resistance in marine and infrastructure applications. Suez Canal Authority maintenance schedules generate recurring demand for marine-grade protective films.
- Decorative:Premium aesthetic finishes including textured, metallic, and faux-effect coatings for high-end residential and commercial interiors. Alexandria and Cairo retail channels move significant volume through designer-specified projects.
Architectural coatings anchor the volume base while waterborne technology gains share at the steepest rate across all product categories.
Application:
Construction permit issuance patterns are concentrating procurement volumes in segments tied to state-backed residential programs, while export-oriented manufacturing drives specialized coating demand.
- Construction:Interior and exterior wall coatings, waterproofing systems, and concrete protection for residential, commercial, and infrastructure projects. Greater Cairo and Alexandria account for the dominant share of construction coating consumption.
- Automotive:Basecoats, clearcoats, and primers specified for passenger vehicle and commercial truck assembly. Suez Canal Economic Zone expansion is localizing procurement previously directed to European suppliers.
- Marine:Antifouling, tank lining, and hull protection systems for vessels transiting Suez Canal and operating from Egyptian ports. Jotun's Suez facility captures premium specification share in this application.
- Furniture:Wood finishes and laminating coatings for Damietta furniture cluster exporters targeting EU compliance requirements. UV-cured platforms are displacing conventional solventborne systems in this application.
Construction absorbs the largest application volume while furniture coatings climb the fastest on export compliance drivers.
End User:
Developer-direct procurement is compressing traditional channel margins and reallocating volume toward specification teams with project-level authority.
- Contractors:Volume purchasers executing government affordable housing and private residential developments. New Administrative City megaproject consortiums negotiate direct formulation plant contracts, bypassing wholesale intermediaries.
- OEMs:Original equipment manufacturers in automotive, appliance, and industrial machinery sectors with specification-grade requirements. Suez Canal Economic Zone automotive plants are qualifying local primer and basecoat suppliers.
- Retailers:Hardware stores and paint shops serving DIY consumers and small-scale contractors in urban and peri-urban markets. Cairo and Alexandria retail density contrasts with Upper Egypt distribution gaps.
- Wholesalers:Regional distributors aggregating volume for secondary markets in Mansoura, Tanta, and Delta governorates. Channel share is eroding as manufacturer specification teams capture project-direct accounts.
Contractors command the dominant procurement volume while OEM direct sourcing expands most quickly on localization mandates.
Technology:
Regulatory enforcement is rendering legacy solventborne capacity economically unviable before full depreciation, forcing accelerated platform transitions.
- Waterborne:Acrylic, polyurethane, and epoxy emulsions with VOC content below Egyptian Organization for Standardization and Quality thresholds. High-rise residential contractors in Sheikh Zayed and 6th of October City specify these systems for faster recoat intervals and lower odor.
- Solventborne:Traditional alkyd and nitrocellulose formulations facing phaseout pressure from Ministry of Environment emissions frameworks. Stranded asset risk concentrates in Greater Cairo manufacturing zones with legacy production lines.
- Powder Coatings:Thermosetting polymer films applied electrostatically to metal substrates with zero VOC emissions. Damietta furniture and appliance exporters adopt these systems for EU market access.
- UV-Cured:Photoinitiator-activated coatings curing instantly under ultraviolet exposure for high-throughput manufacturing. 10th of Ramadan industrial zone wood coating operations are piloting UV platforms for line speed advantages.
Solventborne technology retains residual volume share while waterborne platforms gain specification ground at the fastest clip on regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating formulation capacity clusters along the Nile Delta corridor, with Greater Cairo and Alexandria absorbing the dominant procurement volumes from state-backed construction programs. Geographic demand patterns track government housing initiatives and Suez Canal industrial expansion zones.
Greater Cairo
New Administrative City megaproject consortiums are negotiating direct volume contracts with formulation plants, bypassing traditional wholesale intermediaries. The Egyptian Organization for Standardization and Quality enforces VOC thresholds that accelerate solventborne displacement across 6th of October City and Sheikh Zayed high-rise residential towers. Contractor-grade coating procurement concentrates in satellite desert cities where construction permit issuances are accelerating.
Alexandria
Marine-grade protective coatings demand tracks Suez Canal Authority maintenance schedules and port infrastructure renewal programs. Jotun's Suez facility anchors premium specification share for vessels transiting the canal. The Ministry of Environment's industrial emissions framework is tightening solventborne allowances in Alexandria manufacturing zones, redirecting R&D budgets toward compliant waterborne platforms.
Suez Canal Economic Zone
Automotive OEM assembly plant expansions are generating specification opportunities for locally blended primers and basecoats previously imported from European suppliers. REACH alignment efforts by Egyptian manufacturers target Gulf Cooperation Council export channels. Industrial coatings procurement localizes as Suez Canal Economic Zone qualification requirements favor domestic formulation plants.
Damietta
Furniture cluster exporters are adopting UV-cured and powder coating platforms to meet EU market entry requirements for zero-VOC compliance. The General Authority for Construction and Housing mandates product registration protocols that create six-to-nine month launch delays for reformulated SKUs. Wood coating operations in Damietta industrial zones pilot UV platforms for line speed advantages.
Upper Egypt
Wholesale channel penetration in Sohag, Qena, and Aswan governorates remains underdeveloped relative to Nile Delta saturation, creating first-mover consolidation potential. National Paints Factories Co Ltd extends distribution reach through regional wholesale networks. Affordable housing program spillover into Upper Egypt governorates is accelerating contractor-grade coating demand outside traditional demand centers.
Egypt Paints and Coatings Market Competitive Landscape
Concentration sits with multinational chemical conglomerates and established regional specialists competing across formulation technology tiers. The market structure exhibits tiered competition between premium specification-grade suppliers and volume-oriented local blenders. Three archetypes dominate: global coatings majors with technology leadership positions, regional specialists leveraging distribution control, and national champions optimizing for state procurement channels. Capacity expansion and portfolio diversification toward waterborne platforms represent the dominant competitive moves as regulatory compliance timelines compress.
Among global coatings majors, BASF, PPG Industries, and Akzo Nobel occupy positions exemplifying technology-driven archetypes focused on specification-grade industrial and automotive segments. National Paints Factories Co Ltd represents the regional distribution control archetype, while Jotun anchors marine and protective coatings specialization along Suez Canal infrastructure corridors.
| Leading Market Players |
|---|
| BASF |
| PPG Industries |
| MIDO Coatings |
| National Paints Factories Co Ltd |
| KAPCI Coatings |
| Jotun |
| Asian Paints |
| PACHIN |
| Akzo Nobel |
| Others |
Supply & Pricing Matrix
Egyptian Organization for Standardization and Quality VOC threshold enforcement gates both supplier qualification and price tier differentiation, forcing manufacturers to absorb compliance costs or surrender premium positioning to certified competitors. This regulatory filter simultaneously constrains raw material sourcing options and stratifies pricing power across compliant versus legacy formulation portfolios.
Pricing Analysis
Egyptian Organization for Standardization and Quality VOC thresholds dictate the pricing tier structure across architectural and industrial coating segments. Three-tier pricing structure across premium certified, standard compliant, and economy solventborne levels separates specification-grade projects from contractor-grade volume and residual legacy demand. Cost compression in economy tiers is intensifying because stranded solventborne capacity forces distressed liquidation before depreciation cycles complete. Contractor segments exhibit highest price sensitivity as developer-direct procurement eliminates distributor markups, while marine protective coatings maintain lowest sensitivity due to Suez Canal Authority specification rigidity.
Supply Chain Analysis
Inventory cycles for titanium dioxide and epoxy resin feedstock extend lead times beyond domestic formulation responsiveness, compressing working capital efficiency across Greater Cairo manufacturing zones. Egyptian formulators draw from Chinese and Ukrainian TiO2 suppliers and Middle Eastern petrochemical bases for epoxy resins, creating concentrated geographic dependency. Single-source vulnerability concentrates in Black Sea shipping corridors where geopolitical disruption propagates input cost volatility. Distribution runs through National Paints Factories Co Ltd's wholesale networks in Nile Delta governorates, with manufacturer-owned specification teams increasingly disintermediating project-direct accounts in New Administrative City corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as waterborne technology migration threatens to commoditize legacy solventborne capacity before economic obsolescence. The accelerating displacement of high-VOC formulations by compliant alternatives demands immediate portfolio repositioning.
For Market Incumbents: Fortify waterborne R&D capabilities through recruitment of expatriate polymer chemists trained in resin synthesis, addressing the formulation specialist scarcity constraining Egyptian university output. Secure backward integration into acrylic emulsion supply through captive production partnerships in 10th of Ramadan industrial zones, reducing dependency on imported resin intermediates. This dual lever counters both technical talent gaps and raw material cost volatility threatening margin stability.
For New Entrants and Emerging Players: Lead with UV-cured platform specialization targeting Damietta furniture cluster exporters seeking EU market compliance, where incumbent waterborne transition lags create specification white space. Capture first-mover consolidation potential in Upper Egypt wholesale channels across Sohag, Qena, and Aswan governorates, where National Paints Factories Co Ltd distribution remains underdeveloped relative to Nile Delta saturation. Position through Bureau of Indian Standards certification arbitrage to access preferential COMESA duty treatment for Indian subcontinent export markets.
For Investors and Strategic Acquirers: Ministry of Environment industrial emissions framework enforcement reshapes the acquisition landscape by accelerating stranded asset risk in legacy solventborne capacity. Long-term viability concentrates in formulation plants with compliant waterborne platforms and established General Authority for Construction and Housing product registration portfolios. Acquisition target archetype: regional blenders with certified waterborne capacity and underexploited Upper Egypt distribution infrastructure. The signal to watch is General Authority for Construction and Housing registration timeline compression, which would advantage pre-qualified asset bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Platform Transition | Ministry of Environment compliance mandates render solventborne capacity economically unviable before depreciation completion. |
| Upper Egypt Distribution Expansion | Sohag, Qena, and Aswan governorates offer first-mover consolidation potential against Nile Delta saturation. |
| BIS Certification Investment | Bureau of Indian Standards alignment unlocks preferential COMESA duty access to Indian subcontinent export markets. |
| Automotive OEM Qualification | Suez Canal Economic Zone assembly plant localization mandates create specification opportunities for domestic primer and basecoat suppliers. |
| UV-Cured Technology Adoption | Damietta furniture exporters require zero-VOC compliance for EU market entry, displacing conventional solventborne systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating formulation plant managers, procurement leads at New Administrative City developers, wholesale channel partners in Alexandria and Mansoura, and technical R&D directors overseeing waterborne transition programs. Secondary validation drew from Egyptian Organization for Standardization and Quality regulatory filings, General Authority for Construction and Housing product registration databases, Ministry of Environment emissions framework documentation, and customs trade data tracking TiO2 and epoxy resin import flows. Bottom-up volume estimates from construction permit issuance patterns and industrial coating consumption were triangulated against top-down macroeconomic construction sector indicators.
Across the analysis window, value projections were derived from segmented modeling across product type, application, end user, and technology platform dimensions, with additional industry-specific segmentation by regulatory compliance tier and geographic demand cluster. CAGRs were computed from fitted growth curves incorporating construction sector output trajectories, VOC threshold enforcement timelines, and export market access conditions. Key forecast inputs included New Administrative City megaproject procurement schedules, Suez Canal Economic Zone automotive plant qualification timelines, and Damietta furniture cluster export volume assumptions.
Forecasts assume regulatory continuity in Egyptian Organization for Standardization and Quality VOC enforcement and Ministry of Environment industrial emissions frameworks; material policy shifts would require re-modeling of technology substitution trajectories and stranded asset risk assessments. Specific revision triggers encompass Black Sea shipping corridor disruption severity, General Authority for Construction and Housing registration timeline compression, and Gulf Cooperation Council export specification harmonization acceleration. Revision becomes warranted when titanium dioxide feedstock cost volatility crosses thresholds that force formulation economics restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market