
 South America Paints and Coatings Additives Market | 2026-2036
South America Paints and Coatings Additives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Paints and Coatings Additives Market Analytics
Brazilian specialty chemical producers is realigning capacity toward low-VOC additive lines. BASF SE leverages its integrated surfactant network to supply emulsifiers for waterborne architectural coatings. Dow Inc anchors regional dispersant production through its local manufacturing footprint. Evonik Industries AG differentiates via silane-modified additives targeting automotive clearcoat durability.
Paints and coatings additives comprise functional chemicals—dispersants, thickeners, emulsifiers, and surfactants—dosed at 0.1% to 5.0% weight to control viscosity, pigment stability, film formation, and substrate wetting. Their primary purpose is to enable formulation performance targets while meeting application-specific constraints such as pot life, cure speed, and environmental compliance. Architectural applications dominate volume demand as residential and commercial construction drives decorative coating consumption across Brazilian and Colombian urban corridors. Automotive OEM coatings represent the fastest-expanding segment as assembly plants in Argentina and Brazil adopt higher-solids and waterborne basecoat systems requiring advanced dispersant and rheology packages. Marine applications remain a niche but carry above-average margins due to biocide-free antifouling additive requirements under tightening harbor discharge rules.
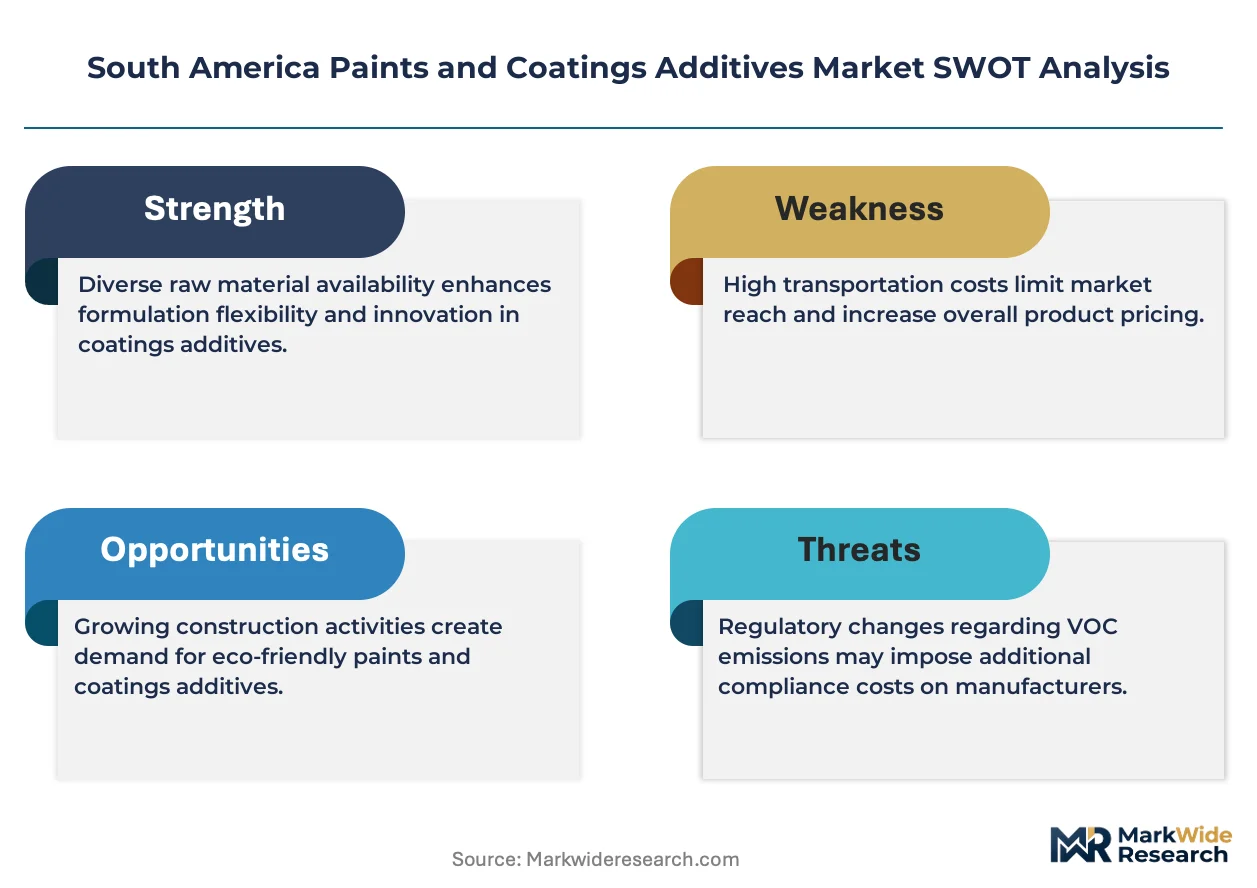
CONAMA Resolution 491 and Argentina's Secretariat of Environment and Sustainable Development enforce VOC content ceilings that directly shape additive selection and formulation architecture. Brazil's ANVISA and Argentina's national chemical regulator scrutinize biocide-containing additives under evolving hazard classification frameworks, extending registration timelines and favoring suppliers with established regulatory dossiers. Stakeholders must monitor pending Mercosur harmonization of chemical inventory notification rules, as unified compliance requirements would reshape competitive access across the customs union.
Market Dynamics
Brazil's CONAMA Resolution 491 is forcing reformulation across architectural and automotive coating segments, redirecting additive procurement toward low-VOC dispersants and rheology modifiers as manufacturers scramble to meet tightening air quality ceilings before enforcement deadlines.
Growth Catalysts
- Automotive OEM waterborne transition:Assembly plants in São Paulo and Córdoba are converting basecoat lines to higher-solids waterborne systems, creating sustained pull for advanced dispersant packages and silane-modified durability additives.
- CONAMA 491 compliance deadlines:Brazil's federal environmental council has set progressive VOC reduction targets that compel coating manufacturers to reformulate with compliant emulsifiers and thickeners, expanding addressable demand for regulatory-grade additives.
- Residential construction clustering:Urban corridor expansion across São Paulo state, Medellín, and Buenos Aires metropolitan zones is concentrating decorative coating consumption, driving volume offtake for architectural-grade rheology modifiers.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and emulsifier production depends on ethylene oxide and propylene oxide derivatives, exposing regional formulators to import price swings when naphtha crackers in the US Gulf Coast experience supply interruptions.
- Specialty chemical import concentration:High-performance dispersants and silane additives flow predominantly through Argentine and Brazilian ports from European and North American manufacturing hubs, creating single-point vulnerability to customs delays and currency mismatch.
- Biocide registration friction:Brazil's ANVISA and Argentina's Secretariat of Environment are extending hazard classification review timelines for microbiocide-containing additives, compressing product launch windows and elevating compliance costs for in-can preservation systems.
Strategic Opportunities
- Colombian Andean corridor penetration:Bogotá and Medellín construction markets remain underserved by specialty additive suppliers, offering first-mover positioning for emulsifier producers establishing local technical service presence.
- Mercosur chemical inventory harmonization:Pending unified notification rules across the customs union would streamline cross-border additive registration, reducing duplicate dossier costs and enabling consolidated supply chain architecture.
- Marine biocide-free antifouling:Tightening harbor discharge regulations in Brazilian port authorities are creating niche demand for silicone-hybrid and fluoropolymer surface modification additives that eliminate copper-based biocide loadings.
Industry Challenges
- Formulation chemist scarcity:Technical universities in Brazil and Argentina graduate insufficient specialists trained in waterborne system rheology, forcing additive suppliers to absorb internal training costs or import talent from European parent operations.
- Legacy solventborne line stranded assets:Coatings manufacturers face write-down pressure on high-VOC production equipment as reformulation accelerates, complicating capital allocation between compliance upgrades and additive inventory expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Paints and Coatings Additives Market |
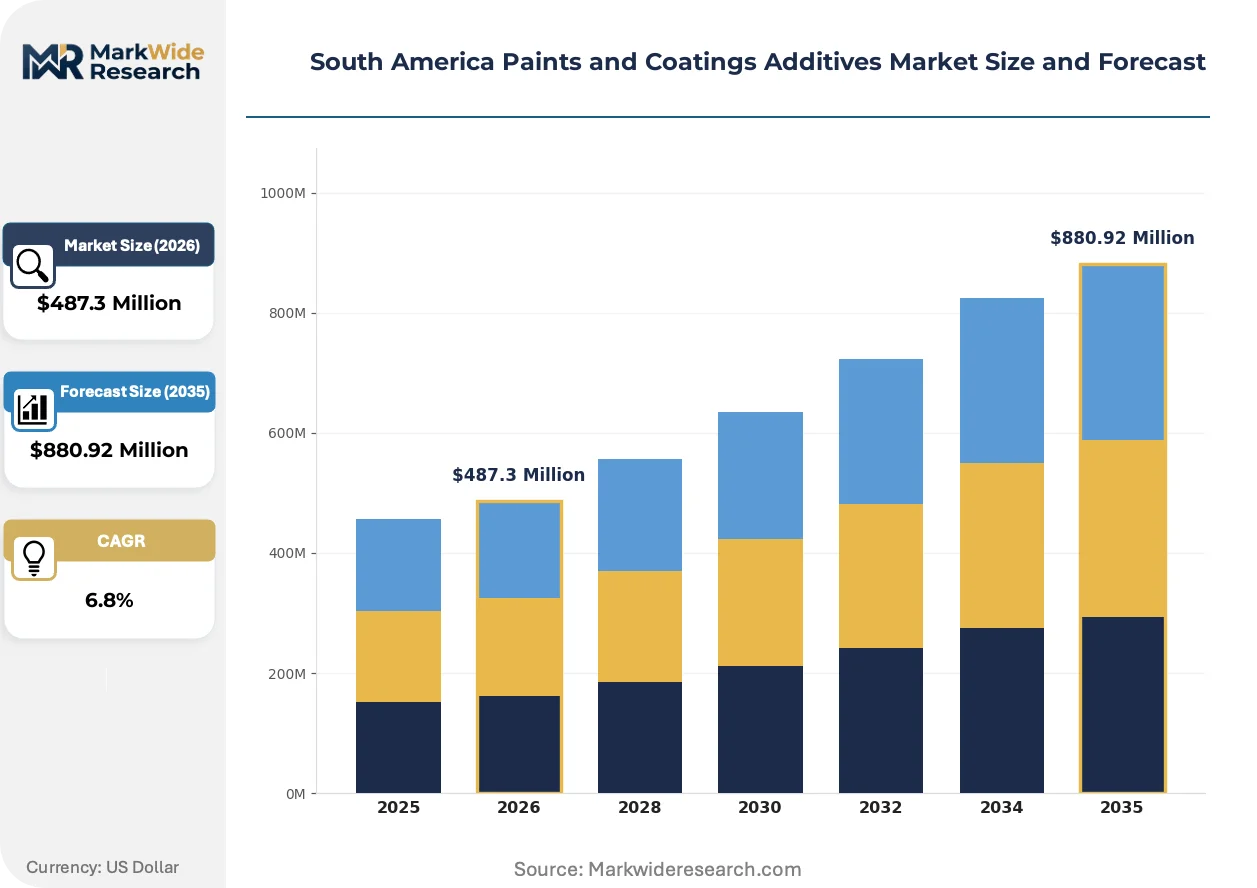
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
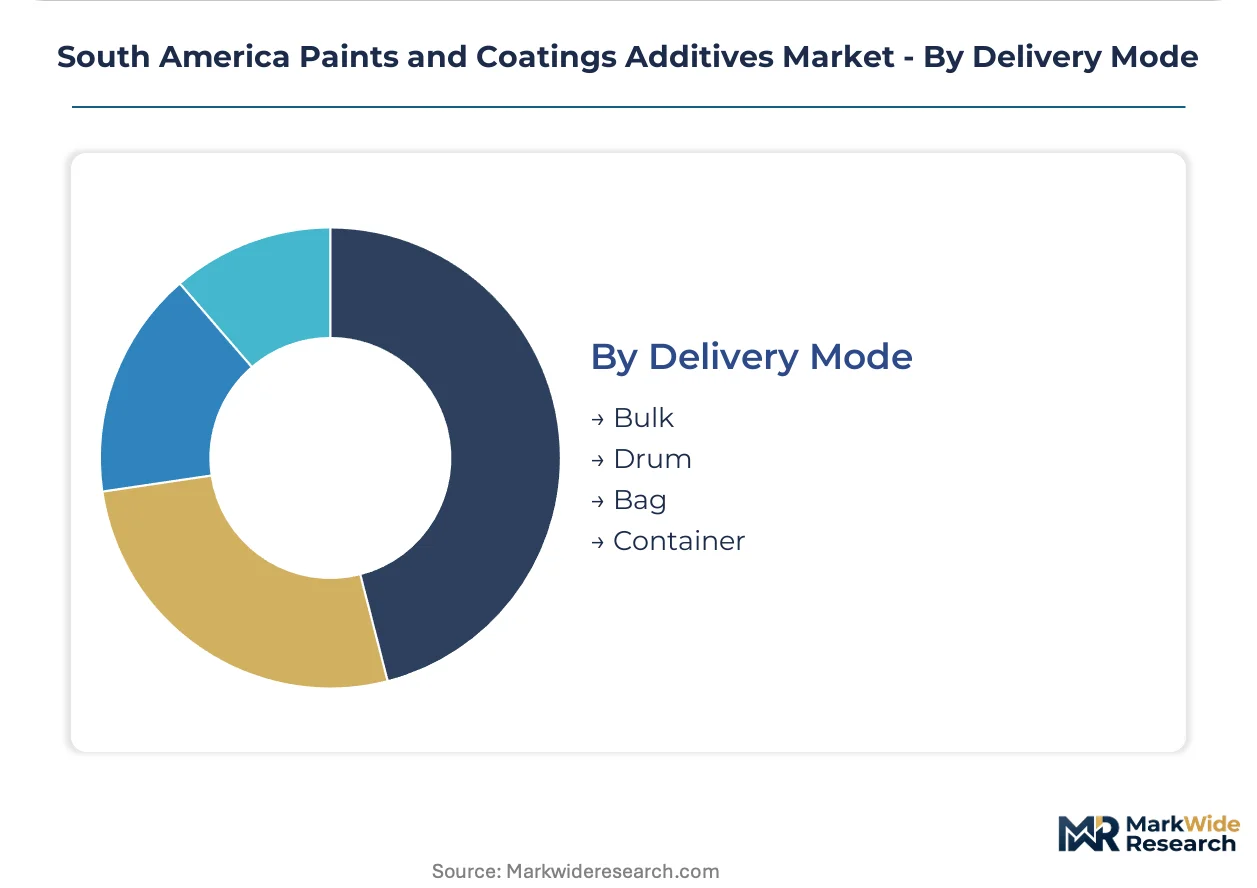
| Segmentation | Product Type: Emulsifiers, Thickeners, Dispersants, Surfactants Application: Architectural, Industrial, Automotive, Marine End User: Construction, Manufacturing, Automotive OEMs, Decorative Delivery Mode: Bulk, Drum, Bag, Container |
| Companies Covered | Arkema SA, BASF SE, Dow Inc, Evonik Industries AG, BYK-Chemie GmbH, Elementis PLC, The Lubrizol Corp, Ashland Inc, Eastman Chemical Co, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Paints and Coatings Additives Market Evolving Landscape
Waterborne formulation chemistry is absorbing the lion's share of R&D investment across South American coating operations, with regulatory pressure and OEM specification changes converging to compress the viable window for solventborne additive portfolios.
Silane-modified polyurethane dispersions are absorbing market share in automotive clearcoat applications as OEMs in Gravataí and São Bernardo do Campo specify enhanced scratch resistance and UV durability. Tier-1 coating suppliers are qualifying these additives at accelerated pace to meet assembly line warranty requirements. The technology is absorbing margins previously captured by conventional acrylic modifiers, compressing price realization for standard dispersant grades.
Argentina's Secretariat of Environment and Sustainable Development is enforcing VOC content ceilings that mirror Brazilian CONAMA frameworks, creating synchronized compliance pressure across the Mercosur bloc. Coating formulators must now architect dual-approval additive packages that satisfy both regulatory regimes simultaneously. Automotive refinish operations in Buenos Aires province are most affected, accelerating qualification of low-HAP thinner systems.
Specification consolidation among Brazilian residential developers is concentrating procurement authority at the general contractor level, displacing traditional distributor-mediated purchasing for architectural coating additives. Large São Paulo-based construction groups now negotiate directly with BASF and Dow for project-specific emulsifier and thickener volumes. This channel compression is most visible in high-rise residential towers across the ABC Paulista industrial belt, where standardized waterborne specifications dominate.
South America Paints and Coatings Additives Market Segmentation
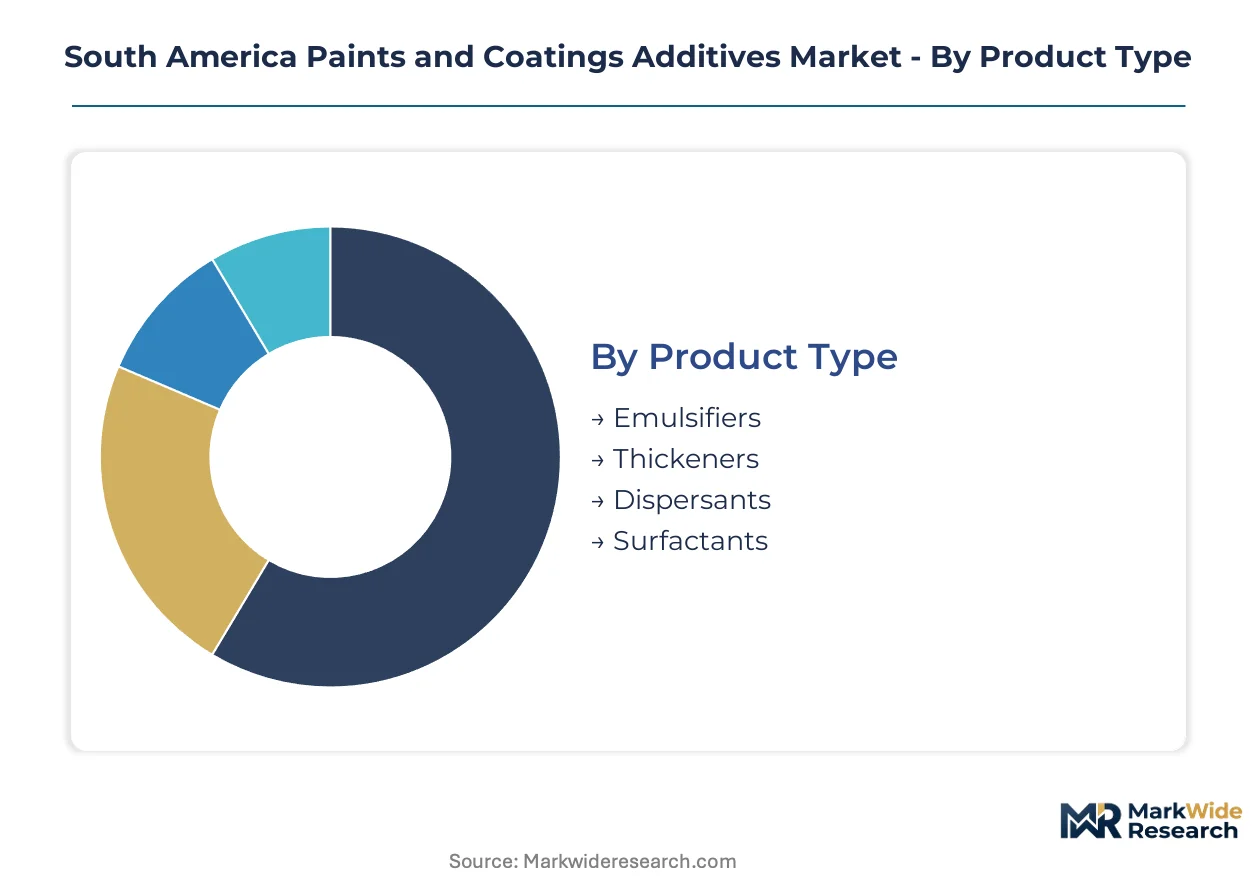
Additive selection across South American coating operations hinges on formulation chemistry, regulatory compliance, and end-use performance specifications. Each segmentation dimension reveals distinct procurement patterns and margin structures that suppliers must navigate to capture value.
Product Type:
Customization intensity varies sharply across this category, with commodity-grade surfactants competing on scale while silane-modified specialties command specification premiums.
- Dispersants:Polymeric and inorganic dispersants stabilize pigment particles in waterborne and solventborne matrices. Demand concentrates in São Paulo automotive OEM clearcoat operations, where higher-solids waterborne basecoat conversions require advanced steric stabilization packages to prevent flocculation under compressed cure cycles.
- Emulsifiers:Non-ionic and anionic surfactant systems enable latex particle formation in architectural coatings. Brazilian construction clusters in the ABC Paulista belt are absorbing volumes as residential developers consolidate procurement and standardize waterborne interior specifications.
- Thickeners:Cellulosic and associative rheology modifiers control sag resistance and brush feel. Argentine architectural formulators favor cost-optimized HEC grades for decorative masonry coatings.
- Surfactants:Wetting agents and defoamers manage substrate penetration and foam control. Marine coating operations in Brazilian port zones specify silicone-free variants to satisfy harbor discharge protocols.
Leading the category by volume: Emulsifiers. Growing fastest: Dispersants.
Application:
Margin profiles diverge by technical complexity, with automotive and marine applications requiring qualification-intensive additive packages.
- Architectural:Decorative and protective coatings for residential and commercial structures. Brazilian high-rise residential towers in Medellín and Buenos Aires corridors are standardizing waterborne acrylic systems, pulling compatible emulsifier and thickener volumes through general contractor direct procurement channels.
- Automotive:OEM and refinish coatings demanding scratch resistance and weatherability. Assembly plants in Gravataí and Córdoba are qualifying silane-modified polyurethane dispersions for clearcoat durability, displacing conventional acrylic modifiers.
- Industrial:Protective coatings for machinery, infrastructure, and metal substrates. Argentine manufacturing facilities prioritize cost-efficient dispersant packages for maintenance coating reformulation.
- Marine:Antifouling and protective systems for vessels and offshore structures. Brazilian port authorities are enforcing biocide-free specifications, creating niche pull for silicone-hybrid surface modification additives.
Dominating volume: Architectural. Steepest expansion trajectory: Automotive.
End User:
Procurement authority is shifting from distributor networks to direct manufacturer engagement, reshaping additive sales coverage models.
- Construction:General contractors and residential developers specifying coating systems for new build and renovation. São Paulo-based construction groups now negotiate emulsifier and thickener volumes directly with multinational suppliers, compressing traditional distribution margins.
- Automotive OEMs:Vehicle assembly plants and Tier-1 coating suppliers. Brazilian and Argentine OEM operations are driving dispersant and durability additive specifications through waterborne basecoat line conversions.
- Manufacturing:Industrial facilities applying protective coatings to equipment and infrastructure. Colombian manufacturing clusters represent underserved demand for technical service-intensive additive packages.
- Decorative:Professional painters and DIY consumers purchasing retail architectural coatings. Price-sensitive segments favor standard-grade thickeners and surfactants through retail channels.
Construction commands volume leadership. Automotive OEMs are gaining share fastest.
Delivery Mode:
Logistics economics and inventory velocity determine packaging selection, with bulk infrastructure concentrated near major formulation clusters.
- Bulk:Tanker and silo delivery for high-volume emulsifier and surfactant offtake. São Paulo state coating manufacturing corridors anchor regional bulk terminal infrastructure.
- Drum:Standard 200-liter packaging for mid-volume dispersant and specialty additive shipments. Argentine formulators rely on drum logistics given limited bulk handling capabilities.
- Bag:Powdered thickener and solid additive delivery for dry-mix coating operations. Colombian construction markets favor bagged rheology modifiers for on-site blending flexibility.
- Container:ISO tank and flexitank options for import-dependent high-performance additives. European and North American silane additive suppliers utilize containerized delivery to Brazilian and Argentine ports.
Bulk leads volume throughput. Containerized delivery is expanding most quickly for specialty imports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide and propylene oxide derivatives from the US Gulf Coast feedstock corridor anchor regional additive supply chains, with Brazilian port infrastructure absorbing the majority of import volumes before redistribution across Mercosur manufacturing clusters.
Brazil
São Paulo state's ABC Paulista industrial belt concentrates automotive OEM coating operations and residential construction demand. ANVISA extends hazard classification review timelines for biocide-containing additives, compressing product launch windows. BASF SE leverages its integrated surfactant network to supply emulsifiers for waterborne architectural coatings across São Paulo metropolitan construction corridors.
Argentina
Assembly plants in Córdoba and Buenos Aires province drive dispersant consumption for automotive refinish and OEM clearcoat applications. The Secretariat of Environment and Sustainable Development enforces VOC content ceilings mirroring Brazilian CONAMA frameworks. Tier-1 coating suppliers in Gravataí and Córdoba accelerate qualification of low-HAP thinner systems for assembly line warranty requirements.
Colombia
Bogotá and Medellín construction markets remain underserved by specialty additive suppliers, offering first-mover positioning for emulsifier producers. Urban corridor expansion across Medellín metropolitan zones concentrates decorative coating consumption. Colombian manufacturing clusters represent underserved demand for technical service-intensive dispersant and rheology packages.
Chile
Industrial protective coating operations in Santiago and Valparaíso port zones sustain steady dispersant offtake for infrastructure maintenance applications. Harbor discharge regulations in Chilean port authorities create niche pull for silicone-hybrid surface modification additives. Marine coating operations specify biocide-free variants to satisfy environmental protocols.
South America Paints and Coatings Additives Market Competitive Landscape
Global majors compete with regional champions across formulation technical service and regulatory compliance capabilities. The vendor base stratifies between integrated petrochemical conglomerates with captive surfactant supply and specialized additive houses focused on performance chemistry. Three archetypes dominate: multinational chemical conglomerates with regional manufacturing footprints, European specialty additive houses with technical service-led market development, and regional distributors with formulation support capabilities. Competitive positioning sharpens through direct procurement channel cultivation with large construction groups and accelerated qualification programs for automotive OEM specification compliance.
Among multinational chemical conglomerates, BASF SE and Dow Inc anchor regional supply architecture through local manufacturing presence and integrated feedstock access. Evonik Industries AG exemplifies the European specialty additive house archetype, occupying a position defined by silane-modified performance chemistry and automotive OEM technical qualification depth. These three entities represent distinct competitive vectors: scale-driven surfactant supply, dispersant manufacturing proximity, and premium durability additive specialization.
| Leading Market Players |
|---|
| Arkema SA |
| BASF SE |
| Dow Inc |
| Evonik Industries AG |
| BYK-Chemie GmbH |
| Elementis PLC |
| The Lubrizol Corp |
| Ashland Inc |
| Eastman Chemical Co |
| Others |
Value Network & Pricing Analysis
Brazilian automotive OEM procurement consolidation around São Paulo assembly plants concentrates buying power and compresses margin capture for standard-grade dispersants, while project-based contracting dominates architectural additive offtake as general contractors negotiate emulsifier and thickener volumes directly with multinational suppliers.
Pricing Analysis
Warranty and technical service bundling separates premium silane-modified additives from unbundled commodity surfactants, with automotive clearcoat applications demanding specification-locked packages that include formulation support and accelerated qualification assistance. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with CONAMA 491-compliant regulatory-grade additives commanding sustained premiums. Pricing pressure stems from ethylene oxide derivative cost volatility transmitted through US Gulf Coast naphtha cracker economics. Decorative coating distributors exhibit highest price sensitivity, while automotive OEMs prioritize performance consistency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European and North American manufacturing hubs for high-performance silane additives, creating customs delay exposure at Argentine and Brazilian ports. Geographic supply concentration centers on Germany, the United States, and domestic Brazilian surfactant operations. Raw material dependencies rest on ethylene oxide, propylene oxide derivatives, and specialty silane precursors. Tariff exposure runs through Mercosur external tariff schedules on chemical imports. Distribution runs through bulk terminal infrastructure anchored in São Paulo state coating manufacturing corridors, supplemented by drum and containerized delivery for specialty imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CONAMA Resolution 491 functions as a cost-of-compliance moat, elevating registration timelines and technical qualification barriers that favor incumbent suppliers with established regulatory dossiers and stranded capital in legacy solventborne equipment.
For Market Incumbents: Anticipate accelerated automotive OEM specification consolidation by deepening technical service presence in Córdoba and Gravataí assembly corridors, while absorbing stranded asset write-down pressure from high-VOC production equipment through selective capacity redeployment toward low-VOC emulsifier lines.
For New Entrants and Emerging Players: Silane-modified polyurethane dispersions for automotive clearcoat durability offer a technology-first wedge into specification-intensive segments underserved by regional champions, with Colombian Andean corridor construction markets representing the most penetrable white-space for emulsifier producers establishing local formulation support capabilities.
For Investors and Strategic Acquirers: The window for entry favors European specialty additive houses with automotive OEM qualification depth and established ANVISA regulatory dossiers, with long-term viability hinging on Mercosur chemical inventory harmonization implementation as the critical inflection signal for cross-border supply chain consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive surfactant supply reduces exposure to US Gulf Coast naphtha cracker volatility for São Paulo-based producers. |
| Automotive OEM Technical Qualification Program | Accelerated silane additive approval at Gravataí and Córdoba assembly plants locks in specification-driven pricing premiums. |
| Colombian Andean Corridor Market Development | First-mover emulsifier positioning in Bogotá and Medellín construction clusters captures underserved technical service demand. |
| Mercosur Regulatory Dossier Harmonization | Unified chemical inventory notification streamlines cross-border additive registration and reduces duplicate compliance costs. |
| Biocide-Free Marine Additive Portfolio Expansion | Silicone-hybrid surface modification additives address Brazilian port authority discharge regulations with above-average margin capture. |
Research Methodology
Independent corroboration across formulation chemists at Brazilian coating manufacturers, procurement leads at Argentine automotive OEMs, and technical directors at multinational additive suppliers underwrites the qualitative findings, combined with customs trade data, ANVISA registration filings, CONAMA regulatory gazettes, and SEC disclosures from listed chemical conglomerates. Bottom-up demand modeling across emulsifier, dispersant, thickener, and surfactant product categories triangulates against top-down macroeconomic construction and automotive production indicators.
Comparable-period anchoring to historical VOC regulatory phase-in timelines across European and North American markets informs elasticity assumptions across the projection horizon. Segmentation dimensions include formulation chemistry type, end-use application, regulatory compliance tier, and regional manufacturing cluster. CAGRs derive from weighted average of demand elasticity coefficients and input cost pass-through rates, with automotive OEM waterborne conversion velocity and residential construction permit flows serving as primary forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including pending Mercosur chemical inventory harmonization implementation timing, ANVISA hazard classification framework revisions, and ethylene oxide supply interruptions from US Gulf Coast weather events. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Iran Paints and Coatings Market