
 US Paints and Coatings Market | 2026-2036
US Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Paints and Coatings Market Intelligence
Buyer concentration among large-scale construction firms and property management portfolios is rebalancing procurement volumes toward specification-grade suppliers. The Sherwin-Williams Company leverages its contractor-direct distribution network to lock in multi-project supply agreements. PPG Industries, Inc. anchors industrial maintenance contracts through technical service bundling. Benjamin Moore & Co. differentiates via independent dealer channel control in high-end residential markets.
Paints and coatings constitute liquid or powder film-forming systems comprising resins, pigments, solvents, and additives that cure to protect substrates from corrosion, weathering, or chemical attack. Waterborne formulations now dominate architectural applications as VOC compliance tightens, while powder coatings capture margin pools in industrial equipment due to near-zero solvent emissions and overspray recyclability. Solventborne systems retain structural importance in marine and aerospace craft segments where extreme durability and chemical resistance outweigh regulatory penalties.
EPA NESHAP standards, OSHA workplace exposure limits, and state-level CARB SCM 2007 regulations collectively dictate permissible solvent content, application methods, and record-keeping burdens across manufacturing and field application. FDA indirect food contact coatings rules further constrain formulation chemistry for consumer goods and agricultural machinery segments. Stakeholders must monitor pending EPA risk evaluations for titanium dioxide and per- and polyfluoroalkyl substances, as reclassification would force reformulation cycles across decorative and industrial product lines.
Market Dynamics
EPA NESHAP standards are compressing solventborne formulation timelines while Sun Belt housing starts pull specification-grade volume toward waterborne systems. The regulatory-application tension is restructuring supplier-contractor relationships across residential and commercial segments.
Growth Catalysts
- EPA VOC Compliance Deadlines:NESHAP and CARB SCM 2007 regulations are mandating waterborne transitions in architectural coatings, forcing specification upgrades that favor compliant suppliers.
- Sun Belt Infrastructure Resurfacing:Texas and Florida DOT contracts for bridge deck and highway maintenance are outpacing national permit averages, concentrating industrial coating demand in the Gulf Coast corridor.
- Powder Coating Technology Maturation:Electrostatic application efficiency and overspray recyclability are displacing liquid systems in agricultural equipment and appliance manufacturing.
Market Restraints
- Titanium Dioxide Feedstock Concentration:Pigment supply vulnerability to EPA risk evaluation reclassification threatens decorative product line stability and reformulation costs.
- Solventborne Regulatory Penalties:Marine and aerospace segments face escalating compliance burdens under NESHAP that compress margins on high-performance protective systems.
- PFAS Contamination Liability:Per- and polyfluoroalkyl substances scrutiny under pending EPA evaluations threatens fluoropolymer coating segments with forced chemistry transitions.
Strategic Opportunities
- Florida Commercial Permitting Surge:Office and retail construction velocity in Miami-Dade and Orlando corridors is outpacing national averages, creating specification-grade volume white space.
- IRA Energy Efficiency Retrofits:Federal tax incentives for building envelope improvements are accelerating cool roof and reflective coating specifications in multi-family housing.
- Digital Color Matching Platforms:Contractor-direct specification tools are compressing the independent dealer channel, enabling volume lock-in through project-based palette standardization.
Industry Challenges
- Waterborne Application Training Gaps:Field crews lack humidity-control and dry-time management skills for high-performance waterborne systems, causing specification failures and callback costs.
- Multi-Jurisdictional Compliance Tracking:Contractors operating across Texas, Florida, and California must maintain parallel VOC documentation systems under divergent state implementation plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Paints and Coatings Market |
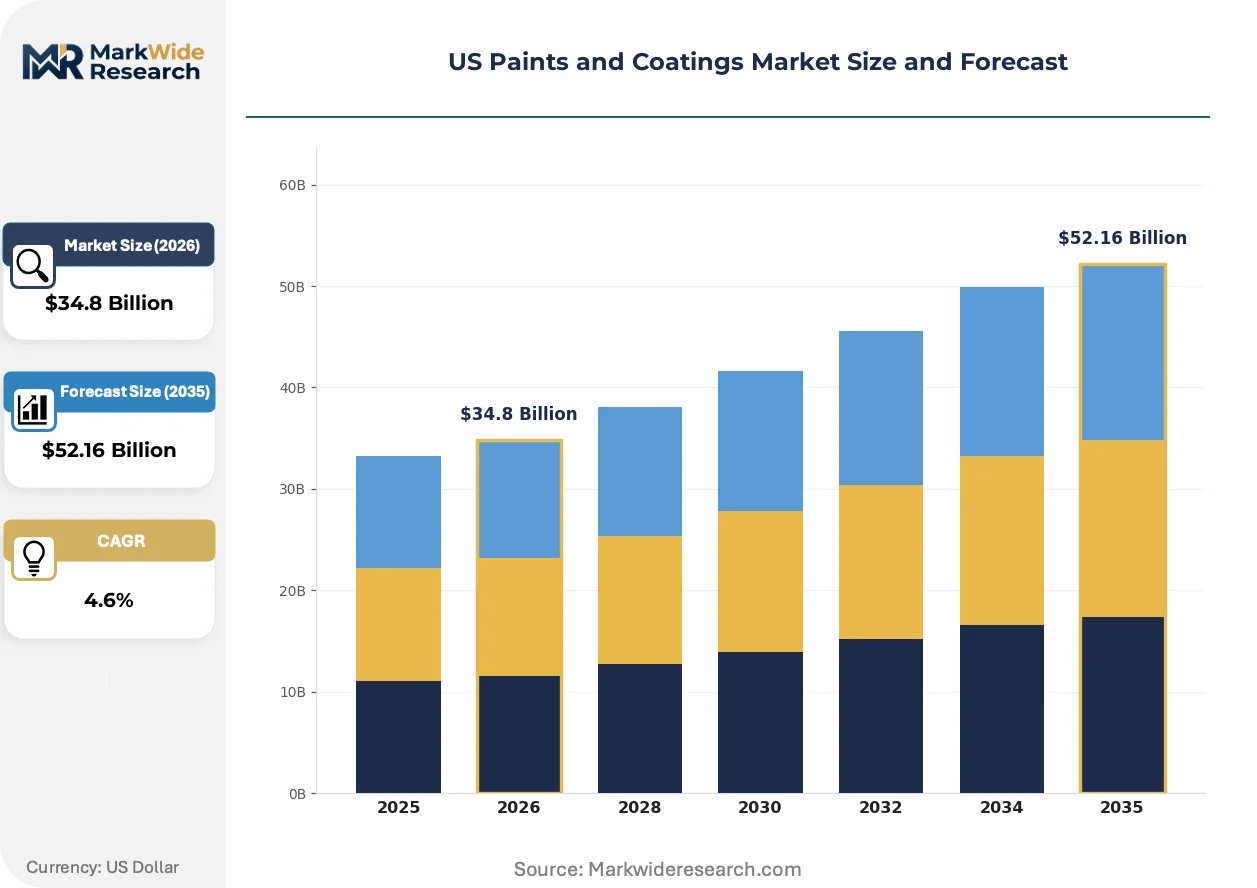
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solventborne, Powder Coatings, UV Curable, Thermal, Decorative Application: Architectural Surfaces, Industrial Equipment, Marine Vessels, Aerospace Craft, Agricultural Machinery, Consumer Goods End User Industry: Construction Firms, Manufacturing Plants, Shipbuilders, Aircraft Services, Farming Operations, Household Consumers Distribution Channel: Direct Sales, Distributors, Online Retailers, Specialty Stores, Wholesale Suppliers, Paint Contractors |
| Companies Covered | Axalta Coating Systems, LLC, Benjamin Moore & Co., The Sherwin-Williams Company, Masco Corporation, ICP Group, PPG Industries, Inc., Behr Paint Co., Diamond Vogel, RPM International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Paints and Coatings Market Strategic Shifts & Innovations
Formulation chemistry, application hardware, and procurement platforms are undergoing simultaneous transformation. Three intersecting developments are compressing traditional supplier-buyer boundaries.
Self-healing microcapsule technology is converging with automotive clearcoat specifications, enabling scratch recovery without full panel refinishing. Tier 1 suppliers are embedding this chemistry in OEM assembly line contracts. The convergence is compressing aftermarket repair volume while raising performance benchmarks for architectural metal coatings.
OSHA workplace exposure limits for isocyanates are tightening spray booth ventilation requirements across industrial maintenance operations. Coatings applicators in shipyard and railcar segments face capital-intensive booth upgrades or contractor qualification loss. Gulf Coast facilities are responding with robotic application investments to reduce human exposure liability.
Property management portfolios are consolidating specification authority into centralized procurement platforms, disintermediating traditional distributor relationships. Institutional owners with multi-state holdings are mandating national account pricing and single-source palette standardization. The shift is most visible in Sun Belt multifamily construction, where REITs leverage scale for direct manufacturer negotiations.
US Paints and Coatings Market Segmentation
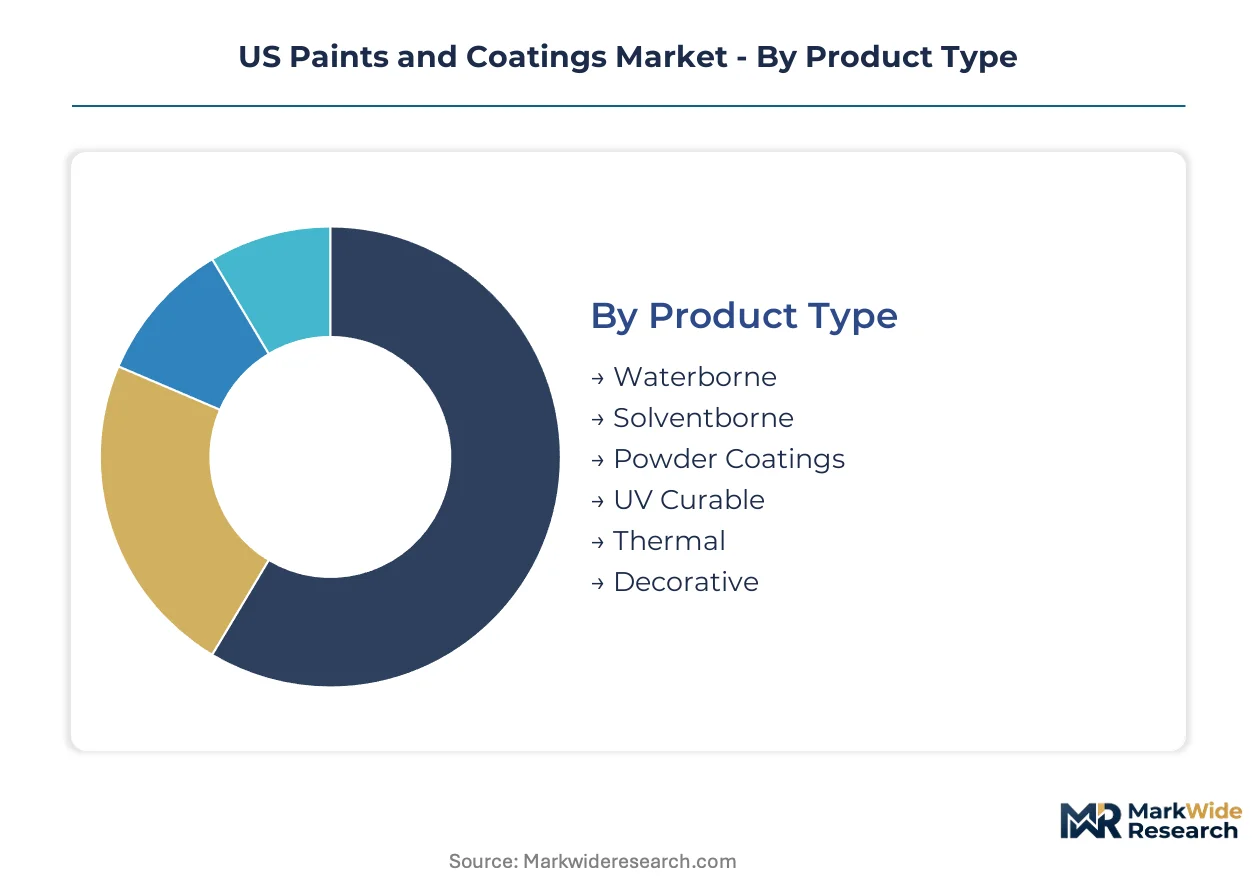
Segmentation in the US paints and coatings market reveals how regulatory pressure and application requirements split demand across incompatible chemistries. Each category exposes different margin structures, from specification-grade architectural volumes to captive industrial maintenance contracts.
Product Type:
Integration depth varies sharply across these six formulation platforms, with some functioning as standalone specification systems and others embedded within broader coating architectures.
- Waterborne:Acrylic and polyurethane dispersions serve as the dominant architectural platform under EPA NESHAP compliance timelines. Sun Belt housing starts in Texas and Florida are pulling specification-grade volume toward low-VOC systems that demand humidity-controlled application protocols.
- Solventborne:Alkyd and epoxy systems retain structural importance in marine and aerospace segments where chemical resistance and film integrity outweigh regulatory penalties. EPA exposure limits are compressing permissible application windows and accelerating booth upgrade requirements.
- Powder Coatings:Thermoset polyester and epoxy formulations capture industrial equipment applications through near-zero solvent emissions and overspray recyclability.
- UV Curable:Acrylate oligomer systems enable rapid line-speed curing for flatstock and furniture finishing.
- Thermal:Silicone and ceramic formulations protect high-temperature industrial substrates.
- Decorative:Tinted architectural coatings serve residential and commercial interior applications.
Volume placements concentrate in Waterborne; the faster expansion belongs to Powder Coatings.
Application:
Cost tier differentiation separates specification-grade commercial projects from commodity residential volumes and maintenance recoating cycles.
- Architectural Surfaces:Interior and exterior wall, trim, and roof coatings dominate total consumption. Florida DOT bridge deck contracts and Texas highway maintenance programs are concentrating industrial-grade architectural demand in the Gulf Coast corridor.
- Industrial Equipment:Factory machinery, storage tanks, and processing infrastructure require chemical-resistant film systems. OSHA isocyanate exposure limits are forcing capital-intensive spray booth upgrades across Gulf Coast maintenance facilities.
- Marine Vessels:Antifouling and protective systems for commercial shipping and offshore platforms face escalating NESHAP compliance burdens.
- Aerospace Craft:OEM and MRO coatings for commercial and military aircraft demand extreme durability specifications.
- Agricultural Machinery:Tractor and implement finishes are transitioning from liquid to powder systems.
- Consumer Goods:Appliance, furniture, and electronics coatings face FDA indirect food contact constraints.
Architectural Surfaces commands the largest share; Industrial Equipment is climbing the fastest.
End User Industry:
Customer type fragmentation splits procurement authority between centralized property management platforms and fragmented contractor networks.
- Construction Firms:Residential and commercial builders specify coating systems through multi-project supply agreements. Large-scale Sun Belt developers are consolidating procurement into national account structures that disintermediate traditional distributors.
- Manufacturing Plants:OEM and maintenance operations specify industrial coatings through technical service bundling. Automotive assembly lines are embedding self-healing microcapsule chemistry in Tier 1 supplier contracts.
- Shipbuilders:New construction and repair yards face robotic application investments to reduce isocyanate exposure liability.
- Aircraft Services:MRO facilities and OEM assembly operations demand certified applicator networks.
- Farming Operations:Equipment owners and dealers specify protective finishes for machinery fleets.
- Household Consumers:DIY purchasers drive retail volume through independent dealer and big-box channels.
Construction Firms anchor volume; Manufacturing Plants show the steepest expansion trajectory.
Distribution Channel:
Supply concentration patterns reveal which channels capture specification-grade margin versus commodity volume.
- Direct Sales:Manufacturer-to-contractor relationships lock in multi-project supply agreements with volume pricing. Property management REITs are mandating direct manufacturer negotiations for Sun Belt multifamily developments.
- Distributors:Independent and company-owned networks serve contractor and retail demand. Traditional distributor relationships face compression from centralized procurement platforms.
- Online Retailers:E-commerce platforms serve DIY and small contractor demand with digital color matching tools.
- Specialty Stores:Independent dealer networks control high-end residential specification authority.
- Wholesale Suppliers:Bulk volume channels serve large contractor and industrial accounts.
- Paint Contractors:Application professionals specify and procure coatings through project-based relationships.
Direct Sales captures specification margin; Online Retailers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Sun Belt corridor where housing starts and infrastructure contracts outpace national benchmarks. Texas and Florida DOT programs are pulling industrial coating volume southward. EPA NESHAP compliance deadlines are compressing formulation transitions unevenly across state implementation plans.
Texas
Commercial building permits in Dallas-Fort Worth and Houston are outpacing national averages, pulling specification-grade architectural volume toward waterborne systems. EPA NESHAP standards are forcing Gulf Coast applicators to upgrade spray booth ventilation for compliance. Industrial maintenance contracts cluster along the Houston Ship Channel where petrochemical infrastructure drives protective coating demand.
Florida
Office and retail construction velocity in Miami-Dade and Orlando corridors is creating specification-grade volume white space for commercial developers. State-level environmental regulations align with federal VOC deadlines but impose additional documentation burdens on contractors. Bridge deck resurfacing contracts through Florida DOT are concentrating industrial coating procurement in the Tampa-Orlando corridor.
California
CARB SCM 2007 regulations maintain stricter VOC limits than federal NESHAP standards, forcing parallel compliance systems for multi-state contractors. Cool roof and reflective coating specifications are accelerating under IRA energy efficiency retrofit incentives. Los Angeles and San Francisco Bay Area construction firms are consolidating procurement into centralized platforms that disintermediate traditional distributors.
Illinois
Manufacturing plant maintenance operations in the Chicago metropolitan area specify industrial coatings through technical service bundling relationships. OSHA workplace exposure limits for isocyanates are forcing capital-intensive spray booth upgrades across railcar and machinery segments. The I-55 industrial corridor anchors OEM coating demand for agricultural equipment and appliance manufacturing.
Ohio
Automotive assembly line specifications in the Cleveland-Akron region are embedding advanced coating chemistry in Tier 1 supplier contracts. EPA risk evaluations for titanium dioxide are threatening decorative product line stability among regional paint manufacturers. The Columbus industrial cluster is transitioning agricultural machinery finishes from liquid to powder systems.
US Paints and Coatings Market Key Industry Players
Midwestern producers anchor one tier; Northeast and Southeast specialists hold specification-grade positions in residential and commercial segments. The supplier base organizes around three strategic archetypes: national account platforms with contractor-direct distribution, independent dealer networks controlling high-end residential authority, and industrial maintenance specialists bundling technical service. Competitive moves concentrate on multi-project supply agreement lock-in and digital color matching platform deployment.
Within the national account tier, The Sherwin-Williams Company and PPG Industries, Inc. exemplify scale-driven positioning through direct contractor relationships and industrial maintenance bundling. Benjamin Moore & Co. occupies a distinct position within the independent dealer-controlled residential segment, anchoring high-end specification authority through channel exclusivity. These three entities represent the dominant competitive configurations reshaping procurement patterns across Sun Belt construction markets.
| Leading Market Players |
|---|
| Axalta Coating Systems, LLC |
| Benjamin Moore & Co. |
| The Sherwin-Williams Company |
| Masco Corporation |
| ICP Group |
| PPG Industries, Inc. |
| Behr Paint Co. |
| Diamond Vogel |
| RPM International Inc. |
| Others |
Cost & Logistics Intelligence
Large-scale Sun Belt construction firms and property management REITs are consolidating procurement into national account structures, compressing pricing power toward volume-tiered contract models that favor direct manufacturer relationships over distributor markups.
Pricing Analysis
Volume-mass architectural coatings trade on commodity spot dynamics while specification-grade systems command project-based premiums tied to EPA compliance certification and technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade waterborne systems from compliant commodity architectural volumes and non-compliant solventborne alternatives. Pricing pressure stems from titanium dioxide feedstock volatility and multi-jurisdictional compliance documentation costs. Residential DIY purchasers exhibit highest price sensitivity; commercial developers with multi-project pipelines show lowest sensitivity due to specification lock-in requirements.
Supply Chain Analysis
Freight costs from Gulf Coast petrochemical clusters to Sun Belt application sites are compressing margins on just-in-time contractor deliveries, favoring regional blending plant proximity over centralized manufacturing. Raw material supply draws from China for titanium dioxide pigment, Germany for specialty epoxy resins, and domestic Gulf Coast crackers for acrylic monomers. Single-source vulnerability concentrates in titanium dioxide feedstock where EPA risk evaluation reclassification threatens decorative product line stability. Distribution runs through contractor-direct national accounts for specification-grade volume, independent dealer networks for residential retail, and bulk wholesale channels for industrial maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around EPA compliance capabilities that force smaller formulators into acquisition or exit as multi-state documentation burdens escalate.
For Market Incumbents: Deploy technical service bundling as the primary retention mechanism against emerging industrial maintenance specialists. Lock in multi-project supply agreements with Sun Belt REITs before centralized procurement platforms fully disintermediate distributor relationships. Invest in robotic application training centers to reduce contractor callback costs from waterborne application failures. For New Entrants and Emerging Players: Specialty powder coating applicators serving agricultural equipment OEMs represent the most penetrable white space as liquid-to-powder transitions accelerate in Ohio and Illinois manufacturing clusters. Target Florida DOT bridge deck resurfacing contractors with compliant waterborne systems and humidity-control application protocols. Enter through technical partnership with regional distributors lacking EPA NESHAP compliance expertise. For Investors and Strategic Acquirers: The window for entry favors mid-cap formulators with captive titanium dioxide supply arrangements and established CARB SCM 2007 compliance systems. Long-term viability hinges on chemistry transition capabilities as PFAS scrutiny intensifies. Watch EPA risk evaluation timelines for titanium dioxide and per- and polyfluoroalkyl substances as inflection indicators forcing accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Supply | Captive pigment sourcing insulates decorative product lines from EPA reclassification-driven reformulation cycles. |
| Robotic Application Technology Deployment | Gulf Coast shipyard investments reduce OSHA isocyanate exposure liability while maintaining NESHAP-compliant throughput. |
| Digital Color Matching Platform Launch | Sherwin-Williams and PPG contractor-direct tools compress independent dealer channel control in specification-grade segments. |
| Multi-State Compliance Documentation System | Parallel VOC tracking capabilities under Texas, Florida, and California implementation plans win cross-regional contractor contracts. |
| Cool Roof Coating Formulation Expansion | IRA energy efficiency retrofit incentives accelerate reflective specification demand in California and Sun Belt multifamily housing. |
Research Approach
EPA NESHAP regulatory filings, ACC industry shipment reports, and SEC 10-K disclosures from publicly traded coating manufacturers formed the secondary backbone. Primary fieldwork incorporated structured interviews with commercial construction procurement directors, industrial maintenance facility managers, and independent dealer network owners. Technical R&D directors at formulation houses provided insight on waterborne transition timelines and self-healing microcapsule development. Bottom-up volume estimates from state-level building permit data and DOT contract awards were triangulated against top-down industry association aggregates.
Bottom-up modeling segmented demand across formulation chemistry, application surface, and end-user procurement authority. The analytical lens weighted specification-grade architectural volumes against commodity residential and industrial maintenance recoating cycles. CAGRs were derived from housing start trajectories, infrastructure contract pipelines, and regulatory compliance deadline impacts. Modeled inputs included Sun Belt permit velocity, powder coating technology adoption curves in agricultural equipment, and centralized procurement platform penetration rates among REITs.
Revisions become necessary when EPA risk evaluations for titanium dioxide or PFAS trigger reclassification, or when multi-jurisdictional compliance timelines diverge sharply across state implementation plans. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market