
 South America Sealants Market | 2026-2036
South America Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Sealants Market Insights
The South America sealants market is restructuring around a sharp divergence between premium formulations with certified durability metrics and commodity-grade products competing on bulk volume. Sika AG leverages its construction chemicals heritage to anchor specification-grade silicone systems across Brazilian commercial building projects. Henkel AG & Co. KGaA differentiates through adhesive-sealant hybrid technologies that sustain margin pools in automotive assembly applications. Dow competes on feedstock integration, controlling regional supply chains for silane-terminated polymer intermediates.
Sealants are polymeric materials formulated to fill gaps, block fluid passage, and maintain adhesion under cyclic thermal or mechanical stress, typically specified by Shore A hardness, elongation at break, and movement accommodation factors. Their primary industrial purpose centers on waterproofing building envelopes, bonding dissimilar substrates, and dampening vibration in transport equipment. Polyurethane formulations lead volume consumption in South American construction sealing due to balanced cost-performance ratios in high-movement joints. Silicone commands premium positioning in glazing and facade applications where UV resistance and temperature stability define specification criteria. Epoxy segments occupy industrial maintenance niches requiring chemical resistance in Brazilian petrochemical and food processing facilities.
Brazil's IBAMA environmental licensing requirements and Argentina's Secretaría de Ambiente y Desarrollo Sustentable chemical substance regulations are elevating compliance costs for solvent-containing formulations while redirecting R&D toward waterborne and low-VOC alternatives. ANVISA oversight of sealants used in medical device and pharmaceutical manufacturing environments adds a secondary regulatory layer constraining material selection in Brazil's health-industrial corridor. Stakeholders must monitor how Mercosur technical harmonization negotiations reshape cross-border product certification requirements and determine whether to centralize formulation platforms or maintain country-specific compliance architectures.
Market Dynamics
IBAMA's tightened VOC thresholds are forcing wholesale formulation reformulation across Brazilian industrial sealant production, compressing margins for solvent-dependent manufacturers while rewarding early movers into waterborne polymer systems. This regulatory compression is the dominant structural force reshaping competitive positioning in the region.
Growth Catalysts
- Brazilian Urban Construction:Commercial building envelopes in São Paulo and Rio de Janeiro corridors are specifying high-movement polyurethane joint systems for seismic accommodation and thermal cycling performance.
- REACH-aligned Mercosur Harmonization:Technical convergence negotiations are streamlining cross-border certification, reducing compliance duplication costs for sealant suppliers operating across Brazilian-Argentine trade corridors.
- Silane-Terminated Polymer Advancement:Hybrid STP intermediates are bridging silicone durability with polyurethane application versatility, opening specification-grade positioning in Brazilian facade glazing contracts.
Market Restraints
- Petrochemical Feedstock Volatility:Polyol and isocyanate input costs fluctuate with Brazilian refinery output disruptions, squeezing formulation margin predictability for polyurethane-dominant producers.
- Import Concentration Risk:Silane-terminated polymer intermediates concentrate through Dow's regional supply chain control, creating single-source vulnerability for Brazilian compounders lacking captive silane production.
- High-Temperature Curing Limitations:Epoxy sealant segments face application constraints in Brazilian ambient conditions exceeding 35°C, restricting industrial maintenance deployment in northern corridor petrochemical facilities.
Strategic Opportunities
- Argentine Infrastructure Rehabilitation:Buenos Aires and Córdoba provincial procurement volumes are concentrating demand for certified durability sealants in bridge deck and tunnel waterproofing applications.
- ANVISA Medical Device Certification:Pharmaceutical manufacturing environments in Brazil's health-industrial corridor require compliant sealant specifications, creating premium positioning for validated low-extractable formulations.
- Hybrid Adhesive-Sealant Convergence:Automotive assembly lines in Brazilian industrial parks are specifying bonded-sealed joint systems that reduce fastener counts and assembly cycle times.
Industry Challenges
- Formulation Chemist Scarcity:Brazilian technical universities produce insufficient polymer chemistry graduates familiar with silane crosslinking mechanisms and VOC-compliant solvent substitution protocols.
- Certification Timeline Compression:IBAMA environmental licensing and ANVISA medical-grade validation run on parallel tracks with unpredictable review cycles, delaying product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Sealants Market |
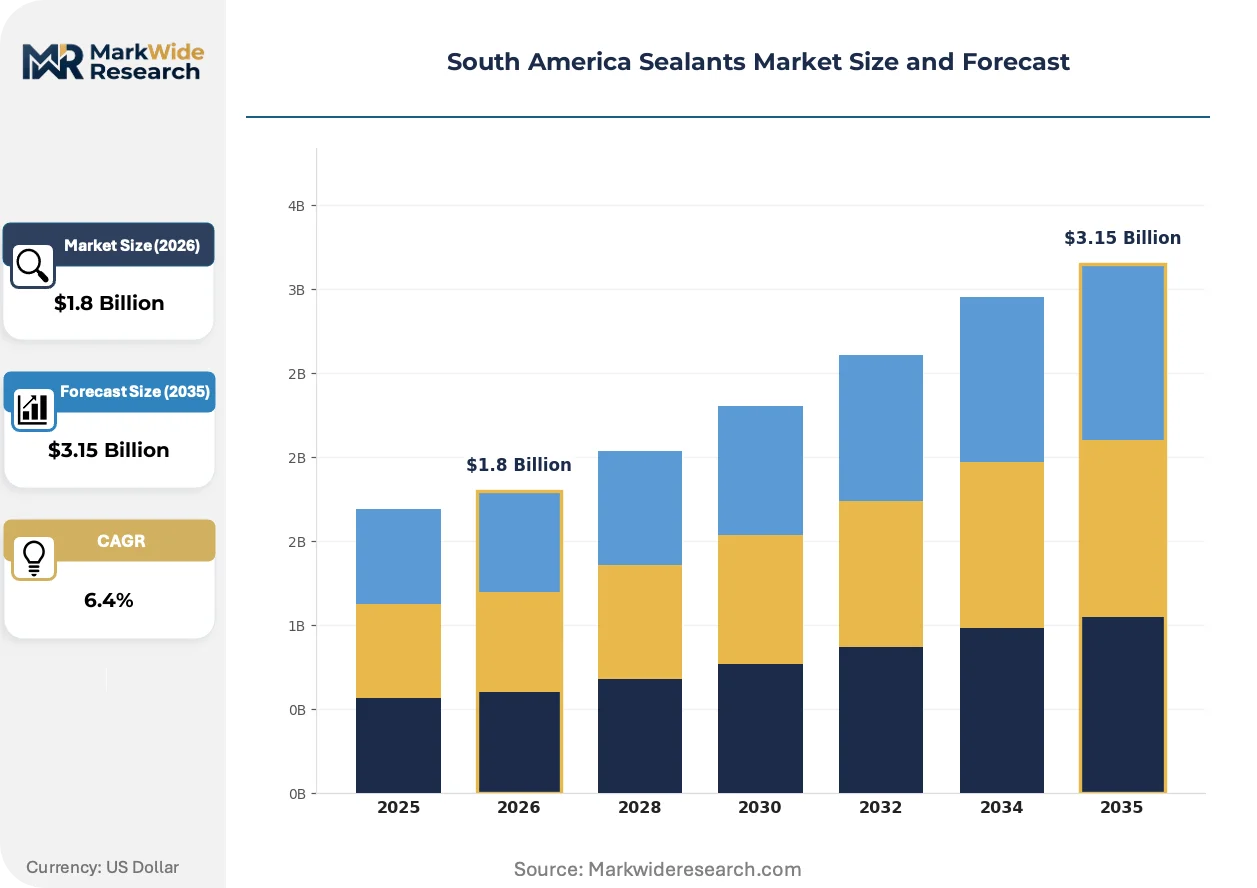
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy End User: Construction, Automotive, Marine, Electronics Application: Sealing, Bonding, Coating, Insulation Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, RPM International, H.B. Fuller Company, Soudal Holding N.V., Dow, Arkema Group, Momentive, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Sealants Market Trends and Innovations
Waterborne polymer chemistry is displacing solvent-based systems across Brazilian construction and industrial applications, driven by regulatory pressure and specification-grade procurement requirements. This shift is compressing legacy formulation advantages while elevating R&D-intensive competitors.
Silane-terminated polyurethane hybrid technology is electrifying specification-grade construction sealing by combining silicone UV stability with polyurethane substrate adhesion. Brazilian commercial facade contractors are adopting these systems for high-rise glazing contracts requiring 25-year durability warranties. The technology is compressing market share for conventional silicone suppliers unable to match hybrid application versatility and cost positioning.
IBAMA's updated environmental licensing framework is mandating VOC threshold reductions for industrial chemical products sold in Brazilian territory. Formulation houses are redirecting R&D expenditure toward waterborne acrylic and hybrid polymer platforms that maintain performance metrics without solvent content. Polyurethane construction sealant segments face the steepest compliance cost escalation, accelerating consolidation among mid-scale Brazilian compounders lacking reformulation capabilities.
Specification-driven procurement is displacing price-first buying patterns in Brazilian commercial building projects. Architects and envelope consultants now require certified movement accommodation factors and accelerated weathering test data before sealant inclusion in tender documents. This behavioral shift concentrates volume with suppliers maintaining in-house testing laboratories and IBAMA-compliant technical documentation, marginalizing commodity-grade importers in São Paulo state construction corridors.
South America Sealants Market Segmentation
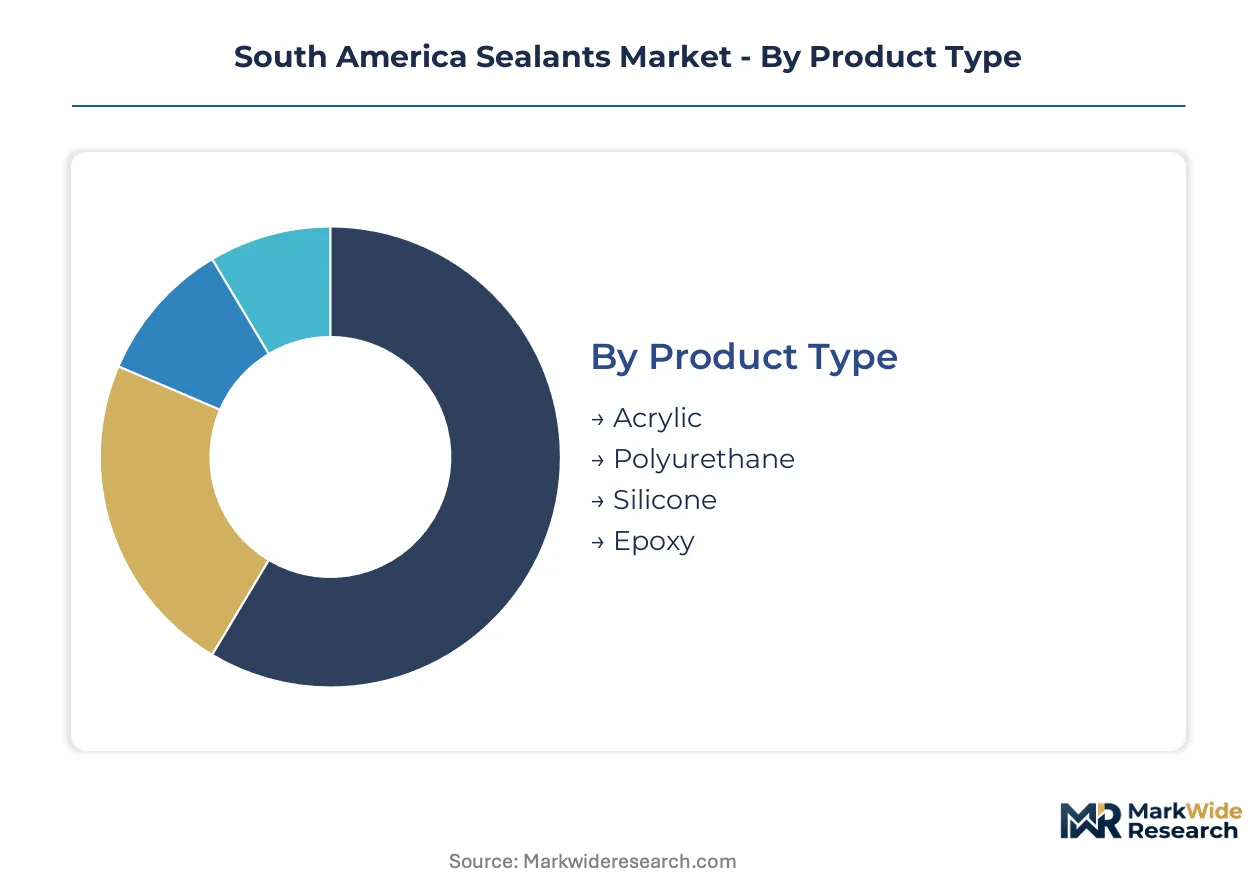
Sealant procurement patterns in South America diverge sharply across formulation chemistry, end-use specification intensity, and channel access economics. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Capital intensity escalates from commodity acrylic production through silane chemistry infrastructure to specialized epoxy curing systems requiring controlled atmosphere manufacturing.
- Polyurethane:Formulated from polyol-isocyanate reactions with tunable Shore A hardness and movement accommodation factors exceeding 25%. São Paulo commercial building corridors specify these systems for seismic joint accommodation and thermal cycling performance in high-rise envelopes.
- Silicone:Crosslinked polydimethylsiloxane networks delivering UV resistance and temperature stability from -50°C to 200°C. Brazilian facade glazing contractors in Rio de Janeiro specify these for 25-year durability warranties where certification documentation determines tender eligibility.
- Acrylic:Waterborne emulsion polymers with lower capital barriers to entry; formulation houses compete on VOC compliance cost rather than performance differentiation.
- Epoxy:Two-part thermosetting systems requiring precise stoichiometric mixing; Brazilian petrochemical maintenance applications in northern corridor facilities face ambient temperature curing constraints above 35°C.
Polyurethane absorbs the bulk of installed capacity; silicone is expanding most quickly.
End User:
Application complexity and specification documentation requirements separate construction procurement from industrial assembly integration.
- Construction:Envelope waterproofing, structural glazing, and expansion joint sealing across Brazilian urban corridors. Buenos Aires and Córdoba provincial infrastructure rehabilitation programs concentrate procurement volumes for certified durability bridge deck systems.
- Automotive:Bonded-sealed joint assemblies reducing fastener counts in Brazilian industrial park assembly lines. Hybrid adhesive-sealant specifications sustain margin pools through technical validation requirements.
- Marine:Below-deck sealing and hull bonding applications subject to saltwater immersion stress; smaller addressable volume with specialized certification protocols.
- Electronics:Potting and environmental protection for assemblies; limited regional manufacturing base constrains demand scale.
Construction commands the dominant revenue share; automotive is climbing the fastest on assembly line specification upgrades.
Application:
Functional purpose determines formulation selection criteria and performance testing protocols across the value chain.
- Sealing:Gap-filling and fluid barrier functions against hydrostatic pressure, thermal cycling, and substrate movement. Brazilian commercial building specifications now require certified movement accommodation factors before tender inclusion.
- Bonding:Structural adhesion combining load transfer with environmental protection; automotive and facade applications specify hybrid systems.
- Coating:Surface protection layers with sealant characteristics; industrial maintenance niches in food processing and chemical facilities.
- Insulation:Thermal and acoustic dampening with secondary sealing function; emerging specification in high-performance building envelopes.
Sealing maintains the largest application footprint; bonding is gaining share fastest on hybrid system adoption.
Distribution Channel:
Channel economics reflect specification complexity, order fragmentation, and technical support requirements.
- Direct Sales:Specification-grade procurement through manufacturer technical representatives. Brazilian commercial facade projects and ANVISA-medical device manufacturing environments require compliant documentation and in-laboratory testing support.
- Wholesale:Volume distribution to contractor networks in São Paulo state construction corridors; price-competitive polyurethane joint systems.
- Retail:Consumer-accessible small-format packaging; limited to commodity-grade acrylic formulations with minimal technical differentiation.
- Online:Emerging channel for standardized product codes with established specifications; procurement offices in mid-scale construction firms piloting digital sourcing.
Direct sales captures the premium specification tier; wholesale handles the highest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's commercial building corridors concentrate sealant specification activity, pulling high-performance polyurethane and silicone formulations through direct sales channels anchored by manufacturer technical representatives.
Brazil
IBAMA's tightened VOC thresholds are forcing wholesale reformulation across industrial sealant production. São Paulo and Rio de Janeiro urban construction corridors specify high-movement polyurethane joint systems for seismic accommodation. Brazilian commercial facade contractors now require certified 25-year durability warranties before tender inclusion.
Argentina
Buenos Aires and Córdoba provincial infrastructure rehabilitation programs concentrate procurement volumes for bridge deck and tunnel waterproofing applications. The Secretaría de Ambiente y Desarrollo Sustentable chemical substance regulations elevate compliance costs for solvent-containing formulations. Argentine construction procurement is shifting toward certified durability metrics in public works contracts.
Chile
Mining maintenance operations in the Atacama and Antofagasta regions generate demand for chemical-resistant epoxy sealants in processing facility upkeep. Chile's environmental regulator enforces emissions controls on industrial chemical products. Santiago's commercial building sector specifies silicone formulations for high-UV exposure facade applications.
Colombia
Bogotá's infrastructure expansion and Medellín's urban renewal projects drive construction sealant consumption. Colombian environmental licensing requirements are tightening for industrial chemical imports. The country's automotive assembly plants in Cundinamarca specify hybrid adhesive-sealant systems for bonded joint applications.
South America Sealants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification documentation and specification-grade positioning. The market structures around three tiers: multinational construction chemical houses with captive silane supply, regional compounders serving wholesale contractor networks, and import-dependent distributors of commodity acrylic formulations. Two dominant competitive moves are reshaping positioning: backward integration into silane-terminated polymer intermediates, and portfolio diversification into hybrid adhesive-sealant technologies.
Within the multinational tier, Sika AG, Henkel AG & Co. KGaA, and Dow occupy positions that exemplify divergent strategic anchors. Sika leverages construction chemicals heritage to anchor specification-grade silicone systems. Henkel differentiates through adhesive-sealant hybrid technologies. Dow competes on upstream control over regional supply chains for silane-terminated polymer intermediates.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| RPM International |
| H.B. Fuller Company |
| Soudal Holding N.V. |
| Dow |
| Arkema Group |
| Momentive |
| Others |
Pricing and Supply Chain Analysis
Brazilian commercial facade contractors and Argentine provincial infrastructure procurement offices concentrate buying power, anchoring a value-based pricing model where certified 25-year durability warranties command substantial premiums over commodity-grade alternatives.
Pricing Analysis
Outcome-based pricing tied to certified movement accommodation factors and accelerated weathering test data anchors premium positioning in Brazilian specification-grade procurement. Three-tier pricing structure across certified durability, standard compliance, and economy-grade tiers separates Sika and Henkel documentation-heavy offerings from wholesale polyurethane volume plays. Cost compression in solvent-dependent formulations is intensifying because IBAMA's VOC threshold reductions force wholesale reformulation expenditure. Mid-scale Brazilian compounders lacking captive R&D capabilities exhibit highest price sensitivity, while ANVISA-medical device manufacturers accept substantial premiums for validated low-extractable formulations.
Supply Chain Analysis
Argentine domestic-content mandates in provincial infrastructure contracts and Brazilian local-sourcing preferences in federal construction tenders are reshaping raw material procurement toward Mercosur-origin feedstocks. Silane-terminated polymer intermediates concentrate through Dow's regional supply chain control, with polyol and isocyanate inputs drawing from Brazilian petrochemical complexes and imported specialty chemical streams. Single-source vulnerability around silane chemistry creates structural risk for compounders lacking backward integration into crosslinking agent production. Distribution runs through manufacturer technical representatives for specification-grade direct sales, with wholesale contractor networks handling bulk polyurethane volume in São Paulo state construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized silane crosslinking chemistry capacity and IBAMA-compliant formulation infrastructure prop pricing premiums, constraining supply elasticity for specification-grade sealant procurement across Brazilian commercial building and Argentine infrastructure rehabilitation programs.
For Market Incumbents: Deploy specification-grade certification investments to deepen technical documentation barriers against commodity-grade importers. Anchor proprietary hybrid adhesive-sealant platforms in automotive assembly line contracts to lock out substitute bonding technologies. Capture Argentine provincial infrastructure procurement through pre-qualified durability certification aligned with Secretaría de Ambiente y Desarrollo Sustentable chemical substance regulations. Expand captive silane-terminated polymer production to eliminate Dow supply chain vulnerability. For New Entrants and Emerging Players: Capture waterborne acrylic white-space in Brazilian mid-scale construction corridors where VOC compliance cost pressures displace solvent-dependent incumbents. Target Buenos Aires and Córdoba provincial bridge deck waterproofing specifications through certified durability partnerships with local engineering consultants. Pursue ANVISA-medical device sealant validation as a premium positioning anchor in Brazil's health-industrial corridor, leveraging low-extractable formulation specialization against generalist competitors. For Investors and Strategic Acquirers: The window for entry favors Brazilian compounders with captive silane chemistry infrastructure and established IBAMA technical documentation archives. Long-term viability rests on backward integration into crosslinking agent production and specification-grade procurement relationships with federal and provincial infrastructure agencies. Monitor Mercosur technical harmonization negotiation outcomes as the inflection signal determining whether centralized formulation platforms or country-specific compliance architectures dominate capital deployment efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Chemistry | Eliminates single-source dependency on Dow's regional supply chain control for Brazilian compounders. |
| Hybrid Adhesive-Sealant Platform Development | Captures automotive assembly line specifications in Brazilian industrial parks reducing fastener counts. |
| ANVISA Medical-Grade Certification Investment | Opens premium positioning in pharmaceutical manufacturing environments requiring validated low-extractable formulations. |
| Waterborne Polymer Reformulation Acceleration | Aligns product portfolios with IBAMA's tightened VOC thresholds compressing solvent-dependent competitor margins. |
| Argentine Provincial Procurement Pre-Qualification | Locks in bridge deck and tunnel waterproofing volumes concentrated in Buenos Aires and Córdoba rehabilitation programs. |
Research Methodology
Document review covered customs and trade flow databases, IBAMA environmental licensing filings, and ANVISA medical device registration records, complemented by interviews with Brazilian formulation house R&D directors, Argentine provincial infrastructure procurement officers, São Paulo commercial facade contractor technical representatives, and Mercosur regulatory affairs specialists. Secondary validation drew from SEC 10-K disclosures of multinational construction chemical houses, Brazilian petrochemical association output reports, and infrastructure tender documentation from Buenos Aires and Córdoba provincial authorities. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry segments.
Cross-referencing historical procurement patterns with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use specification intensity, distribution channel economics, and regional regulatory cluster. CAGRs were derived through trend extrapolation adjusted for structural shift impacts. Key forecast inputs incorporated IBAMA compliance timeline assumptions and Mercosur harmonization negotiation progress indicators.
The model holds under continued VOC threshold tightening and stable petrochemical feedstock availability; deviation in Brazilian refinery output disruptions or accelerated Mercosur regulatory convergence would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market