
 Fire Resistant Paints Market | 2026-2036
Fire Resistant Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Paints Market Analysis
The EU Green Deal is decoupling fire resistant paint procurement from legacy solvent-based formulations across European construction supply chains. Sherwin-Williams Company leverages its North American distribution network to sustain specification dominance in commercial steel protection. PPG Industries anchors its portfolio through R&D intensity in intumescent coating technologies. Akzo Nobel N.V. competes on water-based platform breadth across multiple substrate applications.
Fire resistant paints are formulated coatings containing intumescent or cementitious compounds that expand under heat to form insulating char layers, typically rated for fire resistance durations from 30 to 120 minutes depending on film thickness and substrate. Their primary purpose is passive fire protection of structural elements in buildings and industrial facilities to maintain load-bearing integrity during fire events. Intumescent coatings command premium positioning due to thinner film builds and aesthetic compatibility with exposed steel architectures, while cementitious systems occupy cost-sensitive infrastructure segments where thickness tolerance is less constrained. Water-based technologies lead specification trends in regulated European and North American markets, whereas solvent-based formulations retain share in heavy industrial and offshore oil and gas applications where humidity resistance and rapid cure cycles override VOC constraints.
EMA, REACH, and the EU F-Gas Regulation collectively constrain formulation chemistry and product registration pathways for suppliers operating across European jurisdictions, elevating compliance costs but also consolidating market access around technically capable manufacturers. In the United States, OSHA workplace safety standards and NFPA building codes directly mandate fire protection ratings for commercial structures, creating baseline demand that shifts upward following significant fire incidents. China's NMPA and GB standards enforcement is tightening product certification requirements for imported and domestically manufactured fire resistant coatings alike. Stakeholders must monitor divergence between regional VOC limits and fire performance test protocols when allocating formulation development resources across geographic portfolios.
Market Dynamics
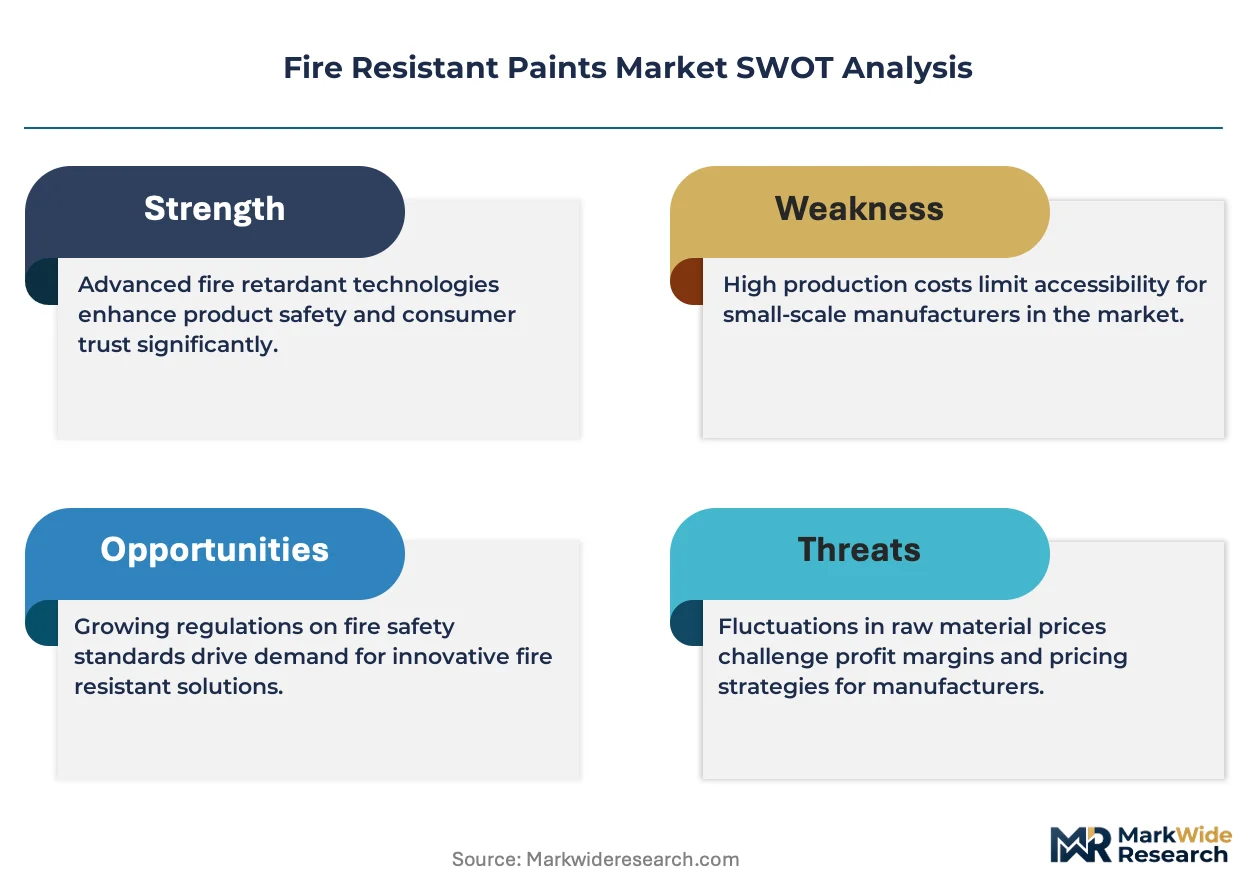
EU Green Deal mandates are forcing solvent-based fire resistant paint formulations out of European construction supply chains, compressing incumbent product lines while elevating water-based chemistry R&D budgets across the sector.
Growth Catalysts
- China's GB Standard Enforcement:Updated fire safety certification requirements for commercial and residential high-rises are accelerating specification upgrades in tier-one cities.
- Intumescent Thin-Film Technology:Steel architects specify these coatings for exposed structural aesthetics, expanding addressable surface area per project.
- REACH Compliance Consolidation:Registration costs and testing protocols are filtering out undercapitalized suppliers, concentrating volume with technically capable manufacturers.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and flame-retardant additive prices swing with crude oil indices, compressing formulation margins unpredictably.
- Raw Material Supplier Concentration:Specialty intumescent chemical production clusters in Germany and China, creating geographic chokepoints.
- Cementitious Substitution Ceiling:Thick-film cementitious systems cannot match intumescent aesthetic performance, locking them out of premium architectural segments.
Strategic Opportunities
- India's Urban Infrastructure Pipeline:Metro rail and commercial tower construction in Mumbai and Delhi remains underpenetrated by certified passive fire protection suppliers.
- Offshore Wind Farm Expansion:North Sea and Baltic turbine foundation specifications are opening new marine-grade intumescent demand.
- Digital Specification Platforms:Construction procurement software is converging with coating databases, enabling direct manufacturer-to-contractor channel bypass.
Industry Challenges
- Fire Testing Laboratory Bottlenecks:ISO 834 and ASTM E119 certification queues extend project timelines by 8-14 weeks.
- Formulation Chemist Scarcity:Expertise in halogen-free flame retardant polymer science commands premium compensation and limits R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Paints Market |
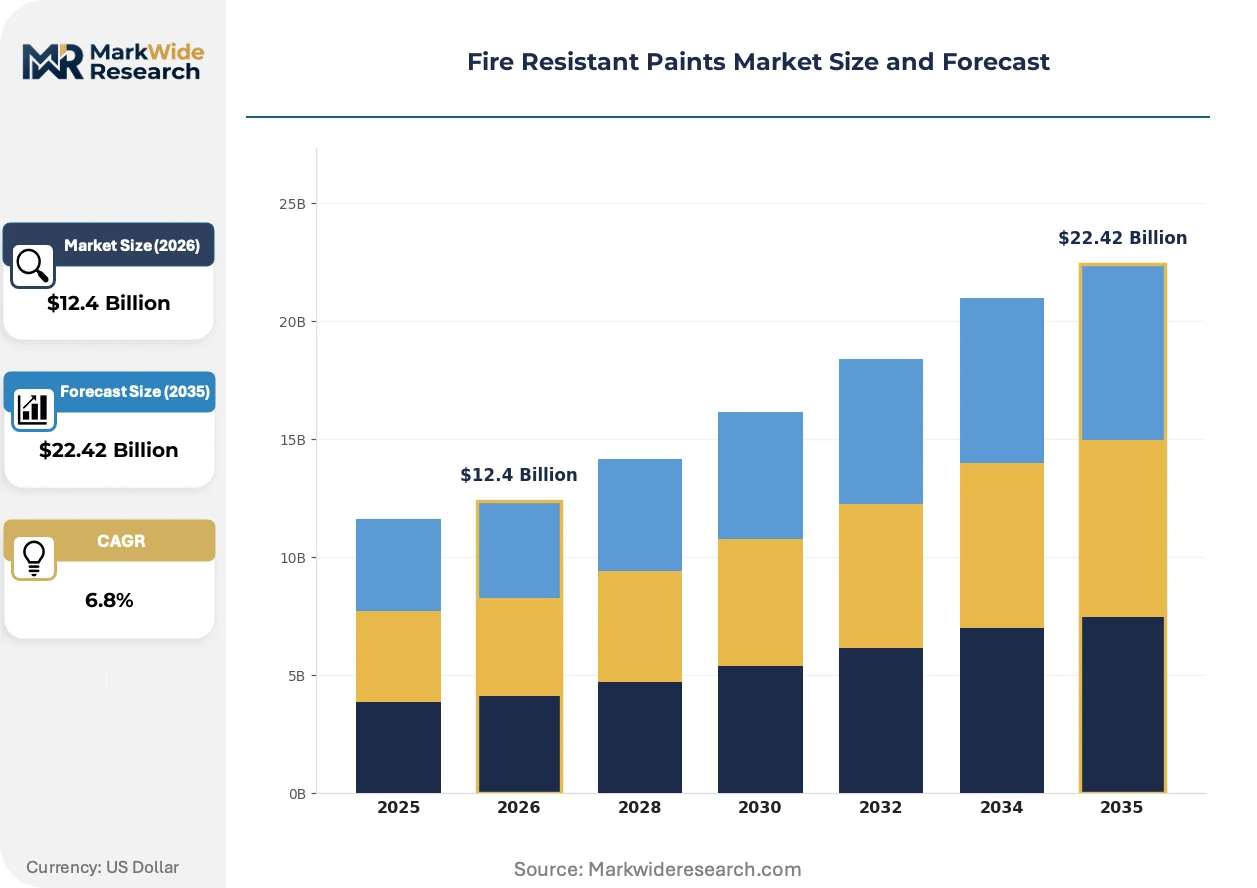
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent, Cementitious, Coatings, Spray Application: Wood, Concrete, Steel, Drywall End User: Construction, Oil & Gas, Manufacturing, Aerospace Technology: Water-based, Solvent-based, Hybrid, Epoxy |
| Companies Covered | Akzo Nobel N.V., Sherwin-Williams Company, PPG Industries, Jotun AS, Hempel A/S, BASF SE, Nippon Paint Co. Ltd., RPM International, Contego International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Paints Market Emerging Trajectories
Reformulation chemistry is converging with digital specification tools and tightening VOC frameworks across multiple jurisdictions, compressing product development cycles and reshaping competitive positioning.
Nano-clay reinforced intumescent systems are converging with self-healing polymer matrices to extend coating durability under cyclic humidity exposure. Offshore oil and gas platform operators in the North Sea specify these hybrid formulations for reduced maintenance intervals. The technology is converging with predictive maintenance analytics to enable condition-based recoating rather than calendar-driven replacement.
REACH authorization timelines for legacy halogenated flame retardants are compressing available formulation windows for solvent-based product lines. ECHA's 2024-2026 substance evaluation rolling action plan targets specific brominated compounds used in industrial coatings. German and French coating manufacturers are accelerating water-based platform investments to maintain registration compliance.
Steel fabricators now bundle fire protection specification with structural engineering services, unbundling traditional distributor relationships. This channel compression is most visible in UK and Australian commercial construction markets where design-build contracts dominate. Manufacturers respond with direct technical sales teams embedded in early-stage project development.
Fire Resistant Paints Market Segmentation
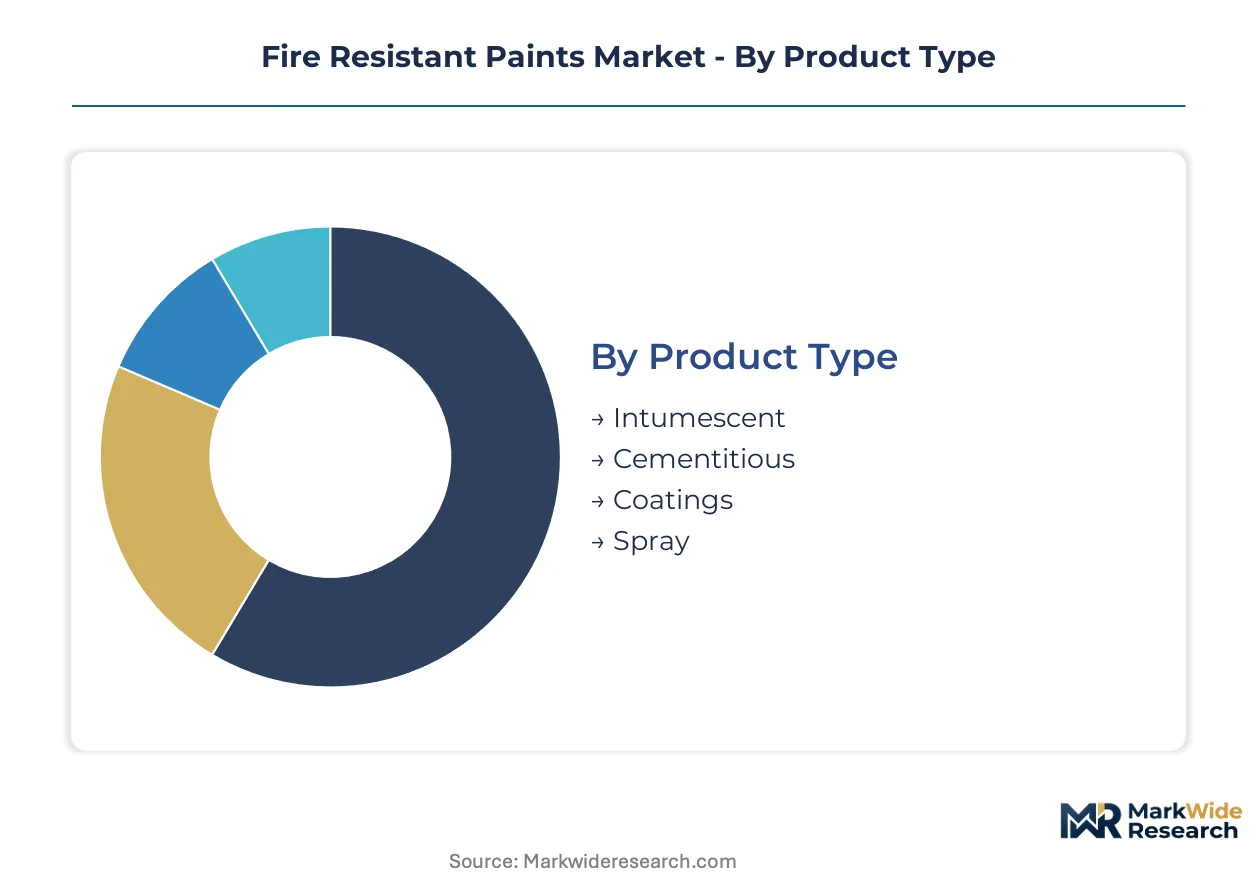
Fire resistant paint procurement diverges sharply across substrate requirements, regulatory exposure, and project scale. Specification patterns in this market track construction method, fire rating duration, and VOC compliance thresholds rather than price alone.
Product Type:
Buyers differentiate primarily by film thickness tolerance and aesthetic exposure requirements, with architectural visibility driving premium chemistry selection.
- Intumescent:These coatings contain expandable graphite or ammonium polyphosphate systems that char under heat to form insulating layers 50-100 times original thickness. Steel architects in commercial high-rises specify thin-film intumescent systems for exposed structural elements where cementitious bulk would compromise design intent. REACH authorization pressure on halogenated retardants is accelerating water-based intumescent R&D budgets.
- Cementitious:Portland cement and vermiculite-based formulations spray-applied at 10-50mm thickness dominate infrastructure tunnels and industrial facilities where substrate concealment eliminates aesthetic constraints. Chinese metro rail construction in Chengdu and Xi'an specifies these systems for cost-sensitive underground passages.
- Coatings:Brush- and roller-applied variants serve maintenance recoating and small-scale commercial retrofit projects with limited spray equipment access.
- Spray:High-volume application systems target large industrial footprints where labor efficiency outweighs material premium.
Volume sits with cementitious systems in infrastructure; growth tilts toward intumescent thin-film technologies gaining specification share in exposed steel architecture.
Application:
Substrate thermal properties and load-bearing criticality determine coating chemistry compatibility and required film thickness.
- Steel:Structural steel loses 50% load capacity at 550°C, mandating intumescent protection for exposed beams and columns in commercial towers. UK design-build contractors now bundle fire protection specification with structural engineering services, compressing traditional distributor channels.
- Concrete:Spalling resistance drives cementitious and epoxy-modified formulations for tunnel linings and parking structures where hydrocarbon fire curves apply. German autobahn tunnel refurbishment projects under EU Tunnel Safety Directive specifications anchor European demand.
- Wood:Mass timber construction in Vancouver and Oslo specifies transparent intumescent systems preserving architectural grain visibility while meeting 60-90 minute ratings.
- Drywall:Joint compounds and surface coatings serve residential and light commercial compartmentalization with lower rating requirements.
Steel applications command the steepest expansion trajectory as exposed structural aesthetics proliferate in commercial architecture.
End User:
Project scale, fire risk profile, and maintenance access cycles differentiate procurement patterns across verticals.
- Construction:Commercial high-rise and institutional projects in China's tier-one cities drive specification volume, with GB standard enforcement tightening certification requirements for imported and domestic coatings alike. Design-build contract prevalence in Australia and the UK accelerates early-stage manufacturer engagement.
- Oil & Gas:Offshore platform operators in the North Sea specify marine-grade intumescent systems with self-healing polymer matrices for reduced maintenance intervals under cyclic humidity exposure.
- Manufacturing:Chemical processing and warehouse facilities balance cost sensitivity with insurance-mandated protection ratings.
- Aerospace:Specialized formulations for aircraft interiors and hangar facilities face FAA flammability standards and weight-critical specifications.
Construction absorbs the dominant share of procurement volume; aerospace presents the narrowest but highest-margin specification niche.
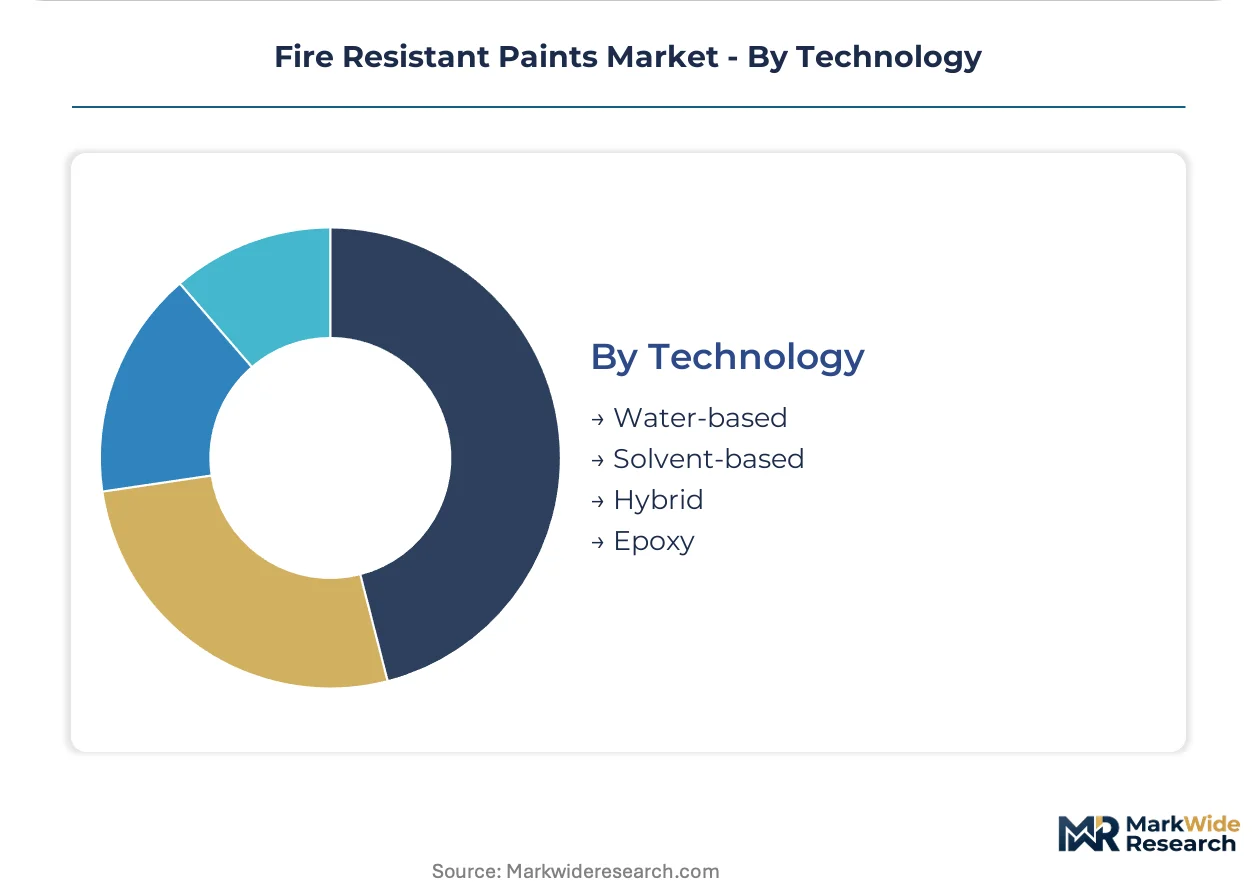
Technology:
Formulation chemistry selection tracks regional VOC limits, cure speed requirements, and humidity resistance needs.
- Water-based:Acrylic and vinyl acetate dispersions lead specification in EU and North American commercial construction where EU Green Deal mandates and OSHA workplace standards constrain solvent emissions. German and French manufacturers accelerate platform investments to maintain REACH compliance.
- Solvent-based:Epoxy and alkyd systems retain offshore oil and gas and heavy industrial applications where rapid cure cycles and humidity resistance override VOC constraints.
- Hybrid:Water-reducible and high-solids formulations bridge performance gaps in markets with transitional regulatory frameworks.
- Epoxy:Two-component systems serve chemical exposure environments and subsea applications requiring barrier protection alongside fire ratings.
Water-based technologies capture the expanding specification share in regulated markets; solvent-based formulations defend position in industrial segments where performance requirements resist substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's commercial tower construction pipeline anchors specification volume across the Asia-Pacific region, while regulatory divergence between jurisdictions fragments formulation chemistry requirements.
China
GB standard enforcement in Beijing and Shenzhen accelerates certification upgrades for high-rise commercial and residential projects. NMPA tightened product registration pathways for imported intumescent coatings in 2024. Chengdu and Xi'an metro rail construction specifies cementitious systems for cost-sensitive underground tunnel passages.
United States
Commercial steel protection in Houston and Dallas drives specification demand for thin-film intumescent systems. OSHA workplace safety standards and NFPA building codes mandate fire protection ratings for commercial structures. Chicago and New York design-build contractors bundle fire protection specification with structural engineering services.
Germany
Autobahn tunnel refurbishment under the EU Tunnel Safety Directive anchors European cementitious demand. ECHA's substance evaluation rolling action plan targets brominated compounds used in industrial coatings. North Rhine-Westphalia coating manufacturers accelerate water-based platform investments to maintain REACH compliance.
United Kingdom
London commercial high-rise development specifies intumescent coatings for exposed structural steel aesthetics. EU Green Deal mandates force solvent-based formulations out of construction supply chains. UK design-build contract prevalence compresses traditional distributor channels toward direct manufacturer engagement.
India
Mumbai and Delhi metro rail and commercial tower construction remains underpenetrated by certified passive fire protection suppliers. BIS certification requirements for fire resistant coatings lag behind enforcement capacity. Maharashtra infrastructure projects balance cost sensitivity with insurance-mandated protection ratings.
Fire Resistant Paints Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification breadth, creating a tiered structure where REACH-compliant water-based specialists command pricing power over solvent-dependent generalists. The vendor base clusters around three strategic archetypes: integrated coatings conglomerates with multi-substrate portfolios, intumescent technology specialists with thin-film R&D depth, and regional formulators serving cost-sensitive infrastructure segments. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into adjacent passive fire protection materials.
Within the integrated coatings tier, Akzo Nobel N.V. and Sherwin-Williams Company occupy positions exemplifying multi-platform breadth across water-based and solvent-based chemistries. PPG Industries anchors the intumescent technology specialist archetype with concentrated R&D positioning in expandable coating systems. These three entities collectively represent the premium-margin tier where technical capability and regulatory compliance consolidate specification access.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Sherwin-Williams Company |
| PPG Industries |
| Jotun AS |
| Hempel A/S |
| BASF SE |
| Nippon Paint Co. Ltd. |
| RPM International |
| Contego International |
| Others |
Supply Flow & Price Mechanics
Epoxy resin and flame-retardant additive costs swing with crude oil indices, compressing formulation margins unpredictably as these petrochemical feedstocks cascade through intumescent and cementitious coating tiers. Water-based chemistry investments in Germany and France absorb premium pricing to offset REACH compliance expenditures, while solvent-based formulations in offshore oil and gas defend position through humidity resistance premiums.
Pricing Analysis
Fire rating duration anchors value-based pricing, with 120-minute certified intumescent systems commanding substantial premiums over 30-minute alternatives due to liability reduction and insurance compliance outcomes. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant water-based specialists from solvent-dependent generalists and uncertified regional formulators. Pricing pressure stems from raw material supplier concentration in Germany and China, with specialty intumescent chemical production creating geographic chokepoints. Cementitious systems in infrastructure tunnels exhibit highest price sensitivity; offshore marine-grade formulations with self-healing polymer matrices show lowest sensitivity due to maintenance interval value.
Supply Chain Analysis
Formulation chemist scarcity in North Rhine-Westphalia and Shanghai constrains batch throughput at water-based manufacturing facilities. Supply concentrates in Germany, China, and the United States for intumescent coating production, with raw material dependencies on expandable graphite from China, ammonium polyphosphate from Germany, and epoxy resins from South Korea. Single-source vulnerability in specialty intumescent chemical production elevates risk exposure for thin-film coating manufacturers. Distribution runs through specification-influencing distributors in European and North American commercial construction, with direct manufacturer engagement compressing traditional channels in UK and Australian design-build markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based intumescent chemistry is displacing legacy solvent-based formulations across regulated construction markets, compressing incumbent product lines while elevating R&D budgets for compliant alternatives.
For Market Incumbents: Acquire water-based formulation IP portfolios to offset REACH authorization pressure on halogenated flame retardants. Consolidate certification breadth across multiple substrate applications to defend specification access against emerging regional formulators. Capacity addition in Maharashtra and Gujarat captures India's underpenetrated metro rail construction pipeline before BIS enforcement tightens. For New Entrants and Emerging Players: Capture specification share in Mumbai and Delhi commercial tower construction where certified passive fire protection suppliers remain scarce. Target offshore wind farm foundation coatings in the North Sea and Baltic as marine-grade intumescent demand opens outside incumbent oil and gas relationships. Digital specification platform partnerships enable direct contractor channel bypass without distributor infrastructure investment. For Investors and Strategic Acquirers: ECHA's 2024-2026 substance evaluation rolling action plan targeting brominated compounds is the leading indicator that water-based technology specialists will consolidate specification access. Long-term viability favors REACH-compliant manufacturers with multi-substrate certification breadth over solvent-dependent generalists facing registration cost barriers. Acquisition target archetype: mid-cap water-based formulators with thin-film R&D depth and established GB standard compliance for China market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame-Retardant Additives | Captive supply of ammonium polyphosphate reduces exposure to German and Chinese supplier concentration. |
| Water-Based Platform Certification Investment | REACH compliance and EU Green Deal alignment secure specification access in tightening European construction markets. |
| Direct Technical Sales Team Deployment | Early-stage project embedding counters distributor channel compression in UK and Australian design-build contracts. |
| Digital Specification Platform Partnership | Construction procurement software integration enables manufacturer-to-contractor channel bypass without traditional distribution. |
| Marine-Grade Intumescent Formulation Development | Self-healing polymer matrices capture offshore wind turbine foundation specifications in North Sea expansion zones. |
Methodological Framework
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone for volume and value estimation across coating chemistry tiers. Primary interviews with plant managers at formulation facilities, procurement leads at steel fabricators, distribution channel partners, and technical R&D directors at integrated coatings conglomerates validated secondary assumptions. Bottom-up and top-down triangulation reconciled project-level specification data with aggregate production capacity assessments.
Bottom-up modeling tracked individual construction project specifications by fire rating duration, substrate type, and chemistry selection across the analysis window. Segmentation dimensions included product type, application substrate, end-use vertical, and technology chemistry, with regional regulatory clusters capturing EU Green Deal, OSHA, and GB standard enforcement patterns. CAGRs derived from project pipeline aggregation and capacity expansion announcements, with intumescent thin-film adoption curves and cementitious infrastructure spend serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and REACH authorization timeline shifts. Forecasts reflect assumptions around GB standard enforcement consistency in China and design-build contract prevalence in UK and Australian commercial construction. Fire testing laboratory bottlenecks and formulation chemist scarcity warrant ongoing watch as potential forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Water Color Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Additives Market