
 Paint Sprayer Market | 2026-2036
Paint Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Sprayer Market Analytics
After-sales maintenance contracts and software-enabled performance monitoring is shifting how manufacturers capture lifetime value from equipment placements. Graco Inc. leverages its North American service network to anchor recurring revenue streams. Wagner Group GmbH differentiates through European distribution density and localized support infrastructure. Anest Iwata Corp. specializes in precision atomization technology for automotive refinishing segments.
A paint sprayer is a pneumatic or electric fluid-handling device that atomizes coating material through controlled pressure delivery, typically operating between 1,500 and 3,000 PSI for airless systems, to deposit uniform films on substrates. Its primary commercial purpose is to accelerate surface coverage rates while reducing material waste versus brush or roller application. Airless sprayers dominate commercial contractor fleets where speed on large surface areas determines labor economics. HVLP sprayers command premium positioning in furniture finishing and automotive coatings where transfer efficiency thresholds approach 65% under environmental compliance. Electrostatic systems represent the fastest-growing technology subset as manufacturers integrate grounded conveyor systems for uniform coating deposition on metal substrates.
EPA VOC regulations and OSHA workplace exposure limits shape equipment specifications and spray booth ventilation requirements across manufacturing and refinishing operations. California Air Resources Board standards enforce stricter emission thresholds than federal baselines, creating a dual-compliance landscape for national equipment suppliers. Stakeholders must monitor evolving state-level environmental mandates and assess whether smart-technology integration in spray systems justifies premium positioning against conventional equipment lifecycles.
Market Dynamics
EPA VOC emission standards and state-level environmental mandates are compressing equipment replacement cycles as contractors face compliance deadlines for HVLP and electrostatic system upgrades.
Growth Catalysts
- EPA VOC Regulations:Federal emission thresholds are mandating equipment turnover in automotive refinishing and industrial coating operations across the United States.
- Infrastructure Renewal Timelines:Commercial contractors in the United States are expanding fleet capacity to meet accelerated bridge, highway, and public building rehabilitation schedules.
- Electrostatic Technology:Grounded conveyor integration in metal fabrication facilities is displacing conventional spray methods through superior transfer efficiency and reduced overspray waste.
Market Restraints
- Steel and Aluminum Input Costs:Pump housing and pressure vessel fabrication faces margin pressure from commodity price volatility in raw materials.
- California CARB Standards:Stricter state-level emission thresholds than federal baselines create dual-compliance burdens for national equipment suppliers.
- Brush and Roller Substitution:Small-scale residential repaint projects retain preference for manual application in price-sensitive consumer segments.
Strategic Opportunities
- Software-Enabled Performance Monitoring:IoT sensor integration in contractor-grade equipment creates recurring revenue streams through predictive maintenance contracts.
- Furniture Finishing Segment:HVLP system penetration remains below saturation in custom woodworking and cabinet manufacturing operations.
- OSHA Workplace Exposure Limits:Tighter ventilation and personal protective equipment mandates are accelerating booth retrofit demand in manufacturing facilities.
Industry Challenges
- Skilled Applicator Shortage:Proper HVLP and electrostatic technique certification requires training investment that smaller contractors struggle to resource.
- Legacy Equipment Integration:Retrofitting smart monitoring capabilities into installed airless sprayer fleets presents technical compatibility hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Sprayer Market |
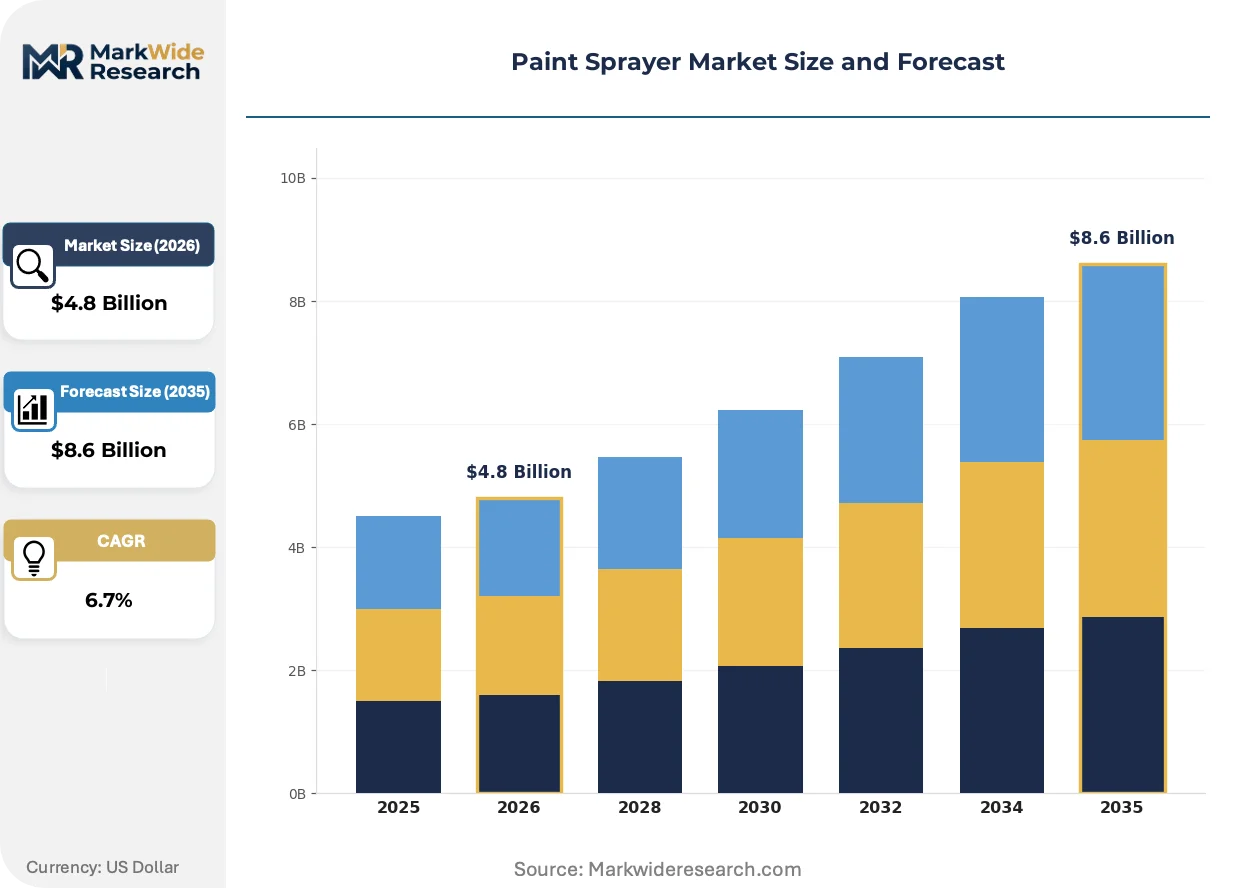
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airless Sprayers, HVLP Sprayers, Compressed Air Sprayers, Electrostatic Sprayers End User: Residential Users, Commercial Contractors, Industrial Users, DIY Enthusiasts Technology: Conventional Technology, Advanced Robotics, Smart Technology, Manual Technology Application: Automotive Coatings, Furniture Finishing, Wall Painting, Protective Coatings |
| Companies Covered | Graco Inc., Wagner Group GmbH, Anest Iwata Corp., 3M Co., SATA GmbH & Co. KG, Fuji Industrial Spray Equipment Ltd., Nordson Corporation, Titan Tool, Apollo Sprayers Intl. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Sprayer Market Evolving Landscape
Equipment manufacturers are embedding connectivity and automation to capture lifetime value beyond initial hardware sales, while regulatory pressure accelerates technology substitution in coating application methods.
Smart spray systems with embedded pressure sensors and flow meters are expanding into commercial contractor fleets through real-time performance tracking and automated tip-wear alerts. Large-scale painting operations in the United States are piloting these systems to reduce material overuse and document compliance for environmental audits. This connectivity layer is expanding into subscription-based service models that anchor manufacturer-customer relationships beyond warranty periods.
California Air Resources Board standards are enforcing emission thresholds that exceed federal EPA baselines, creating a bifurcated compliance landscape for equipment suppliers serving multiple states. Automotive refinish shops in California face accelerated equipment replacement timelines to maintain operating permits. National distributors are responding with state-specific inventory stratification that segments HVLP and compliant electrostatic inventory by destination market.
Rental and lease-to-own arrangements are displacing outright equipment purchases among mid-sized commercial contractors managing cash flow across project cycles. Equipment distributors in the United States are building fleet management programs that bundle maintenance, training, and upgrade pathways. This financing flexibility is most visible in residential construction corridors where project volume fluctuation makes capital deployment timing critical.
Paint Sprayer Market Segmentation
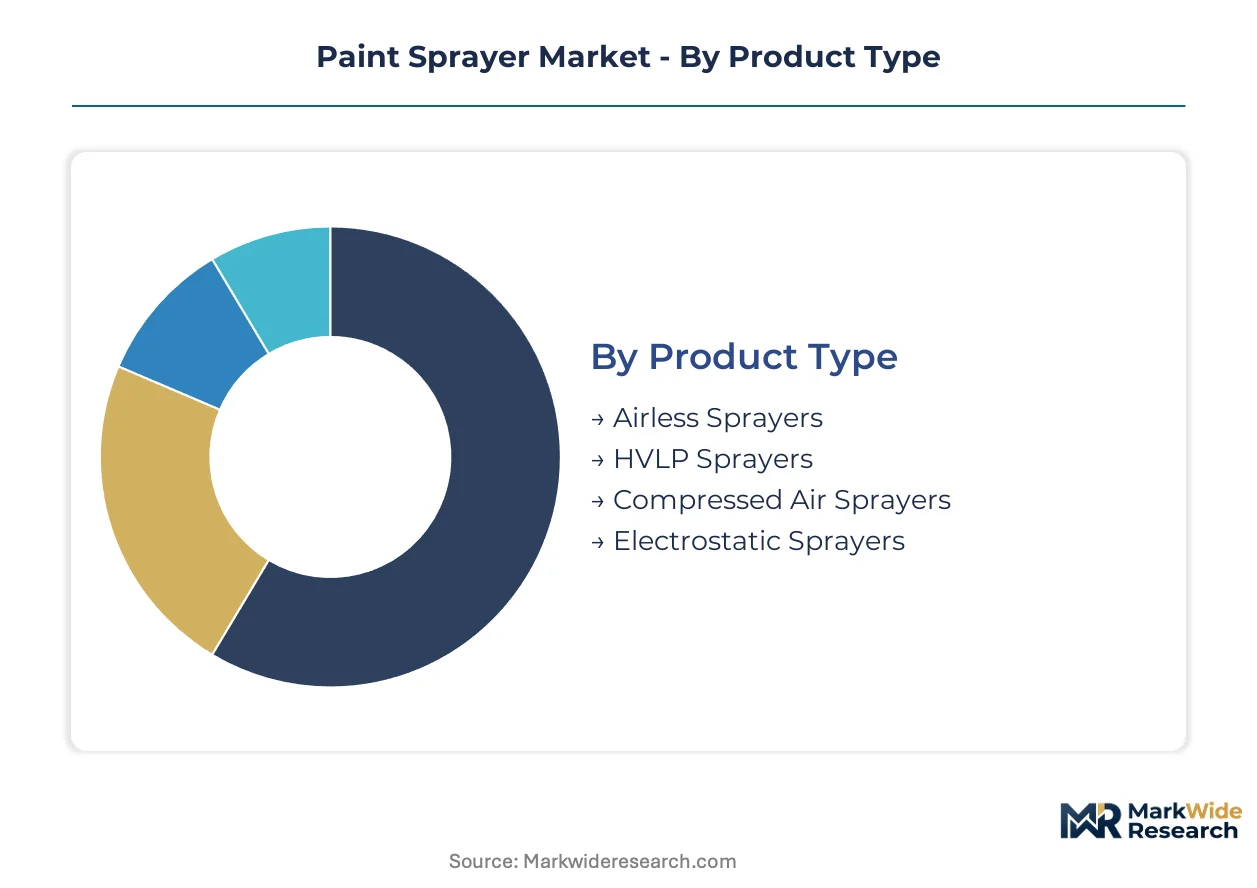
Paint sprayer segmentation reveals how application requirements fragment equipment specifications across pressure ratings, transfer efficiency mandates, and operator skill levels. Contractors select systems based on substrate geometry, coating viscosity, and environmental compliance obligations rather than brand preference alone.
Product Type:
Airless systems dominate volume shipments while HVLP and electrostatic technologies command premium positioning through regulatory compliance advantages.
- Airless Sprayers:These high-pressure systems atomize coatings through hydraulic force without compressed air, typically operating between 1,500 and 3,000 PSI for rapid surface coverage. Demand concentrates among commercial contractors in the United States executing bridge rehabilitation and commercial building exteriors where labor economics favor speed over material conservation. Steel and aluminum input costs for pump housings create margin pressure during commodity price spikes.
- HVLP Sprayers:High Volume Low Pressure technology uses high air volume at reduced pressure to achieve transfer efficiency approaching 65%, minimizing overspray and VOC emissions. California Air Resources Board standards and EPA mandates are accelerating replacement cycles in automotive refinishing and furniture manufacturing operations where environmental permits require documented compliance.
- Compressed Air Sprayers:Conventional pneumatic systems remain entrenched in legacy manufacturing facilities with existing compressor infrastructure.
- Electrostatic Sprayers:Grounded conveyor integration in metal fabrication facilities is displacing conventional methods through superior coating uniformity and reduced waste.
Today's leader: Airless Sprayers. Tomorrow's challenger: Electrostatic Sprayers.
End User:
Commercial contractors drive replacement demand through fleet refresh cycles while residential and DIY segments show price-sensitive equipment selection.
- Commercial Contractors:Fleet operators managing multiple project types across infrastructure renewal timelines require equipment durability and rapid service response. United States-based contractors are expanding capacity to meet accelerated public building rehabilitation schedules, with rental and lease-to-own arrangements displacing outright purchases to manage cash flow across project cycles.
- Industrial Users:Manufacturing facilities with integrated spray booths face OSHA workplace exposure limits and ventilation retrofit mandates that accelerate equipment turnover in automotive, aerospace, and metal fabrication operations.
- Residential Users:Homeowners undertaking interior and exterior repaint projects favor lower-cost compressed air or handheld electric units.
- DIY Enthusiasts:Price-sensitive consumers retain preference for brush and roller substitution on small-scale projects despite equipment availability.
Commercial Contractors anchor current revenue. Industrial Users are climbing the fastest as compliance deadlines tighten.
Technology:
Smart system penetration creates recurring revenue opportunities while conventional technology retains installed base dominance.
- Smart Technology:Embedded pressure sensors and flow meters enable real-time performance tracking, automated tip-wear alerts, and predictive maintenance contracts. Large-scale painting operations in the United States pilot these systems to document environmental compliance and reduce material overuse, expanding manufacturer-customer relationships beyond warranty periods through subscription service models.
- Conventional Technology:Pneumatic and electric systems without connectivity dominate existing contractor fleets where capital replacement cycles extend equipment lifecycles.
- Advanced Robotics:Automated spray systems integrate with grounded conveyor infrastructure in high-volume metal fabrication facilities.
- Manual Technology:Handheld units without automation retain position in price-sensitive residential and entry-level commercial segments.
Conventional Technology holds installed base. Smart Technology shows steepest expansion trajectory through service revenue attachment.
Application:
Automotive and protective coatings segments lead equipment specification complexity while wall painting standardizes around contractor-grade airless systems.
- Automotive Coatings:Precision atomization requirements for basecoat, clearcoat, and specialty finishes demand HVLP and electrostatic systems with transfer efficiency thresholds enforced by California CARB standards. Automotive refinish shops face accelerated equipment replacement timelines to maintain operating permits under stricter state-level emission thresholds.
- Protective Coatings:Bridge, highway, and industrial infrastructure applications require high-pressure airless systems capable of handling high-viscosity epoxy and polyurethane formulations. United States infrastructure renewal schedules are expanding contractor fleet capacity for these demanding specifications.
- Furniture Finishing:Custom woodworking and cabinet manufacturing operations show below-saturation HVLP penetration.
- Wall Painting:Residential and commercial interior-exterior applications standardize on contractor-grade airless equipment.
Automotive Coatings command premium positioning. Protective Coatings gain share fastest through infrastructure investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States infrastructure spending contrasts sharply with European regulatory stringency, while Asian manufacturing hubs scale coating capacity to serve export markets. Equipment specifications diverge sharply across these demand centers.
United States
Commercial contractors in Texas and Florida are expanding airless sprayer fleets to meet bridge rehabilitation timelines under the Infrastructure Investment and Jobs Act. EPA VOC standards compress replacement cycles for automotive refinish operations. The Southeast construction corridor from Atlanta to Charlotte shows concentrated demand for contractor-grade equipment serving residential and commercial building booms.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria require precision HVLP systems for EV manufacturing paint shops. ECHA REACH compliance and EU Green Deal emission targets enforce stricter coating application standards than federal German baselines. The Stuttgart industrial cluster anchors electrostatic system demand for metal fabrication and automotive component finishing.
China
Shipbuilding yards in Jiangsu and Shandong provinces drive high-pressure protective coating equipment demand for maritime construction. MIIT industrial upgrading directives accelerate smart spray system adoption in state-owned manufacturing facilities. The Yangtze River Delta manufacturing belt concentrates precision finishing equipment procurement for electronics and automotive export production.
India
Infrastructure projects in Maharashtra and Gujarat generate contractor fleet expansion for highway and public building coatings. BIS certification requirements for industrial equipment create compliance barriers for imported systems. The Delhi-Mumbai Industrial Corridor anchors demand for mid-tier airless equipment serving commercial construction and manufacturing facility expansion.
Japan
Automotive refinishing in Aichi Prefecture maintains stringent transfer efficiency requirements under METI industrial efficiency guidelines. JIS standards for coating equipment quality exceed regional baselines, favoring precision-engineered HVLP and electrostatic systems. The Nagoya industrial cluster sustains replacement demand for high-reliability equipment in aerospace and automotive component finishing.
Paint Sprayer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established equipment houses commanding premium positioning in regulated end-uses while Asian fabricators capture volume in price-sensitive contractor tiers. The vendor base concentrates around three strategic archetypes: integrated fluid-handling conglomerates with service network density, precision atomization specialists serving automotive and aerospace niches, and regional equipment assemblers competing on first-cost positioning. Consolidation pressure is accelerating through vertical integration into pump manufacturing and strategic partnerships for IoT-enabled service platforms.
Among North American and European integrated specialists, Graco Inc. and Wagner Group GmbH occupy positions anchored by continental service infrastructure and recurring revenue attachment through maintenance contracts. Anest Iwata Corp. exemplifies the precision-specialist archetype, with its corporate designation indicating Japanese engineering heritage and focused competence in atomization technology. These three represent contrasting pathways to defensibility: scale-driven service density, regional distribution lock-in, and technical specialization in high-specification segments.
| Leading Market Players |
|---|
| Graco Inc. |
| Wagner Group GmbH |
| Anest Iwata Corp. |
| 3M Co. |
| SATA GmbH & Co. KG |
| Fuji Industrial Spray Equipment Ltd. |
| Nordson Corporation |
| Titan Tool |
| Apollo Sprayers Intl. Inc. |
| Others |
Value Network & Pricing Analysis
Captive pump manufacturing in the United States and Germany anchors pricing power for integrated equipment houses serving EPA-regulated end-uses, while outsourced fabrication in Asian contract facilities feeds price-competitive tiers for emerging market contractors. This integration choice separates premium HVLP and electrostatic systems with embedded service contracts from commoditized airless units competing on first-cost positioning.
Pricing Analysis
Capacity additions in China are reshaping price floors for entry-level airless equipment, compressing margins for regional assemblers dependent on steel pump housings. Pricing stratifies across premium, standard, and economy tiers where certification grade and after-sales bundling drive differentiation. Cost compression in mid-tier segments intensifies because aluminum pressure vessel fabrication faces commodity volatility. DIY enthusiasts exhibit highest price sensitivity while automotive refinish shops prioritize transfer efficiency compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision-machined pump components sourced from Germany and Japan, where JIS and DIN quality standards exceed regional baselines. Manufacturing draws from China for cast housings, Taiwan for electronic control modules, and Italy for specialized spray tips. Tariff exposure on steel and aluminum inputs creates margin pressure during trade policy shifts. Distribution runs through authorized dealer networks for contractor-grade equipment and mass retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where infrastructure renewal and environmental compliance are concentrating demand toward premium specifications with embedded service contracts.
For Market Incumbents: Extend service network density in the United States Southeast to capture recurring revenue from infrastructure contractors facing accelerated replacement timelines. Deepen backward integration into pump manufacturing to defend margins against steel and aluminum commodity volatility. Anchor positioning through California CARB-compliant inventory stratification that segments national distribution by regulatory destination. For New Entrants and Emerging Players: Enter via furniture finishing and custom woodworking segments where HVLP penetration remains below saturation and established service infrastructure is sparse. Target mid-sized commercial contractors in India and Southeast Asia seeking lease-to-own arrangements with bundled training. Build go-to-market through equipment rental platforms that reduce capital barriers for project-based operators. For Investors and Strategic Acquirers: Roll-up economics work for precision atomization specialists because automotive and aerospace coating requirements concentrate demand among engineering-capable vendors with certified service networks. Favor targets with captive manufacturing in Germany or Japan and established aftermarket parts revenue. Watch EPA state-level mandate expansion beyond California and New York as inflection signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Service Platform Launch | Embedded sensors in contractor-grade units anchor recurring maintenance contracts beyond warranty periods. |
| Backward Integration into Pump Manufacturing | In-house production of pressure vessels defends margins against steel and aluminum commodity volatility. |
| California CARB-Compliant Product Line Expansion | State-specific inventory stratification captures premium positioning in the United States' strictest emission market. |
| Lease-to-Own Fleet Program Development | Financing flexibility attracts mid-sized contractors managing cash flow across infrastructure project cycles. |
| Furniture Finishing Segment Penetration | Below-saturation HVLP adoption in custom woodworking creates white-space opportunity with lower competitive intensity. |
Research Methodology
Multiple input streams — primary interviews with equipment distributors and aftermarket service heads, regulatory filing analysis, and customs trade records — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned commercial painting contractors, automotive refinish shop operators, industrial facility maintenance directors, and OEM procurement teams at equipment manufacturers. Secondary validation drew from EPA enforcement databases, California Air Resources Board compliance filings, SEC 10-K disclosures from listed equipment houses, and infrastructure spending appropriations tracked through federal procurement systems.
Segment-level volume and value outputs were reconciled across product type, end user archetype, technology tier, and application vertical throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance deadline mapping, and infrastructure investment flow projections. Industry-specific forecast inputs included bridge rehabilitation timeline acceleration under federal infrastructure legislation and state-level environmental mandate adoption curves.
Inputs from regulatory agencies and equipment manufacturer disclosures were available through the study window; gaps in private contractor fleet composition data introduce uncertainty bands around commercial segment sizing. Forecasts reflect assumptions about compliance deadline adherence and infrastructure appropriation execution that could shift with political or macroeconomic conditions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market