
 Qatar Paints and Coatings Market | 2026-2036
Qatar Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Paints and Coatings Market Analytics
Water-based polymer dispersion technology is rewriting formulation priorities across Qatar's coatings value chain. Jotun leverages its marine-grade R&D heritage to dominate protective coatings for offshore and industrial infrastructure. Asian Paints Berger anchors its position through localized production and distribution networks serving residential and commercial construction. Akzo Nobel N.V. differentiates via powder coating capabilities aligned with Qatar's sustainability mandates.
Paints and coatings are liquid or solid film-forming compositions comprising resins, pigments, solvents, and additives that cure to provide protective, decorative, or functional surfaces on substrates. Acrylic formulations lead residential and commercial applications due to UV stability and color retention in Qatar's extreme desert climate. Epoxy systems represent the fastest-growing technology segment driven by oil and gas infrastructure maintenance and marine coating requirements. Water-based technology commands expanding share as GSAS certification and Ministry of Municipality and Environment regulations restrict solvent-borne volatile organic compound emissions.
Qatar's Ministry of Municipality and Environment enforces GSAS green building standards that mandate low-emission coating systems for public and private developments. The Qatar General Organization for Standardization (QS) aligns product specifications with Gulf Standardization Organization benchmarks for chemical safety and performance testing. Construction stakeholders must monitor regulatory tightening on VOC thresholds and carbon footprint disclosure requirements. Procurement teams should evaluate supplier compliance certification depth before committing to long-term coating supply agreements.
Market Dynamics
Water-based polymer dispersion technology is compressing solvent-borne formulation margins while GSAS certification mandates reconfigure procurement specifications across Qatar's construction pipeline.
Growth Catalysts
- GSAS Green Building Codes:Qatar's Ministry of Municipality and Environment mandates low-VOC coating systems for public and private developments, creating guaranteed demand pull for compliant water-based technologies.
- Oil and Gas Infrastructure Maintenance:Offshore platforms and downstream facilities require high-performance protective coatings, with epoxy systems capturing expanding specification share in marine and industrial applications.
- Lusail and Doha Mega-Projects:Concentrated construction activity in these urban centers generates sustained demand for decorative and protective coatings across residential, commercial, and hospitality verticals.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment cost fluctuations compress formulation margins and complicate long-term contract pricing for water-based architectural coatings.
- Specialty Resin Import Dependence:Qatar lacks domestic epoxy and polyurethane resin production, exposing coating manufacturers to supply chain disruptions and currency risk.
- Extreme Desert Climate Performance Thresholds:UV degradation and thermal cycling requirements exceed standard formulation capabilities, limiting technology transfer from temperate-climate markets.
Strategic Opportunities
- Al Wakrah Industrial Zone Expansion:Manufacturing and logistics facility construction creates demand for industrial floor coatings, tank linings, and corrosion protection systems.
- Powder Coating Technology Convergence:Electrostatic application methods combined with zero-VOC formulations align with sustainability mandates while reducing overspray waste in metal fabrication.
- Digital Specification Platforms:Building information modeling integration enables real-time coating selection and quantity estimation, streamlining procurement workflows for EPC contractors.
Industry Challenges
- GSAS Certification Timeline Compression:Third-party testing and documentation requirements extend product qualification cycles, delaying market entry for new formulations.
- Specialized Applicator Skill Scarcity:Spray application of high-solids epoxy and polyurethane systems demands certified technicians, with training capacity lagging project ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Paints and Coatings Market |
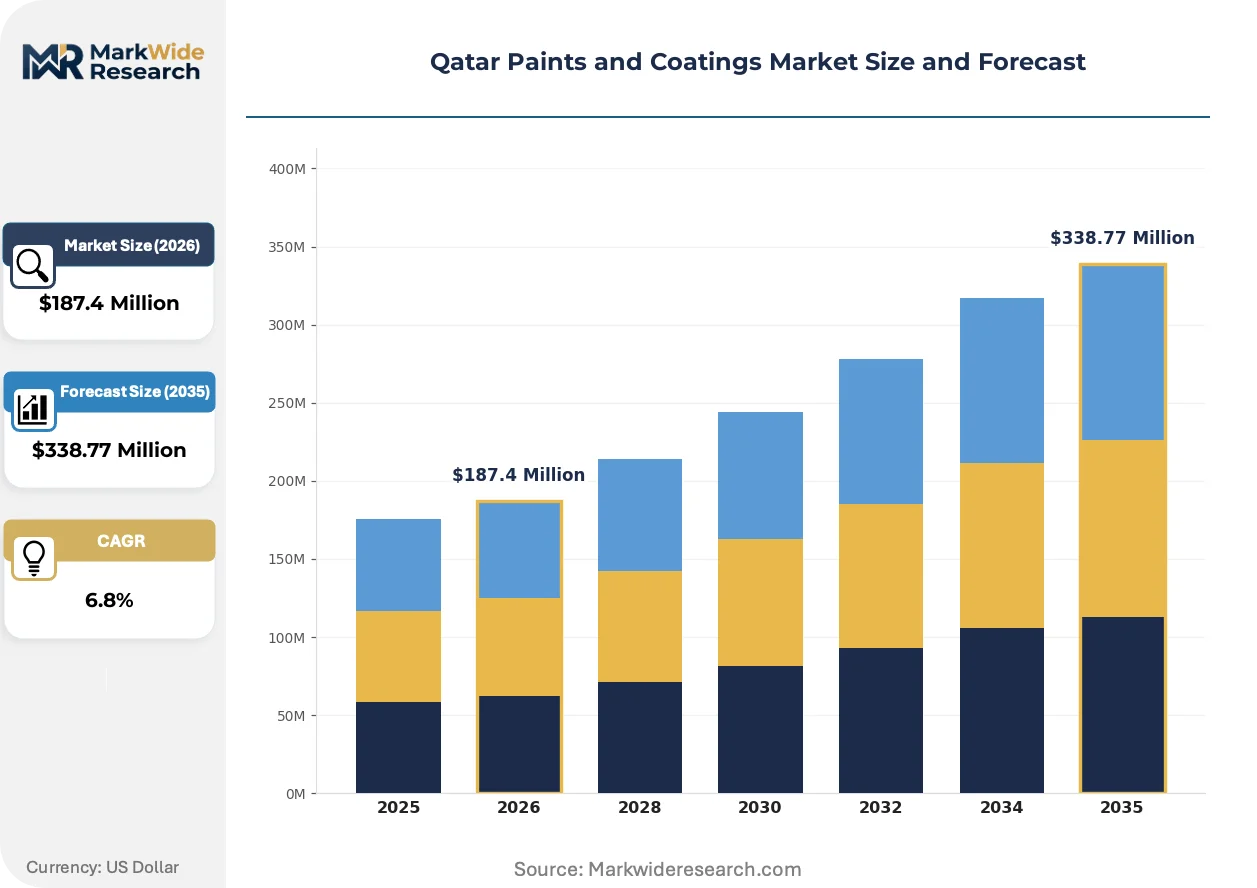
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Alkyd, Polyurethane Application: Construction, Automotive, Marine, Industrial End User: Residential, Commercial, Institutional, Infrastructure Technology: Water-Based, Solvent-Based, Powder Coating, UV-Curing |
| Companies Covered | Jotun, Asian Paints Berger, Akzo Nobel N.V., National Paints Factories Co. Ltd, Jazeera Paints, Axalta Coating Systems, Caparol, Ritver Paints & Coatings, Hempel A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Paints and Coatings Market Evolving Landscape
Formulation digitization, regulatory tightening on embodied carbon, and procurement platform adoption are restructuring how coating specifications flow from architect to applicator across Qatar's project pipeline.
Smart coating systems incorporating embedded sensors and self-healing chemistries are digitizing asset management protocols for offshore oil and gas infrastructure. Operators including QatarEnergy deploy these technologies to monitor corrosion progression in real time, reducing inspection frequency and enabling predictive maintenance scheduling. The data layer is digitizing traditional reactive coating replacement cycles into condition-based interventions.
Qatar General Organization for Standardization alignment with Gulf Standardization Organization benchmarks is tightening chemical safety disclosure requirements for imported coating formulations. Manufacturers must now submit comprehensive hazard communication documentation and performance testing data prior to product registration. Industrial protective coatings face the steepest compliance burden due to higher solvent content and specialized additive packages.
Consolidated procurement through master service agreements is displacing spot purchasing for major infrastructure developers. Lusail City contractors now specify coating systems through pre-qualified supplier panels, compressing vendor count and standardizing performance warranties. This concentration is most visible in commercial high-rise construction, where repeatability and supply security override unit cost minimization.
Qatar Paints and Coatings Market Segmentation
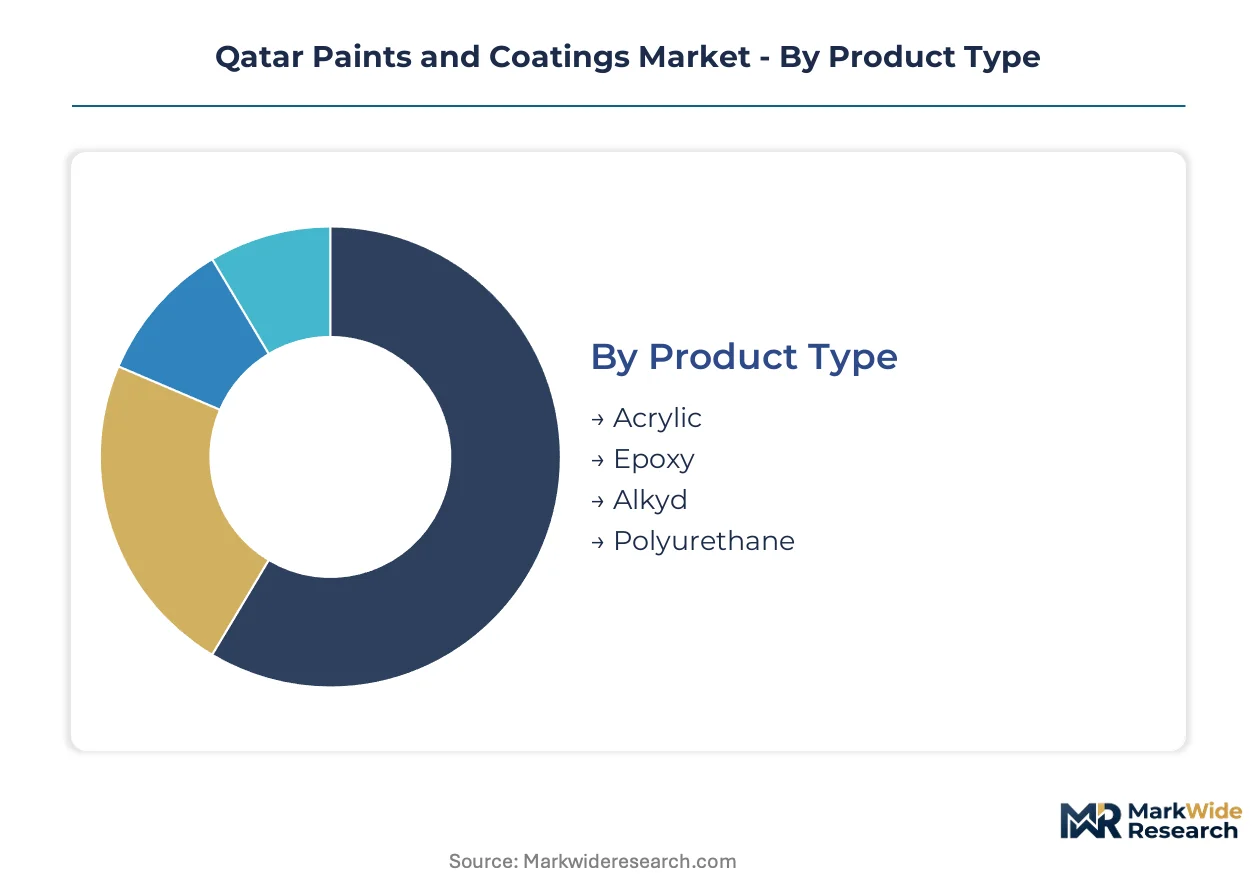
Segmentation reveals how Qatar's coating procurement diverges across project types and compliance tiers. Each dimension exposes distinct specification logics—from GSAS-mandated low-VOC technologies to marine-grade protective systems for offshore infrastructure.
Product Type:
Cost tier differentiation separates commodity architectural coatings from premium industrial formulations serving Qatar's energy and marine sectors.
- Acrylic:Water-dispersed thermoplastic resins deliver UV stability and color retention critical for Doha's extreme desert exposure. Residential towers and commercial facades in Lusail specify acrylic emulsions for exterior durability under thermal cycling stress.
- Epoxy:Two-component thermoset systems cure into dense, chemically resistant films. Offshore platforms and downstream facilities across Ras Laffan Industrial City mandate epoxy primers and topcoats for corrosion protection in saline atmospheres.
- Alkyd:Oil-modified polyester resins retain solvent-borne application characteristics for metal substrates. Decorative trim and maintenance repainting in established Doha districts still specify alkyd enamels where rapid dry-to-touch matters.
- Polyurethane:Isocyanate-cured films balance abrasion resistance with aesthetic finish. Industrial floors and tank exteriors in Al Wakrah manufacturing zones deploy polyurethane systems for mechanical durability.
Acrylic holds installed capacity. Epoxy is rotating up the share rankings.
Application:
Volume concentration tracks Qatar's construction pipeline and energy infrastructure maintenance cycles.
- Construction:Architectural coatings for vertical and horizontal surfaces dominate procurement tonnage. Mega-projects in Lusail and Msheireb Downtown Doha drive decorative coating specifications across residential, hospitality, and retail verticals.
- Industrial:Protective systems for manufacturing facilities, storage tanks, and processing equipment. Al Wakrah Industrial Zone expansion and Ras Laffan complex maintenance generate recurring demand for high-performance anti-corrosive formulations.
- Marine:Immersion-grade and atmospheric-zone coatings for vessels and offshore structures. QatarEnergy fleet operations and port infrastructure at Hamad Port require specialized fouling control and cathodic protection compatibility.
- Automotive:OEM and refinish coatings for vehicle assembly and repair. Limited domestic manufacturing concentrates demand in aftermarket refinishing and commercial fleet maintenance segments.
Construction absorbs the largest volume share. Industrial applications are climbing the fastest.
End User:
Customer type determines specification authority and compliance stringency across Qatar's built environment.
- Residential:Individual and developer-driven housing units from luxury villas to worker accommodation. Lusail's waterfront residential districts and Pearl-Qatar compounds prioritize aesthetic finish and warranty-backed durability.
- Commercial:Office towers, retail centers, and hospitality assets where brand visibility drives color precision. West Bay business district and Mall of Qatar developments specify coating systems through design-build contracts with performance guarantees.
- Institutional:Government buildings, healthcare facilities, and educational campuses under Ministry of Municipality and Environment oversight. GSAS certification mandates enforce low-VOC requirements across this segment.
- Infrastructure:Transportation, utilities, and public works projects with extended asset lifecycles. Doha Metro expansion and highway corridor maintenance specify protective coatings for concrete and steel substrates.
Commercial projects command specification authority. Institutional procurement is tightening compliance thresholds fastest.
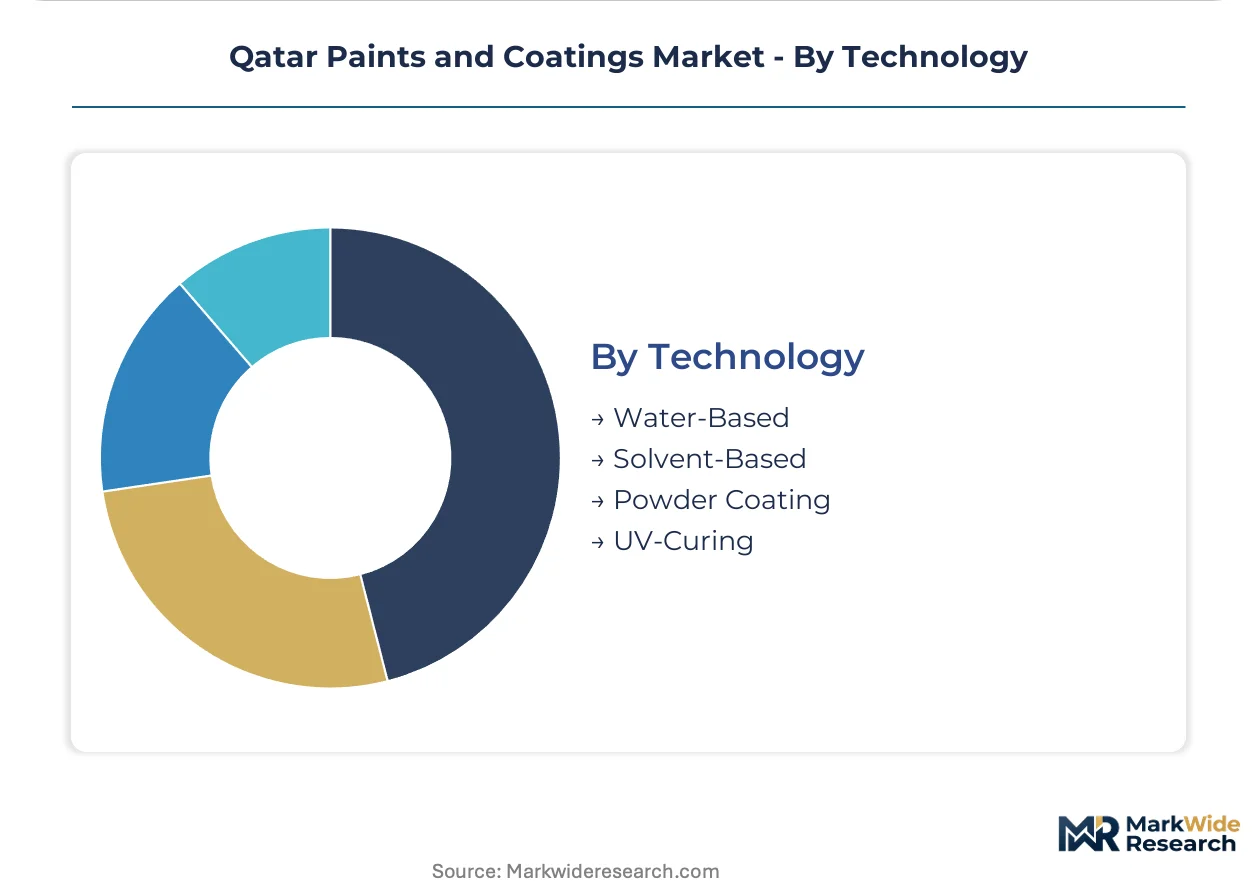
Technology:
Maturity curves separate established application methods from emerging zero-emission platforms.
- Water-Based:Polymer dispersions in aqueous carriers meeting GSAS VOC thresholds. Construction sector procurement in Doha and Lusail is compressing solvent-borne share through green building code enforcement.
- Solvent-Based:Traditional alkyd and epoxy formulations with higher solids for industrial durability. Marine and heavy industrial applications retain solvent-borne specifications where film build and chemical resistance override emission concerns.
- Powder Coating:Thermoplastic and thermoset powders applied electrostatically with zero liquid waste. Metal fabrication for stadium infrastructure and architectural metalwork adopts powder systems for overspray elimination and GSAS alignment.
- UV-Curing:Photoinitiator-activated instant cure systems for specialized industrial lines. Limited adoption in Qatar concentrates in furniture manufacturing and electronics coating operations.
Solvent-based retains industrial installed base. Water-based technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based coating manufacturers export water-based architectural systems to Qatar's Lusail and Doha construction corridors, while Saudi producers supply solvent-borne industrial formulations for Ras Laffan energy infrastructure.
United Arab Emirates
Sharjah and Dubai industrial zones manufacture acrylic emulsions and epoxy primers for cross-border shipment to Qatar's mega-project pipeline. The UAE's Ministry of Climate Change and Environment enforces product safety standards aligned with Gulf Standardization Organization benchmarks. Jebel Ali port clusters coordinate bulk coating logistics serving Doha and Lusail development schedules.
Saudi Arabia
Eastern Province petrochemical complexes produce specialty resins and high-solids formulations for Qatar's offshore maintenance cycles. The Saudi Standards, Metrology and Quality Organization mandates chemical disclosure documentation for exported coating systems. Jubail Industrial City coating plants supply epoxy and polyurethane systems to Ras Laffan corrosion protection programs.
India
Gujarat and Maharashtra coating manufacturers export decorative emulsions and industrial primers to Qatar's residential and commercial construction verticals. The Bureau of Indian Standards certifies product quality for Gulf-bound shipments under harmonized testing protocols. Mumbai port operations consolidate containerized coating exports for Doha distribution networks.
Germany
Bavaria and North Rhine-Westphalia chemical producers supply powder coating resins and UV-curing additives to Qatar's metal fabrication and stadium infrastructure sectors. The Federal Institute for Risk Management monitors chemical safety compliance for Middle East exports. Cologne-based logistics hubs coordinate specialty coating ingredient shipments to Doha applicators.
Qatar Paints and Coatings Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers anchored by multinational formulators, regional production specialists, and import-dependent distributors. European and Asian multinationals dominate protective coatings through marine-grade R&D heritage and localized manufacturing investments. Regional Arab producers compete on logistics proximity and Gulf Standardization Organization certification speed. Competitive moves concentrate on GSAS compliance documentation acceleration and water-based formulation portfolio expansion.
Within the multinational tier, Jotun and Akzo Nobel N.V. exemplify integrated coating suppliers with marine and industrial specialization. Asian Paints Berger occupies a position bridging regional production scale with localized distribution density. These three entities represent divergent strategic archetypes: Nordic marine-grade expertise, Dutch powder coating technology, and Indian subcontinent manufacturing-to-market integration.
| Leading Market Players |
|---|
| Jotun |
| Asian Paints Berger |
| Akzo Nobel N.V. |
| National Paints Factories Co. Ltd |
| Jazeera Paints |
| Axalta Coating Systems |
| Caparol |
| Ritver Paints & Coatings |
| Hempel A/S |
| Others |
Value Network & Pricing Analysis
Titanium dioxide feedstock volatility compresses formulation margins and dictates tier spreads across Qatar's coating procurement, forcing buyers toward long-term resin contracts while suppliers segment pricing by GSAS compliance grade.
Pricing Analysis
The water-based versus solvent-borne technology-generation pricing gap spans three distinct tiers: premium GSAS-certified water-based systems command specification premiums for institutional procurement, mid-grade water-based formulations serve commercial construction through volume discounts, and legacy solvent-borne products retreat to marine and industrial niches with eroding margins. Price differentiation rests on certification depth and resin import exposure, with epoxy systems bearing the steepest cost compression due to specialty resin currency risk. Pricing pressure intensifies in architectural segments as UAE-based acrylic emulsion imports expand. Residential developers exhibit highest price sensitivity, while QatarEnergy offshore maintenance contracts tolerate premium protective coating costs.
Supply Chain Analysis
Upstream titanium dioxide and epoxy resin feedstock concentration in Saudi Arabia's Eastern Province and India's Gujarat state anchors Qatar's coating value chain, with specialty polyurethane precursors sourced from Germany's North Rhine-Westphalia chemical cluster. Raw material dependencies center on pigment intermediates, isocyanate curing agents, and acrylic monomer streams. Single-source vulnerability concentrates in high-performance marine resin supply from Jubail Industrial City. Distribution runs through Jebel Ali port consolidation hubs serving Doha and Lusail applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's paints and coatings market functions as a service-attach opportunity where predictive maintenance contracts and coating inspection subscriptions expand faster than standalone product sales, particularly for offshore asset operators.
For Market Incumbents: Harden GSAS certification documentation capabilities to compress product qualification cycles and defend specification share against emerging UAE-based water-based specialists. Deepen backward integration into acrylic emulsion production through captive supply agreements with Saudi resin producers, mitigating currency exposure on imported feedstocks. For New Entrants and Emerging Players: Build out powder coating application service capabilities targeting Al Wakrah Industrial Zone metal fabrication demand, where zero-VOC compliance and overspray elimination create specification advantages. Penetrate the institutional segment through GSAS pre-certification partnerships with Ministry of Municipality and Environment-approved testing laboratories. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional production specialists with established Gulf Standardization Organization certification speed and localized distribution density. Long-term viability hinges on water-based formulation transition completion and digital specification platform integration. Watch for Qatar General Organization for Standardization alignment with EU chemical disclosure benchmarks as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GSAS Certification Acceleration | Compresses product qualification timelines for Ministry of Municipality and Environment compliance. |
| Water-Based Formulation Expansion | Aligns portfolio with Lusail and Doha green building code enforcement. |
| Powder Coating Technology Investment | Captures stadium infrastructure and architectural metalwork zero-VOC demand. |
| Resin Supply Backward Integration | Reduces exposure to Saudi and Indian specialty chemical currency volatility. |
| Digital Specification Platform Partnership | Integrates coating selection workflows with EPC contractor building information modeling systems. |
Research Methodology
A spread of perspectives from coating formulators, EPC procurement managers, Ministry of Municipality and Environment compliance officers, and industrial applicator technicians converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through Qatar General Organization for Standardization product registration databases, Gulf Standardization Organization technical committee documentation, and customs import records for titanium dioxide and epoxy resin shipments. Bottom-up project pipeline assessment triangulated against top-down construction sector expenditure tracking.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, application vertical, end-user category, and technology platform dimensions. CAGRs were derived from fitted growth curves applied to construction sector capex schedules and energy infrastructure maintenance cycles. Industry-specific forecast inputs included GSAS certification penetration rates and water-based technology substitution elasticities.
Stress conditions across titanium dioxide price spikes, Saudi riyal exchange rate movements, and GSAS timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and mega-project completion schedules. Cross-checking against Qatar Central Bank construction sector credit data and QatarEnergy maintenance expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Water Color Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market