
 Middle East & Africa Corrosion Protection Coating Market | 2026-2036
Middle East & Africa Corrosion Protection Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Corrosion Protection Coating Market Analytics
REACH compliance pressure from European offtakers is decoupling procurement specifications across Middle East & Africa energy projects from legacy solvent-based norms. AkzoNobel leverages its water-based epoxy portfolio to capture refinery maintenance contracts in the Arabian Gulf. Jotun A/S anchors its position through marine coating dominance at Port of Durban and Suez Canal transit fleets. Hempel A/S specializes in high-temperature pipeline solutions for Nigerian crude gathering systems.
Corrosion protection coatings are barrier-formulating systems, typically comprising epoxy resins, zinc-rich primers, or polyurethane binders, engineered to inhibit electrochemical degradation of steel and concrete substrates exposed to saline, acidic, or high-humidity environments. These formulations cure through ambient-temperature crosslinking or forced-heat polymerization to achieve adhesion ratings exceeding 15 MPa on blast-cleaned surfaces, primarily serving asset life extension in hydrocarbon extraction, maritime transport, and coastal infrastructure. Epoxy formulations occupy the dominant volume position due to chemical resistance requirements in sour gas processing facilities, while nano coating technology captures premium pricing from operators seeking thin-film cathodic protection in subsea riser applications. Water-based technology is gaining fastest in UAE and South African manufacturing plants responding to municipal discharge regulations.
Saudi Arabia's SFDA and MEE enforce coating VOC thresholds through product registration mandates, while South Africa's Department of Forestry, Fisheries and the Environment applies ambient air quality standards to Durban-Richards Bay industrial coating yards. Nigeria's Department of Petroleum Resources mandates third-party coating inspection for offshore structures, creating certification barriers for uncertified applicators. Stakeholders must monitor how SFDA harmonization with EU REACH testing protocols reshapes import approval timelines and local formulation requirements.
Market Dynamics
Saudi Arabia's SFDA and MEE are tightening volatile organic compound thresholds on solvent-based formulations, forcing a wholesale reformulation pivot across Arabian Gulf coating supply chains while Nigerian offshore operators accelerate third-party inspection mandates.
Growth Catalysts
- Epoxy resin chemistry:Chemical resistance requirements in sour gas processing facilities across Saudi Arabia's industrial cities drive specification upgrades for high-performance barrier systems.
- SFDA product registration mandates:Regulatory harmonization with EU REACH testing protocols creates certification premiums for compliant importers serving UAE and Saudi refinery maintenance cycles.
- Subsea riser applications:Nano coating technology captures thin-film cathodic protection demand from offshore platform operators in the Gulf of Guinea seeking asset life extension.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and polyurethane binder input costs fluctuate with crude oil derivatives, compressing margin stability for formulators serving Nigerian pipeline corridors.
- Applicator certification concentration:Nigeria's Department of Petroleum Resources mandates third-party coating inspection, creating bottlenecks where certified applicator pools remain thin in the Niger Delta.
- Water-based performance gaps:Ambient-temperature curing limitations in high-humidity environments restrict substitution rates for solvent-based primers in critical offshore structures.
Strategic Opportunities
- South African manufacturing plants:Municipal discharge regulations in Durban-Richards Bay industrial coating yards open conversion contracts for water-based technology suppliers.
- Port of Durban marine fleets:Suez Canal transit vessel maintenance cycles create recurring demand for high-temperature pipeline-compatible marine coating systems.
- MEE-SFDA alignment:Anticipated regulatory convergence on VOC thresholds positions early-compliant formulators for accelerated import approval timelines across UAE and Saudi Arabia.
Industry Challenges
- Blast-cleaned surface preparation:Adhesion rating requirements exceeding 15 MPa demand skilled applicator labor that remains scarce in Nigeria's offshore contractor market.
- Heat polymerization infrastructure:Forced-cure coating systems require capital-intensive oven installations that smaller maintenance yards in South Africa's industrial zones struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Corrosion Protection Coating Market |
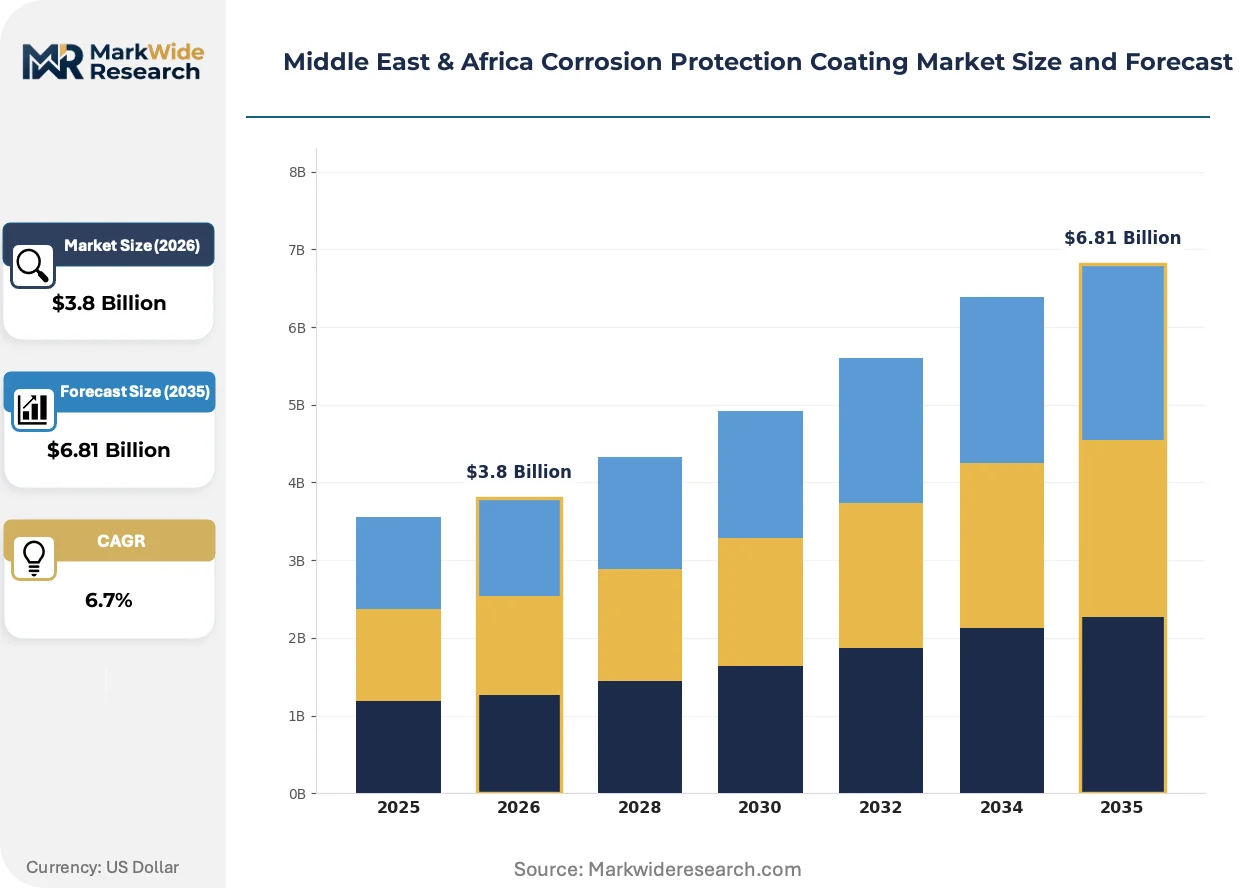
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Zinc, Acrylic Application: Marine, Infrastructure, Oil & Gas, Automotive End User: Construction, Manufacturing, Energy, Transportation Technology: Water-Based, Solvent-Based, Powder Coating, Nano Coating |
| Companies Covered | Sherwin-Williams Company, Carboline, AkzoNobel, BASF SE, RPM International Inc., Jotun A/S, Hempel A/S, Sika AG, PPG Industries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Corrosion Protection Coating Market Evolving Landscape
Formulation chemistry and procurement specifications across Middle East & Africa energy projects are decoupling from legacy solvent-based norms as environmental enforcement tightens and buyer technical standards elevate.
Water-based epoxy technology is consolidating its position in refinery maintenance applications as Saudi Arabia's SFDA enforces registration mandates aligned with EU REACH protocols. Arabian Gulf operators specify these systems for atmospheric storage tanks and process equipment where ambient curing suffices. The shift is compressing demand for high-VOC alkyd primers in non-immersion service.
South Africa's Department of Forestry, Fisheries and the Environment applies ambient air quality standards to industrial coating yards, compelling Durban-Richards Bay applicators to retrofit spray booths and solvent recovery systems. Formulators serving this market must document emission profiles to maintain yard authorization. The enforcement pattern is spreading to UAE municipal jurisdictions.
Buyers in Nigeria's offshore sector now bundle coating procurement with third-party inspection contracts, unbundling traditional supply arrangements. Department of Petroleum Resources mandates drive this specification bundling, favoring formulators with in-house NACE-certified inspection capabilities or established partnerships with accredited verification bodies. The model concentrates contract awards among integrated service providers.
Middle East & Africa Corrosion Protection Coating Market Segmentation
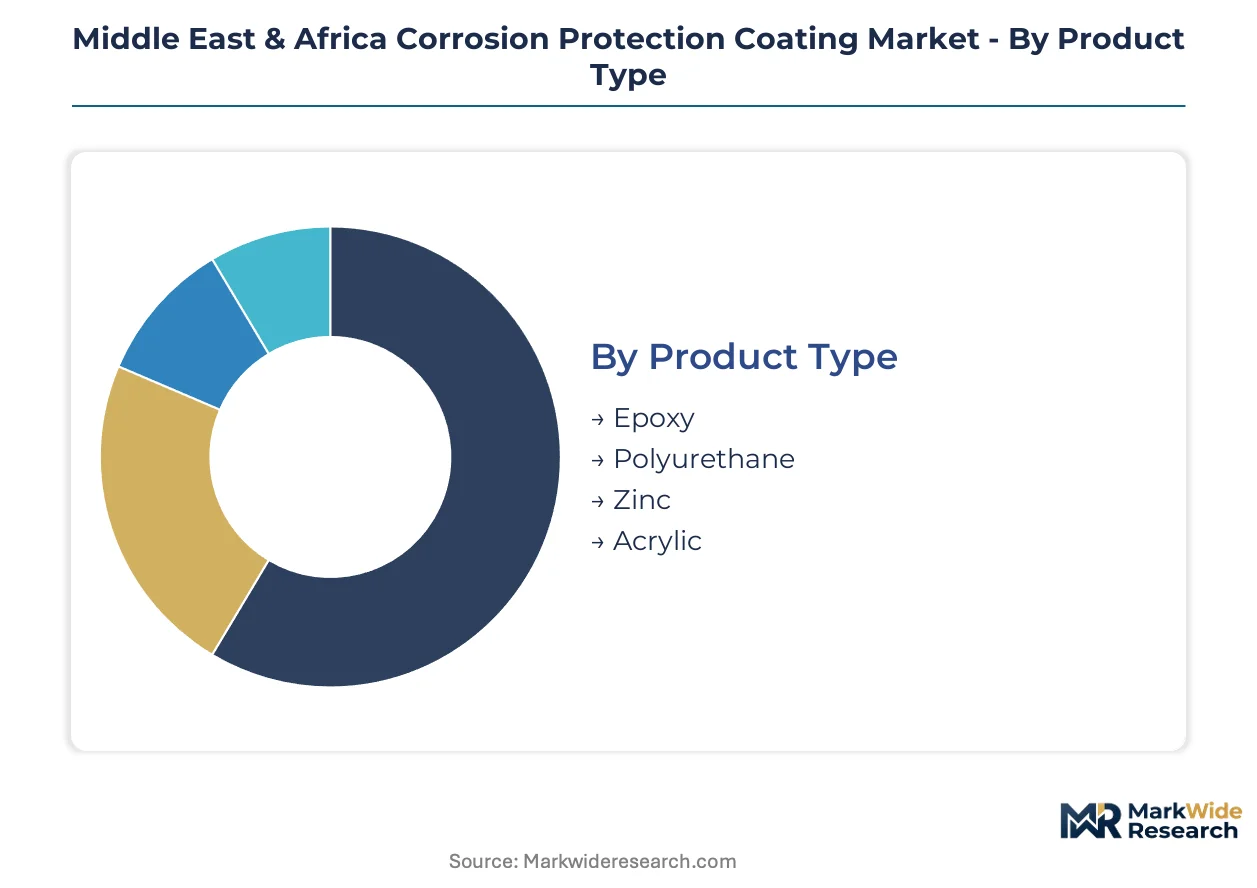
Corrosion protection coating procurement across the Middle East & Africa fragments across four structural dimensions. Product chemistry, application environment, end-use sector, and formulation technology each create distinct specification regimes that reshape supplier positioning and margin capture.
Product Type:
Supply concentration in epoxy resin manufacturing anchors procurement patterns across Arabian Gulf industrial cities.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or novolac backbones deliver chemical resistance against hydrogen sulfide and carbon dioxide in sour gas processing facilities. Saudi Aramco maintenance specifications favor these formulations for above-ground storage tanks and process vessels across Jubail and Yanbu industrial corridors.
- Polyurethane:Aliphatic and aromatic isocyanate-cured binders provide UV stability and abrasion resistance for exterior structural steel. Demand concentrates in UAE infrastructure projects where architectural finish requirements combine with coastal salt exposure.
- Zinc:Inorganic and organic zinc-rich primers deliver sacrificial cathodic protection through metallic zinc loading above 80% by weight. Nigerian offshore platform specifications mandate these systems for splash zone protection.
- Acrylic:Thermoplastic emulsion or solvent-borne systems offer rapid drying and color retention for atmospheric service. South African manufacturing plants specify water-based acrylics for non-critical structural elements.
Today's leader: Epoxy. Tomorrow's challenger: Polyurethane.
Application:
Cost tier stratification separates specification-grade marine systems from commodity infrastructure coatings.
- Marine:Immersion-grade epoxy and polyurethane systems engineered for permanent seawater exposure. Port of Durban dry-dock operators and Suez Canal transit fleets drive recurring maintenance demand for anti-fouling and ballast tank protection.
- Infrastructure:Atmospheric protection for bridges, pipelines, and coastal structures where blast-cleaned surface preparation achieves 15 MPa adhesion ratings. Nigerian Niger Delta pipeline corridors and Saudi industrial city expansions concentrate procurement volume.
- Oil & Gas:High-temperature resistant formulations for refinery process equipment and subsea production systems. SFDA product registration mandates aligned with EU REACH protocols filter supplier eligibility for Arabian Gulf upstream contracts.
- Automotive:Electrocoat primer and topcoat systems for vehicle manufacturing and aftermarket refinishing. South African assembly plants and UAE commercial vehicle operations sustain niche demand.
Marine commands premium pricing. Oil & Gas delivers volume scale.
End User:
Customer type determines certification burden and procurement cycle length.
- Construction:Specifiers of protective coatings for commercial buildings, industrial facilities, and civil infrastructure. Municipal discharge regulations in South African industrial zones filter water-based technology adoption.
- Manufacturing:In-house maintenance departments and OEM coating operations. Durban-Richards Bay industrial coating yards retrofit spray booths to comply with ambient air quality standards.
- Energy:Upstream oil and gas operators, power generation utilities, and renewable energy developers. Nigeria's Department of Petroleum Resources mandates third-party coating inspection for offshore structures.
- Transportation:Maritime fleet operators, pipeline companies, and automotive service networks. Suez Canal transit vessel maintenance cycles create recurring demand for high-performance marine systems.
Energy concentrates contract value. Manufacturing expands fastest.
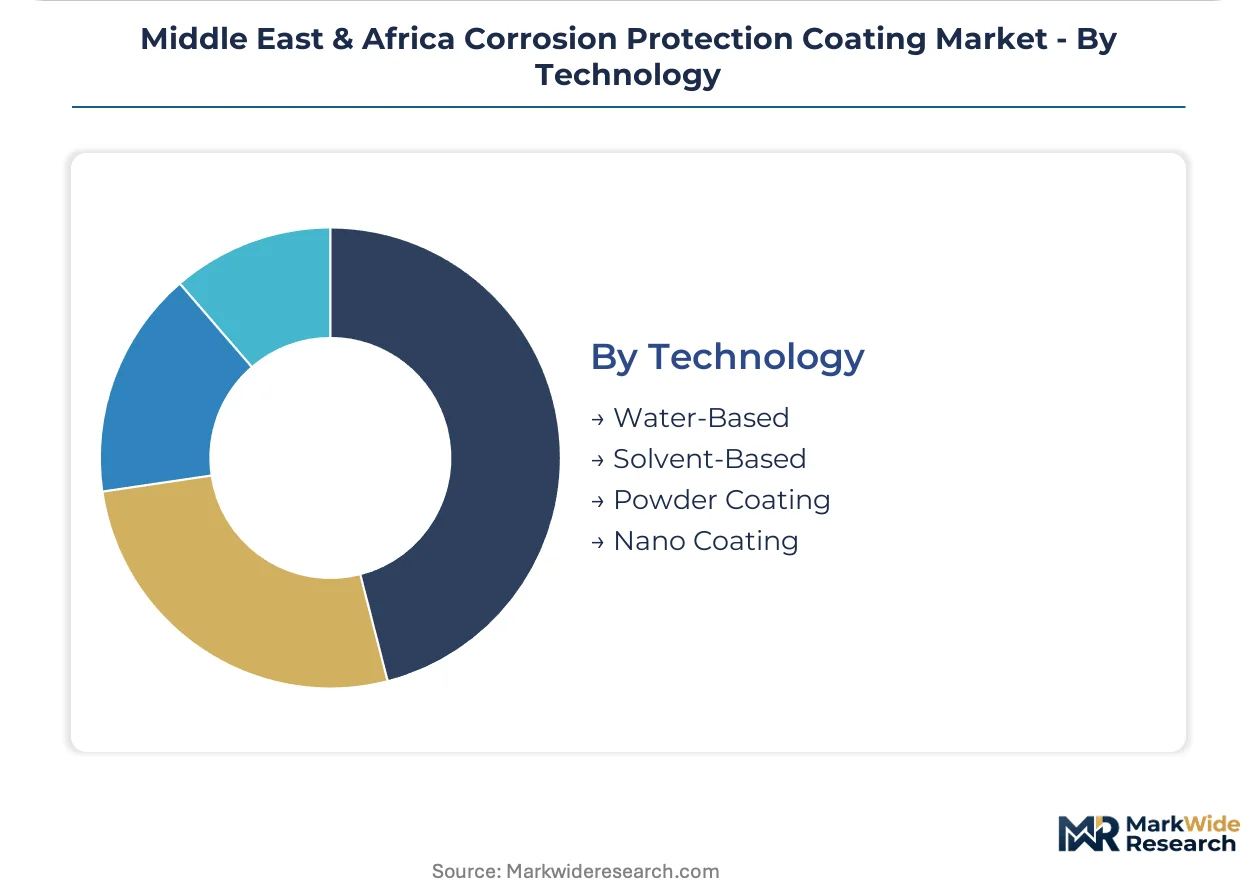
Technology:
Formulation chemistry maturity separates established solvent-based systems from emerging water-based and nano alternatives.
- Water-Based:Acrylic and epoxy emulsions with VOC content below regulatory thresholds. Saudi SFDA and MEE enforcement tightens volatile organic compound limits, accelerating refinery maintenance contract conversions.
- Solvent-Based:Conventional alkyd, epoxy, and polyurethane systems delivering ambient-temperature curing in high-humidity environments. Performance advantages persist in critical offshore structures where water-based alternatives face curing limitations.
- Powder Coating:Thermoset epoxy and polyester powders applied through electrostatic spray and heat polymerization. South African industrial zones struggle to finance capital-intensive oven installations required for forced-cure systems.
- Nano Coating:Thin-film formulations incorporating nanoparticles for enhanced barrier properties and cathodic protection. Offshore platform operators in the Gulf of Guinea specify these systems for subsea riser applications seeking asset life extension.
Solvent-Based holds installed base. Nano Coating climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial coating demand across the Middle East & Africa traces its modern lineage to the 1970s oil boom, when offshore platform construction in the Arabian Gulf created the region's first large-scale specification-grade coating procurement. Today's market spans five distinct national jurisdictions with divergent regulatory maturities and infrastructure investment cycles.
Saudi Arabia
Jubail and Yanbu industrial corridors drive epoxy formulation demand for sour gas processing facilities. SFDA product registration mandates aligned with EU REACH testing protocols filter import eligibility for refinery maintenance contractors. Eastern Province coating applicators face compressed timelines as MEE enforcement tightens VOC thresholds on solvent-based systems.
UAE
Dubai and Abu Dhabi infrastructure projects specify polyurethane systems for coastal steel protection against salt exposure. Municipal discharge regulations in industrial free zones accelerate water-based technology conversions among manufacturing plants. Jebel Ali coating yards retrofit spray booths to comply with emerging ambient air quality standards.
Nigeria
Niger Delta pipeline corridors concentrate procurement for high-temperature resistant formulations in crude gathering systems. Department of Petroleum Resources mandates third-party coating inspection for offshore structures, creating certification bottlenecks. Lagos and Port Harcourt applicators struggle with scarce NACE-certified labor pools.
South Africa
Durban-Richards Bay industrial coating yards face Department of Forestry, Fisheries and the Environment enforcement of ambient air quality standards. Manufacturing plants specify water-based acrylics for non-critical structural elements to meet municipal discharge regulations. Cape Town marine dry-dock operators drive recurring demand for anti-fouling systems.
Qatar
North Field expansion projects drive specification-grade coating procurement for offshore production systems. Ras Laffan industrial city applicators navigate product registration requirements for high-performance barrier systems. Doha-based contractors face compressed curing windows due to extreme summer humidity.
Middle East & Africa Corrosion Protection Coating Market Competitive Landscape
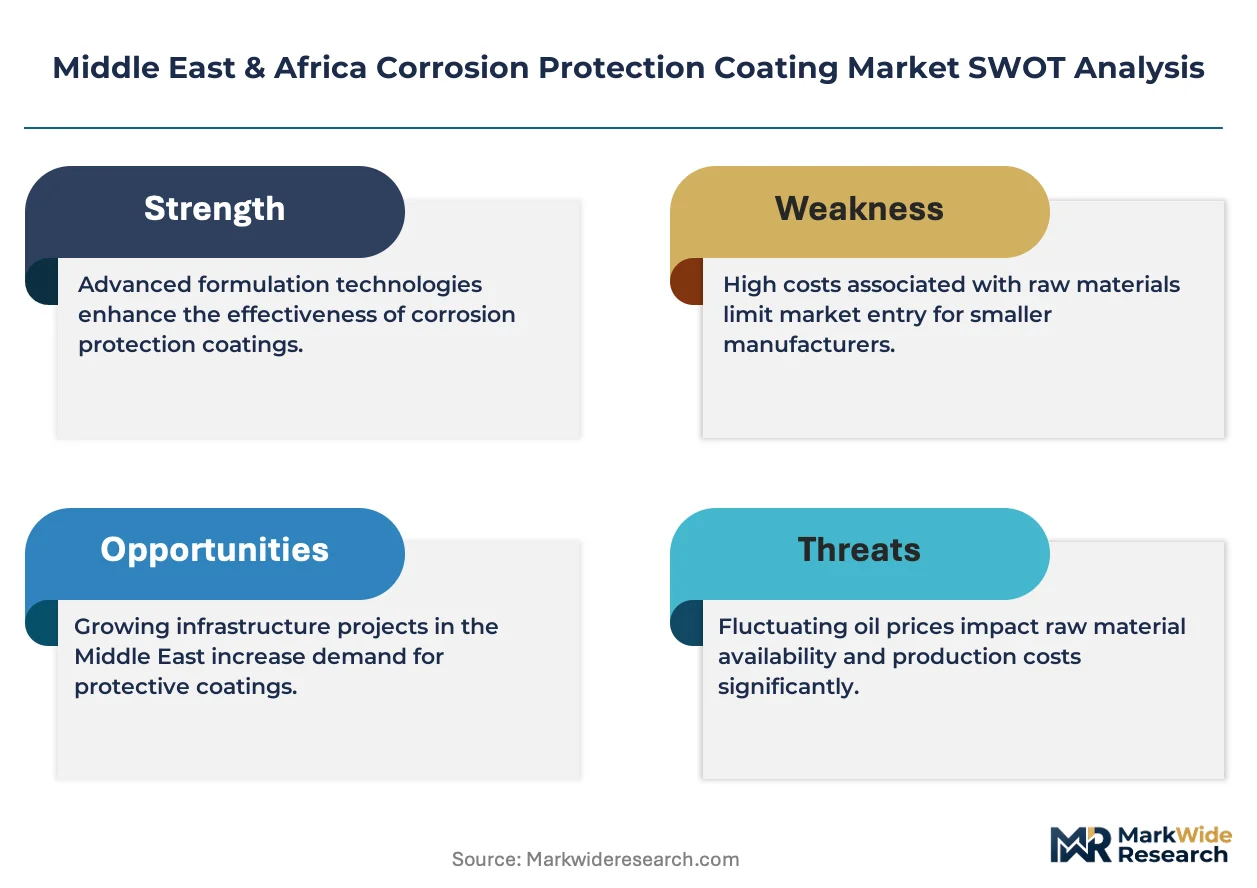
Premium-margin players sit above commodity-margin players across formulation technology tiers, with water-based epoxy specialists commanding certification premiums while solvent-based formulators compete on price. The vendor base organizes around three archetypes: integrated multinationals with in-house inspection capabilities, regional specialists in marine or high-temperature applications, and local distributors serving maintenance yards. Consolidation pressure intensifies as Nigerian bundling requirements and Saudi registration mandates favor integrated service providers. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among integrated multinationals, AkzoNobel and Jotun A/S exemplify archetypes positioned for specification-grade procurement. AkzoNobel occupies a position aligned with water-based epoxy conversions in Arabian Gulf refinery maintenance. Jotun A/S anchors the marine specialization tier through Port of Durban and Suez Canal transit fleet relationships. Hempel A/S represents the high-temperature pipeline segment serving Nigerian offshore operators.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| Carboline |
| AkzoNobel |
| BASF SE |
| RPM International Inc. |
| Jotun A/S |
| Hempel A/S |
| Sika AG |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
Epoxy resin feedstock costs originating from Saudi Aramco's petrochemical complexes flow through formulation tiers, compressing margins for solvent-based suppliers serving Nigerian pipeline contractors while elevating pricing power for water-based specialists holding SFDA registration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates nano coating specialists commanding project premiums from commodity epoxy formulators competing on volume. Price differentiation hinges on EU REACH certification tier and applicator NACE credentialing. Cost compression in standard-tier solvent-based systems is intensifying because of MEE VOC enforcement tightening input formulation costs. Nigerian offshore operators show least price sensitivity due to bundled inspection mandates, while South African manufacturing plants exhibit highest sensitivity amid municipal discharge compliance investments.
Supply Chain Analysis
Zinc metal supply rests on South African mining output and Australian concentrate exports feeding Nigerian sacrificial primer production. Epoxy resin production draws from Saudi Arabian and UAE petrochemical complexes, while polyurethane isocyanates source from European and Asian specialty chemical producers. Single-source vulnerability concentrates in blast-cleaning equipment and forced-cure oven installations for powder coating applications. Distribution runs through Jebel Ali and Durban port warehousing into applicator yards across Jubail, Yanbu, and Port Harcourt industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SFDA-MEE VOC harmonization accelerates technology substitution cycles and consolidates procurement around certified formulators.
For Market Incumbents: Cement Arabian Gulf market position through backward integration into water-based resin production capturing refinery maintenance contract premiums. Deepen NACE-certified applicator partnerships in Nigeria before DPR inspection mandates concentrate awards among integrated service providers. Priority defensive lever: SFDA product registration acceleration ahead of anticipated UAE municipal alignment.
For New Entrants and Emerging Players: Nano coating thin-film technology offers entry wedge through subsea riser specifications in Gulf of Guinea projects where asset life extension commands premium pricing. Target South African manufacturing plant conversions responding to Department of Forestry, Fisheries and the Environment air quality enforcement. Go-to-market angle: municipal discharge compliance documentation bundled with water-based acrylic supply contracts.
For Investors and Strategic Acquirers: Roll-up economics work for regional applicator networks because Nigerian DPR bundling and Saudi registration mandates concentrate contract flow toward integrated coating-plus-inspection providers. Five-to-ten year viability favors targets with established SFDA dossiers and NACE-certified labor pools. Signal to watch: MEE-SFDA regulatory convergence timeline accelerating import approval bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Based Resin Production | Saudi SFDA registration premiums reward captive supply of compliant formulations for Jubail refinery cycles. |
| NACE-Certified Applicator Network Acquisition | Nigerian DPR inspection mandates concentrate awards among coating-plus-inspection integrated providers. |
| Nano Coating R&D Partnership | Gulf of Guinea subsea riser specifications favor thin-film cathodic protection technology suppliers. |
| Durban-Richards Bay Spray Booth Retrofit Service Launch | South African ambient air quality enforcement creates recurring revenue from compliance infrastructure. |
| SFDA-EU REACH Testing Protocol Harmonization Investment | Early alignment positions formulators for accelerated UAE and Saudi import approval timelines. |
Research Methodology
Direct dialogue with coating formulator technical directors, refinery maintenance procurement managers at Saudi Aramco and ADNOC, Nigerian DPR certification officers, and Durban industrial yard operators grounded qualitative findings in operational reality. Secondary validation drew from SFDA product registration databases, Nigerian Department of Petroleum Resources inspection records, South African Department of Forestry, Fisheries and the Environment enforcement notices, and customs trade data on epoxy resin imports. Bottom-up project pipeline analysis and top-down petrochemical demand modeling provided cross-verification.
Bottom-up volume estimation tracked individual coating procurement cycles across Jubail, Yanbu, and Ras Laffan industrial corridors alongside Niger Delta pipeline maintenance schedules. Top-down validation anchored in hydrocarbon production forecasts and infrastructure investment pipelines across the analysis window. Segmentation modeling spanned product chemistry, application environment, formulation technology, and end-use sector. CAGR derivation incorporated SFDA regulatory phase-in schedules and MEE enforcement intensity assumptions.
The model holds under sustained VOC regulatory tightening; deviation in crude derivative pricing volatility or applicator certification pool expansion would shift margin distribution. Forecasts embed assumptions on REACH-SFDA testing protocol alignment timelines and Nigerian inspection mandate coverage expansion. A small set of regulatory enforcement intensity and feedstock cost triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Paint Buckets Market