
 South Africa Automotive OEM Coatings Market | 2026-2036
South Africa Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive OEM Coatings Market Analytics
South Africa's Eastern Cape automotive hub is rewriting supplier geography as OEM assembly plants expand coating demand across the Port Elizabeth-Gqeberha corridor. Akzo Nobel N.V. leverages its global color matching infrastructure to serve localized production requirements. BASF SE anchors its position through integrated resin and pigment supply chains into the domestic market. PPG Industries competes on technical service density across multiple OEM programs simultaneously.
Automotive OEM coatings comprise formulated polymer systems applied to vehicle bodies during original manufacture, typically incorporating epoxy primers, polyurethane basecoats, and acrylic-melamine clearcoats that cure through electrostatic spray deposition to achieve corrosion resistance, color consistency, and gloss retention over a vehicle's service life. Water-based technology leads volume adoption as environmental compliance tightens, while UV-cured formulations represent the fastest-expanding segment due to energy efficiency and line-speed advantages in high-throughput plants. Electrocoat application dominates the corrosion-protection layer where uniform film build on complex geometries remains critical.
South Africa's National Regulator for Compulsory Specifications enforces coating VOC limits aligned with industrial emission frameworks, while the Department of Forestry, Fisheries and Environment implements air quality standards that constrain solvent-based formulation volumes. The South African Bureau of Standards maintains product conformity assessment protocols that condition market access for imported coating systems. Stakeholders must monitor regulatory calibration between domestic content incentives and evolving chemical restriction schedules to align capital allocation with compliant technology trajectories.
Market Dynamics
Water-based coating conversion is compressing solvent-based capacity across South Africa's OEM supply base as the Department of Forestry, Fisheries and Environment tightens VOC enforcement timelines. Local paint manufacturers face simultaneous pressure to retool production lines while absorbing resin import cost volatility.
Growth Catalysts
- Automotive Masterplan Incentives:The Department of Trade, Industry and Competition production-linked benefits are redirecting supplier capital toward domestic coating manufacturing capacity.
- Electrocoat Corrosion Standards:OEM assembly plants in Gauteng and the Eastern Cape require uniform primer film build for complex body geometries, expanding automated e-coat line investment.
- Localization Procurement Mandates:Volkswagen, Toyota, and Ford assembly operations in the Pretoria-Johannesburg corridor are consolidating coating supply contracts with domestic-qualified vendors.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and isocyanate precursor costs fluctuate with rand-dollar exchange rates and international crude pricing.
- Import Dependency Concentration:Specialty pigment and additive supply concentrates through Durban port logistics, creating bottleneck exposure during labor disruptions.
- Water-Based Cure Speed Limitations:Ambient humidity in coastal Eastern Cape assembly plants extends flash-off times versus solvent-based alternatives.
Strategic Opportunities
- UV-Cured Clearcoat Expansion:Energy-efficient acrylic-urethane formulations that cure through ultraviolet exposure offer line-speed advantages for high-throughput plants.
- Color-Matching Digital Infrastructure:Spectrophotometer-linked dispensing systems enable just-in-time tinting at OEM assembly sites, reducing finished goods inventory.
- Recycled Content Mandates:Extended producer responsibility frameworks under development create first-mover positioning for bio-based resin formulations.
Industry Challenges
- Formulation Chemist Scarcity:Polymer science expertise with automotive OEM specification experience remains concentrated at multinational technical centers.
- South African Bureau of Standards Certification Timelines:Product conformity assessment protocols for imported coating systems extend market entry lead times.
- Legacy Solvent Line Stranded Assets:Capital equipment depreciation schedules misalign with regulatory phase-out timelines for high-VOC application systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive OEM Coatings Market |
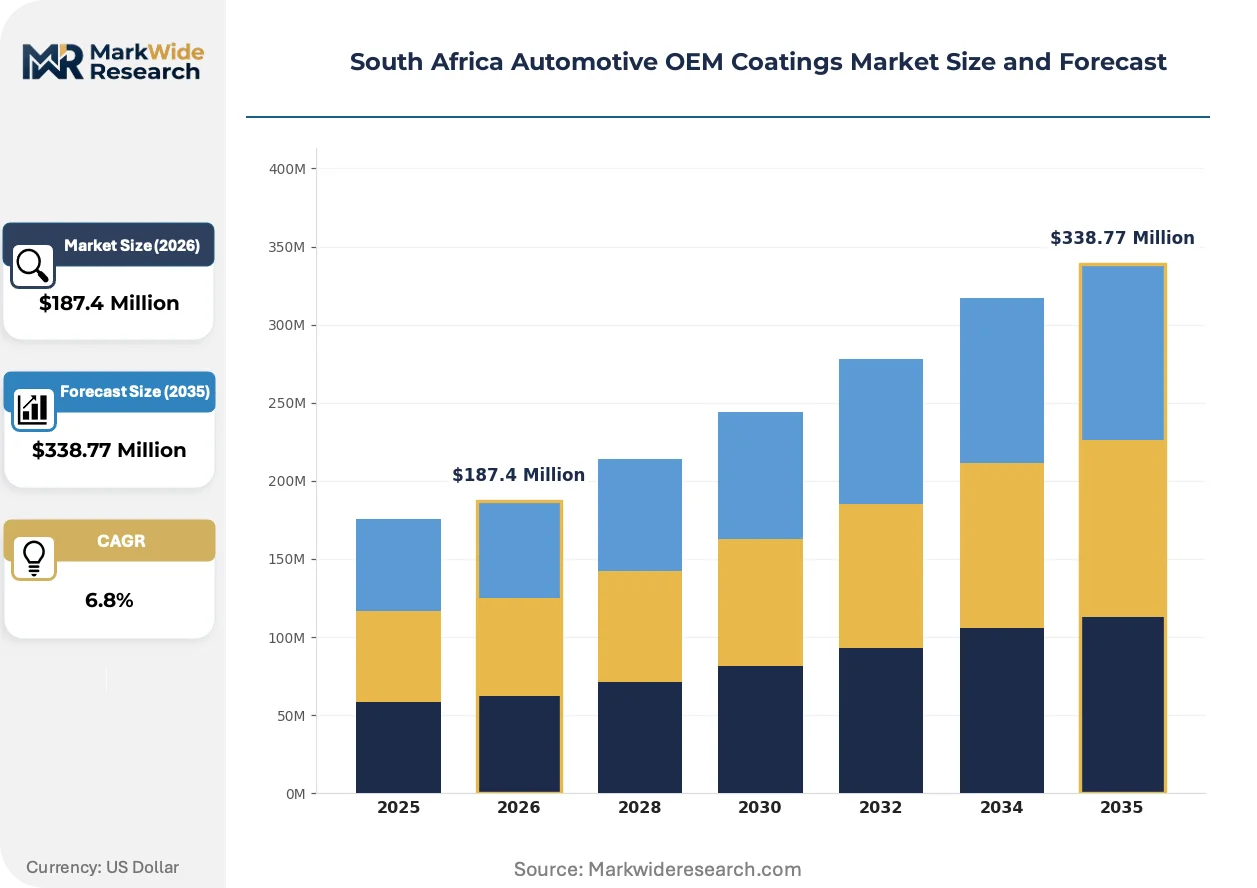
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Primer, Basecoat, Clearcoat, Electrocoat Application Method: Spray, Roller, Brush, Dip End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy Trucks Technology: Water-based, Solvent-based, UV-cured, Powder |
| Companies Covered | Akzo Nobel N.V., Axalta Coating Systems, BASF SE, PPG Industries, Kansai Plascon, Autoboys Holdings, Beckers Group, Mankiewicz Gebr. & Co., The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive OEM Coatings Market Evolving Landscape
Spectral color-matching hardware is digitizing quality control workflows across South African OEM assembly plants. Three concurrent developments are compressing traditional coating supply and application models.
Inline spectrophotometry is digitizing real-time color deviation detection during basecoat application. Volkswagen and Toyota assembly operations in Gauteng deploy closed-loop feedback systems that adjust spray parameters without line stoppage. This technology is digitizing manual quality inspection roles while compressing rework rates and warranty claims.
The National Regulator for Compulsory Specifications enforces coating VOC limits aligned with industrial emission frameworks. South Africa's Department of Forestry, Fisheries and Environment implements air quality standards that constrain solvent-based formulation volumes. Waterborne primer and basecoat systems capture procurement preference in new OEM supply agreements.
Integrated supply contracts now bundle coating formulation with technical service density across multiple OEM programs simultaneously. Tier-one suppliers in the Eastern Cape corridor consolidate vendor relationships to reduce qualification overhead. This consolidation concentrates procurement decision-making with plant engineering directors rather than decentralized purchasing functions.
South Africa Automotive OEM Coatings Market Segmentation
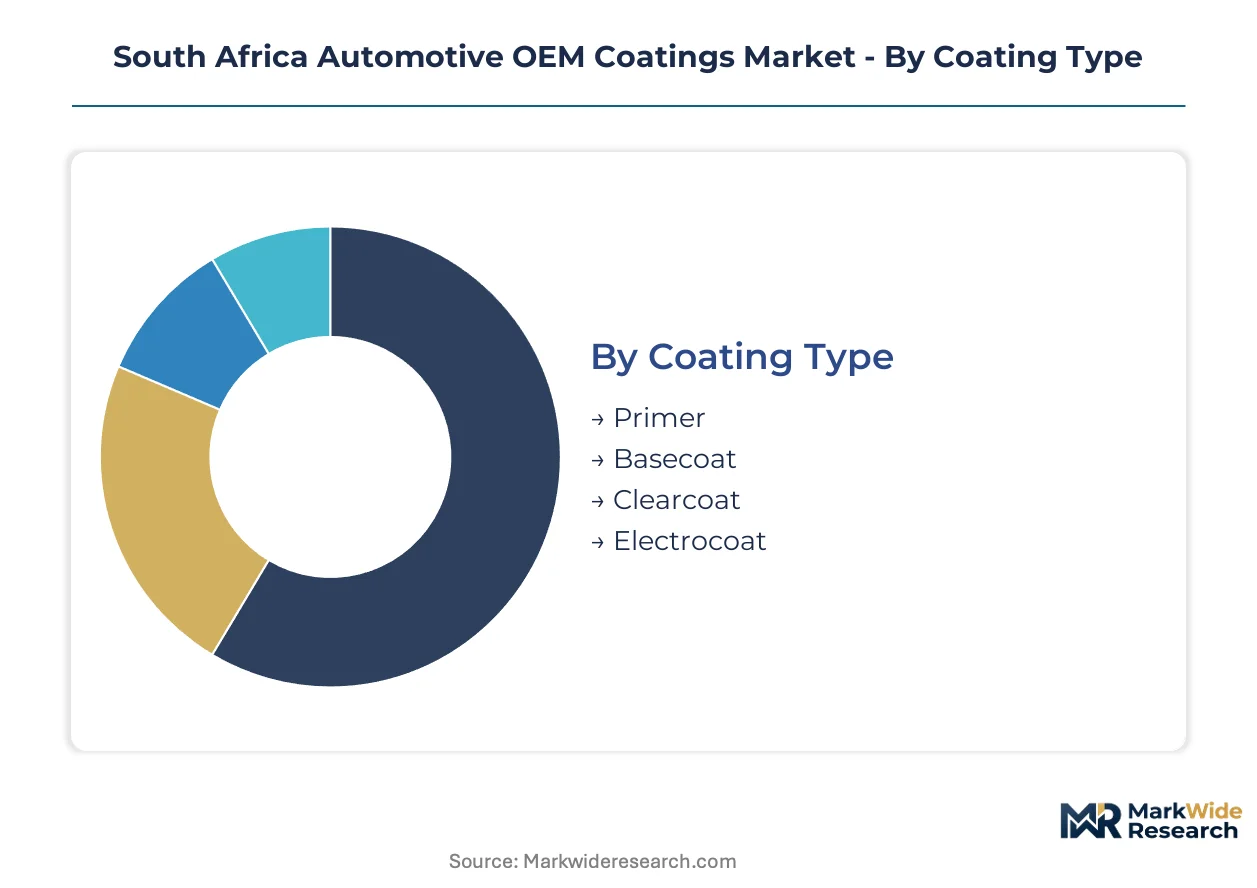
Automotive OEM coatings in South Africa fragment across four intersecting dimensions that determine procurement patterns at Volkswagen, Toyota, and Ford assembly plants. Coating type and technology choices carry regulatory compliance implications, while application method and end-user specifications dictate capital equipment requirements across Gauteng and Eastern Cape production corridors.
Coating Type:
Mature automotive coating categories dominate procurement volumes in South Africa's established assembly infrastructure, though emerging specifications are gaining specification share in next-generation plant investments.
- Primer:Epoxy-based formulations provide corrosion protection and adhesion promotion for galvanized steel body panels. Demand concentrates at Ford's Silverton plant and Toyota's Prospecton facility where salt-spray resistance specifications exceed 1,000 hours for coastal export markets.
- Electrocoat:Cathodic epoxy systems deposit uniform films on complex geometries through electrodeposition, consuming 60-70% of coating line energy budgets. Volkswagen's Uitenhage assembly operation in the Eastern Cape requires automated e-coat tanks exceeding 200 cubic meters for SUV body-in-white throughput.
- Basecoat:Pigmented layers delivering color and metallic effects through polyurethane or waterborne acrylic systems.
- Clearcoat:Acrylic-melamine or polyurethane top layers providing gloss retention and UV protection.
Electrocoat retains volume leadership; basecoat holds the steepest expansion curve as color-variant complexity increases.
Application Method:
Cost tier differentiation separates mass-production automated systems from lower-volume manual operations serving niche vehicle programs.
- Spray:Electrostatic rotary bell atomizers dominate high-throughput lines, achieving 85% transfer efficiency with 12-15 micron film control. BMW's Rosslyn plant and Nissan's Pretoria operations specify robotic spray cells with real-time viscosity monitoring for waterborne basecoat application.
- Dip:Immersion coating remains essential for electrocoat deposition where complete interior cavity coverage prevents corrosion initiation. The Pretoria-Johannesburg corridor hosts the densest concentration of dip-tank infrastructure outside European manufacturing zones.
- Roller:Limited to flat panel pre-treatment and sealant application in South African assembly contexts.
- Brush:Restricted to touch-up operations and prototype builds with negligible OEM procurement volume.
Spray application commands the premium tier; dip coating anchors the high-volume baseline.
End User:
Customer type segmentation aligns with South Africa's Department of Trade, Industry and Competition automotive masterplan production targets and export orientation.
- Passenger Vehicles:Sedan, hatchback, and SUV coating programs represent the procurement concentration at all major OEM facilities. Volkswagen's Gqeberha plant and Toyota's Durban-adjacent operations specify multi-layer systems with 5-year gloss retention warranties for European export compliance.
- Heavy Trucks:Commercial vehicle coating emphasizes chip resistance and underbody durability for mining fleet applications. Isuzu's Port Elizabeth truck assembly requires modified epoxy primers with extended film builds on chassis components.
- Commercial Vehicles:Light commercial and van programs with intermediate durability specifications.
- Two-wheelers:Minimal presence in South African OEM manufacturing with negligible coating demand.
Passenger vehicles retain volume leadership; heavy trucks hold the steepest expansion curve under masterplan commercial vehicle incentives.
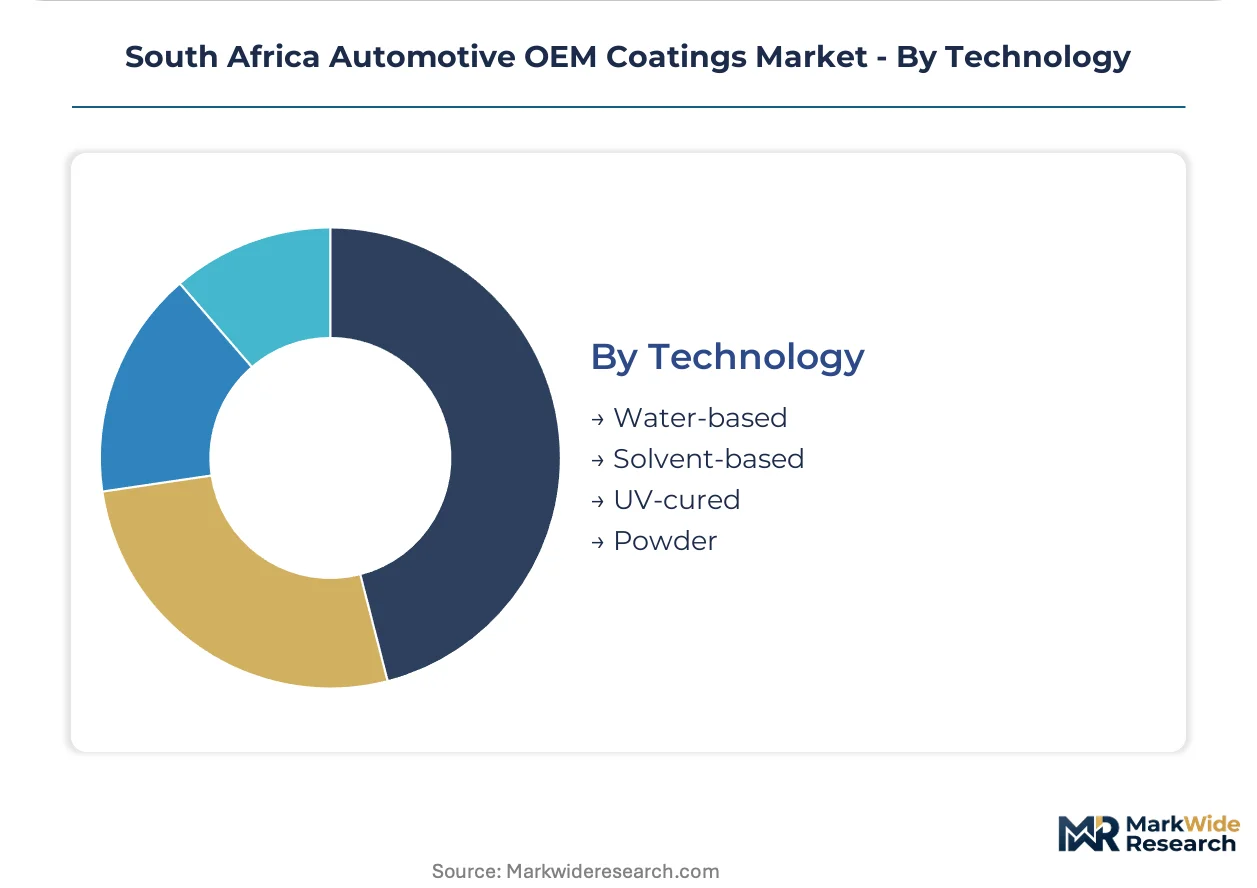
Technology:
Supply concentration in resin and additive imports shapes technology adoption timelines across domestic formulation capacity.
- Water-based:Acrylic-polyurethane dispersions with VOC content below 420 g/liter dominate new OEM supply agreements. The Department of Forestry, Fisheries and Environment enforcement timelines are compressing solvent-based conversion at remaining plants in the Eastern Cape corridor.
- UV-cured:Acrylate oligomer systems cure through photoinitiator activation, reducing energy consumption 40-60% versus thermal ovens. Mercedes-Benz's East London facility piloted UV clearcoat lines for compact vehicle programs requiring accelerated line speeds.
- Solvent-based:Declining share constrained by National Regulator for Compulsory Specifications VOC limits, though retained for specific metallic effect basecoats.
- Powder:Thermoset epoxy-polyester systems limited to wheel and underbody component coating in South African OEM contexts.
Water-based technology retains volume leadership; UV-cured systems are climbing the fastest under energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The South African Bureau of Standards anchors coating conformity protocols across sub-regional manufacturing corridors. The Department of Trade, Industry and Competition automotive masterplan redistributes supplier investment toward domestic capacity. Gauteng and Eastern Cape provinces concentrate assembly infrastructure requiring integrated coating supply.
Gauteng Province
Volkswagen's Silverton plant and Toyota's Prospecton facility drive electrocoat and basecoat procurement volumes. The Department of Forestry, Fisheries and Environment enforces VOC limits that compress solvent-based conversion timelines. The Pretoria-Johannesburg corridor hosts dense robotic spray cell infrastructure with real-time viscosity monitoring for waterborne systems.
Eastern Cape Province
Mercedes-Benz's East London facility and Isuzu's Port Elizabeth truck assembly anchor coating demand for passenger and commercial vehicle programs. National Regulator for Compulsory Specifications alignment with industrial emission frameworks constrains high-VOC formulation volumes. The Port Elizabeth-Gqeberha corridor expands automated e-coat tank capacity for SUV body-in-white throughput.
KwaZulu-Natal Province
Toyota's Durban-adjacent operations specify multi-layer systems with extended gloss retention warranties for European export compliance. The country's national environmental regulator implements air quality standards that redirect procurement toward water-based technology. Durban port logistics concentrate specialty pigment and additive import flows, creating bottleneck exposure during labor disruptions.
Western Cape Province
Commercial vehicle refurbishment and specialty automotive manufacturing generate niche coating demand outside mass-production corridors. Extended producer responsibility frameworks under development create positioning opportunities for bio-based resin formulations. Cape Town industrial zones host limited OEM-scale coating infrastructure compared to eastern manufacturing belts.
South Africa Automotive OEM Coatings Market Competitive Landscape
Multinational chemical conglomerates and regional coating specialists split the market across technology tiers. The vendor base concentrates around integrated resin supply chains and global color matching infrastructure. Three archetypes dominate: integrated chemical majors with captive raw material positions, dedicated automotive coating specialists with OEM program density, and regional distributors with technical service proximity. Capacity expansion and localization partnerships constitute the dominant competitive moves as masterplan incentives reshape supplier geography.
Within the integrated chemical major tier, Akzo Nobel N.V., BASF SE, and PPG Industries exemplify archetypes anchored by global formulation expertise and domestic technical service presence. These entities occupy positions defined by resin and pigment supply chain integration rather than standalone coating manufacturing. Regional specialists including Kansai Plascon and Beckers Group represent mid-tier positioning focused on OEM program-specific relationships. The competitive dynamic situates procurement decision-making with plant engineering directors consolidating vendor relationships to reduce qualification overhead.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| PPG Industries |
| Kansai Plascon |
| Autoboys Holdings |
| Beckers Group |
| Mankiewicz Gebr. & Co. |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
The Pretoria-Johannesburg corridor concentrates South Africa's automotive coating formulation capacity, with resin import costs and rand-dollar volatility feeding directly into OEM procurement pricing power. Domestic manufacturers absorb feedstock fluctuations while competing against landed imports from European and Asian suppliers.
Pricing Analysis
Coating procurement across Gauteng and Eastern Cape assembly plants shows widening price spreads between water-based and legacy solvent systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade alignment with National Regulator for Compulsory Specifications VOC thresholds and volume scale commitments. Cost compression in solvent-based tiers is intensifying because regulatory phase-out timelines strand remaining production assets. Tier-one OEMs demonstrate lowest price sensitivity due to integrated supply contracts bundling technical service density, while independent repair and refurbishment operators in Western Cape commercial vehicle segments exhibit highest sensitivity to per-liter coating costs.
Supply Chain Analysis
Epoxy resin and isocyanate precursor supply draws from Germany, China, and South Korea through Durban port logistics corridors. Specialty pigment and additive flows rest on concentrated import channels with limited domestic substitution capacity. Single-source vulnerability concentrates around cathodic electrocoat resin systems where qualified alternative suppliers require extended South African Bureau of Standards certification timelines. Distribution runs through integrated chemical majors with captive technical service teams co-located at OEM assembly plants, supplemented by regional distributors serving secondary refurbishment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's automotive OEM coatings market represents a high-growth disruption as water-based technology conversion and UV-cured system adoption compress legacy solvent capacity under Department of Forestry, Fisheries and Environment enforcement timelines.
For Market Incumbents: Entrench position through backward integration into acrylic-polyurethane resin production within the Eastern Cape corridor, reducing rand-dollar exposure on imported feedstocks. Defend against emerging regional specialists by accelerating South African Bureau of Standards pre-certification of next-generation low-VOC formulations ahead of regulatory phase-out deadlines. Prioritize technical service team expansion at Toyota's Prospecton and Volkswagen's Silverton facilities to lock in multi-program supply contracts.
For New Entrants and Emerging Players: KwaZulu-Natal's Durban-adjacent coating demand offers underpenetrated white-space for UV-cured clearcoat specialists serving export-oriented gloss retention specifications. Target heavy truck refurbishment segments in Western Cape commercial vehicle zones where incumbent technical service density remains thinnest. Enter through color-matching digital infrastructure partnerships with independent body shops, bypassing capital-intensive e-coat tank investments required for OEM tier-one qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Department of Trade, Industry and Competition masterplan incentives are redistributing supplier investment toward domestic manufacturing capacity with multi-year procurement visibility. Acquisition targets should emphasize mid-tier regional formulators with existing South African Bureau of Standards product conformity assessments and established OEM engineering relationships. Watch for National Regulator for Compulsory Specifications VOC limit calibration announcements as the critical signal for technology transition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive epoxy and polyurethane supply reduces rand-dollar volatility exposure for Gauteng-based formulators. |
| UV-Cured Clearcoat Line Investment | Mercedes-Benz East London pilot demonstrates energy-efficient curing viable for compact vehicle throughput expansion. |
| Digital Color-Matching Infrastructure Deployment | Spectrophotometer-linked dispensing at Toyota Prospecton enables just-in-time tinting with finished goods inventory reduction. |
| Extended Producer Responsibility Partnership | Bio-based resin formulations position first-movers ahead of developing South African waste framework mandates. |
| Technical Service Team Co-location | Integrated support density at Ford Silverton consolidates multi-program procurement decisions with plant engineering directors. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, coating plant managers, and aftermarket distribution specialists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from South African Bureau of Standards conformity assessment records, Department of Trade, Industry and Competition automotive masterplan documentation, customs and trade flow data, and OEM production registration databases. Bottom-up coating volume estimates triangulated against top-down automotive production forecasts.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling coating demand by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. Segmentation dimensions included coating type, application method, technology tier, and end-user specification. CAGRs derived from production-linked incentive trajectories and regulatory compliance timelines, with inputs from resin import cost volatility patterns and rand-dollar exchange rate sensitivity analyses.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated chemical majors or accelerated National Regulator for Compulsory Specifications VOC limit revisions would shift outcomes substantially. Cross-checking against vehicle production databases and OEM procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Cool Roof Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Coating Resins Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Acrylic Protective Coating Market