
 Protective Coatings Market | 2026-2036
Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Coatings Market Analysis
Skilled applicator availability for high-performance marine and industrial systems is collapsing across Gulf Coast and North European hubs. PPG Industries sustains broad geographic coverage through integrated distribution networks spanning major shipbuilding regions. AkzoNobel N.V. differentiates via specialized fouling-control chemistry for deep-water offshore structures. Hempel A/S anchors its position through direct technical service presence at mega-yard complexes in South Korea and China.
Protective coatings are formulated barrier systems—typically incorporating epoxy resins, polyurethane binders, zinc dust sacrificial layers, or acrylic polymers—applied to steel, concrete, or composite substrates to prevent corrosion, chemical attack, and ultraviolet degradation in aggressive operating environments. Film thickness specifications range from 150 μm for atmospheric service to exceeding 1,000 μm for immersed marine conditions, with multi-coat architectures engineered for cathodic disbondment resistance and thermal cycling durability. Epoxy formulations dominate heavy industrial and marine maintenance cycles due to adhesion strength and chemical resistance, while polyurethane topcoats command premium positioning in architectural and transportation applications where gloss retention and color stability determine specification. Water-borne technology is displacing solvent-borne equivalents in regulated European and North American construction sectors, though solvent systems retain share in high-humidity shipyard applications where flash time control proves critical.
EPA VOC emission limits under 40 CFR Part 59 constrain solvent-borne product formulations across US industrial and architectural segments, while REACH Annex XVII restrictions on chromium(VI) compounds and isocyanates force reformulation of pretreatment and curing agent chemistries throughout European supply chains. China's MEE enforcement of GB standards on volatile organic compound content in container and ship manufacturing is tightening compliance timelines for domestic and imported coating suppliers. Stakeholders must monitor regulatory divergence between VOC caps, hazardous substance phase-outs, and carbon-border adjustment mechanisms as these frameworks increasingly determine product eligibility and project specification authority across procurement decisions.
Market Dynamics
REACH Annex XVII restrictions on chromium(VI) compounds and isocyanates are forcing wholesale reformulation of pretreatment and curing agent chemistries across European supply chains, redirecting capital toward water-borne and powder alternatives while solvent systems retain defensive positions in high-humidity shipyard zones.
Growth Catalysts
- Offshore wind construction:North Sea lease rounds are accelerating epoxy and zinc-rich system procurement for monopile foundations and transition pieces.
- GB standards enforcement:China's MEE is tightening VOC content timelines in container and ship manufacturing, upgrading specification floors for marine-grade protective systems.
- Fleet expansion mandates:State-led vessel programs in China's coastal shipyard clusters are driving procurement volume for high-performance anti-corrosive architectures.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol A and epichlorohydrin price swings compress formulation margins for industrial maintenance coatings.
- Applicator scarcity:Gulf Coast and North European hubs face collapsing availability of certified technicians for high-performance marine and industrial systems.
- Flash time constraints:Water-borne technologies face technical friction in high-humidity shipyard environments where solvent systems retain specification lock-in.
Strategic Opportunities
- Carbon-border adjustment positioning:EU CBAM implementation creates first-mover advantage for low-carbon coating producers serving export-oriented steel fabricators.
- Deep-water fouling control:Unmet specification needs for ultra-deep offshore structures in Brazil's pre-salt fields reward specialized biocide chemistry development.
- Direct technical service models:Embedded application support at mega-yard complexes in South Korea and China builds specification authority and switching costs.
Industry Challenges
- Cathodic disbondment certification:Extended test protocols for immersed marine service delay new product commercialization by 18-24 months.
- Multi-coat application complexity:Film thickness specifications exceeding 1,000 μm for subsea conditions require precise intercoat adhesion control and quality assurance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Coatings Market |
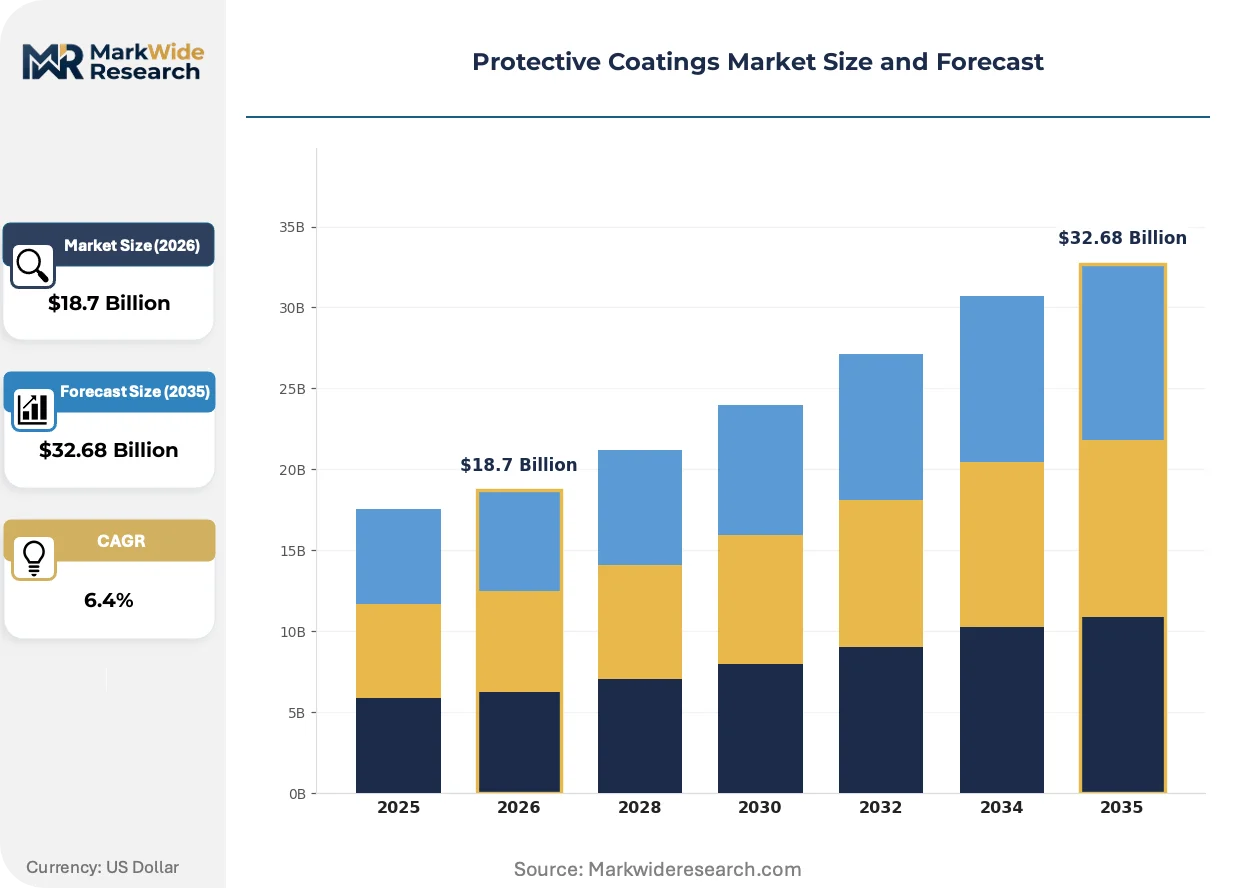
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc-rich Application: Industrial Equipment, Marine, Aerospace, Automotive End User: Construction, Manufacturing, Oil & Gas, Power Generation Technology: Solvent-borne, Water-borne, Powder Coating, UV-cured |
| Companies Covered | Jotun A/S, RPM International Inc., PPG Industries, Inc., Kansai Paint Co., Ltd., Sika AG, AkzoNobel N.V., Hempel A/S, Axalta Coating Systems, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Coatings Market Emerging Trajectories
Formulation chemistry is pivoting toward lower-carbon binder systems and application-optimized architectures as regulatory pressure compounds with end-user sustainability procurement criteria across heavy industrial and marine segments.
Nano-engineered zinc dust loadings are miniaturizing sacrificial layer thickness requirements while maintaining galvanic protection performance. Offshore wind developers in the North Sea are specifying these systems for monopile internals to reduce material weight and application labor. This technology is miniaturizing the trade-off between film thickness and corrosion resistance that has governed marine coating design for decades.
EPA VOC emission limits under 40 CFR Part 59 are constraining solvent-borne product formulations across US industrial and architectural segments. Formulators are accelerating water-borne and high-solids alternatives, though flash time performance gaps persist in humid Gulf Coast application environments. The construction and maintenance sectors are absorbing compliance costs through specification tiering and contractor qualification requirements.
Asset owners are compressing coating selection cycles from multi-year framework agreements toward project-specific technical qualification. Engineering procurement divisions at major offshore contractors are unbundling coating supply from application services, forcing material suppliers to compete on standalone performance data rather than integrated package pricing. This pattern is most pronounced in Norway's offshore fabrication sector and spreading to UK North Sea decommissioning projects.
Protective Coatings Market Segmentation
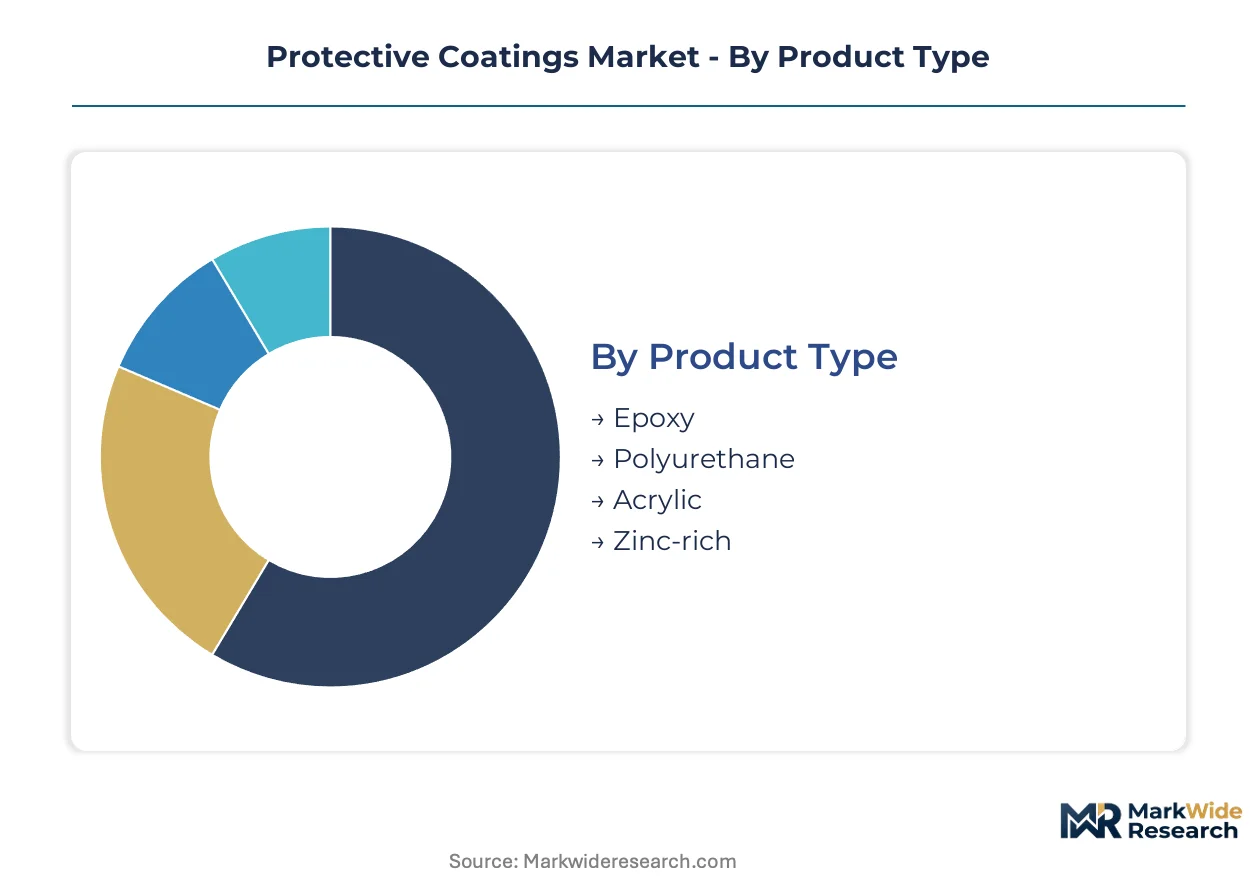
Protective coatings segmentation reveals distinct procurement patterns across heavy industrial, marine, and infrastructure verticals. Specification authority varies sharply by end-use, with offshore wind developers and state shipyard programs driving divergent technical requirements for film thickness, cure chemistry, and environmental compliance.
Product Type:
Domestic formulation capacity concentrates epoxy and zinc-rich systems in coastal industrial clusters, while polyurethane and acrylic supply chains serve export-oriented architectural and transportation OEMs.
- Epoxy:Two-part thermoset systems built from bisphenol A and epichlorohydrin feedstocks deliver superior adhesion to blast-cleaned steel and chemical resistance against process fluids. Demand clusters in China's state-led shipyard expansion and North Sea offshore wind monopile fabrication, where specifications exceed 1,000 μm for immersed service.
- Polyurethane:Aliphatic isocyanate-cured topcoats provide UV stability and gloss retention for architectural and transportation exteriors. Procurement runs through automotive OEM supply chains in Germany and premium infrastructure projects in the UAE, where aesthetic durability commands specification priority.
- Acrylic:Thermoplastic emulsions and solvent-based resins serve atmospheric corrosion protection with faster dry-to-touch characteristics. Water-borne acrylic demand is climbing fastest in US commercial construction as EPA VOC limits tighten.
- Zinc-rich:Inorganic and organic binders loaded with metallic zinc dust provide sacrificial galvanic protection for steel substrates. Application concentrates on offshore platform structural members and bridge steel in coastal environments.
Epoxy commands the established base. The steepest expansion runs through zinc-rich systems for offshore wind foundations.
Application:
Volume concentration tracks heavy asset installation cycles, with marine and industrial equipment absorbing multi-coat architectures while aerospace and automotive specify thinner-film precision systems.
- Industrial Equipment:Chemical processing vessels, pipelines, and structural steel in refineries and petrochemical complexes require epoxy-phenolic and glass-flake reinforced systems. Procurement is accelerating in US Gulf Coast LNG export terminals and Saudi Aramco downstream expansions.
- Marine:Ballast tanks, cargo holds, and underwater hulls demand cathodic disbondment-resistant epoxies and specialized fouling-control topcoats. North Sea offshore wind construction and China's naval fleet modernization are driving specification upgrades for deep-water service.
- Aerospace:Chromate-free pretreatments and polyurethane topcoats for airframe exteriors operate under FAA airworthiness certification. Demand remains concentrated in Boeing and Airbus final assembly supply chains.
- Automotive:Electrocoat primers, basecoats, and clearcoats for vehicle bodies prioritize chip resistance and appearance retention. OEM specifications are tightening VOC content limits ahead of regulatory phase-ins.
Industrial equipment absorbs the highest absolute volumes. Marine applications are gaining share fastest on offshore wind capital deployment.
End User:
Construction and manufacturing procurement dominates domestic consumption, while oil & gas and power generation specifications flow through international EPC contractors with standardized material approval lists.
- Construction:Steel bridges, commercial building exteriors, and infrastructure assets specify zinc-rich primers and polyurethane topcoats for atmospheric service. US state DOT bridge rehabilitation programs and Chinese high-speed rail expansion are driving tender volumes.
- Manufacturing:General industrial maintenance cycles for plant equipment and structural steel favor high-solids epoxies for recoatability. Procurement is consolidating under national distributor frameworks in Germany and Japan.
- Oil & Gas:Offshore platforms, subsea pipelines, and downstream facilities require NORSOK M-501 and ISO 20340 certified systems for splash zone and immersed conditions. Brazil's pre-salt field development is opening specification opportunities for deep-water qualified coatings.
- Power Generation:Cooling water systems, stacks, and structural steel in thermal and renewable assets demand chemical-resistant linings and high-temperature silicones. Offshore wind turbine tower internals are specifying nano-engineered zinc systems for weight reduction.
Construction maintains the largest installed base. Power generation is expanding most quickly on offshore wind buildout.
Technology:
Regulatory pressure is fragmenting technology adoption by geography, with water-borne and powder systems capturing share in Europe and North America while solvent-borne formulations defend position in high-humidity Asian shipyards.
- Solvent-borne:Traditional alkyd, epoxy, and polyurethane formulations rely on organic solvent carriers for flow and leveling. Retains specification lock-in in China's Pearl River Delta shipyards where flash time control proves critical during monsoon humidity.
- Water-borne:Acrylic and epoxy emulsions displace solvent systems in regulated construction and industrial maintenance markets. REACH VOC restrictions and EPA 40 CFR Part 59 compliance are redirecting capital toward aqueous resin development.
- Powder Coating:Thermoset epoxy and polyester powders applied electrostatically deliver zero-VOC finishes for pipeline fittings, rebar, and architectural aluminum. European fabricators are adopting powder for CBAM-aligned low-carbon steel coating.
- UV-cured:Acrylate oligomers cured by ultraviolet radiation enable instant handling for wood, plastic, and specialty substrates. Niche adoption persists in flooring and electronics masking where line speed dictates process economics.
Solvent-borne retains the largest specification footprint. Water-borne technology is climbing the fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through GB standards enforcement that redirects formulation investment toward compliant water-borne and high-solids systems. State-led vessel programs and offshore wind construction are compressing procurement timelines across coastal industrial clusters.
China
State shipyard expansion and offshore wind monopile fabrication are driving specification upgrades for marine-grade epoxy systems. MEE enforcement of GB VOC content standards is accelerating technology transitions in container and vessel manufacturing. Yangtze River Delta and Pearl River Delta shipyard clusters are absorbing the highest procurement volumes for cathodic disbondment-resistant architectures.
United States
Gulf Coast LNG terminal construction and bridge rehabilitation programs are sustaining demand for zinc-rich primers and high-solids epoxies. EPA 40 CFR Part 59 VOC limits are constraining solvent-borne formulations across industrial maintenance sectors. Houston and Corpus Christi industrial corridors face acute applicator scarcity for high-performance marine systems.
Germany
Automotive OEM supply chains and premium infrastructure projects are specifying aliphatic polyurethane topcoats for UV stability and gloss retention. REACH Annex XVII restrictions on chromium(VI) and isocyanates are forcing pretreatment chemistry reformulation. Ruhr industrial region and Bavarian automotive clusters are consolidating procurement under national distributor frameworks.
South Korea
Mega-yard complexes and naval fleet modernization are driving multi-coat specification for deep-water service conditions. Korean Register certification requirements are extending product qualification timelines for immersed marine applications. Ulsan and Geoje shipbuilding hubs are embedding direct technical service models to reduce switching costs.
Brazil
Pre-salt field development and offshore platform fabrication are opening specification opportunities for deep-water qualified fouling-control systems. ANVISA biocide registration requirements are filtering supplier eligibility for ultra-deep offshore structures. Rio de Janeiro and Espírito Santos offshore fabrication yards are qualifying new entrants against NORSOK-equivalent standards.
Protective Coatings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated multinationals commanding specification authority through embedded service networks while regional specialists defend margin positions in application-intensive niches. The market structure tiers across three concentration levels: global formulators with direct yard presence, national champions serving domestic industrial maintenance, and technology licensors supplying resin and additive systems. Two archetypes dominate competitive positioning—specification-driven innovators competing on certification breadth and scale-driven producers optimizing formulation cost curves. M&A activity concentrates on geographic white-space filling and water-borne technology acquisition, while capacity expansion targets coastal industrial clusters in Asia-Pacific and Gulf Coast North America.
Within the integrated multinational tier, PPG Industries and AkzoNobel N.V. exemplify divergent strategic positioning—PPG sustaining broad geographic coverage through distribution network density, AkzoNobel occupying a specialized position in fouling-control chemistry for offshore structures. Hempel A/S anchors the direct technical service archetype through embedded presence at mega-yard complexes. Among Japanese and European coating specialists, Kansai Paint Co., Ltd. and Sika AG represent regional champions extending into marine and industrial segments through certification accumulation rather than acquisition-led expansion.
| Leading Market Players |
|---|
| Jotun A/S |
| RPM International Inc. |
| PPG Industries, Inc. |
| Kansai Paint Co., Ltd. |
| Sika AG |
| AkzoNobel N.V. |
| Hempel A/S |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
Water-borne epoxy resin substitution for solvent-borne formulations simultaneously redraws raw material sourcing maps around German and Dutch chemical clusters and compresses formulation margins as applicators demand retraining premiums. This input transition concentrates bargaining power with resin suppliers who have achieved REACH-compliant aqueous polymer certification ahead of formulation houses.
Pricing Analysis
Geographic price spreads between European and Chinese procurement contracts for marine-grade epoxy systems have widened as REACH compliance costs embed in continental quotes while Pearl River Delta shipyards exploit solvent-borne residual availability. Three-tier pricing structure across NORSOK-certified premium, ISO 20340-compliant standard, and economy industrial maintenance tiers dominates contract architecture. Cost compression in water-borne segments is intensifying because MEE enforcement timelines accelerate R&D amortization schedules. State shipyard programs exhibit lowest price sensitivity due to specification floor mandates, while independent Gulf Coast fabricators face acute budget constraints.
Supply Chain Analysis
Inventory lead times for zinc dust feedstock have extended from South Korean smelters as battery sector competition for refined zinc tightens metal allocation priorities. Manufacturing gravity centers on China, Germany, and the United States for formulated products, with bisphenol A, epichlorohydrin, and metallic zinc dust as critical input dependencies. Single-source vulnerability concentrates in European epichlorohydrin supply anchored to Rheinland petrochemical complexes. Distribution runs through integrated multinational networks for marine specifications and national distributor frameworks for industrial maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protective coatings market is entering a cyclical recovery phase driven by North Sea offshore wind capital deployment schedules that compress procurement timelines and elevate specification authority toward certified suppliers.
For Market Incumbents: Shield specification authority by embedding technical service teams at Ulsan and Geoje mega-yard complexes before Korean Register certification windows close. Accelerate backward integration into aqueous resin production to capture margin erosion from specialty chemical suppliers. Defend against Chinese state-yard procurement consolidation by pre-qualifying systems for GB standard compliance ahead of MEE enforcement deadlines. For New Entrants and Emerging Players: Differentiate on deep-water fouling-control chemistry for Brazil's pre-salt field development where ANVISA registration barriers filter incumbent competition. Target nano-engineered zinc loadings for offshore wind tower internals as specification unbundling creates standalone material competition. Pursue direct qualification with Norway's offshore fabrication sector where project-specific technical procurement rewards performance data transparency. For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape by elevating low-carbon coating producers serving export-oriented steel fabricators toward premium valuation multiples. Long-term viability favors targets with aqueous technology portfolios and embedded yard service presence over commodity formulation capacity. Monitor cathodic disbondment certification completion rates as the signal indicating which development-stage technologies will achieve commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aqueous Resin Production | Captures margin compression from German and Dutch specialty chemical suppliers serving REACH-compliant formulation houses. |
| Embedded Technical Service at Mega-Yard Complexes | Builds specification lock-in with Korean Register and Chinese state shipyard procurement committees. |
| NORSOK M-501 Certification Investment | Unlocks project-specific procurement at Norway's offshore fabrication sector and UK North Sea decommissioning contractors. |
| Nano-Engineered Zinc Loading Development | Addresses offshore wind developer weight reduction specifications for monopile internal protection systems. |
| Long-Term Supply Agreement with Offshore Wind EPCs | Secures volume commitments as North Sea lease rounds accelerate epoxy and zinc-rich system procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports through structured interviews with plant managers at coating formulation facilities, procurement leads at downstream shipyard and offshore EPC contractors, distribution channel partners, and technical R&D directors. Bottom-up volume estimates derived from asset installation cycles and maintenance scheduling patterns were cross-validated against top-down macroeconomic indicators and energy infrastructure investment flows.
Segmentation dimensions modeled span resin chemistry type, film thickness specification tier, cure technology, end-use vertical, and regional regulatory compliance cluster across the projection horizon. CAGRs were synthesized from historical procurement volume trajectories, announced capacity expansion timelines, and regulatory phase-in schedules. Forecast inputs incorporated offshore wind installation capacity pipelines, state vessel program procurement calendars, and MEE enforcement trajectory assumptions.
Material uncertainties — feedstock price volatility, certification protocol delays, and regulatory divergence between VOC caps and carbon-border mechanisms — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology substitution rates and specification authority migration patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Textile Coatings Market
Coatings
Global Waterborne Coatings Market