
 Road Marking Paints and Coatings Market | 2026-2036
Road Marking Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Road Marking Paints and Coatings Market Analytics
Waterborne resin chemistry is tilting formulation priorities away from solvent-based systems across the road marking value chain. Sherwin-Williams Company leverages its North American distribution network to sustain contractor channel dominance in municipal road applications. PPG Industries anchors its position through specialized epoxy technologies for airport runway markings where FAA certification requirements create technical barriers to entry. Asian Paints competes on cost-optimized acrylic formulations tailored to tropical climate degradation profiles.
Road marking paints and coatings are pigmented, film-forming materials applied to traffic-bearing surfaces to convey regulatory, warning, or guidance information through retroreflective or color-coded performance. Thermoplastic compositions incorporating glass beads and hydrocarbon resins achieve dry times under two minutes at application temperatures of 180–220°C, enabling lane reopening during short highway maintenance windows. Among product type segments, waterborne formulations command expanding share in European municipal contracts where ECHA restrictions on volatile organic compound emissions constrain solvent alternatives. Application demand in parking lots generates stable margin pools through recurring restriping cycles, while airport markings require specialized FAA-certified epoxies that sustain premium pricing structures.
The EPA enforces VOC emission thresholds under 40 CFR 59 Subpart D that determine product eligibility for federal highway procurement contracts. ECHA implements REACH restrictions on chromium pigment chemistries that force reformulation of yellow road marking systems across EU member states. The EU Green Deal embeds carbon footprint criteria in public infrastructure tendering that advantage low-emission waterborne technologies. Stakeholders must monitor evolving state-level procurement specifications in the US and EU member implementation of CSRD sustainability disclosure rules that will reshape supplier qualification criteria for public road marking contracts.
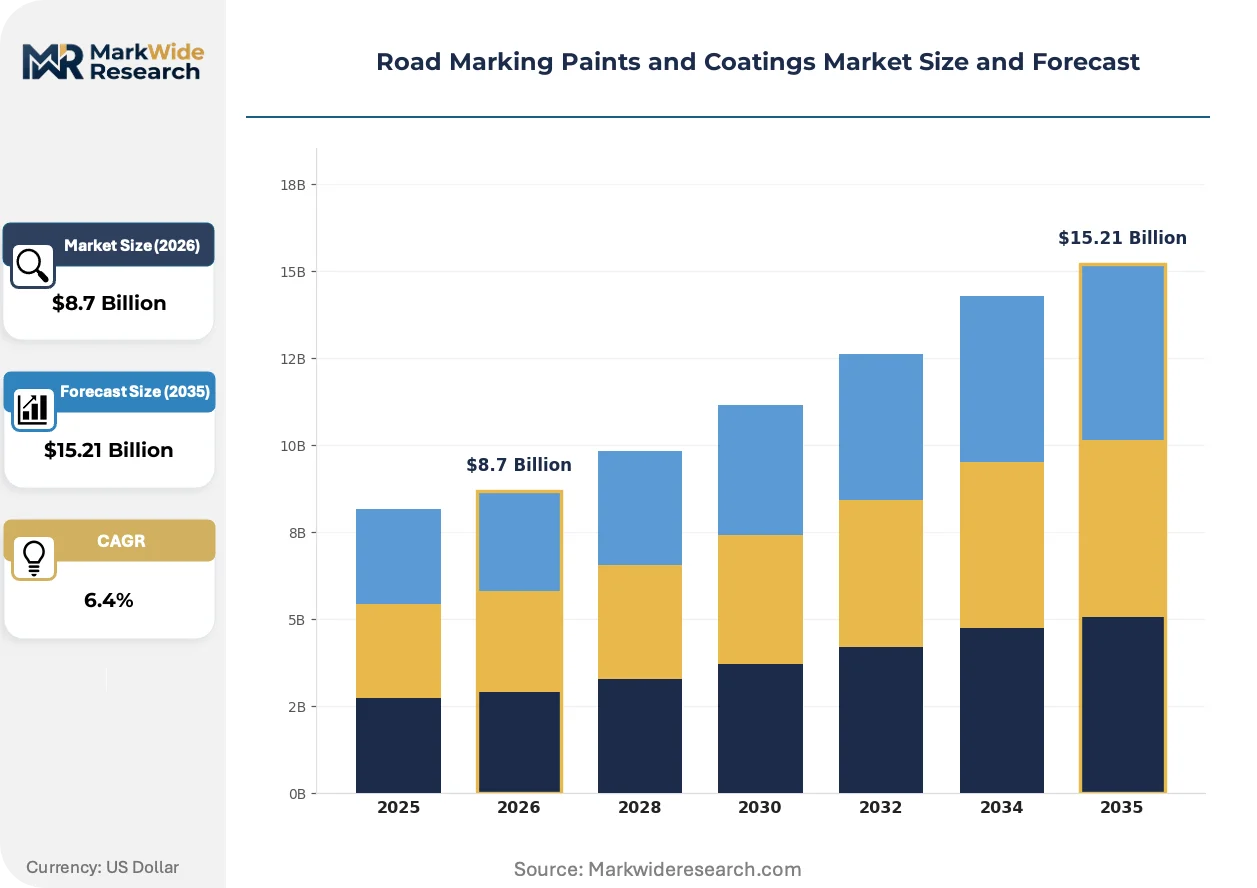
Market Dynamics
Thermoplastic resin supply concentration in East Asian petrochemical clusters is compressing formulation margins while EU Green Deal carbon accounting mandates restructure procurement qualification criteria for highway agencies.
Growth Catalysts
- EU Green Deal tender criteria:Carbon footprint disclosure requirements in German federal highway contracts advantage low-emission waterborne technologies over solvent-based alternatives.
- Expressway network expansion:Chinese provincial transport authorities prioritize durable road marking systems for new expressway construction in second-tier cities.
- Thermoplastic application speed:Two-minute dry times at 180–220°C enable lane reopening during compressed highway maintenance windows, reducing traffic disruption penalties.
Market Restraints
- Chromium pigment reformulation costs:ECHA REACH restrictions on yellow marking chemistries force complete system redesigns across EU member states.
- Glass bead supply concentration:Retroreflective bead production clusters in Chinese and US Midwest manufacturing zones create input cost volatility.
- Epoxy certification barriers:FAA certification timelines for airport runway formulations extend 18–24 months, freezing new entrant participation.
Strategic Opportunities
- Smart city integration:Embedded sensor-compatible marking substrates enable convergence with autonomous vehicle infrastructure in Singapore and Dubai pilot programs.
- Parking lot recurring revenue:Restriping cycles in commercial retail and logistics facilities generate stable margin pools independent of public infrastructure budgets.
- CSRD supplier qualification:EU sustainability disclosure rules create first-mover advantage for contractors with verified lifecycle assessment documentation.
Industry Challenges
- Applicator certification scarcity:Thermoplastic spray equipment operation requires specialized training that municipal workforces lack, constraining deployment speed.
- VOC compliance fragmentation:US state-level procurement specifications vary across California, Texas, and Northeast corridor markets, multiplying SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Marking Paints and Coatings Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Thermoplastic, Epoxy, Waterborne Application: Highways, Airports, Parking Lots, Municipal Roads End User: Government Agencies, Contractors, Private Enterprises, Infrastructure Developers Technology: Spray, Roll, Stencils, Hot Melt |
| Companies Covered | Sherwin-Williams Company, 3M Company, PPG Industries, Asian Paints, Geveko Markings, Ennis-Flint, Dow Inc., Berger Paints, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Marking Paints and Coatings Market Evolving Landscape
Waterborne chemistry advances and embedded sensor compatibility are restructuring competitive priorities across formulation portfolios and application equipment specifications.
Retroreflective glass bead integration with photoluminescent pigments is digitizing nighttime visibility performance in tunnel and urban canyon environments. Japanese expressway operators deploy these hybrid systems in Tokyo-Osaka corridor segments. The technology is digitizing safety assurance metrics for insurance risk modeling and infrastructure asset valuation.
EPA 40 CFR 59 Subpart D enforcement tightens VOC thresholds for federal highway eligibility, eliminating solvent-based alternatives from US procurement pools. Formulators accelerate waterborne acrylic and epoxy development to maintain contractor channel access. Airport runway segments face parallel FAA certification reviews that compress product development timelines.
Asset lifecycle contracting is displacing transactional material procurement in German and Dutch municipal markets. Highway agencies bundle marking application, maintenance, and performance guarantees into multi-year service agreements. This shift concentrates volume with vertically integrated contractors possessing in-house formulation and application capabilities.
Road Marking Paints and Coatings Market Segmentation
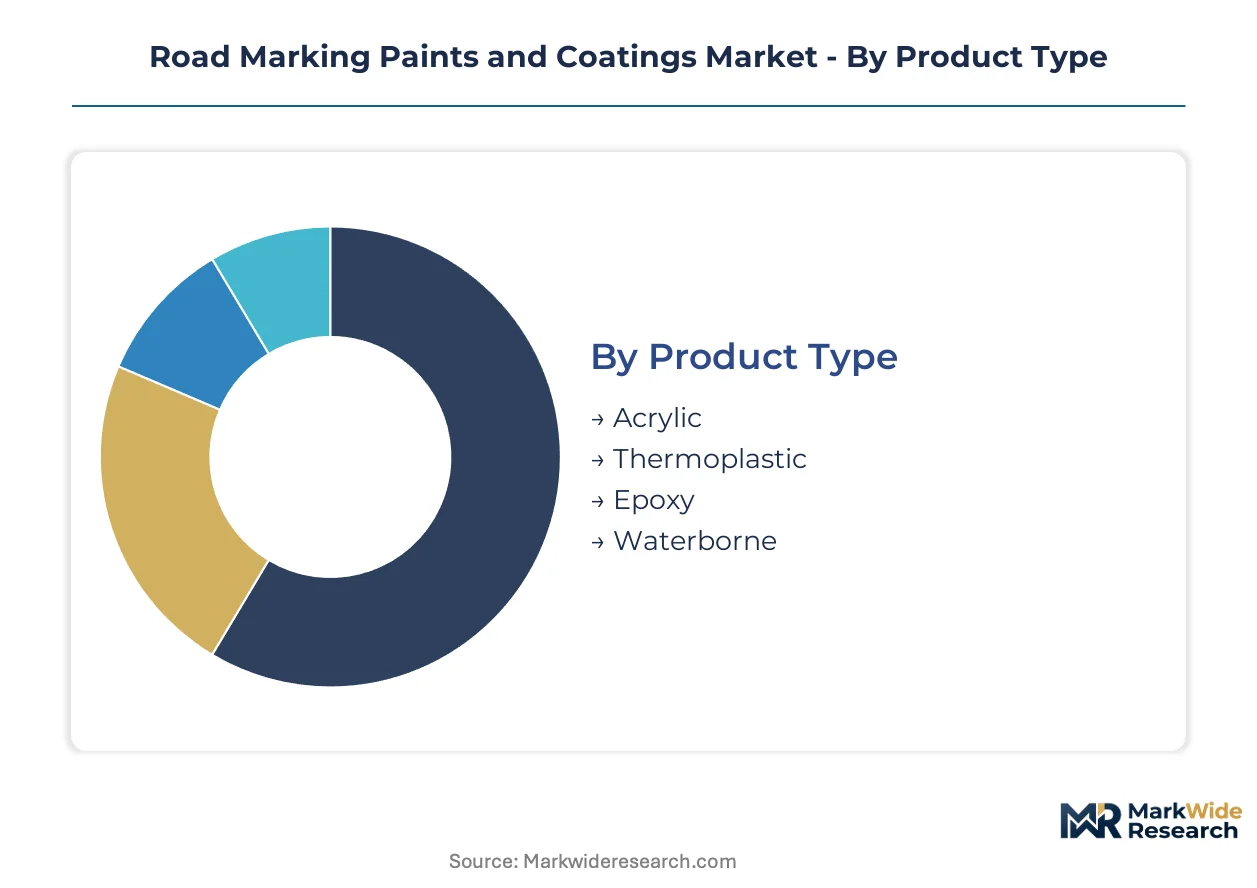
Segmentation in road marking paints and coatings reveals distinct margin profiles and service intensity requirements across formulation chemistries and installation methods. Specification diversity forces suppliers to maintain parallel certification tracks for thermoplastic, epoxy, and waterborne systems serving divergent end-use durability standards.
Product Type:
Thermoplastic formulations demand intensive after-sales service through specialized applicator training and equipment calibration support, while waterborne systems shift service burden toward compliance documentation and VOC certification maintenance.
- Thermoplastic:Hydrocarbon resin compositions incorporating glass beads achieve retroreflective performance with sub-two-minute dry times at 180–220°C application temperatures. German federal highway contracts under EU Green Deal procurement rules specify thermoplastic systems for high-traffic corridors where rapid lane reopening minimizes disruption penalties.
- Waterborne:Acrylic and epoxy emulsion chemistries operate at ambient temperatures with extended cure windows, reducing equipment capital requirements for municipal contractors. ECHA REACH restrictions on solvent emissions in EU member states accelerate specification shifts toward waterborne alternatives in European municipal tenders.
- Acrylic:Cost-optimized solvent and waterborne variants dominate tropical climate applications where UV degradation resistance determines lifecycle economics.
- Epoxy:Two-component systems command premium positioning in airport runway segments where FAA certification creates technical barriers to substitution.
Thermoplastic holds the largest share; momentum sits with waterborne as regulatory pressure intensifies.
Application:
Application segmentation maps directly to procurement authority structures and contract value concentration, with highway agencies and airport authorities operating distinct specification regimes.
- Highways:Federal and state transport agencies specify performance-guaranteed systems with 3–5 year durability warranties. Chinese provincial authorities prioritize durable markings for expressway expansion in second-tier cities, driving volume concentration.
- Airports:FAA certification requirements for runway markings enforce 18–24 month product qualification timelines, freezing formulation substitution and sustaining premium pricing structures.
- Parking Lots:Commercial retail and logistics facilities generate recurring restriping revenue through 12–18 month maintenance cycles independent of public infrastructure budgets.
- Municipal Roads:City-level procurement fragments across varying VOC thresholds and climate adaptation requirements, multiplying SKU complexity for national suppliers.
Highways generate the highest contract values; parking lots deliver the most predictable recurring margin streams.
End User:
End user segmentation reflects divergent technical capability and procurement sophistication, from specification-setting government engineers to price-sensitive private facility managers.
- Government Agencies:Federal highway administrations and transport departments embed lifecycle cost criteria and carbon disclosure requirements in tender evaluation, advantaging suppliers with verified LCA documentation.
- Contractors:Vertically integrated application firms with in-house formulation capabilities capture multi-year asset lifecycle contracts in German and Dutch municipal markets.
- Private Enterprises:Retail chains and logistics operators prioritize first-cost minimization in parking facility restriping, accepting shorter performance lifecycles.
- Infrastructure Developers:Build-operate-transfer concessionaires specify extended-durability systems to minimize maintenance cost exposure over 20–30 year franchise periods.
Government agencies set specification standards; infrastructure developers are expanding most quickly as public-private delivery models proliferate.
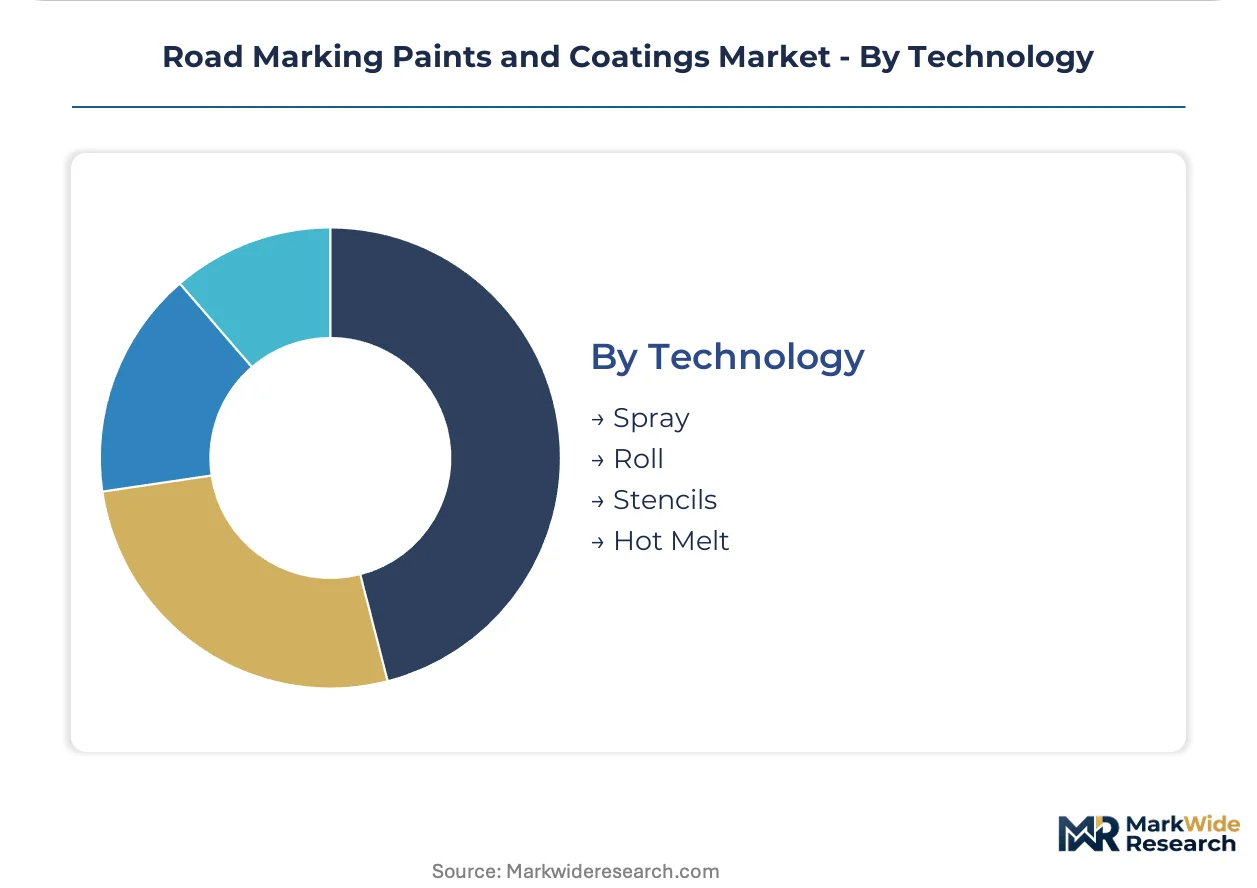
Technology:
Technology segmentation tracks equipment capital intensity and labor skill requirements, with hot melt and spray systems diverging in deployment economics.
- Hot Melt:Thermoplastic application at 180–220°C requires specialized spray equipment and certified operators, creating capability scarcity that constrains deployment speed in municipal markets.
- Spray:Ambient-cure waterborne and solvent systems deploy through conventional airless equipment, lowering barrier to entry for small contractors.
- Roll:Manual application persists in small-scale parking lot restriping and touch-up work where equipment mobilization costs exceed project value.
- Stencils:Template-based systems enable standardized symbol application for pedestrian crossings, bicycle lanes, and regulatory markings across diverse surface conditions.
Spray technology dominates installed base; hot melt commands the steepest expansion trajectory as highway agencies prioritize traffic disruption minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highway procurement authorities concentrate demand in Germany, China, and the United States, where federal infrastructure programs and expressway expansion create distinct specification environments for marking system suppliers.
Germany
Federal highway contracts prioritize thermoplastic systems with carbon footprint documentation under EU Green Deal tender criteria. ECHA REACH restrictions on chromium pigments force reformulation of yellow marking chemistries nationwide. Industrial clusters around Cologne and Hamburg host applicator training centers for specialized hot-melt equipment operation.
China
Provincial transport authorities in Jiangsu and Guangdong specify durable markings for expressway networks connecting second-tier cities. The Ministry of Ecology and Environment enforces dual carbon goals that advantage low-emission waterborne technologies in municipal tenders. Manufacturing concentration in the Yangtze River Delta supplies glass beads and hydrocarbon resins to domestic formulators.
United States
State DOTs in California, Texas, and the Northeast corridor operate divergent VOC thresholds that multiply SKU complexity for national suppliers. EPA 40 CFR 59 Subpart D enforcement eliminates solvent-based alternatives from federal highway procurement pools. Application contractors cluster in the Midwest manufacturing zone near retroreflective bead production facilities.
India
National highway expansion under the Bharatmala program drives specification of cost-optimized acrylic formulations for tropical UV degradation profiles. BIS standards for road marking materials create compliance entry barriers for imported systems. Manufacturing activity concentrates in Maharashtra and Gujarat where logistics hubs serve western and southern corridor projects.
Japan
Expressway operators in the Tokyo-Osaka corridor deploy photoluminescent hybrid markings for tunnel visibility assurance. METI promotes smart city infrastructure convergence through embedded sensor-compatible marking substrates. Industrial formulation capabilities cluster in the Chubu region around Nagoya petrochemical complexes.
Road Marking Paints and Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented municipal procurement and concentrated federal highway segments. The vendor base separates into three archetypes: diversified coatings conglomerates with distribution scale, regional formulation specialists with climate-adapted portfolios, and vertically integrated contractors capturing asset lifecycle contracts. Dominant competitive moves include backward integration into resin production and geographic expansion through applicator network partnerships.
Among North American coatings conglomerates, Sherwin-Williams Company and PPG Industries occupy positions spanning municipal road and airport runway specification tiers. Asian Paints exemplifies regional formulation specialization with cost-optimized acrylic systems. 3M Company anchors the retroreflective materials tier through glass bead and tape technologies that interface with marking system integrators.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| 3M Company |
| PPG Industries |
| Asian Paints |
| Geveko Markings |
| Ennis-Flint |
| Dow Inc. |
| Berger Paints |
| AkzoNobel |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta petrochemical clusters dictate hydrocarbon resin availability, concentrating formulation cost leverage among East Asian suppliers and compressing margins for European waterborne specialists facing EU Green Deal carbon accounting mandates.
Pricing Analysis
Cost-plus contracts with resin indexation dominate thermoplastic procurement, tying highway agency payments to fluctuating hydrocarbon feedstock benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified epoxy systems from municipal waterborne formulations and tropical-grade acrylics. Pricing pressure stems from chromium pigment reformulation costs under ECHA REACH restrictions. Private facility managers in parking lot segments exhibit highest price sensitivity, while airport authorities accept premium positioning for certified runway markings.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta resin compounders and US Midwest glass bead processors. Hydrocarbon resins, retroreflective glass beads, and titanium dioxide pigments anchor material dependencies. Single-source vulnerability clusters in Chinese bead production create input cost volatility. Distribution runs through applicator contractor networks that bundle formulation supply with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks highway maintenance budget cycles, with federal infrastructure stimulus programs creating procurement surges that favor contractors with pre-positioned resin inventories and certified applicator workforces.
For Market Incumbents: Entrench through captive supply of hydrocarbon resins and acquisition of regional applicator networks. Waterborne formulation specialists threaten solvent-based legacy positions as ECHA restrictions tighten. Certification investment in FAA runway systems preserves premium tier access.
For New Entrants and Emerging Players: Second-tier Chinese expressway corridors offer underpenetration for durable thermoplastic systems. Municipal parking lot restriping contracts provide lowest barrier to entry through conventional spray equipment. Target logistics facility managers with subscription-style maintenance bundling.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated contractors with in-house formulation and application capabilities. Five-to-ten year viability rests on carbon disclosure compliance infrastructure. Monitor EU member state CSRD implementation pace as inflection signal for supplier qualification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive hydrocarbon supply secures margin control against Yangtze River Delta price volatility. |
| Applicator Network Acquisition | Vertically integrated service bundling captures German asset lifecycle contract concentration. |
| FAA Certification Investment | Epoxy runway qualification creates 18-24 month barriers that freeze substitution threats. |
| CSRD Documentation Infrastructure | Verified lifecycle assessment capability qualifies suppliers for EU Green Deal tender evaluation. |
| Smart City Substrate Development | Embedded sensor compatibility positions markings for Singapore and Dubai autonomous vehicle pilots. |
Research Methodology
Desk research of customs trade databases, EPA enforcement records, and ECHA restriction filings preceded structured interviews with highway agency procurement officers, thermoplastic applicator contractors, resin plant managers, and airport engineering consultants. Primary fieldwork with municipal maintenance directors and commercial facility managers validated specification trends. Secondary sources included SEC 10-K filings of coatings conglomerates, German federal highway tender documentation, and Chinese provincial transport authority procurement announcements. Bottom-up volume estimates from application equipment deployment data triangulated against top-down construction spending forecasts.
Assumptions held fixed include ECHA REACH enforcement timelines and FAA certification protocol stability, while oil price volatility and highway maintenance budget allocations varied across sensitivity scenarios. Segmentation modeling spanned formulation chemistry, application method, end-use durability tier, and regional regulatory cluster. CAGRs derived from equipment installation rates and restriping cycle frequencies. Industry-specific inputs incorporated glass bead supply concentration indices and thermoplastic dry-time performance benchmarks.
Practitioners should monitor chromium pigment substitution progress and EU member state CSRD adoption speed for early signals of reformulation cost trajectories. Forecasts reflect assumptions about federal infrastructure program continuity and petrochemical feedstock price normalization. Quarterly review of highway agency tender awards and applicator certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Global Wood Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Germany Industrial Wood Coatings Market