
 Aircraft Paint Market | 2026-2036
Aircraft Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Paint Market Analysis
North American specialty chemical producers is realigning capacity toward aerospace-grade polyurethane resins as OEM build rates recover. PPG Industries, Inc. leverages its integrated supply chain from resin synthesis to approved applicator networks across multiple continents. Akzo Nobel N.V. sustains a dominant position in European MRO channels through its Sikkens Aerodur product architecture and EASA-certified technical service infrastructure. Sherwin-Williams Company anchors North American military aviation demand through long-term contracts with U.S. defense logistics agencies.
Aircraft paint comprises multi-layer coating systems—typically a chromate or non-chromate conversion coating, epoxy primer, and polyurethane topcoat—engineered to withstand thermal cycling, UV degradation, and hydraulic fluid exposure while maintaining aerodynamic smoothness and radar signature control. The polyurethane segment leads value generation due to its gloss retention and fuel-saving drag reduction properties on long-haul commercial jets. MROs represent the fastest-growing end-user category as aging narrow-body fleets require stripping and recoating at extended maintenance intervals. Spray coating technology dominates application methods, though powder coating advances for landing gear and interior components where edge coverage and chip resistance matter.
EPA regulations in the United States enforce National Emission Standards for Hazardous Air Pollutants at coating facilities, compelling manufacturers to reformulate toward compliant chemistries. EASA enforces REACH-aligned substance restrictions through its continuing airworthiness directives, affecting primer systems containing hexavalent chromium. OEMs and MROs must monitor evolving dual-certification requirements across FAA and EASA jurisdictions, as divergence in substance approval timelines threatens supply continuity for international operators.
Market Dynamics
REACH substance restrictions and EPA National Emission Standards for Hazardous Air Pollutants are forcing simultaneous reformulation of chromate primers and solvent-borne topcoats across dual-jurisdiction supply chains.
Growth Catalysts
- Fleet renewal cycles:Narrow-body replacement programs at Boeing and Airbus assembly lines in the United States and China are pulling coating procurement forward.
- EPA NESHAP enforcement:Coating facility compliance deadlines are accelerating adoption of waterborne polyurethane systems in North American MRO networks.
- Drag reduction specifications:Airlines are specifying gloss-retentive polyurethane topcoats for fuel efficiency gains on long-haul routes.
Market Restraints
- Titanium dioxide volatility:Pigment cost swings constrain margin stability for coating formulators serving price-locked military contracts.
- German resin concentration:Specialty polyurethane precursor supply concentrates among a handful of Rhine-Ruhr chemical producers.
- Hexavalent chromium phase-out:EASA continuing airworthiness directives are sunsetting proven primer chemistries before qualified alternatives achieve full qualification.
Strategic Opportunities
- India MRO expansion:Bangalore and Hyderabad maintenance hubs lack captive stripping and recoating capacity for incoming leased narrow-body fleets.
- Powder coating convergence:Electrostatic application technology is crossing over from automotive into landing gear and interior component finishing.
- EU Green Deal procurement rules:Publicly owned flag carriers face mandated sustainable coating specifications in tender documents.
Industry Challenges
- Applicator certification bottlenecks:FAA and EASA dual-qualified spray technicians remain scarce relative to recoating queue depth at major hubs.
- Legacy system integration:New waterborne primers require modified spray booth humidity controls incompatible with existing MRO infrastructure in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Paint Market |
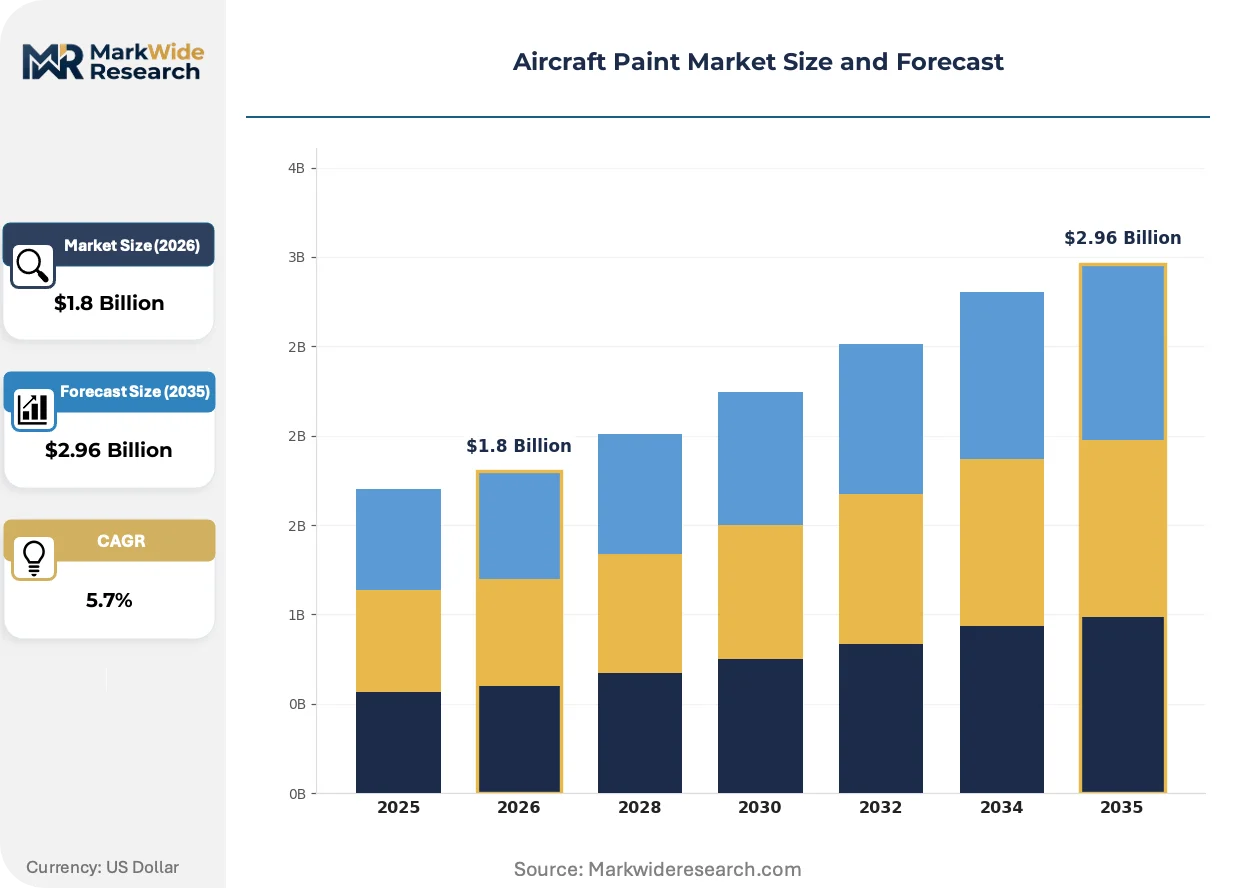
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Enamel Application: Commercial Aviation, Military Aviation, General Aviation, Aerospace End User: OEMs, MROs, Airlines, Private Operators Technology: Spray Coating, Brush Application, Electrodeposition, Powder Coating |
| Companies Covered | Mankiewicz Gebr. & Co., IHI Ionbond AG, PPG Industries, Inc., 3M Company, BASF SE, Akzo Nobel N.V., Hentzen Coatings, Inc., Axalta Coating Systems, Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Paint Market Emerging Trajectories
Coating system architecture is fragmenting into interchangeable sub-layers as certification timelines compress and airlines demand faster turnaround on custom liveries.
Multilayer coating stacks are modularizing around standardized epoxy primer platforms that accept interchangeable polyurethane topcoats without full system requalification. Low-cost carriers in Southeast Asia are adopting this approach to accelerate seasonal livery changes. The shift is compressing formulation lock-in periods and opening specification battles at the topcoat tier rather than the full system level.
EASA has aligned its continuing airworthiness directives with REACH Annex XVII restrictions on hexavalent chromium compounds, forcing primer reformulation across European MRO channels. Manufacturers must now maintain parallel qualified systems for FAA and EASA jurisdictions with divergent substance approval timelines. The regulatory friction most heavily affects international operators with mixed-registry fleets based in Germany and the United Kingdom.
Airline technical procurement teams are unbundling coating supply from airframe heavy maintenance contracts, creating direct specification authority previously held by MRO integrators. This pattern is most visible among Middle Eastern flag carriers with in-house engineering departments. The disintermediation is forcing coating manufacturers to build airline-facing technical service capabilities alongside traditional MRO distributor relationships.
Aircraft Paint Market Segmentation
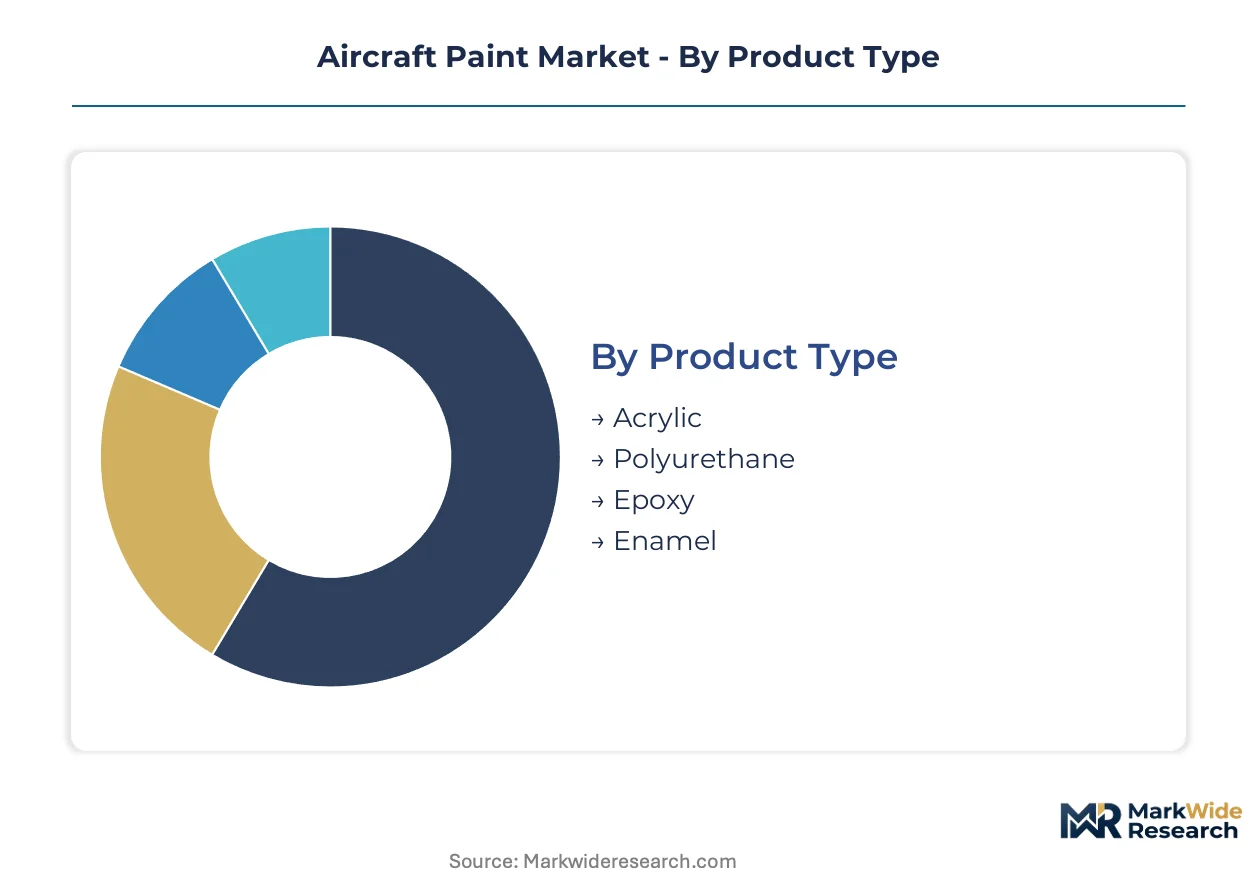
Aircraft paint procurement splits across four decision axes: chemistry selection determines regulatory compliance and durability; application scope dictates specification stringency; buyer type controls volume concentration and contract structure; application technology shapes capital requirements and throughput economics.
Product Type:
Buyer decisions here pivot on gloss retention requirements versus VOC compliance deadlines, with fuel-efficiency specifications increasingly tilting selection toward high-performance chemistries.
- Polyurethane:Dominant topcoat chemistry delivering exceptional gloss retention and aerodynamic smoothness for long-haul commercial jets. Airlines specify this chemistry for drag reduction gains on transoceanic routes, though EPA NESHAP enforcement is accelerating waterborne formulation adoption at US MRO facilities.
- Epoxy:Primer-layer foundation providing corrosion resistance and substrate adhesion across aluminum and composite airframes. OEM assembly lines in the United States and Germany pull concentrated volume as build rates recover, with hexavalent chromium phase-outs forcing reformulation investments.
- Acrylic:Lower-cost option with faster cure times for general aviation touch-up and interior component finishing where exterior durability demands are reduced.
- Enamel:Legacy chemistry persisting in military overhaul depots under grandfathered specifications, though new procurement increasingly specifies polyurethane systems.
Polyurethane leads on scale; epoxy leads on momentum as primer-layer reformulation cycles accelerate.
Application:
Specification intensity varies dramatically across these categories, with commercial aviation demanding the most extensive qualification documentation and military aviation imposing the longest contract lock-in periods.
- Commercial Aviation:Narrow-body and wide-body fleet operators specify multi-layer systems with EASA and FAA dual certification. Fleet renewal programs at Boeing and Airbus assembly lines concentrate procurement volume in the United States, China, and Germany.
- Military Aviation:Radar signature control and infrared suppression requirements drive specialized formulation development. Long-term supply agreements with defense logistics agencies in the United States anchor revenue stability for approved suppliers.
- General Aviation:Smaller volume, higher customization demand from private owners and charter operators with diverse livery preferences and less standardized maintenance intervals.
- Aerospace:Satellite and launch vehicle applications requiring thermal cycling resistance and extreme UV stability, with procurement concentrated among specialized contractors in the United States and France.
Commercial aviation dominates absolute volume; military aviation delivers the most predictable contract tenure.
End User:
Procurement authority is shifting as airlines build in-house technical capabilities, unbundling coating specification from heavy maintenance contracts previously controlled by MRO integrators.
- MROs:Maintenance, repair, and overhaul facilities execute stripping and recoating cycles for aging narrow-body fleets. Bangalore and Hyderabad hubs in India lack captive capacity for incoming leased aircraft, creating expansion opportunities.
- OEMs:Original equipment manufacturers specify initial coating systems at assembly, with build rate recovery at Boeing and Airbus facilities pulling resin procurement forward.
- Airlines:Technical procurement teams at Middle Eastern flag carriers are gaining direct specification authority, forcing manufacturers to build airline-facing service capabilities.
- Private Operators:Fragmented demand with high customization requirements, shorter lead times, and price sensitivity distinct from fleet operator procurement patterns.
MROs are expanding most quickly as fleet age profiles deepen recoating queues; OEMs retain the highest per-unit value capture.
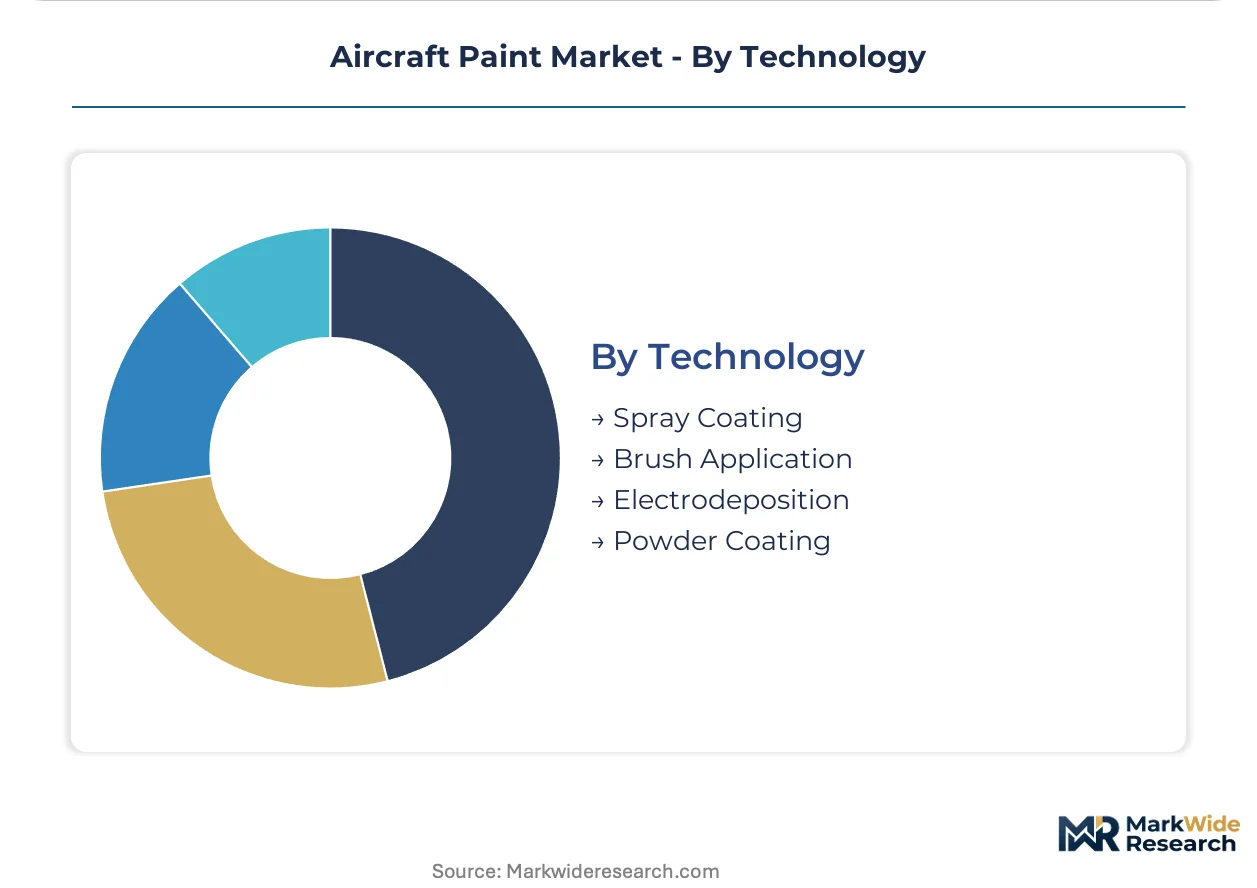
Technology:
Capital investment requirements and throughput economics separate these methods, with spray coating infrastructure dominating existing MRO footprints while powder coating gains traction for component-level applications.
- Spray Coating:Dominant application method for full airframe finishing, requiring controlled humidity environments and FAA or EASA certified technician pools that remain scarce relative to demand.
- Powder Coating:Electrostatic application crossing from automotive into landing gear and interior components where edge coverage and chip resistance outweigh cosmetic finish requirements.
- Brush Application:Touch-up and repair work on limited surface areas, retaining relevance for field maintenance and AOG (aircraft on ground) recovery scenarios.
- Electrodeposition:Automated primer application for high-volume component manufacturing, with limited airframe-scale deployment due to tank size constraints.
Spray coating leads on installed base; powder coating shows the steepest expansion trajectory as component finishing specifications evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as coating formulators migrate toward jurisdictions with phased compliance deadlines. The cost-of-compliance gap between EPA NESHAP enforcement in the United States and REACH-aligned EASA directives in Europe is accelerating capacity realignment toward Asian assembly corridors.
United States
Boeing assembly lines in Washington and South Carolina pull concentrated polyurethane procurement as narrow-body build rates recover. EPA National Emission Standards for Hazardous Air Pollutants enforce VOC limits at coating facilities, compelling MRO networks toward waterborne system adoption. The Southeast maintenance corridor—Atlanta and Miami hubs—faces certified technician scarcity relative to recoating queue depth.
Germany
Airbus Hamburg and Bremen facilities anchor European OEM demand for chromate-free primer systems under EASA continuing airworthiness directives. REACH Annex XVII restrictions on hexavalent chromium compounds are sunsetting legacy chemistries before qualified alternatives achieve full qualification. The Rhine-Ruhr chemical cluster concentrates specialty polyurethane precursor supply among a handful of producers.
China
COMAC Shanghai assembly and Tianjin maintenance hubs are expanding coating procurement as domestic narrow-body fleets mature. MIIT emission standards for industrial coating operations are tightening faster than MRO infrastructure can adapt spray booth humidity controls. The Yangtze River Delta corridor is capturing redirected capacity from European formulators facing accelerated substance restrictions.
India
Bangalore and Hyderabad maintenance hubs lack captive stripping and recoating capacity for incoming leased narrow-body fleets. DGFT import licensing frameworks for aerospace chemicals create compliance friction for MRO operators sourcing approved systems. The Delhi-Mumbai industrial corridor is attracting investment from coating distributors seeking to bypass European regulatory bottlenecks.
United Kingdom
Mixed-registry fleet operators based in London and Manchester face dual-certification complexity as FAA and EASA substance approval timelines diverge. The UK's post-Brexit chemicals regulatory framework is maintaining REACH alignment while creating separate registration requirements for imported coating components. The Midlands aerospace cluster is specializing in military overhaul contracts with grandfathered enamel specifications.
Aircraft Paint Market Vendor Landscape
United States producers anchor the scale-driven tier; European specialists hold regulatory-certification advantages. The vendor base concentrates around integrated resin-to-applicator supply chains and EASA-certified technical service infrastructures. Three archetypes dominate: diversified chemical conglomerates with aerospace divisions, pure-play coating formulators with MRO channel dominance, and materials science conglomerates with adjacent aerospace portfolios. Competitive moves center on backward integration into polyurethane resin production and geographic expansion into Indian MRO corridors.
Among diversified chemical conglomerates, PPG Industries, Inc. and BASF SE exemplify integrated supply chain architectures spanning resin synthesis to approved applicator networks. Akzo Nobel N.V. occupies a position within the regulatory-specialist tier, leveraging EASA-certified technical service infrastructure. These three entities represent distinct competitive vectors: scale-backed procurement power, regulatory navigation capability, and channel-specific technical service depth.
| Leading Market Players |
|---|
| Mankiewicz Gebr. & Co. |
| IHI Ionbond AG |
| PPG Industries, Inc. |
| 3M Company |
| BASF SE |
| Akzo Nobel N.V. |
| Hentzen Coatings, Inc. |
| Axalta Coating Systems |
| Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
EPA National Emission Standards for Hazardous Air Pollutants and REACH-aligned EASA directives gate both qualified supply access and premium-tier pricing power, as coating formulators must maintain dual-jurisdiction certification portfolios to serve international operators with mixed-registry fleets.
Pricing Analysis
Distributor margins in the MRO channel typically run higher than direct-to-OEM contract pricing due to technical service bundling and applicator certification support. Three-tier pricing structure across aerospace-grade polyurethane systems, standard epoxy primers, and general aviation acrylics separates specification tiers by certification grade and volume commitment. Cost compression in military contract tiers is intensifying because titanium dioxide pigment volatility collides with price-locked long-term agreements. Low-cost carriers and regional operators exhibit the highest price sensitivity, while flag carriers with in-house engineering prioritize fuel-efficiency performance over unit cost.
Supply Chain Analysis
Stripping and recoating waste streams require specialized hazardous material handling infrastructure that constrains MRO site selection and adds reverse-logistics cost layers to total coating economics. Specialty polyurethane precursor supply concentrates in Germany, the United States, and China, with the Rhine-Ruhr chemical cluster anchoring resin production for European OEM assembly lines. Formulation draws from titanium dioxide pigments, isocyanate curing agents, and chromate-free corrosion inhibitors. Single-source vulnerability runs through certified applicator technician pools, particularly for FAA-EASA dual-qualified spray operators. Distribution runs through approved MRO networks and OEM-integrated supply chains with direct airline specification authority emerging as a parallel channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aircraft paint hinges on the shift from solvent-borne to waterborne polyurethane systems, where regulatory compliance premiums offset reformulation investment and captive resin production captures upstream value.
For Market Incumbents: To counter applicator certification bottlenecks, deepen captive technical training infrastructure and secure exclusive technician pipeline agreements with FAA-EASA dual-qualified programs. Backward integration into aerospace-grade polyurethane resin production insulates margin pressure from German precursor supply concentration and enables faster reformulation cycles under divergent EPA-EASA substance approval timelines. For New Entrants and Emerging Players: The price-point gap between premium aerospace-grade systems and economy-tier general aviation coatings creates entry space for mid-tier polyurethane formulators with MRO channel partnerships. Target the India MRO corridor, specifically Bangalore and Hyderabad stripping and recoating capacity shortages for leased narrow-body fleets. Build airline-facing technical service capabilities to bypass incumbent MRO distributor lock-in as procurement authority shifts to flag carrier engineering departments. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play coating formulators without captive resin production, where regulatory compliance costs have compressed multiples below integrated chemical conglomerates. Long-term viability favors targets with EASA-certified technical service infrastructure and established presence in Asian assembly corridors. Monitor divergence in FAA-EASA substance approval timelines as an inflection signal for supply chain disruption and acquisition opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Resin Production | Captures upstream margin and accelerates reformulation response to EPA-EASA regulatory divergence. |
| Dual-Jurisdiction Certification Investment | Maintains supply continuity for international operators with mixed-registry fleets based in Germany and the United Kingdom. |
| India MRO Corridor Capacity Buildout | Addresses captive stripping and recoating shortages for incoming leased narrow-body fleets in Bangalore and Hyderabad. |
| Airline-Facing Technical Service Development | Aligns with procurement authority shift from MRO integrators to Middle Eastern flag carrier engineering departments. |
| Waterborne System Portfolio Expansion | Positions formulators for EPA NESHAP compliance deadlines accelerating adoption across North American MRO networks. |
Methodological Framework
Multiple input streams — primary interviews with coating formulators, MRO procurement leads, airline technical directors, and regulatory compliance officers; secondary validation through EASA continuing airworthiness directives, EPA NESHAP enforcement records, OEM build rate disclosures, and aerospace chemical trade data; plus customs and import licensing frameworks — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical volume trajectories were cross-referenced against expert panel assessments of fleet renewal timing and regulatory compliance deadlines across the analysis window. Segmentation modeling incorporated chemistry selection, application scope, buyer type, and technology dimensions with CAGRs derived from build rate projections and recoating interval assumptions. Forecast inputs included narrow-body fleet age profiles, MRO capacity expansion plans, and substance restriction phase-out schedules.
Caveats apply where divergence in FAA-EASA substance approval timelines, titanium dioxide supply disruptions, or MRO infrastructure adaptation lags could materially shift the outlook. Practitioners should monitor certified technician pipeline development and waterborne system qualification progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Water Color Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Global Thinners and Paint Strippers Market