
 Paint Mixing Market | 2026-2036
Paint Mixing Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Mixing Market Analytics
Asian coating compounders is rebalancing capacity toward low-VOC formulations as environmental enforcement tightens. Graco Inc. leverages its fluid handling technology leadership across automotive and industrial end uses. Netzsch anchors European precision grinding and dispersion equipment supply. Hockmeyer Equipment Corporation specializes in immersion mill systems for high-solids paint production.
Paint mixing encompasses the mechanical blending of pigments, resins, solvents, and additives to achieve specified color, viscosity, and performance characteristics, typically requiring controlled shear rates between 1000-5000 rpm for uniform particle distribution. The process serves architectural, industrial, and automotive coating applications where batch consistency determines finish quality and regulatory compliance. Water-based paints command expanding share as VOC restrictions harden, though oil-based formulations retain margin density in marine and specialty protective segments. Architectural coatings generate the largest volume pool, while automotive finishes concentrate value through precision color-matching requirements and just-in-time delivery protocols.
EPA oversees VOC emission limits under the National Emission Standards for Hazardous Air Pollutants, compelling equipment upgrades across US paint production facilities. REACH registration requirements in Europe redirect formulation chemistry toward pre-registered substance lists, reshaping raw material procurement. China's MEE enforces GB standards on industrial coating emissions, accelerating water-based technology substitution. Stakeholders must weigh capital allocation between incremental equipment upgrades and full process reconfiguration as regulatory thresholds tighten across their operating geographies.
Market Dynamics
Water-based paint formulation mandates are compressing equipment replacement cycles across coating production facilities, forcing capital redeployment from solvent recovery systems toward low-VOC mixing infrastructure.
Growth Catalysts
- Automotive refinishing demand:Collision repair shops are building in-house color-matching laboratories to reduce third-party dependency and accelerate turnaround times.
- REACH substance registration:Pre-registered chemical lists under ECHA requirements are redirecting European formulation chemistry toward compliant raw material baskets.
- Industrial coating emission standards:China's MEE enforcement of GB standards on VOC output is accelerating water-based technology substitution across manufacturing provinces.
Market Restraints
- Titanium dioxide price volatility:Pigment cost swings compress margin predictability for architectural coating compounders operating on fixed-price contracts.
- Precision grinding equipment concentration:European dispersion machinery supply tightens around specialized German and Italian equipment houses.
- High-solids formulation limits:Viscosity management constraints restrict water-based alternatives in marine protective applications where oil-based chemistry retains performance advantages.
Strategic Opportunities
- India industrial corridor expansion:Gujarat and Maharashtra manufacturing clusters are upgrading coating facilities under BIS environmental compliance timelines.
- On-demand tinting systems:Point-of-sale colorant dispensing is displacing centralized batch production in retail paint distribution channels.
- Dual carbon policy alignment:China's carbon intensity targets create procurement preference for energy-efficient mixing equipment with regenerative drive systems.
Industry Challenges
- Colorimetric technician scarcity:Spectrophotometer operation and color formulation expertise gaps constrain automotive refinishing shop expansion plans.
- Legacy solvent infrastructure strandedness:Existing explosion-proof mixing vessels and recovery systems face accelerated obsolescence under tightening VOC thresholds.
- Cross-jurisdictional certification complexity:Divergent EPA, REACH, and GB standard compliance requirements multiply testing burden for multinational coating suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Mixing Market |
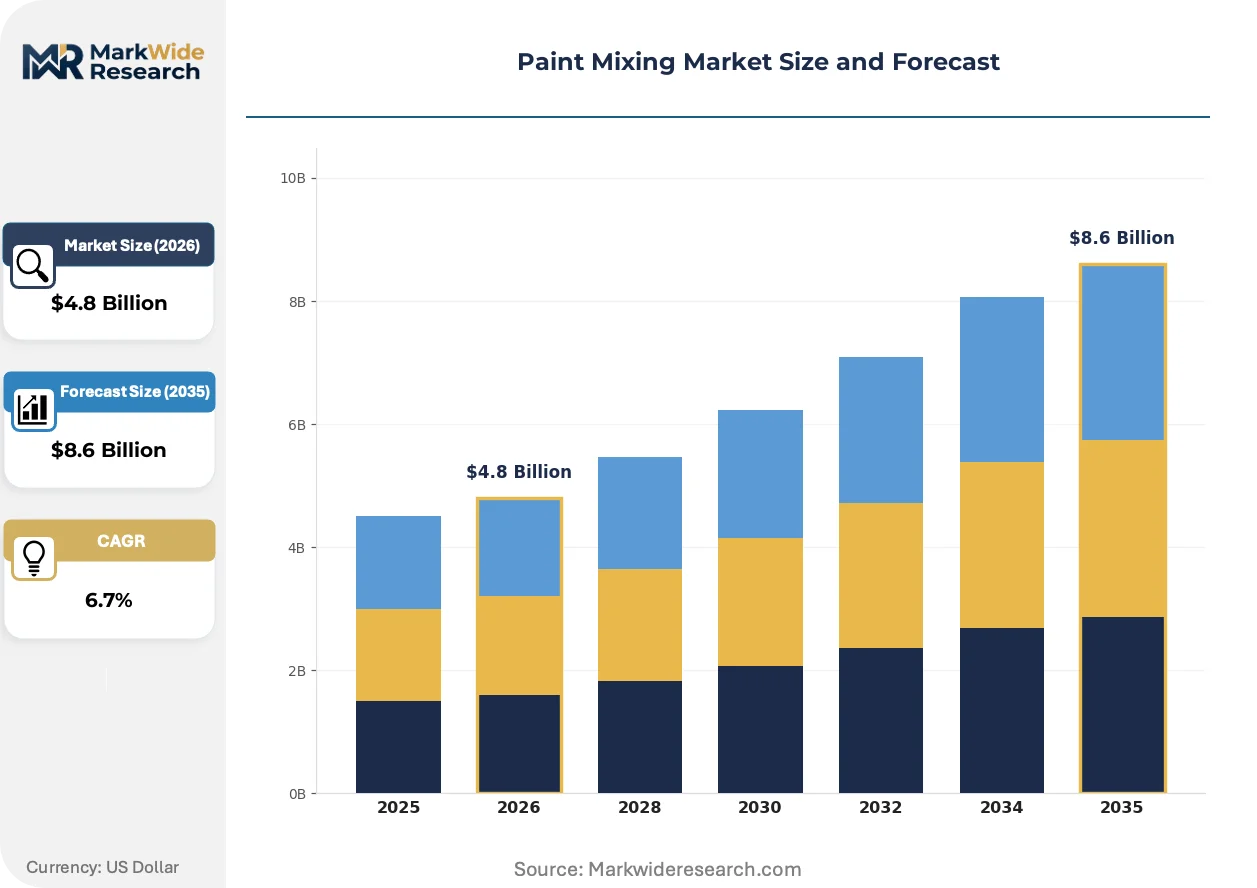
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Paints, Water-Based Paints, Oil-Based Paints, Specialty Paints Application: Architectural Coatings, Industrial Coatings, Automotive Finishes, Marine Coatings End User: Contractors, Homeowners, Manufacturers, Artisans Distribution Channel: Online Retail, Specialty Stores, Wholesale Suppliers, Direct Sales |
| Companies Covered | DynaMix, Charles Ross & Son, Hockmeyer Equipment Corporation, Graco Inc., Farfly Machinery, Netzsch, J. Wagner GmbH, Nordson Corporation, Brillux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Mixing Market Evolving Landscape
Digital color-matching platforms and inline viscosity monitoring are compressing batch variation tolerances while regulatory emission calculators reshape equipment specification criteria across coating production.
Automated spectrophotometric dispensing is consolidating quality control workflows in automotive refinishing and architectural coating operations. Tier-one collision repair networks and national retail paint chains are deploying closed-loop tinting systems that reduce human color-matching intervention. This consolidation is compressing the technician-to-output ratio and enabling just-in-time pigment inventory models.
EPA National Emission Standards for Hazardous Air Pollutants are mandating vapor recovery and leak detection upgrades across US paint production facilities. Equipment procurement specifications now incorporate continuous emission monitoring as a baseline requirement. Architectural coating manufacturers in California and Texas are retrofitting mixing vessels with sealed agitator systems to meet localized air district rules.
Just-in-time colorant procurement is replacing bulk pigment stocking among mid-size industrial coating compounders. Automotive OEM approved supplier programs are consolidating purchase orders toward vendors with integrated mixing and testing capabilities. This pattern concentrates procurement leverage in Germany's automotive supply corridor and China's Yangtze River Delta manufacturing belt.
Paint Mixing Market Segmentation
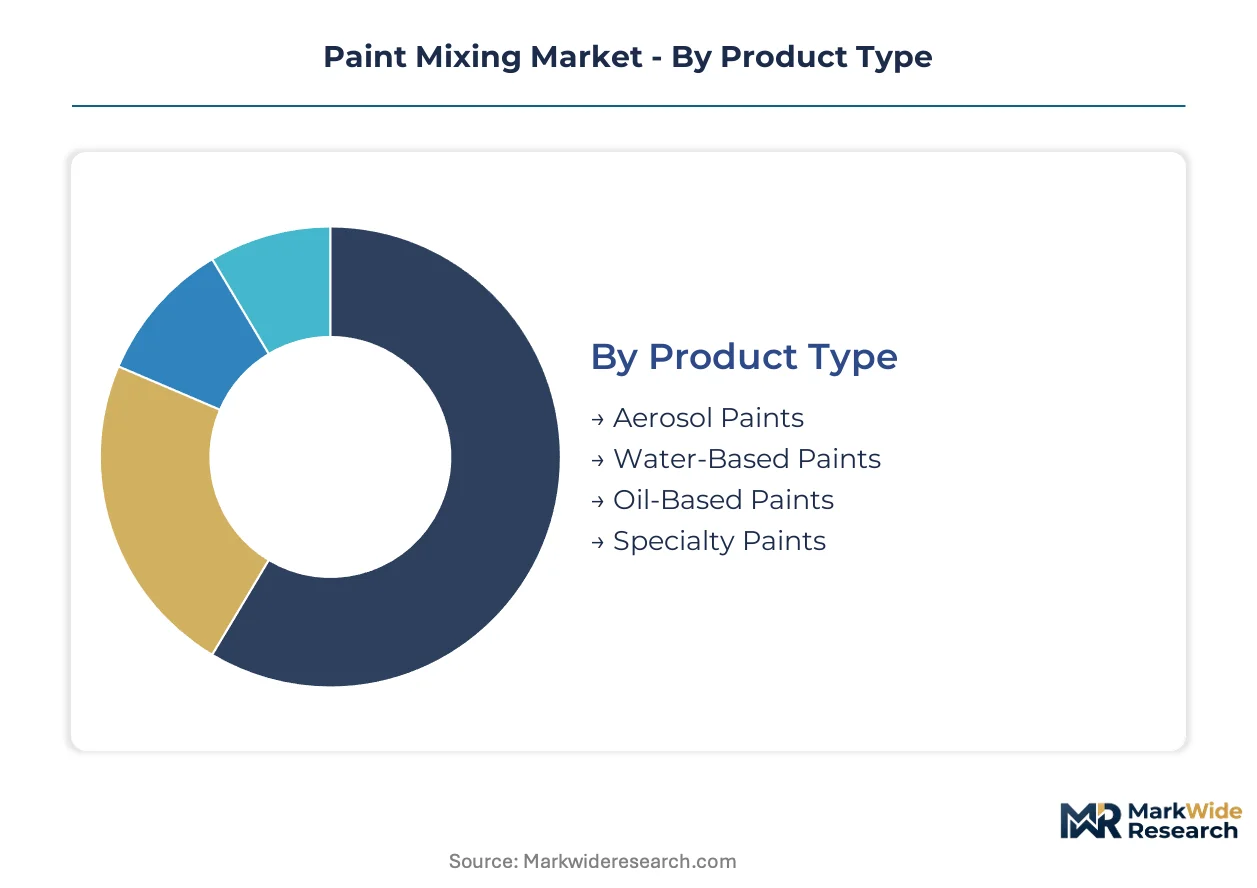
Paint mixing equipment specifications diverge sharply across formulation chemistries and end-use precision requirements. Segmentation reveals where capital investment concentrates versus where margin compression threatens equipment suppliers.
Product Type:
Standalone mixing systems dominate high-volume water-based production, while embedded dispersion units integrate into continuous manufacturing lines for specialty formulations.
- Water-Based Paints:Low-VOC formulations require controlled shear mixing between 1000-3000 rpm to prevent pigment agglomeration while maintaining viscosity stability. German automotive OEMs and China's Yangtze River Delta manufacturing belt are driving demand for explosion-proof water-based systems as MEE enforcement tightens.
- Specialty Paints:High-performance coatings for aerospace and electronics demand precision temperature-controlled mixing vessels with nitrogen blanketing capabilities. California's architectural specification market and Texas industrial corridors concentrate procurement for these premium systems.
- Aerosol Paints:Propellant-blending operations use pressure-rated mixing chambers with inline homogenization for uniform particle suspension.
- Oil-Based Paints:Solvent-handling infrastructure faces accelerated obsolescence under EPA NESHAP requirements, constraining replacement demand to marine and protective segments.
Water-based systems lead volumes today; specialty paint equipment is gaining share fastest.
Application:
Cost tier stratification separates high-precision automotive installations from volume-driven architectural coating operations.
- Automotive Finishes:Spectrophotometric color-matching integration demands mixing vessels with sub-batch tolerance control and automated viscosity feedback loops. Collision repair networks across Germany's automotive supply corridor are building in-house laboratories to reduce third-party dependency.
- Architectural Coatings:Batch consistency at 5000+ liter scale drives demand for high-torque agitator systems with variable frequency drives. India's Gujarat and Maharashtra manufacturing clusters are upgrading facilities under BIS environmental compliance timelines.
- Industrial Coatings:Protective formulations for infrastructure and machinery require corrosion-resistant mixing vessel construction with heated jacketing for high-solids processing.
- Marine Coatings:Biofouling-resistant formulations retain oil-based chemistry advantages, limiting water-based substitution despite regulatory pressure.
Architectural coatings anchor volume demand; automotive finishes command the steepest expansion trajectory in value terms.
End User:
Customer type determines equipment scale and service intensity, from homeowner tinting machines to manufacturer-integrated production lines.
- Manufacturers:Integrated coating compounders operate continuous mixing trains with inline quality monitoring and automated batch documentation for regulatory traceability.
- Contractors:Mobile mixing units with portable pigment dispensing support on-site color matching for commercial and residential projects.
- Artisans:Small-batch benchtop mixers serve custom furniture restoration and heritage conservation applications with low throughput but high margin.
- Homeowners:Point-of-sale tinting systems at retail chains displace centralized production for consumer architectural coatings.
Manufacturers absorb the largest equipment investment; contractor segment procurement is climbing the fastest as service models proliferate.
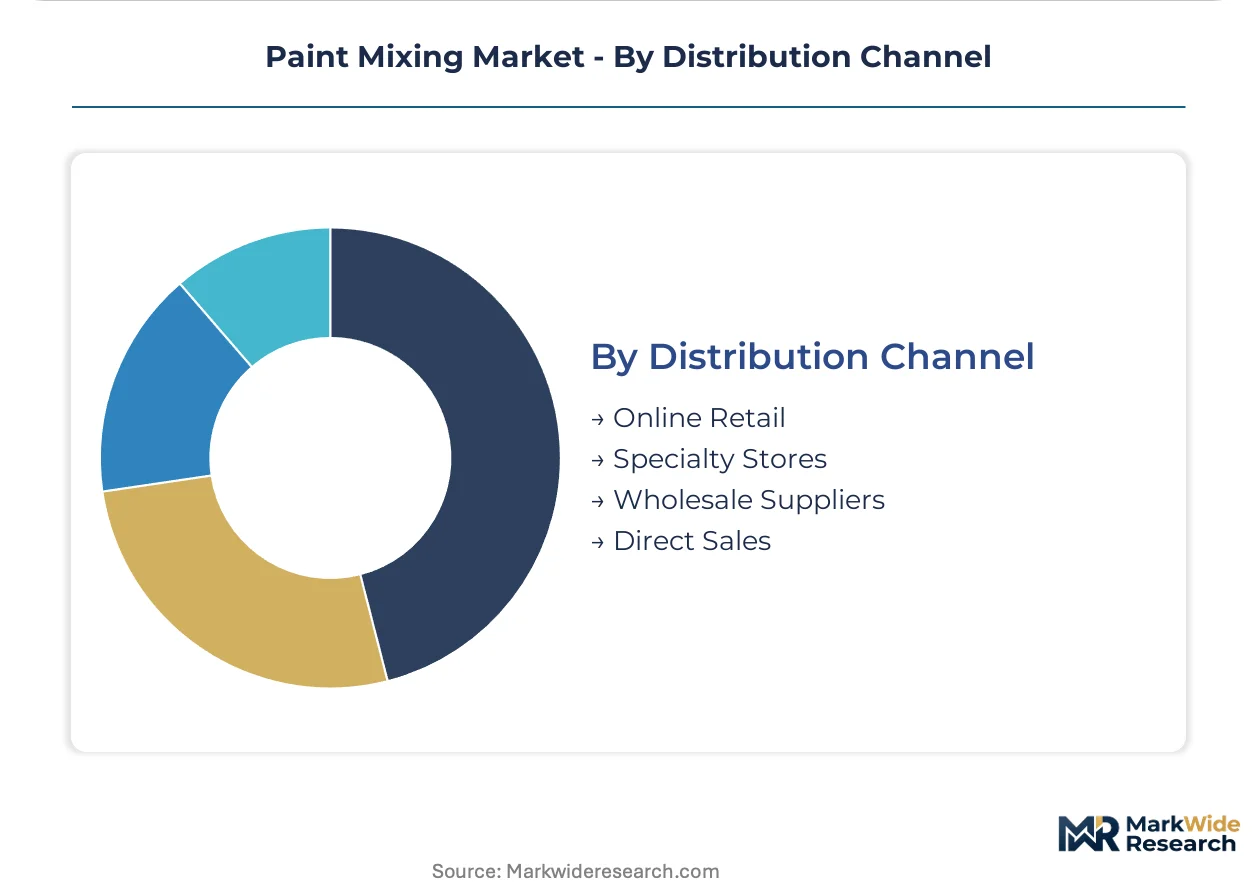
Distribution Channel:
Supply concentration favors direct relationships for complex installations, while commoditized equipment flows through wholesale intermediaries.
- Direct Sales:Graco and Netzsch maintain field engineering teams for turnkey mixing system commissioning and regulatory compliance documentation.
- Wholesale Suppliers:Distributor networks inventory standard agitator motors and vessel components for maintenance replacement cycles.
- Specialty Stores:Regional equipment houses serve mid-size compounders with configured mixing packages and local service support.
- Online Retail:E-commerce channels capture small-batch mixing accessories and replacement parts for artisan and contractor segments.
Direct sales dominate project value; online retail channels are expanding most quickly in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions where environmental enforcement creates first-mover advantages in low-VOC equipment installation, compressing the cost-of-compliance gap between early adopters and laggard facilities.
United States
Automotive refinishing networks and industrial coating compounders drive equipment procurement as EPA NESHAP mandates vapor recovery upgrades. California's South Coast Air Quality Management District imposes localized emission thresholds that exceed federal baselines. Dallas-Fort Worth and Houston industrial corridors concentrate demand for explosion-proof mixing vessels serving petrochemical protective coatings.
Germany
Precision automotive OEM supply chains and heritage architectural restoration sustain premium equipment demand. ECHA REACH substance registration redirects formulation chemistry toward pre-registered raw material baskets. Bavaria's automotive supply corridor and North Rhine-Westphalia's chemical industry cluster anchor European dispersion machinery procurement.
China
Yangtze River Delta manufacturing belt and Pearl River Delta export coating facilities scale water-based production lines. MEE enforcement of GB standards on industrial VOC emissions accelerates solvent infrastructure replacement. Suzhou and Dongguan industrial parks concentrate demand for energy-efficient mixing systems aligned with dual carbon policy targets.
India
Gujarat and Maharashtra manufacturing clusters upgrade coating facilities under BIS environmental compliance timelines. Automotive OEM localization programs and infrastructure protective coatings expand batch production capacity. Mumbai-Pune industrial corridor and Ahmedabad chemical belt drive procurement of high-torque agitator systems for architectural coating volumes.
Japan
Automotive refinishing precision requirements and electronics-grade specialty coatings sustain premium equipment demand. METI industrial efficiency standards favor regenerative drive systems in mixing equipment specification. Kansai manufacturing belt and Chubu industrial corridor concentrate procurement for nitrogen-blanketed precision mixing vessels.
Paint Mixing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and service-integrated configurations to bypass capital-intensive installed bases. Market structure consolidates around fluid handling specialists, precision grinding houses, and regional fabrication shops serving distinct formulation chemistry requirements. Strategic archetypes include integrated dispersion technology providers, automotive-focused system integrators, and commodity agitator fabricators. Dominant competitive moves center on regulatory compliance documentation bundling and energy-efficient drive system differentiation.
Among Germany-based precision equipment houses, Netzsch and J. Wagner GmbH exemplify the European dispersion machinery archetype. Graco Inc. represents the fluid handling technology tier with cross-sector automotive and industrial positioning. Hockmeyer Equipment Corporation occupies a specialist position within immersion mill system configuration for high-solids production environments.
| Leading Market Players |
|---|
| DynaMix |
| Charles Ross & Son |
| Hockmeyer Equipment Corporation |
| Graco Inc. |
| Farfly Machinery |
| Netzsch |
| J. Wagner GmbH |
| Nordson Corporation |
| Brillux |
| Others |
Value Network & Pricing Analysis
Automotive refinishing shop procurement consolidation toward integrated mixing and testing capabilities is forcing equipment suppliers to bundle regulatory compliance documentation and after-sales service, compressing channel margins and elevating price transparency across tier-one collision repair networks.
Pricing Analysis
Distributor margin layers absorb 15-25 points between German precision equipment houses and end-user compounders, with direct-to-OEM channels commanding steepest discounts for volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-blanketed precision vessels from modular water-based systems and commodity agitator components. Cost compression in standard-tier equipment is intensifying because Chinese manufacturers are scaling regenerative drive production. Contractor segments exhibit highest price sensitivity, while automotive OEM approved supplier programs prioritize certification tier over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Germany's automotive supply corridor and China's Yangtze River Delta manufacturing belt, while wholesale distributors inventory maintenance components for mid-size compounders. Precision grinding equipment concentrates in Germany and Italy, with motor and drive assemblies sourcing from Japan and Taiwan. Supply chain risk hinges on single-source vulnerability for explosion-proof vessel certification from specialized European testing houses. Distribution runs through field engineering teams for turnkey commissioning, regional equipment houses for configured packages, and e-commerce for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paint mixing equipment functions as a stable compounder anchored by regulatory-driven replacement cycles, with water-based formulation mandates ensuring sustained capital deployment regardless of macroeconomic volatility.
For Market Incumbents: Extend service-integrated offerings to capture stranded solvent infrastructure replacement demand, embedding continuous emission monitoring and regulatory documentation into long-term maintenance contracts. Backward integration into precision grinding component supply insulates margin pressure from European equipment house concentration. Prioritize energy-efficient drive system certification to align with China's dual carbon procurement preferences.
For New Entrants and Emerging Players: Capture India's Gujarat and Maharashtra manufacturing cluster upgrade cycle by configuring high-torque agitator systems for BIS environmental compliance timelines. Artisan and heritage restoration segments remain underpenetrated, offering premium pricing for small-batch benchtop mixers with nitrogen blanketing. Pursue point-of-sale tinting system partnerships with national retail paint chains to bypass capital-intensive production line competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with modular equipment specialists serving contractor mobile mixing and on-demand tinting applications. The five-to-ten year viability window favors targets with embedded regulatory compliance software and aftermarket service density. Monitor MEE enforcement intensity in China's Pearl River Delta as inflection indicator for water-based equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Bundling | EPA NESHAP and REACH documentation integration secures automotive OEM approved supplier status. |
| Energy-Efficient Drive Development | Regenerative systems align with China's dual carbon procurement preferences in Yangtze River Delta. |
| Point-of-Sale Tinting Expansion | Closed-loop colorant dispensing displaces centralized batch production in retail distribution channels. |
| Backward Integration into Precision Grinding | In-house dispersion machinery production reduces dependency on concentrated German and Italian supply. |
| Mobile Mixing Unit Configuration | Portable pigment dispensing systems capture contractor segment procurement growth in commercial projects. |
Research Methodology
Direct dialogue with plant managers at coating compounders, procurement leads at automotive refinishing networks, technical R&D directors at dispersion equipment manufacturers, and aftermarket service heads at fluid handling specialists grounded qualitative assessment. Secondary validation drew from EPA NESHAP regulatory filings, ECHA REACH substance registration databases, China MEE GB standard enforcement records, and SEC 10-K disclosures from listed equipment suppliers. Bottom-up equipment shipment analysis and top-down coating production capacity modeling enabled triangulation across segmentation dimensions.
Bottom-up volume estimates aggregated water-based, specialty, aerosol, and oil-based paint mixing system shipments by torque rating and vessel capacity, cross-referenced against top-down coating production forecasts from automotive, architectural, industrial, and marine end uses. Segmentation modeling incorporated formulation chemistry, application precision requirements, end-user scale, and distribution channel structure. CAGRs were derived from regression analysis against regulatory compliance timeline acceleration and OEM localization program intensity.
Titanium dioxide price volatility, precision grinding equipment supply concentration, and cross-jurisdictional certification divergence are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions against MEE enforcement intensity and REACH substance list updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market