
 Mosquito-Repellent Paints Market | 2026-2036
Mosquito-Repellent Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Mosquito-Repellent Paints Market Outlook
Application-layer service contracts for periodic repellency reactivation is rebalancing how value gets captured in this market. BASF SE leverages its polymer science heritage to anchor premium microencapsulation formulations. AkzoNobel N.V. competes through architectural coatings distribution networks that extend into tropical housing markets. PPG Industries, Inc. specializes in industrial-grade durability standards for agricultural and perimeter fencing deployments.
Mosquito-repellent paints are wall-coating systems incorporating synthetic pyrethroids or plant-derived active agents into acrylic, latex, or oil-based binders, engineered to release insecticidal compounds through controlled diffusion over multiyear lifespans. The primary commercial purpose is to reduce indoor and outdoor vector-borne disease transmission in residential, commercial, and agricultural environments where conventional spraying cycles prove unsustainable. Water-based formulations now lead volume shipments due to lower volatile organic compound profiles and faster drying times suited to humid climates. Microencapsulation technology commands the fastest expansion as it extends active-agent release duration and protects pyrethroids from ultraviolet degradation. Agricultural end-use remains comparatively mature, with margin pools concentrating in residential exterior surfaces where reapplication frequency and aesthetic performance requirements sustain pricing power.
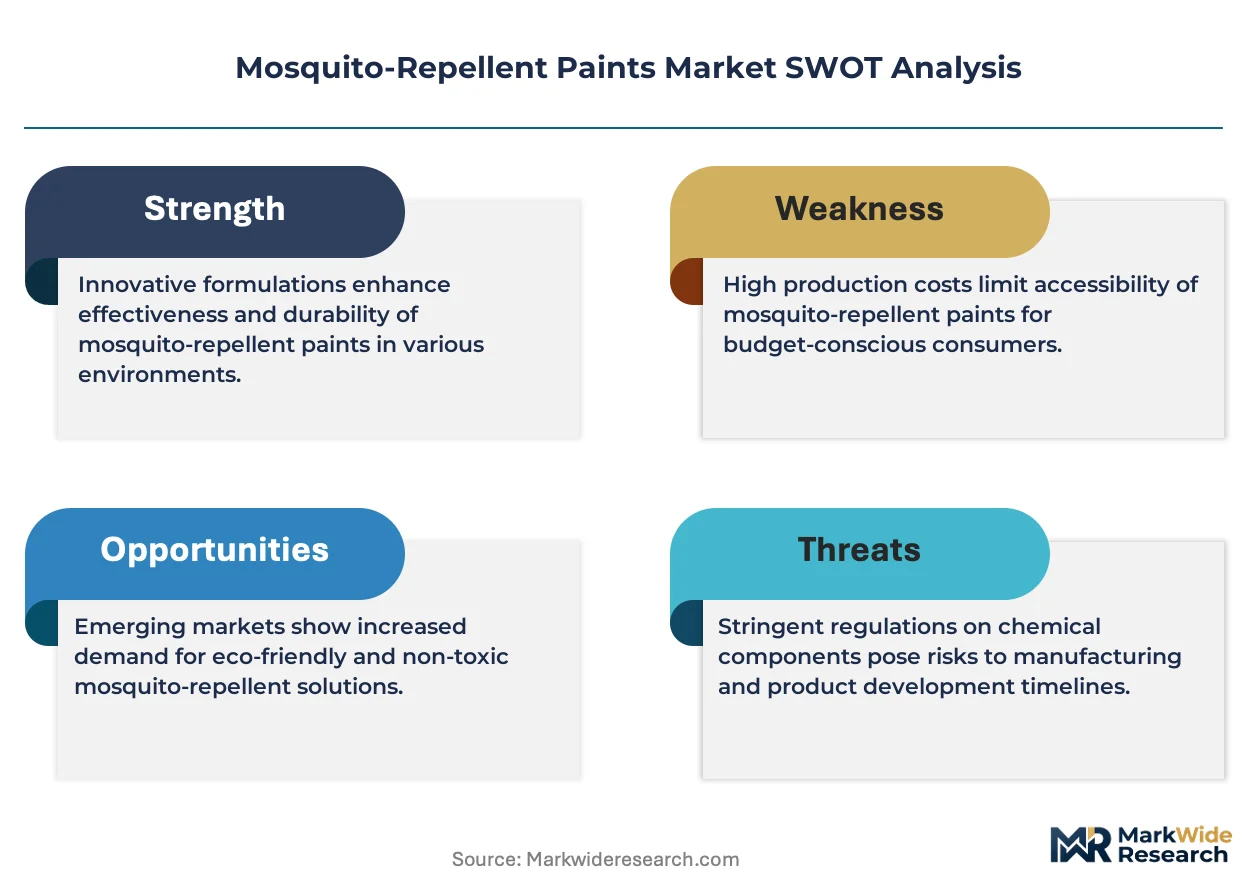
India's BIS and CDSCO frameworks govern active-agent concentration limits and toxicity labeling, while the US EPA regulates pyrethroid incorporation under pesticide registration requirements that shape product development timelines and market access costs. REACH compliance in Europe restricts certain synthetic actives, pushing formulators toward biodegradable technology pathways that alter raw-material sourcing and certification investments. Stakeholders must monitor evolving vector-control mandates across tropical geographies and decide whether to build captive microencapsulation capacity or source from specialized chemical suppliers.
Market Dynamics
Microencapsulation technology is compressing reapplication cycles and redistributing margin pools toward formulation specialists who control release-kinetics intellectual property.
Growth Catalysts
- BIS Certification Mandates:India's Bureau of Indian Standards requirements for insect-repellent coatings are forcing quality differentiation and accelerating formal market development.
- Synthetic Pyrethroid Microencapsulation:This process extends active-agent release duration while protecting compounds from ultraviolet degradation, creating measurable performance premiums.
- Urban Corridor Density:South Asian metropolitan housing clusters sustain recurring paint refresh cycles driven by endemic dengue and malaria burdens.
Market Restraints
- Pyrethroid Input Volatility:Synthetic active-agent prices fluctuate with agricultural chemical feedstock markets, squeezing formulation margins unpredictably.
- REACH Compliance Costs:European chemical registration requirements restrict certain synthetic actives and force expensive biodegradability testing.
- Plant-Derived Substitutes:Citronella and neem oil formulations compete on perceived safety despite shorter efficacy windows.
Strategic Opportunities
- Service Contract Layering:Application-layer agreements for periodic repellency reactivation capture recurring revenue streams beyond initial coating sales.
- Water-Based Formulation Share:Lower volatile organic compound profiles align with tightening environmental standards in tropical construction markets.
- Perimeter Fencing Deployments:Agricultural and institutional exterior applications remain underpenetrated relative to residential interior surfaces.
Industry Challenges
- Microencapsulation Talent Scarcity:Polymer science expertise for controlled-release engineering concentrates among limited specialist pools.
- Dual Certification Timelines:Simultaneous pesticide registration and coatings compliance extends product launch schedules substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosquito-Repellent Paints Market |
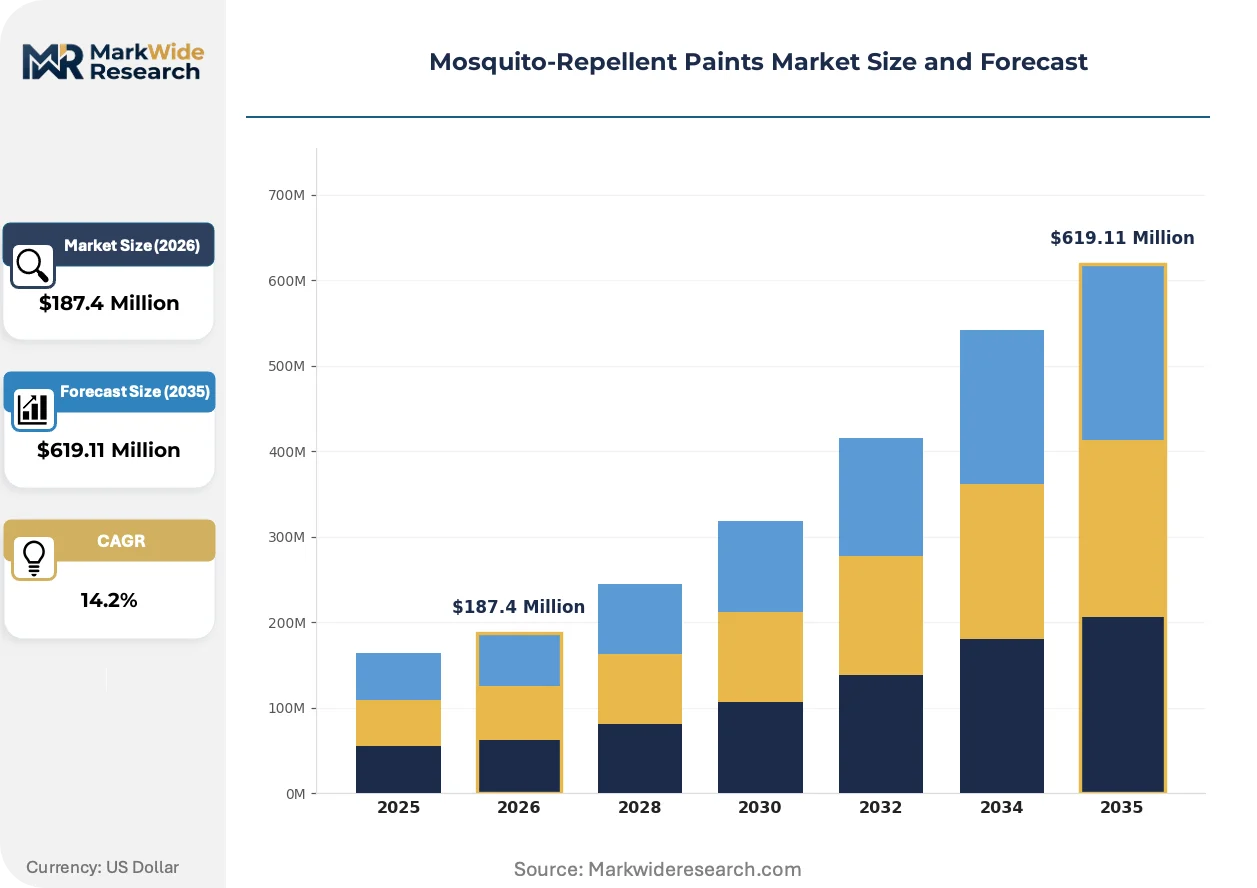
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Latex, Oil-based, Water-based End User: Residential, Commercial, Industrial, Agricultural Application: Interior Walls, Exterior Surfaces, Furniture, Fences Technology: Microencapsulation, Nanotechnology, Biodegradable, Thermal |
| Companies Covered | BASF SE, AkzoNobel N.V., PPG Industries, Inc., Sherwin-Williams Company, Nippon Paint Holdings Co., Ltd., Asian Paints Limited, DuluxGroup Limited, Kansai Paint Co., Ltd., Adapta Powder Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosquito-Repellent Paints Market Strategic Shifts
Formulation science and service-model innovation are converging to extend product lifecycles and capture value through recurring engagement rather than transactional coating sales.
Silica-shell microencapsulation is absorbing ultraviolet exposure that would otherwise degrade pyrethroid actives, extending effective release periods from months to multiyear spans. Agricultural fencing contractors and tropical housing developers are adopting these systems fastest where labor costs make frequent reapplication uneconomical. The technology is absorbing margin share from conventional emulsion suppliers who lack captive polymer science capabilities.
EPA pesticide registration requirements for pyrethroid incorporation impose multi-year development timelines and substantial market access costs on new entrants. These rules compress the viable supplier base to established chemical conglomerates with regulatory affairs infrastructure. Residential exterior coating lines face the steepest compliance burdens as they must demonstrate both efficacy and environmental fate data.
After-sales reactivation services are unbundling from initial product sales as buyers prioritize sustained vector control over upfront coating costs. Distributors in Indian urban corridors are building technician networks for periodic microcapsule replenishment visits. This pattern concentrates in high-turnover rental housing markets where landlords bear recurring public health liability.
Mosquito-Repellent Paints Market Segmentation
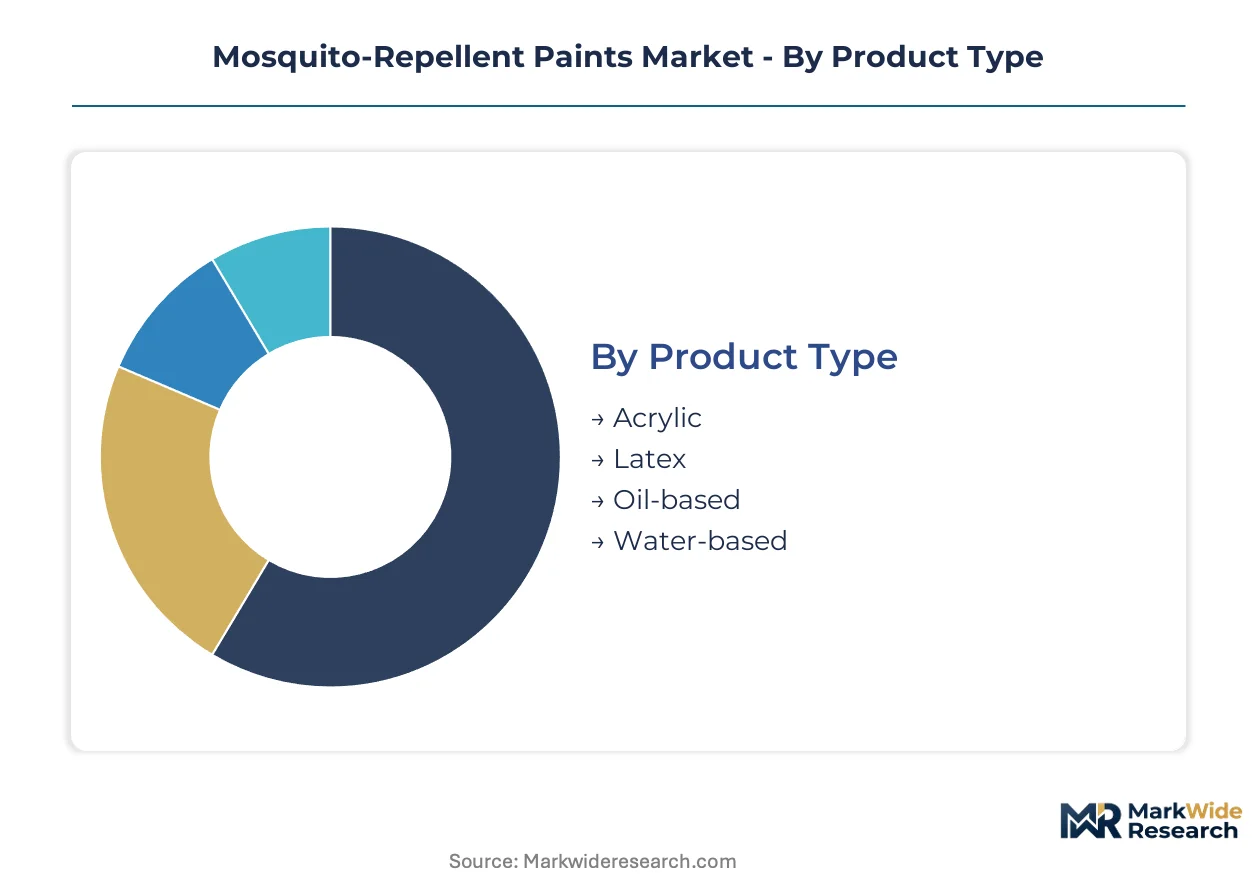
Buyers in tropical construction markets prioritize formulation chemistry and reapplication economics over aesthetic attributes. Segmentation reveals how active-agent delivery mechanisms and surface exposure conditions reshape procurement patterns across housing, agriculture, and institutional verticals.
Product Type:
Cost tier determines specification adoption, with water-based formulations commanding volume leadership due to environmental compliance advantages and labor efficiency in humid climates.
- Water-based:Acrylic-latex hybrids with sub-50 g/L volatile organic compound profiles dominate tropical residential new-build specifications. Indian urban housing clusters in Mumbai and Chennai specify these formulations for faster drying cycles that reduce construction labor idle time.
- Acrylic:Pure acrylic binders with synthetic pyrethroid integration offer superior ultraviolet stability for exterior agricultural deployments. Brazilian soybean estate fencing contracts specify these systems where multiyear durability outweighs premium pricing.
- Latex:Styrene-acrylic copolymers balance cost and washability for interior institutional applications in Southeast Asian healthcare facilities.
- Oil-based:Alkyd resin systems retain niche demand for metal substrate adhesion in perimeter security installations where solvent resistance matters.
Water-based leads on scale; acrylic leads on momentum.
End User:
Application maturity varies sharply by liability exposure and refresh cycle predictability.
- Residential:Exterior wall coatings in dengue-endemic urban corridors sustain recurring specification demand. Indonesian developer PT Ciputra mandates repellent coatings across mid-rise rental portfolios where tenant turnover accelerates maintenance cycles.
- Agricultural:Perimeter fencing and storage facility coatings address labor scarcity in mechanized farming operations. Vietnamese rice cooperative contracts specify these systems where manual spraying becomes uneconomical at scale.
- Commercial:Hospitality and retail exterior surfaces in tropical tourism zones adopt repellent coatings to reduce guest complaint incidence and liability exposure.
- Industrial:Warehouse and logistics facility coatings remain underpenetrated relative to residential, with procurement concentrated in food processing plants where vector control intersects with sanitary regulations.
Residential dominates absolute volume; agricultural climbs the fastest.
Application:
Surface exposure conditions dictate active-agent degradation rates and reactivation service economics.
- Exterior Surfaces:Direct ultraviolet and rainfall exposure demand silica-shell microencapsulation for multiyear efficacy. Kenyan affordable housing developments in Nairobi specify these systems where maintenance access is limited.
- Interior Walls:Controlled environments enable simpler emulsion formulations with shorter efficacy windows acceptable to high-turnover rental markets. Bangladeshi garment worker dormitory operators prioritize first-cost minimization over longevity.
- Fences:Agricultural and institutional perimeter applications combine high sun exposure with mechanical abrasion from vegetation contact.
- Furniture:Outdoor fixtures in hospitality settings represent a nascent specification channel with concentrated margin potential.
Exterior surfaces anchor revenue concentration; fences gain share fastest.
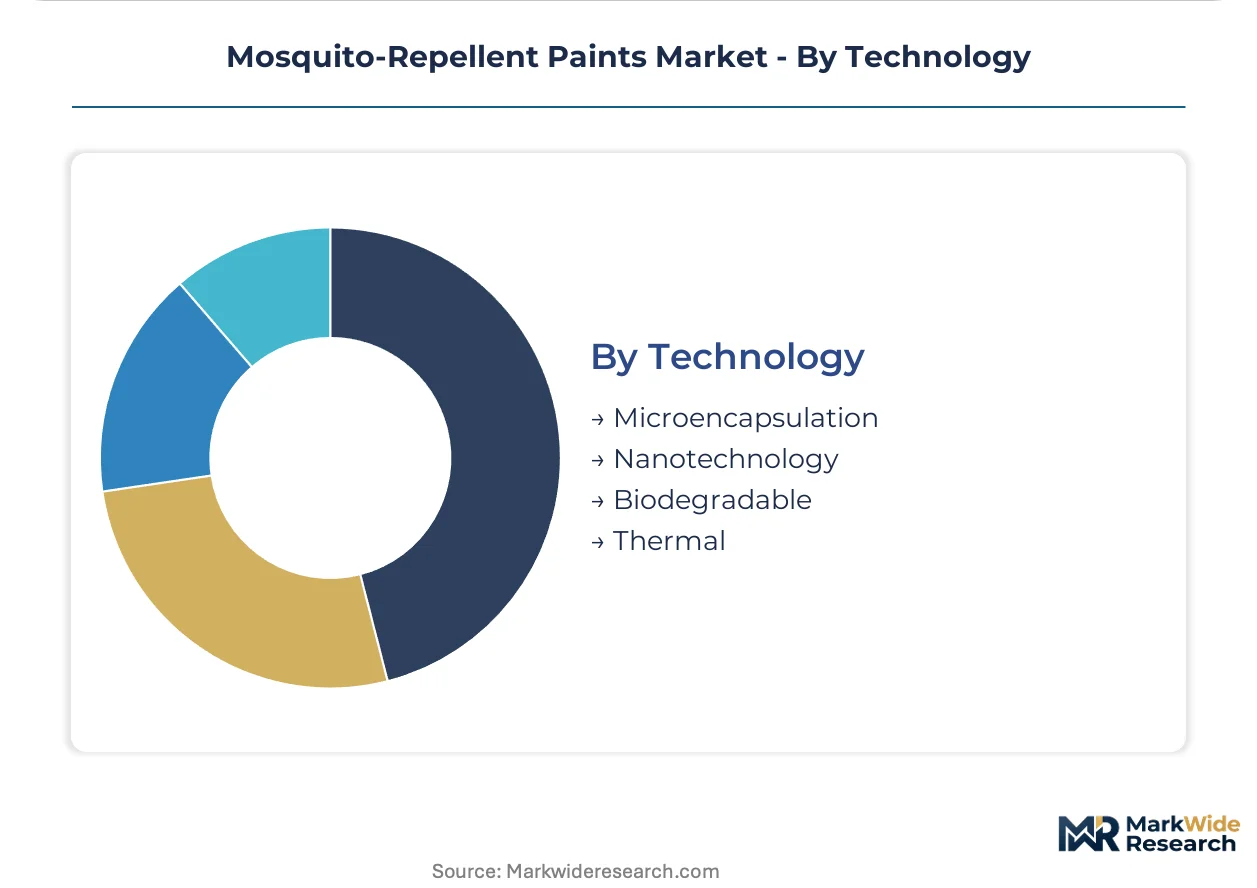
Technology:
Intellectual property control over release kinetics separates formulation specialists from commodity suppliers.
- Microencapsulation:Polymer-shell systems protecting pyrethroids from environmental degradation command premium positioning. BASF SE's proprietary interfacial polymerization processes extend effective release periods beyond conventional emulsions.
- Biodegradable:Plant-derived active carriers using chitosan or starch matrices align with REACH restrictions on synthetic pyrethroids in European applications.
- Nanotechnology:Silica and metal-oxide nanoparticles as active-agent vehicles remain developmental, with scale-up constrained by toxicology registration timelines.
- Thermal:Heat-activated release systems for specialized agricultural storage applications where temperature differentials trigger repellent emission.
Microencapsulation leads on scale; biodegradable shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as formulators seek jurisdictions with streamlined pesticide-coating dual registration pathways. India's BIS certification mandates and Brazil's ANVISA frameworks create compliance cost differentials that favor established chemical conglomerates with dedicated regulatory affairs infrastructure.
India
Dengue-endemic urban corridors in Mumbai, Delhi-NCR, and Chennai sustain recurring exterior coating specifications in mid-rise rental housing. BIS and CDSCO jointly govern active-agent concentration limits and toxicity labeling requirements that compress the viable supplier base to certified formulators. Construction clusters in Maharashtra and Tamil Nadu specify water-based microencapsulation systems where tenant turnover accelerates maintenance refresh cycles.
Brazil
Soybean estate fencing and agricultural perimeter applications drive demand for acrylic-based durability in Mato Grosso and Paraná states. ANVISA registration requirements for pyrethroid incorporation extend product development timelines while favoring incumbents with established toxicology dossiers. São Paulo-based housing developers specify repellent coatings across affordable residential portfolios where vector-control liability intersects with public health mandates.
United States
EPA pesticide registration requirements for pyrethroid incorporation impose multi-year compliance burdens that limit new entrant viability. Southeast and Gulf Coast construction markets specify exterior-grade formulations where humidity and ultraviolet exposure degrade conventional emulsions. Florida and Texas housing developments represent concentrated demand nodes where integrated vector-control specifications penetrate suburban new-build segments.
Germany
REACH compliance restrictions on synthetic pyrethroids push formulators toward biodegradable active-carrier development using chitosan matrices. Industrial coatings procurement in Bavaria and North Rhine-Westphalia concentrates in food-processing facilities where sanitary regulations intersect with vector-control requirements. ECHA registration timelines for novel actives extend commercialization pathways for European specialty chemical suppliers.
Indonesia
Jakarta and Surabaya metropolitan housing clusters sustain specification demand driven by endemic dengue burdens and recurring paint refresh economics. National pharmaceutical regulator oversight of insecticidal coating claims creates dual-registration complexity that favors multinational formulators with local regulatory partnerships. Developer PT Ciputra mandates repellent coatings across rental portfolios where landlord liability for vector-borne disease transmission shapes procurement priorities.
Mosquito-Repellent Paints Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation intellectual property holders capturing margin premiums while toll manufacturers serve volume tiers. The supplier base concentrates among diversified chemical conglomerates with captive polymer science capabilities and dedicated pesticide registration infrastructure. Three archetypes dominate: microencapsulation technology specialists, architectural coatings distributors with tropical market penetration, and agricultural-chemical heritage players repurposing pyrethroid supply chains. Competitive moves center on backward integration into active-agent production and strategic partnerships with housing developers for specification anchoring.
Among diversified chemical conglomerates, BASF SE and AkzoNobel N.V. occupy positions that exemplify the technology-differentiation archetype, while PPG Industries, Inc. represents the industrial-durability specialization tier. These entities anchor competitive positioning through distinct capability configurations rather than overlapping segment contestation.
| Leading Market Players |
|---|
| BASF SE |
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| Sherwin-Williams Company |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints Limited |
| DuluxGroup Limited |
| Kansai Paint Co., Ltd. |
| Adapta Powder Paints |
| Others |
Value Chain & Pricing Dynamics
Synthetic pyrethroid feedstock costs transmit directly from agricultural chemical markets through formulation tiers to end-user pricing, with microencapsulation-grade actives commanding premiums that separate certified suppliers from commodity emulsion producers in Indian and Brazilian procurement channels.
Pricing Analysis
Distributor margins in tropical urban corridors absorb the steepest compression as BIS-certified formulators compete for specification anchoring in Mumbai and Chennai housing developments. Three-tier pricing structure across premium microencapsulation, standard water-based emulsion, and economy oil-based alkyd systems separates procurement budgets by performance durability requirements. Pricing pressure stems from pyrethroid input volatility linked to agricultural chemical feedstock cycles. Agricultural fencing contractors in Mato Grosso exhibit lowest price sensitivity due to labor substitution economics, while Bangladeshi garment worker dormitory operators prioritize first-cost minimization over longevity.
Supply Chain Analysis
Freight costs for temperature-sensitive pyrethroid concentrates from China and India to Southeast Asian formulation plants concentrate margin pressure on regional toll manufacturers lacking captive active-agent production. Supply concentration rests on German polymer science specialists for microencapsulation shell materials, Indian pyrethroid synthesis infrastructure, and Chinese acrylic resin feedstocks. Raw material dependencies include synthetic pyrethroid technical-grade actives, silica nanoparticle carriers, and water-based latex binders. Single-source vulnerability in interfacial polymerization expertise constrains capacity expansion for controlled-release formulations. Distribution runs through architectural coatings distributors with tropical housing developer relationships and agricultural chemical channel partners serving perimeter fencing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage opportunities concentrate where India's BIS certification timelines and cost structures diverge from Brazil's ANVISA frameworks, rewarding formulators with dedicated compliance infrastructure in both jurisdictions.
For Market Incumbents: Acquire captive microencapsulation technology assets to defend formulation margin pools against polymer science specialists entering from adjacent agrochemical markets. Prioritize backward integration into pyrethroid technical-grade production to offset agricultural feedstock price volatility squeezing toll manufacturers. Anchor specification relationships with Jakarta and São Paulo housing developers through bundled reactivation service contracts that extend engagement beyond initial coating sales.
For New Entrants and Emerging Players: Biodegradable active-carrier formulations using chitosan matrices offer technology-first positioning in European markets where REACH restrictions displace synthetic pyrethroid incumbents. Target underpenetrated agricultural perimeter fencing segments in Vietnamese rice cooperatives and Kenyan affordable housing developments where labor scarcity drives demand for multiyear efficacy systems. Pursue toll manufacturing partnerships with established distributors lacking captive formulation capabilities to bypass dual-registration timeline barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where microencapsulation talent scarcity concentrates among limited polymer science specialist pools and regulatory compliance costs compress viable supplier bases. Long-term viability favors formulators with integrated active-agent supply chains and tropical housing developer specification anchoring. Acquisition target archetypes include regional toll manufacturers with BIS or ANVISA certifications and agricultural chemical heritage players repurposing pyrethroid infrastructure. Monitor EPA registration timeline acceleration as signal for new entrant viability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrethroid Synthesis | Captive supply of technical-grade actives insulates margins from agricultural chemical feedstock volatility in Indian formulation clusters. |
| Microencapsulation Capacity Expansion | Proprietary interfacial polymerization capabilities extend release-kinetics differentiation against commodity emulsion competitors in Brazilian agricultural markets. |
| Reactivation Service Network Buildout | Technician deployment infrastructure captures recurring revenue streams from high-turnover rental housing markets in Jakarta and Surabaya metropolitan corridors. |
| Biodegradable Formulation Development | Chitosan-matrix active carriers align with REACH synthetic pyrethroid restrictions while opening European specification channels previously closed to conventional formulators. |
| Joint Venture with Tropical Housing Developers | Specification anchoring through PT Ciputra-style portfolio mandates creates defensive positioning against distributor channel competitors in dengue-endemic urban clusters. |
Study Parameters
Direct dialogue with formulation R&D directors, agricultural fencing procurement leads, tropical housing developer specification teams, and architectural coatings distributors grounded qualitative insights in operational realities across Indian, Brazilian, and Southeast Asian markets. Secondary validation drew from BIS certification registries, EPA pesticide registration databases, ANVISA toxicology submission records, and customs trade data on pyrethroid concentrate flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for tropical construction activity and vector-control expenditure patterns.
Bottom-up modeling aggregated individual country-level demand projections across residential, agricultural, commercial, and industrial end-use segments, with technology splits between microencapsulation, biodegradable, nanotechnology, and thermal release systems. Top-down cross-checks incorporated construction spend forecasts, dengue incidence correlation analysis, and paint refresh cycle economics in endemic urban corridors. CAGRs derived from regression analysis of historical adoption curves in comparable functional coating categories. Industry-specific forecast inputs included BIS certification penetration rates and EPA registration queue timelines.
The model holds under stable regulatory enforcement intensity and pyrethroid supply continuity; deviation in REACH restriction expansion or Indian certification acceleration would shift competitive positioning assumptions. Forecasts reflect documented base-case assumptions on technology adoption trajectories and channel margin structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Water Color Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Acrylic Paints Market