
 India Industrial Coatings Market | 2026-2036
India Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Coatings Market Foresight
Performance-based maintenance contracts is expanding as a service layer that transforms how coating vendors monetize industrial relationships. Asian Paints Ltd leverages its distribution density to lock in recurring service revenue from manufacturing clients. Kansai Nerolac Paints Ltd anchors its position through captive technical support teams embedded at automotive OEM facilities. JSW Paints competes by bundling coating application audits with substrate-specific product recommendations.
India industrial coatings are formulated systems comprising resins, pigments, solvents, and additives that cure into protective films resistant to corrosion, chemicals, and thermal stress, with film thickness specifications typically ranging from 25 to 250 microns depending on end-use exposure severity. These coatings serve primarily to extend asset life and reduce maintenance downtime for capital-intensive industrial infrastructure. Water-based technology leads volume growth as environmental compliance tightens, while powder coating commands margin pools in the automotive segment due to its zero-VOC profile and superior transfer efficiency. Solvent-based formulations still dominate legacy industrial equipment refurbishments where substrate compatibility constraints persist.
BIS mandates product certification under IS 15489 for protective coatings, while the CEA enforces fire-retardant standards for electrical infrastructure applications, collectively raising compliance costs for new entrants. The PLI scheme for specialty chemicals indirectly subsidizes domestic resin production, altering raw material sourcing economics for formulators. Stakeholders must monitor how state-level pollution control board enforcement of MEE guidelines on VOC emissions reshapes plant location decisions and technology migration timelines.
Market Dynamics
BIS certification mandates for protective coatings under IS 15489 are compressing supplier margins while simultaneously consolidating procurement toward certified formulators with captive technical service capabilities.
Growth Catalysts
- Automotive OEM Cluster Expansion:Manufacturing hubs around Chennai and Pune are scaling coating procurement for corrosion protection of stamped metal components and assembly line equipment.
- PLI Scheme for Specialty Chemicals:Production-linked incentives for domestic resin manufacturing are altering raw material economics for water-based and powder coating formulators.
- MEE Guidelines Enforcement:State pollution control boards are accelerating VOC emission compliance timelines, forcing solvent-to-water technology migration across Gujarat and Maharashtra industrial corridors.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy and polyurethane resin prices fluctuate with crude-derived intermediate costs, compressing formulator margins during supply shocks.
- Import Dependency for Specialty Additives:Corrosion inhibitors and UV stabilizers concentrate sourcing from Chinese and German chemical suppliers, exposing domestic blenders to currency and logistics risk.
- Substrate Compatibility Limitations:Legacy industrial equipment with aged surface profiles resists water-based adhesion, prolonging solvent-based formulation dominance in refurbishment cycles.
Strategic Opportunities
- Performance-Based Maintenance Contracts:Coating vendors can capture recurring revenue streams by guaranteeing asset life extension and downtime reduction for capital-intensive manufacturing clients.
- Fire-Retardant Electrical Infrastructure:CEA mandates for transmission and distribution equipment coatings create certified product demand from utility sector procurement.
- Powder Coating Automotive Penetration:Zero-VOC profiles and superior transfer efficiency position powder technology for expansion beyond wheels and chassis into body-in-white applications.
Industry Challenges
- Certification Timeline Compression:BIS laboratory testing queues and documentation requirements delay product launches by 8-14 months for new entrants.
- Application Technician Scarcity:Specialized skills for spray parameter optimization and film thickness verification are concentrated among aging workforces in Mumbai and Ahmedabad industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Coatings Market |
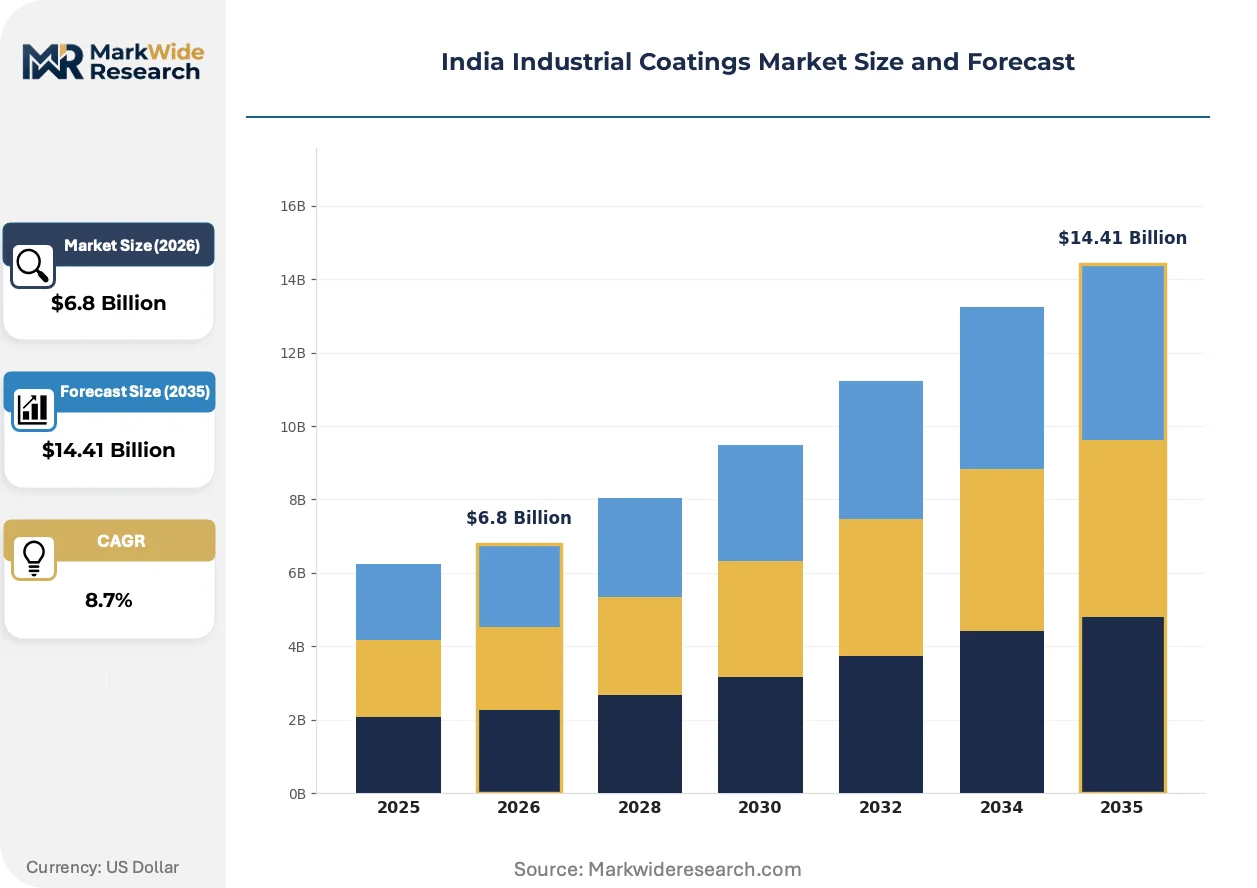
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
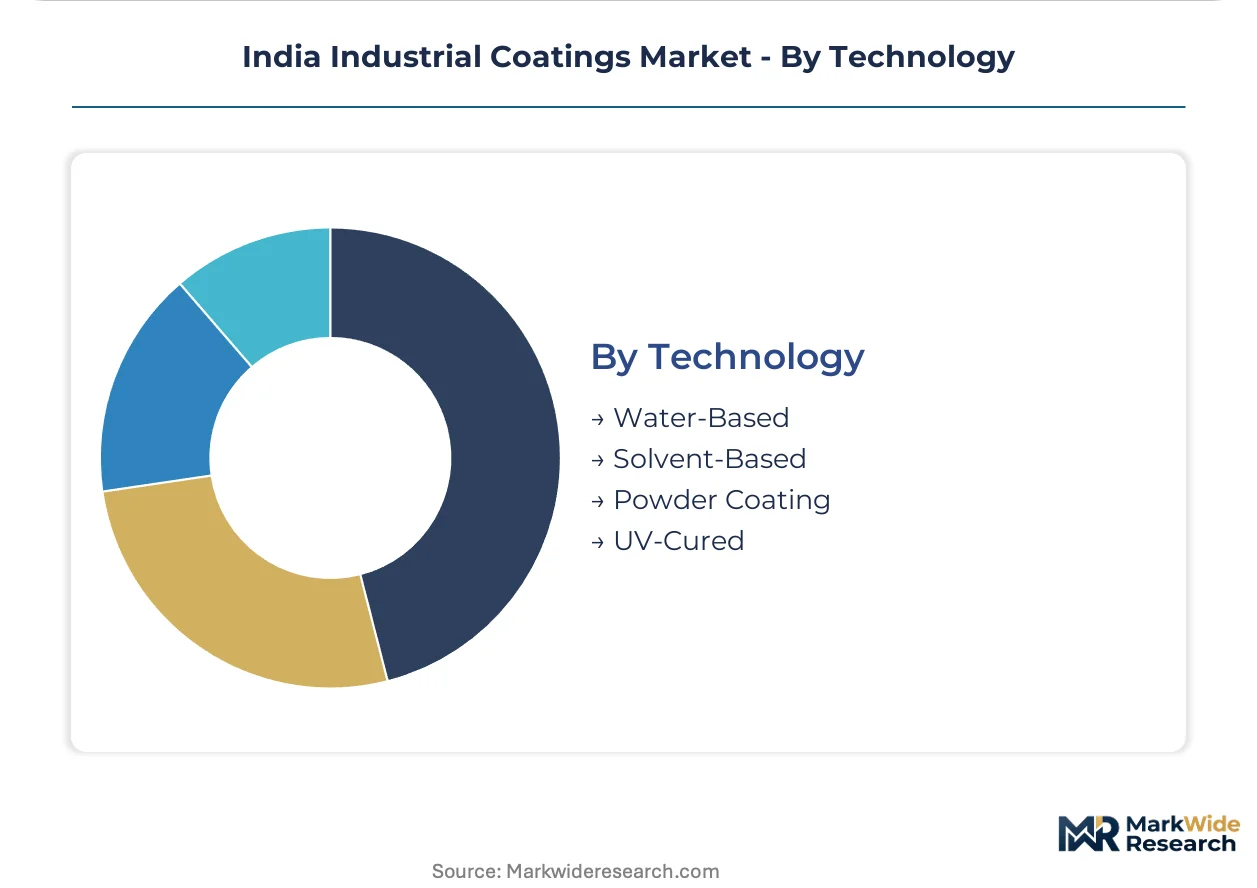
| Segmentation | Product Type: Paints, Varnishes, Primers, Sealants Application: Automotive, Aerospace, Industrial Equipment, Infrastructure End User: Manufacturing, Construction, Oil & Gas, Electronics Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured |
| Companies Covered | JSW Paints, Akzo Nobel India (Dulux), Asian Paints Ltd, Indigo Paints Ltd, Shalimar Paints, Berger Paints India Ltd, Nippon Paint India, Birla Opus Paints, Kansai Nerolac Paints Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Coatings Market Shifts & Advancements
Coating formulation and application workflows are digitizing rapidly, with sensor-enabled quality assurance and predictive maintenance protocols reshaping how vendors demonstrate value to asset owners.
Self-healing coating chemistry incorporating microcapsule-based corrosion inhibitors is automating damage response in offshore and chemical processing environments. Reliance Industries and Indian Oil refineries are piloting these systems on storage tank exteriors and pipeline flanges. The technology is automating inspection cycles and reducing manual touch-up labor by triggering polymer flow at crack initiation points.
BIS has tightened VOC emission thresholds under revised IS 15489 compliance schedules, effective across all 28 states. Formulators must reformulate solvent-based portfolios or exit certified supplier lists for government and PSU contracts. Automotive OEMs in Tamil Nadu and Maharashtra are responding fastest, mandating water-based primers and clearcoats in supplier qualification documents.
Asset owners are unbundling coating procurement from integrated maintenance contracts, creating direct vendor relationships that bypass traditional EPC intermediaries. Manufacturing plants in Vadodara and Nagpur are establishing technical qualification panels that evaluate formulators on substrate-specific performance data rather than distributor relationships. This shift is most visible in steel processing and cement manufacturing verticals where annual coating expenditure exceeds maintenance outsourcing budgets.
India Industrial Coatings Market Segmentation
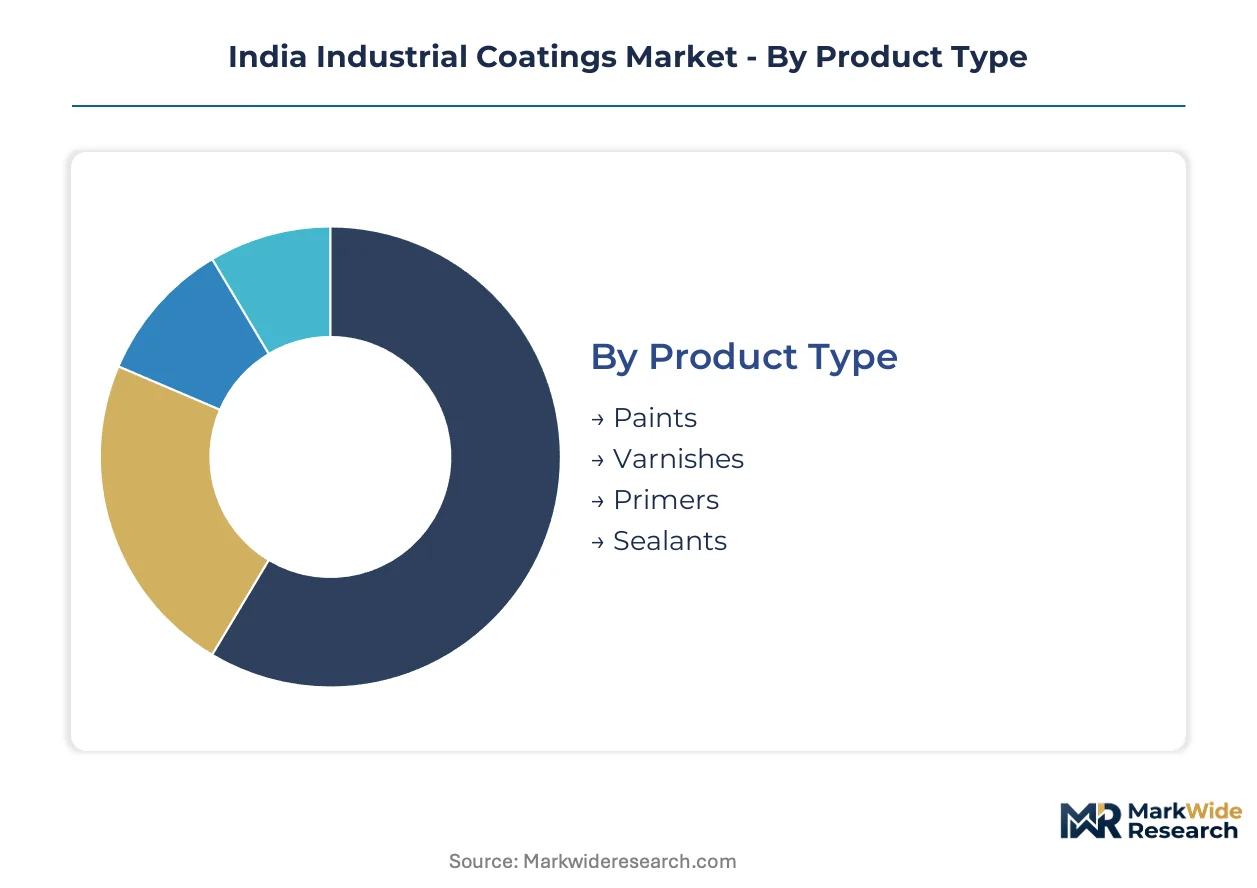
Industrial coatings in India segment across formulation chemistry, substrate requirements, and regulatory compliance tiers. Each axis reveals distinct margin structures and procurement patterns that vendors must navigate to capture value in this expanding market.
Product Type:
Formulation chemistry determines application protocol and film performance specifications across Indian manufacturing verticals.
- Paints:Acrylic and alkyd resin systems dominate volume, formulated for 25-250 micron dry film thickness specifications. Demand concentrates in Gujarat and Maharashtra manufacturing corridors where corrosion protection of structural steel commands procurement budgets.
- Primers:Epoxy and zinc-rich formulations establish adhesion and cathodic protection on blast-cleaned substrates. Automotive OEM hubs around Chennai and Pune specify these for stamped metal component pretreatment, driven by BIS IS 15489 certification requirements for supplier qualification.
- Varnishes:Clear polyurethane and alkyd topcoats seal decorative wood and metal finishes in furniture manufacturing and heritage infrastructure refurbishment.
- Sealants:Elastomeric polysulfide and silicone compounds fill expansion joints and seams in chemical processing equipment and storage tank construction.
Mature deployment sits with Paints. Newer deployment is concentrated in Primers as automotive certification standards tighten.
Application:
End-use environment severity dictates coating system specification and reapplication frequency.
- Automotive:Cathodic electrodeposition primers, basecoats, and clearcoats protect body-in-white and component assemblies. OEM facilities in Tamil Nadu and Maharashtra mandate water-based and powder technologies under supplier sustainability scorecards.
- Industrial Equipment:Chemical-resistant epoxy and polyurethane systems protect pumps, valves, and processing vessels in Vadodara and Nagpur manufacturing clusters.
- Infrastructure:High-build epoxy and fluoropolymer coatings extend service life of bridges, power transmission towers, and port handling equipment exposed to coastal corrosion.
- Aerospace:Chromate-free pretreatments and polyurethane topcoats meet MRO requirements for commercial aviation and defense platforms.
Volume concentration rests with Industrial Equipment. Steepest expansion trajectory belongs to Automotive as OEM localization accelerates.
End User:
Procurement sophistication varies dramatically across buyer categories, shaping vendor engagement models.
- Manufacturing:Steel processing, cement, and textile plants in Gujarat and Maharashtra specify performance-based coating systems with technical service support embedded in supply contracts.
- Construction:Commercial and residential developers source decorative and protective coatings through distributor networks, with BIS certification increasingly specified in tender documents.
- Oil & Gas:Reliance Industries and Indian Oil refineries demand high-temperature resistant and chemical-immersion coatings for storage tanks, pipelines, and offshore platforms.
- Electronics:Conformal coatings and EMI shielding formulations protect printed circuit boards and enclosure assemblies from moisture and thermal cycling.
Technical specification maturity concentrates in Oil & Gas. Procurement modernization is advancing fastest in Manufacturing as asset owners unbundle coating from integrated maintenance contracts.
Technology:
Environmental compliance timelines are forcing technology migration across Indian industrial corridors.
- Water-Based:Acrylic and polyurethane dispersions achieve sub-100 g/L VOC content, qualifying for government and PSU contracts under revised BIS IS 15489 schedules. MEE guidelines enforcement in Gujarat and Maharashtra is accelerating solvent-to-water conversion.
- Powder Coating:Thermoset epoxy and polyester formulations deliver zero-VOC profiles with 95%+ transfer efficiency. Automotive wheel and chassis applications in Pune and Chennai anchor current demand, with body-in-white penetration expanding.
- Solvent-Based:High-solids epoxy and polyurethane systems retain dominance in legacy equipment refurbishment where aged surface profiles resist water-based adhesion.
- UV-Cured:Rapid-cure acrylate oligomers enable high-throughput coating of flat stock and assembled components in electronics and furniture manufacturing.
Established installed base remains with Solvent-Based. Technology transition is concentrating in Water-Based as state pollution control boards compress compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing plants in Gujarat and Maharashtra anchor coating procurement volumes for corrosion protection of industrial equipment, with state pollution control boards enforcing MEE guidelines on VOC emissions.
Maharashtra
Automotive OEM facilities around Pune and Mumbai drive specification of water-based primers and clearcoats under supplier sustainability mandates. BIS certification requirements under IS 15489 compress supplier qualification timelines for protective coating procurement. Manufacturing clusters in Nagpur and Vadodara industrial corridors unbundle coating procurement from integrated maintenance contracts.
Gujarat
Reliance Industries and Indian Oil refineries demand high-temperature resistant coatings for storage tanks and pipeline infrastructure in Jamnagar and Vadodara. The PLI scheme for specialty chemicals subsidizes domestic resin production, altering raw material economics for local formulators. Chemical processing equipment manufacturers in Ankleshwar specify epoxy and polyurethane systems for pump and valve protection.
Tamil Nadu
Automotive OEM hubs around Chennai mandate powder coating technologies for wheel and chassis applications with zero-VOC profiles. CEA fire-retardant standards for electrical infrastructure create certified product demand from utility sector procurement. Manufacturing plants specify cathodic electrodeposition primers for body-in-white corrosion protection.
Karnataka
Electronics manufacturing clusters in Bengaluru source conformal coatings and EMI shielding formulations for printed circuit board protection. MEE guideline enforcement accelerates solvent-to-water technology migration across industrial zones. Aerospace MRO facilities specify chromate-free pretreatments and polyurethane topcoats for defense platform maintenance.
Telangana
Cement and steel processing plants in Hyderabad specify performance-based coating systems with embedded technical service support. State pollution control boards compress VOC emission compliance timelines for legacy equipment refurbishment. Industrial equipment manufacturers source chemical-resistant epoxy systems for processing vessel protection.
India Industrial Coatings Market Competitive Landscape
Capital-heavy producers with captive resin manufacturing compete with asset-light formulators sourcing raw materials through distributor networks. The vendor base concentrates around integrated paint manufacturers with established BIS certification infrastructure and embedded technical service teams. Three archetypes dominate: diversified coatings conglomerates with automotive OEM relationships, specialty industrial formulators focused on substrate-specific performance, and emerging challengers bundling application audits with product recommendations. Competitive moves center on backward integration into resin production and performance-based maintenance contract structures that guarantee asset life extension.
Among domestic integrated manufacturers, Asian Paints Ltd, Kansai Nerolac Paints Ltd, and JSW Paints occupy distinct positioning vectors. Asian Paints exemplifies the distribution-dense archetype leveraging procurement channel control for recurring service revenue. Kansai Nerolac represents the automotive-embedded technical service model with captive support teams at OEM facilities. JSW Paints anchors the challenger position through bundled coating application audits and substrate-specific recommendations that bypass traditional EPC intermediaries.
| Leading Market Players |
|---|
| JSW Paints |
| Akzo Nobel India (Dulux) |
| Asian Paints Ltd |
| Indigo Paints Ltd |
| Shalimar Paints |
| Berger Paints India Ltd |
| Nippon Paint India |
| Birla Opus Paints |
| Kansai Nerolac Paints Ltd |
| Others |
Supply & Pricing Matrix
Epoxy and polyurethane resin costs cascade through three pricing tiers as formulators absorb petrochemical feedstock volatility and pass selective premiums to automotive OEMs demanding certified water-based systems. BIS IS 15489 certification requirements compress margins at the economy tier while concentrating procurement power among integrated manufacturers with captive technical service teams.
Pricing Analysis
Asset life guarantees anchor value-based contracts for manufacturing clients in Gujarat and Maharashtra, with pricing stratifying across premium certified, standard compliant, and economy unbranded tiers. Certification level under BIS IS 15489 and embedded technical service intensity differentiate price bands. Cost compression in the economy tier is intensifying because raw material volatility outpaces reformulation savings. Steel processing and cement manufacturing verticals exhibit highest price sensitivity, while automotive OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Empty container returns from coating application sites to resin manufacturing hubs in Gujarat and Maharashtra create reverse-logistics inefficiencies that inflate working capital cycles for mid-tier formulators. Raw material sourcing draws from domestic petrochemical complexes for base resins, Chinese suppliers for corrosion inhibitors, and German specialty chemical houses for UV stabilizers. Single-source vulnerability concentrates in specialty additives from Chinese chemical suppliers. Distribution runs through manufacturer-direct technical service teams for automotive OEMs and distributor networks for construction sector procurement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India industrial coatings market functions as a vertical-integration race where backward control over resin manufacturing separates margin leaders from price-takers. Players are pursuing captive production of water-based acrylic and polyurethane dispersions to escape import dependency and BIS certification queue bottlenecks.
For Market Incumbents: Anticipate margin compression from emerging challengers bundling application audits with substrate-specific recommendations by accelerating backward integration into domestic resin production under the PLI scheme for specialty chemicals. Lock in automotive OEM relationships through embedded technical service teams at Chennai and Pune facilities before certification timelines compress further. For New Entrants and Emerging Players: Direct-to-plant digital procurement platforms targeting manufacturing verticals in Vadodara and Nagpur offer the most penetrable entry vector, bypassing traditional EPC intermediaries that currently control coating specification. Focus initial penetration on steel processing and cement manufacturing where asset owners have unbundled coating procurement from integrated maintenance contracts. Lead with performance-based maintenance contracts guaranteeing downtime reduction rather than competing on unit price. For Investors and Strategic Acquirers: Accelerated BIS laboratory testing queues exceeding 8-14 months is the leading indicator that certification infrastructure scarcity will consolidate procurement toward established formulators with captive testing relationships. Over the projection horizon, target acquisition of specialty industrial formulators with substrate-specific performance data libraries and existing BIS IS 15489 certification portfolios. Monitor state pollution control board enforcement of MEE guidelines as the signal for technology migration timing and water-based formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | PLI scheme subsidies alter raw material economics for water-based formulators in Gujarat. |
| Performance-Based Maintenance Contracts | Asset life guarantees transform coating vendors into recurring revenue service providers. |
| Fire-Retardant Certification Investment | CEA mandates for electrical infrastructure create utility sector procurement access. |
| Powder Coating Capacity Expansion | Zero-VOC profiles position expansion beyond wheels into body-in-white applications. |
| Digital Quality Assurance Integration | Sensor-enabled film thickness verification reduces application technician dependency. |
Research Methodology
BIS certification databases, state pollution control board enforcement records, and automotive OEM supplier qualification documents formed the secondary backbone for demand quantification. Primary interviews with plant engineers at Reliance Industries and Indian Oil refineries, procurement leads at Chennai and Pune automotive facilities, distribution channel partners in Mumbai and Ahmedabad, and technical R&D directors at integrated paint manufacturers combined with customs data on specialty additive imports. Bottom-up coating consumption estimates triangulated against top-down manufacturing sector capital expenditure allocations.
Bottom-up modeling aggregated substrate-specific film thickness specifications, reapplication frequencies, and end-use environment severity across automotive, industrial equipment, infrastructure, and oil and gas verticals. Segmentation dimensions included formulation chemistry, technology migration stage, certification tier, and regional manufacturing cluster density. CAGRs derived from regression against industrial production indices, automotive OEM capacity announcements, and regulatory compliance timeline enforcement patterns. Forecast inputs incorporated PLI scheme disbursement schedules and MEE guideline implementation trajectories.
The model holds under sustained BIS certification enforcement and PLI scheme continuity; deviation in state pollution control board MEE compliance timelines or petrochemical feedstock supply disruptions would shift technology migration rates and margin structures. Practitioners should monitor BIS laboratory testing queue lengths and specialty additive import tariff adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Water Color Market