
 Global Waterborne Coatings Market | 2026-2036
Global Waterborne Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterborne Coatings Market Foresight
The EU Green Deal's industrial emissions benchmarks is consolidating procurement standards across European automotive and construction supply chains. PPG Industries leverages its North American distribution density to sustain volume leadership in OEM refinish segments. AkzoNobel anchors its position through marine and yacht coating specialization, while Jotun competes aggressively in protective coatings for offshore energy infrastructure across Nordic and Middle Eastern project corridors.
Waterborne coatings disperse resin binders in water rather than organic solvents, typically containing 10-20% volatile organic compounds by volume versus 50-80% in conventional solvent systems, and serve primarily to reduce hazardous air emissions during application and curing. Acrylic formulations dominate architectural surface applications due to their balance of cost, durability, and color retention in exterior exposure. Polyurethane segments command premium positioning in industrial equipment and wood finishes where abrasion resistance and chemical tolerance justify higher formulation complexity. Epoxy waterborne systems are penetrating marine vessel applications as shipyards in South Korea and Japan retrofit spray booths to meet port authority emission protocols.
EPA NESHAP standards for surface coating operations and REACH Annex XVII restrictions on solvent-based formulations are compressing viable product portfolios and redirecting R&D budgets toward compliant resin chemistry. China's MEE enforcement of GB standards on industrial VOC emissions is accelerating domestic waterborne conversion in manufacturing hubs around Shanghai and Guangdong. Formulators, applicators, and raw material suppliers must monitor regulatory divergence between jurisdictions to avoid stranded capacity in solvent-based production assets.
Market Dynamics
REACH Annex XVII restrictions on solvent-based formulations and China's MEE enforcement of GB standards are compressing viable product portfolios and redirecting R&D budgets toward compliant resin chemistry across automotive, marine, and industrial verticals.
Growth Catalysts
- Automotive OEM refinishing conversion:Assembly lines in Germany, the United States, and Japan are retrofitting spray infrastructure to meet EPA NESHAP and EU Green Deal industrial emissions benchmarks, pulling waterborne system adoption.
- MEE enforcement in China:The Ministry of Ecology and Environment's GB standard implementation around Shanghai and Guangdong manufacturing hubs is accelerating domestic solvent-to-waterborne conversion at industrial scale.
- Epoxy waterborne penetration:Shipyards in South Korea and Japan are retrofitting spray booths to meet port authority emission protocols, opening marine vessel applications previously locked by solvent performance requirements.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin precursors track naphtha and propylene pricing, compressing formulation margins during upstream commodity spikes.
- Application equipment retrofit costs:Existing solvent-optimized spray booths, drying ovens, and fluid delivery systems require capital-intensive reconfiguration to handle waterborne viscosity and flash profiles.
- Cold-climate performance limitations:Waterborne epoxy and polyurethane films exhibit extended cure times and reduced hardness development below 10°C, restricting year-round outdoor application in Nordic and alpine geographies.
Strategic Opportunities
- India industrial manufacturing expansion:BIS standards alignment with REACH-equivalent VOC limits is creating first-mover advantage for formulators establishing technical service presence in Gujarat and Maharashtra chemical corridors.
- Offshore wind tower coating specifications:Protective coating contracts for North Sea and Baltic installations are specifying waterborne epoxy systems to satisfy EU Green Deal procurement criteria and port state control inspections.
- Digital color-matching platform integration:Cloud-based spectrophotometry and AI-driven tinting systems are reducing refinish cycle times and inventory carrying costs for automotive body shops.
Industry Challenges
- Formulator-applicator skill transfer:Waterborne film formation, humidity control, and flash timing require retraining of experienced solvent-system technicians, extending qualification timelines.
- Cross-jurisdiction certification complexity:Divergent EPA, REACH, and MEE test protocols for VOC content, corrosion resistance, and weathering performance force parallel product development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterborne Coatings Market |
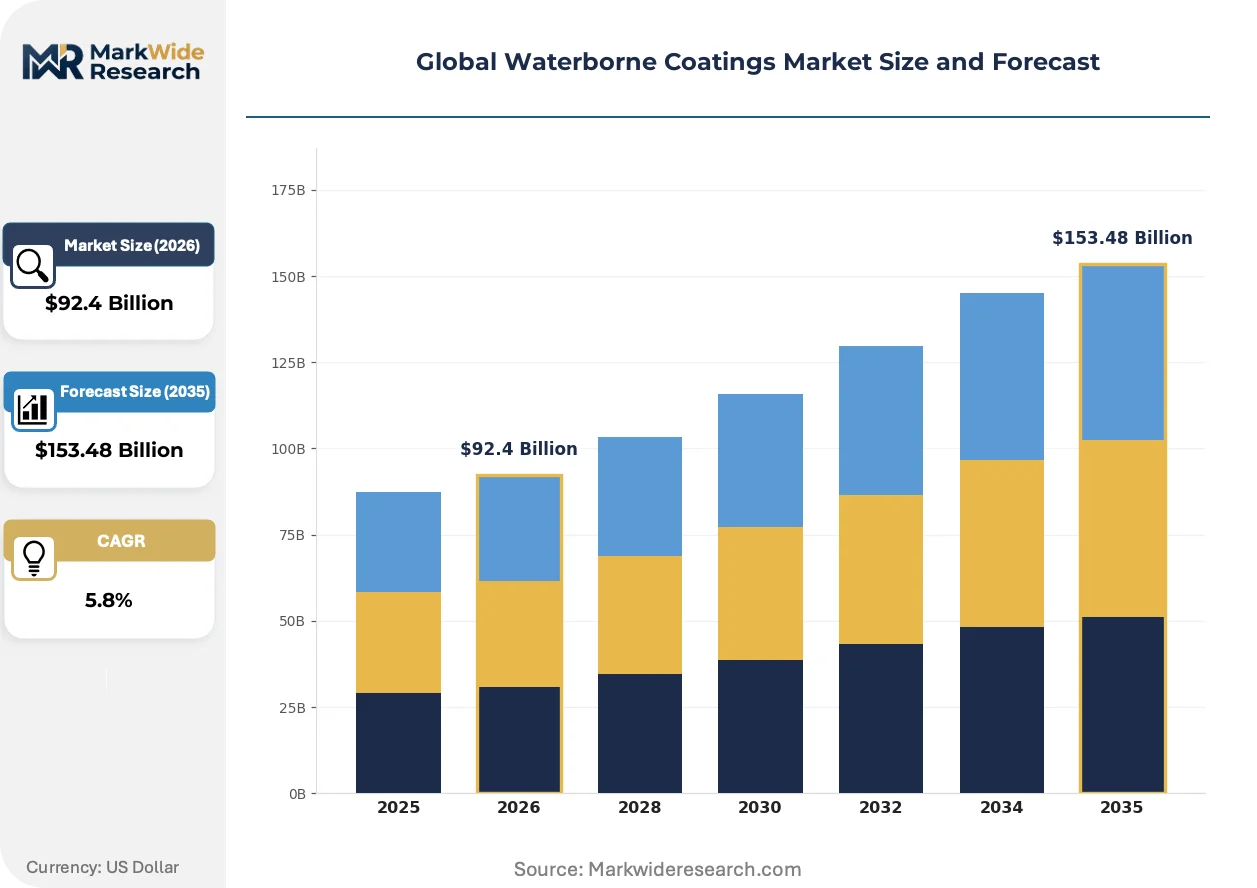
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Alkyd, Vinyl, Silicone Application: Architectural Surfaces, Marine Vessels, Industrial Equipment, Consumer Goods, Protective Coatings, Wood Finishes End User Industry: Construction, Shipbuilding, Manufacturing, Furniture, Aerospace, Electronics Packaging Type: Drums, Pails, Carboys, Totes, Cans, Bottles |
| Companies Covered | PPG Industries, Sherwin-Williams Company, AkzoNobel, BASF SE, Axalta Coating Systems, Dow, Jotun, Hempel, Nippon Paint Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterborne Coatings Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and procurement specifications are converging to redefine competitive advantage in protective and decorative coating supply chains.
Hybrid acrylic-polyurethane dispersion technology is consolidating architectural and light industrial applications by delivering exterior durability approaching solvent-borne alkyds with sub-50 g/L VOC content. German and Dutch coating contractors are specifying these systems for municipal infrastructure and commercial facade projects. The technology is consolidating mid-tier supplier positions by collapsing the traditional premium-economy segmentation in exterior maintenance coatings.
EU Green Deal industrial emissions benchmarks are consolidating procurement standards across European automotive and construction supply chains. Tier-1 suppliers to German OEMs must now document waterborne system share in sustainability scorecards to maintain preferred vendor status. French and Italian refinish distributors are restructuring inventory mixes to align with CSRD-aligned customer reporting requirements.
Automotive fleet operators and municipal procurement departments are unbundling coating specification from application service contracts, issuing performance-based tenders that emphasize warranty terms and lifecycle cost over unit price. This model is displacing traditional distributor-led specification in United States municipal transit and German rail refurbishment programs. The shift is most visible in California and New York state procurement frameworks, where low-VOC mandates intersect with public-sector sustainability disclosure rules.
Global Waterborne Coatings Market Segmentation
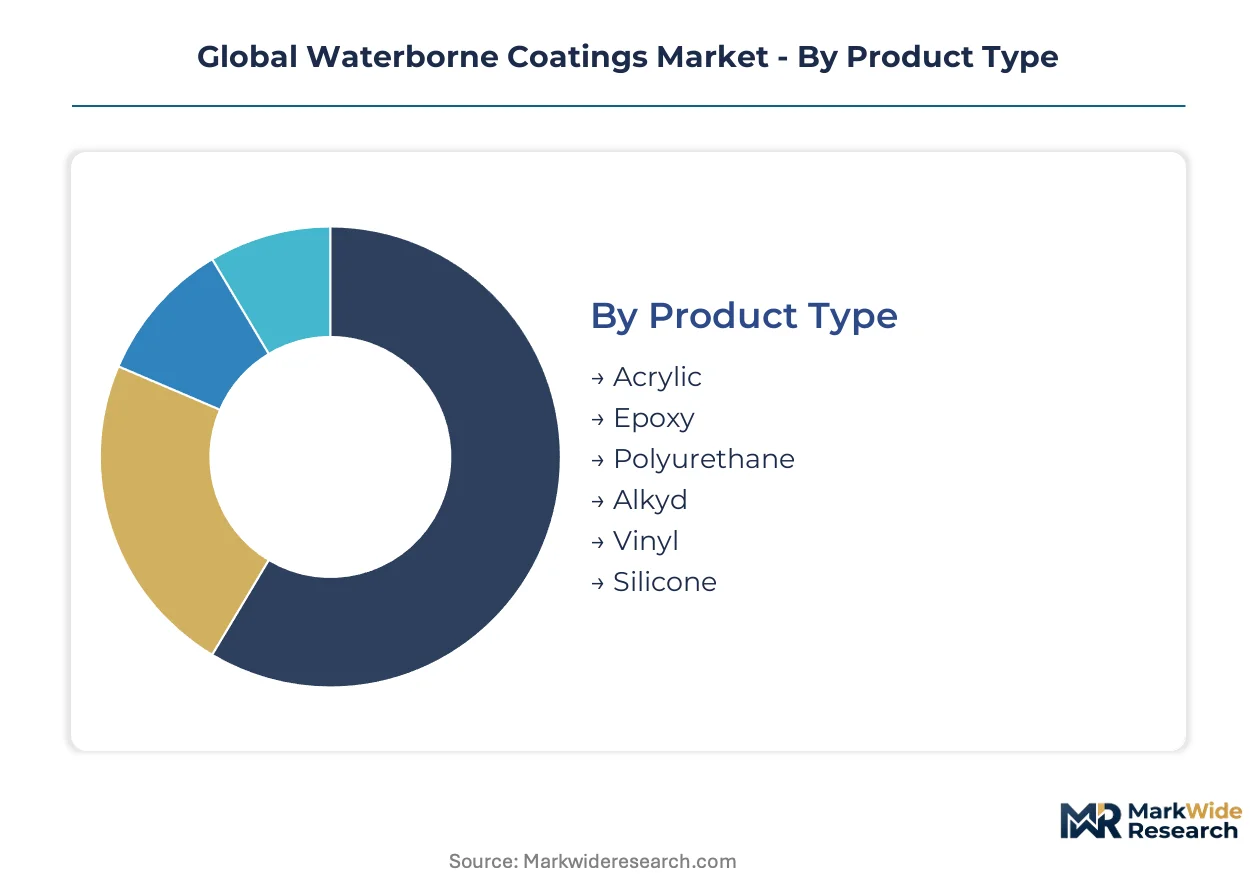
Waterborne coatings segmentation reflects divergent certification burdens across chemistry classes and end-use specifications. Product type determines REACH Annex XVII and EPA NESHAP compliance pathways, while application segments dictate performance testing protocols for corrosion resistance and weathering durability.
Product Type:
Certification requirements cluster around VOC content thresholds and corrosion performance standards, with acrylic and polyurethane systems facing distinct EPA and REACH validation protocols for architectural versus industrial use cases.
- Acrylic:Thermoplastic resin dispersions formulated for exterior color retention and UV stability in building facades. Demand concentrates in German municipal infrastructure and Dutch commercial construction where EU Green Deal procurement mandates specify sub-50 g/L VOC content for public tenders. REACH compliance documentation adds 12-18 months to product qualification timelines for cross-border European distribution.
- Polyurethane:Two-component waterborne systems delivering abrasion resistance and chemical tolerance for industrial equipment and wood finishes. Japanese automotive OEM refinishing lines and United States cabinet manufacturers drive specification, with EPA NESHAP surface coating standards requiring third-party VOC verification for facility compliance audits.
- Epoxy:Amine-cured waterborne systems penetrating marine vessel applications as South Korean and Japanese shipyards retrofit spray booths to meet port authority emission protocols.
- Alkyd:Modified polyester resins offering solvent-borne performance characteristics in water-dispersible formats for maintenance coatings.
- Vinyl:Chlorinated polymer emulsions specified for concrete sealing and swimming pool applications requiring moisture barrier properties.
- Silicone:Hybrid organic-inorganic systems delivering thermal stability and weathering resistance for high-performance architectural specifications.
Leading the category by volume: Acrylic. Growing fastest: Polyurethane.
Application:
Cost tier differentiation separates commodity architectural volumes from premium protective specifications, with marine and industrial segments commanding formulation complexity premiums.
- Architectural Surfaces:Exterior and interior building coatings representing the volume foundation of waterborne consumption. German and Dutch coating contractors specify hybrid acrylic-polyurethane systems for municipal infrastructure and commercial facade projects where lifecycle cost calculations displace unit-price procurement.
- Marine Vessels:Ship hull, deck, and superstructure coatings subject to port state control inspection regimes. South Korean shipyards in Ulsan and Geoje drive epoxy waterborne adoption as IMO-aligned emission protocols tighten solvent-based application windows.
- Industrial Equipment:Manufacturing machinery and infrastructure protective coatings requiring chemical resistance and thermal cycling tolerance.
- Consumer Goods:Appliance, electronics housing, and recreational product finishes where aesthetic consistency and scratch resistance balance cost constraints.
- Protective Coatings:Offshore wind tower and pipeline specifications in the North Sea and Baltic installations mandating waterborne epoxy systems for EU Green Deal procurement compliance.
- Wood Finishes:Furniture and flooring coatings where polyurethane waterborne systems displace solvent-based conversion varnishes in United States and Italian manufacturing.
Architectural Surfaces dominates shipment volumes. Protective Coatings expands most quickly on offshore wind infrastructure investment.
End User Industry:
Customer type fragmentation separates project-based construction demand from OEM-integrated manufacturing procurement, with shipbuilding and aerospace requiring longest qualification cycles.
- Construction:Residential, commercial, and infrastructure building activity across China, Germany, and the United States. Shanghai and Guangdong manufacturing hubs accelerate solvent-to-waterborne conversion under MEE GB standard enforcement.
- Shipbuilding:Newbuild and maintenance coating programs in South Korea, Japan, and Chinese yards. Port authority emission protocols in Busan, Yokohama, and Shanghai mandate spray booth retrofit investments.
- Manufacturing:Industrial equipment OEM and maintenance coating demand spanning automotive, machinery, and fabricated metal products.
- Furniture:Residential and contract furniture finishing where Italian and United States manufacturers specify waterborne polyurethane for VOC compliance.
- Aerospace:Aircraft interior and exterior coating specifications requiring FAA and EASA flame resistance and durability certification.
- Electronics:Device housing and component coatings where thin-film waterborne systems balance appearance with functional performance.
Construction leads by volume. Shipbuilding gains share fastest on marine emission regulation tightening.
Packaging Type:
Supply concentration in drum and tote formats reflects bulk industrial procurement patterns, with pail and can segments serving distributor-dealer maintenance coating channels.
- Drums:200-liter steel and polymer containers for high-volume industrial and marine coating distribution. German and United States formulators standardize drum specifications for OEM direct procurement.
- Pails:20-liter plastic containers serving contractor and maintenance applicator segments. French and Italian refinish distributors restructure inventory mixes to align with CSRD-aligned customer reporting requirements.
- Carboys:Glass and polymer vessels for specialized additive and hardener components requiring chemical compatibility protection.
- Totes:Intermediate bulk containers for large-scale manufacturing and shipyard consumption minimizing packaging waste.
- Cans:Retail and professional trade sizes for architectural and consumer goods applications.
- Bottles:Small-volume specialty formulations for touch-up, repair, and sample distribution.
Drums lead the category by volume. Totes represent the steepest expansion trajectory on bulk procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors waterborne coatings demand through its concentration of automotive assembly plants and shipbuilding yards undergoing simultaneous EPA NESHAP and MEE GB standard compliance retrofits. Manufacturing clusters across three continents drive specification divergence between architectural and industrial formulations.
China
Automotive OEM refinishing lines in Guangdong and Yangtze River Delta manufacturing hubs accelerate solvent-to-waterborne conversion under MEE enforcement of GB standards on industrial VOC emissions. Shanghai port authorities mandate spray booth retrofit investments for vessel maintenance contractors. Domestic formulators concentrate technical service presence in Jiangsu and Zhejiang chemical corridors to capture state-backed infrastructure procurement.
Germany
Automotive OEM sustainability scorecards now document waterborne system share for Tier-1 supplier qualification under EU Green Deal industrial emissions benchmarks. Bavarian and Baden-Württemberg coating contractors specify hybrid acrylic-polyurethane systems for municipal infrastructure projects. REACH Annex XVII compliance documentation extends product qualification timelines for cross-border European distribution.
United States
California and New York state procurement frameworks intersect low-VOC mandates with public-sector sustainability disclosure rules for municipal transit and rail refurbishment programs. EPA NESHAP surface coating standards require third-party VOC verification for facility compliance audits in automotive and industrial equipment segments. Cabinet manufacturers in Southeast and Midwest regions drive waterborne polyurethane specification for wood finishes.
South Korea
Shipyards in Ulsan and Geoje drive epoxy waterborne adoption as IMO-aligned port authority emission protocols tighten solvent-based application windows. Busan port state control inspections mandate compliant coating documentation for vessel maintenance contractors. Domestic formulators align product development with Japanese shipyard qualification protocols for cross-border marine project bidding.
India
BIS standards alignment with REACH-equivalent VOC limits creates first-mover positioning for technical service presence in Gujarat and Maharashtra chemical corridors. Construction activity in Delhi-NCR and Bangalore metropolitan regions concentrates architectural coatings demand. Industrial manufacturing expansion in Tamil Nadu and Karnataka pulls protective coatings specification for machinery and fabricated metal products.
Global Waterborne Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification documentation intensity. The vendor base organizes into three tiers: integrated resin-coating conglomerates with captive raw material supply; specialized marine and protective coating houses with project-based contracting expertise; and regional architectural formulators competing on distributor coverage and tinting service speed. M&A activity concentrates on resin technology acquisitions and geographic whitespace entry through distressed solvent-based asset purchases.
Within the integrated conglomerate tier, PPG Industries and AkzoNobel occupy positions exemplifying divergent specialization strategies—North American OEM refinish distribution density versus marine and yacht coating technical depth. Jotun represents the project-contracting specialist archetype with protective coatings positioning for offshore energy infrastructure. These three anchors illustrate how competitive advantage fragments across regulatory jurisdiction mastery, end-use specification capture, and raw material integration depth.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams Company |
| AkzoNobel |
| BASF SE |
| Axalta Coating Systems |
| Dow |
| Jotun |
| Hempel |
| Nippon Paint Holdings |
| Others |
Supply & Pricing Matrix
Naphtha and propylene price indices cascade through waterborne coatings supply chains, compressing formulation margins for acrylic and polyurethane resin producers while amplifying pricing power for backward-integrated conglomerates with captive petrochemical supply. This raw-material volatility stratifies the market into three performance tiers: premium polyurethane systems for automotive OEM refinishing, standard acrylic architectural coatings, and economy alkyd maintenance formulations.
Pricing Analysis
Outcome-based contracting tied to warranty duration and lifecycle coating performance anchors premium pricing for marine and protective applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence, with REACH Annex XVII and EPA NESHAP compliance documentation adding substantial qualification costs to premium tiers. Price erosion runs through standard architectural acrylics as Chinese domestic formulators expand export capacity. Municipal procurement departments in Germany and the United States exhibit highest price sensitivity, while offshore wind EPC contractors prioritize performance guarantees over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's BIS standards alignment and China's GB standard enforcement are reshaping raw-material sourcing patterns toward regional resin production hubs. Supply concentrates in China, Germany, and the United States for acrylic emulsion production, with epoxy curing agents drawing from South Korean and Japanese specialty chemical manufacturers. Naphtha and propylene feedstock dependencies create margin vulnerability during upstream commodity spikes. Single-source vulnerability characterizes amine hardener supply for epoxy waterborne systems. Distribution runs through drum and tote bulk formats for OEM direct procurement, with pail segments serving contractor maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coatings markets function as a cost-of-compliance story where REACH Annex XVII and EPA NESHAP certification investments erect substantial barrier-to-entry moats favoring incumbents with established regulatory affairs infrastructure and documented qualification histories.
For Market Incumbents: Deploy technical service capacity expansion as the primary defensive lever. Deepen captive resin production for acrylic and polyurethane precursors to insulate margin structures from naphtha volatility. Acquire distressed solvent-based coating assets in European and North American manufacturing corridors to consolidate distribution density and block emerging competitor facility access. Certification documentation archives represent defensible intellectual property against unqualified entrants. For New Entrants and Emerging Players: Small-to-mid shipyards in India's Gujarat chemical corridor present the most penetrable buyer archetype for first-mover positioning. Target BIS standards-aligned waterborne epoxy qualification ahead of domestic enforcement intensification. Establish toll-manufacturing partnerships with existing resin producers to bypass capital-intensive backward integration requirements. Digital color-matching platform integration offers differentiated entry angle for automotive refinish distributor channels. For Investors and Strategic Acquirers: The window for entry favors specialized marine and protective coating houses with project-contracting expertise and established port authority relationships. Long-term viability hinges on regulatory jurisdiction mastery across EPA, REACH, and MEE enforcement patterns. Watch for MEE GB standard implementation acceleration in Shanghai and Guangdong as inflection signal for Chinese domestic consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic and polyurethane supply insulates margin compression from naphtha price volatility. |
| REACH Annex XVII Certification Investment | Documentation archives create 12-18 month qualification barriers against unqualified competitors. |
| Technical Service Presence Expansion | Localized formulation support captures state-backed infrastructure procurement in Gujarat and Maharashtra. |
| Digital Color-Matching Platform Deployment | Cloud-based spectrophotometry reduces refinish cycle times for automotive body shop distributors. |
| Distressed Solvent-Based Asset Acquisition | Manufacturing facility purchases in European corridors block emerging competitor geographic entry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving coating formulators, automotive OEM procurement leads, shipyard technical directors, and industrial equipment maintenance managers. EPA NESHAP compliance documentation, REACH Annex XVII substance restrictions, and MEE GB standard enforcement records provided regulatory boundary conditions. Bottom-up volume modeling triangulated against top-down value estimates from petrochemical feedstock price indices and resin precursor trade flows.
Data-stream reconciliation across shipment volumes, formulation cost structures, and end-use procurement patterns shaped the analytical framework. Segmentation dimensions included resin chemistry class, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of solvent-to-waterborne conversion rates, enforcement intensity trajectories, and manufacturing capacity expansion announcements. Forecast inputs incorporated spray booth retrofit investment cycles, port authority emission protocol adoption timelines, and offshore wind installation procurement specifications.
Revisions become necessary when MEE enforcement intensity deviates from announced GB standard implementation schedules, when petrochemical feedstock volatility exceeds historical bands, or when EU Green Deal procurement criteria expand beyond current industrial emissions benchmarks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Topcoat Market
Coatings
Australia Industrial Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Japan Protective Coatings Market
Coatings
Clear Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Extrusion Coating Market
Coatings
Canada Floor Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
China Protective Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Industrial Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Asia-Pacific Marine Coatings Market