
 Chemical Silage Additives Market | 2026-2036
Chemical Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Silage Additives Market Analytics
Organic acid blends are consolidating around buffered propionic and formic acid formulations as farmers phase out mineral salt preservatives that corrode equipment and limit palatability. BASF SE leverages its industrial chemical backbone to supply standardized acid premixes at scale across European cooperatives. Chr. Hansen Holding A/S specializes in multi-strain bacterial inoculants with documented homofermentative dominance, while Lallemand Inc. anchors North American supply through yeast-compatible fermentation enhancers.
Chemical silage additives comprise formulated organic acids, bacterial inoculants, enzymes, and preservatives applied to forage crops to accelerate lactic acid fermentation, suppress spoilage organisms, and preserve nutritional value through anaerobic storage. Typical application rates range from one to three liters per ton of fresh forage depending on dry matter content and ambient temperature conditions. Among product types, inoculants command the largest volume footprint due to proven efficacy in high-moisture grass and legume silages, while acid-based formulations retain premium positioning in low-sugar crops and challenging harvest windows. Liquid formulations dominate commercial channels for uniform spray application, though powder concentrates gain traction among smaller silage producers seeking extended shelf stability and reduced freight costs.
The European Food Safety Authority (EFSA) evaluates feed additive safety under Regulation (EC) No 1831/2003, requiring full toxicological dossiers before market authorization. REACH compliance governs chemical ingredient disclosure and environmental fate testing for acid-based products manufactured or imported into EU member states. The US Food and Drug Administration (FDA) enforces feed-grade substance standards through the Code of Federal Regulations Title 21, while state-level Department of Agriculture inspectors verify label claims and manufacturing practices. Stakeholders must track evolving residue limits and mutual recognition agreements between jurisdictions to avoid supply disruptions and reformulation costs.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing formulation timelines as producers must certify additives under tightened residue limits before the 2030 sustainability targets lock in. Dairy cooperatives in Germany and the Netherlands are consolidating procurement to secure compliant supply chains ahead of regulatory deadlines.
Growth Catalysts
- REACH-compliant acid premixes:ECHA registration requirements for chemical ingredients are standardizing manufacturing practices and creating entry barriers that favor established European suppliers with full toxicological dossiers.
- Precision fermentation investments:Climate-controlled silage bunkers and automated pH monitoring systems are expanding additive application precision across Western European dairy belts.
- Homofermentative bacterial dominance:Multi-strain inoculants with documented lactic acid conversion rates are displacing mineral salt preservatives in high-moisture grass silage production.
Market Restraints
- Propionic acid feedstock volatility:Petrochemical-derived organic acid precursors expose formulators to crude oil price swings that compress margin stability.
- EFSA authorization timelines:Full toxicological dossier requirements under Regulation (EC) No 1831/2003 extend product launch cycles by 18-36 months.
- Equipment corrosion legacy:Unbuffered formic acid formulations continue to damage stainless steel application machinery, limiting adoption among smaller silage producers.
Strategic Opportunities
- Powder concentrate shelf stability:Extended freight-viable formulations are opening distribution to remote dairy regions in Eastern Poland and Romania where liquid logistics remain costly.
- Enzyme-inoculant convergence:Cellulase-enhanced bacterial preparations are creating hybrid categories that accelerate fiber digestibility in low-sugar forage crops.
- Cooperative procurement platforms:Vertically integrated dairy collectives in Denmark are consolidating additive purchasing through multi-year supply agreements that lock in volume commitments.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and fermentation optimization expertise concentrates among a limited pool of European research institutions.
- Legacy storage infrastructure:Older concrete bunker silos lack anaerobic sealing adequate for high-performance inoculant efficacy, requiring producer education on complementary investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Silage Additives Market |
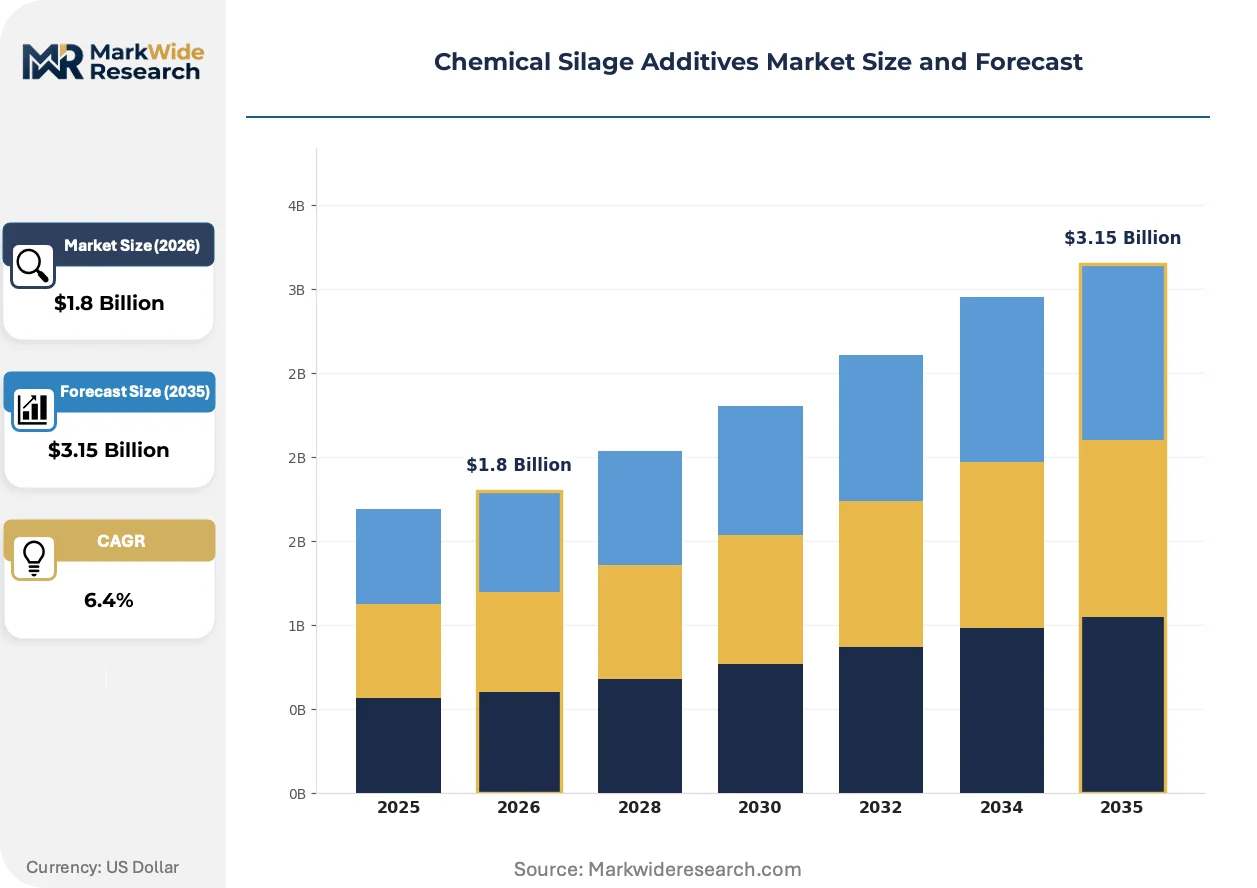
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inoculants, Acids, Enzymes, Preservatives Application: Dairy Cattle, Beef Cattle, Fermentation, Storage Form: Liquid, Powder, Granular, Concentrate End User: Dairy Farms, Feedlots, Silage Producers, Others |
| Companies Covered | BASF SE, ADM, DSM Firmenich, Chr. Hansen Holding A/S, Lallemand Inc., Kemin Industries, Cargill Incorporated, ADDCON GmbH, Volac International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Silage Additives Market Evolving Landscape
Automation and regulatory precision are compressing the gap between additive formulation and on-farm application. Digital monitoring systems now bridge laboratory strain development with real-time fermentation management.
Sensor-integrated application equipment is automating dosage calibration based on real-time dry matter readings and ambient temperature fluctuations. Large dairy operations in the Netherlands are deploying these systems across 500+ ton harvest windows. The technology is automating quality variance reduction that previously required manual sampling and laboratory turnaround.
REACH environmental fate testing requirements are mandating biodegradability documentation for acid-based products manufactured or imported into EU member states. Formulators must now submit aquatic toxicity data and soil persistence studies as standard dossier components. Acid premix suppliers with industrial chemical backbones are absorbing these compliance costs more readily than specialty biotech entrants.
Certification-driven procurement is consolidating buyer preferences around EFSA-authorized formulations with documented homofermentative efficacy. Dairy cooperatives are unbundling after-sales technical support from product supply, contracting independent agronomists for on-farm fermentation audits. This pattern is most visible in northern Germany where precision agriculture adoption rates outpace southern European dairy regions.
Chemical Silage Additives Market Segmentation
Segmentation reveals how formulation chemistry, application context, and farm-scale economics intersect to determine procurement patterns. Each dimension carries distinct regulatory and logistical implications that shape supplier positioning across European dairy belts.
Product Type:
Inoculants dominate volume throughput while acid-based formulations capture premium positioning in challenging harvest conditions.
- Inoculants:Multi-strain bacterial preparations with documented homofermentative lactic acid conversion anchor procurement for high-moisture grass and legume silages. Dairy cooperatives in Germany and the Netherlands specify these for climate-controlled bunker systems where fermentation precision justifies per-ton application costs.
- Acids:Buffered propionic and formic acid blends suppress spoilage organisms in low-sugar crops and adverse weather windows. REACH-compliant premixes from established European chemical suppliers command price premiums over mineral salt alternatives that corrode stainless steel application equipment.
- Enzymes:Cellulase-enhanced preparations accelerate fiber digestibility in mature forage crops.
- Preservatives:Mineral salt formulations persist among cost-sensitive producers phasing out corrosive unbuffered acids.
Mature deployment sits with inoculants. Newer deployment is concentrated in enzyme-inoculant hybrid preparations.
Application:
Dairy cattle feed preservation drives formulation specification while beef operations prioritize dry matter retention economics.
- Dairy Cattle:High-producing herds in the Netherlands and northern Germany demand additives that stabilize rumen-degradable protein through anaerobic storage. EFSA-authorized formulations with documented homofermentative efficacy anchor cooperative procurement contracts.
- Beef Cattle:Feedlot operators in France prioritize dry matter loss reduction over fermentation kinetics, favoring acid-based preservatives for corn silage and high-moisture grain storage.
- Fermentation:pH stabilization applications concentrate in precision agriculture zones with automated monitoring infrastructure.
- Storage:Extended anaerobic preservation requirements shape additive selection for multi-year feed security.
Volume concentration clusters with dairy cattle applications. Steepest expansion trajectory appears in fermentation-integrated systems.
Form:
Liquid formulations dominate commercial channels while powder alternatives address freight economics in peripheral regions.
- Liquid:Uniform spray application compatibility makes this the default for large-scale harvest operations. Dutch dairy collectives deploy sensor-integrated equipment that automates dosage calibration across 500+ ton windows.
- Powder:Extended shelf stability and reduced freight costs open distribution to Eastern Poland and Romania where liquid logistics remain costly. Smaller silage producers favor concentrates for on-farm dilution flexibility.
- Granular:Mechanical spreading compatibility suits bunker silo face management.
- Concentrate:On-farm dilution protocols reduce per-shipment volumes for remote operations.
Established supply chains favor liquid. Powder is gaining share fastest in cooperative procurement platforms consolidating Eastern European purchasing.
End User:
Dairy farm scale determines technical service intensity while feedlot procurement prioritizes volume pricing.
- Dairy Farms:Vertically integrated cooperatives in Denmark consolidate additive purchasing through multi-year supply agreements. These buyers unbundle after-sales technical support from product supply, contracting independent agronomists for fermentation audits.
- Feedlots:Large beef operations in France negotiate acid premix contracts based on dry matter loss guarantees rather than fermentation kinetics.
- Silage Producers:Custom harvest contractors serving multiple farms require formulation flexibility across crop types.
- Others:Sheep and goat operations in Mediterranean regions represent fragmented demand with limited standardization.
Procurement sophistication concentrates with dairy farms. Feedlot additive deployment is expanding most quickly as beef operations adopt dairy-sector fermentation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork strategy operates as a special regulatory zone compressing formulation timelines across member states, with sustainability certification requirements concentrating additive procurement in Western European dairy belts ahead of 2030 targets.
Germany
Dairy cooperatives in Lower Saxony and Bavaria are consolidating procurement through multi-year supply agreements for EFSA-authorized inoculants. The country's Federal Office of Consumer Protection and Food Safety enforces strict residue limits under the Feed Regulation. Precision fermentation infrastructure clusters around Münsterland, where climate-controlled bunkers now exceed 500-ton capacity.
France
Beef feedlot operators in Brittany prioritize acid-based preservatives for corn silage dry matter retention. ANSM coordinates with EFSA on feed additive safety assessments under harmonized EU frameworks. The Grand Est region anchors formulation manufacturing, with Strasbourg-area chemical suppliers absorbing REACH compliance costs ahead of smaller competitors.
Netherlands
High-producing dairy herds in Friesland demand additives stabilizing rumen-degradable protein through automated pH monitoring. The Dutch Food and Consumer Product Safety Authority implements EFSA guidelines with accelerated authorization pathways for documented homofermentative strains. Wageningen University's fermentation research cluster supplies technical talent to regional cooperatives.
Denmark
Vertically integrated dairy collectives are unbundling after-sales technical support from product supply, contracting independent agronomists for fermentation audits. The Danish Veterinary and Food Administration maintains stringent import controls on non-EFSA-authorized formulations. Jutland's precision agriculture adoption rates outpace southern European dairy regions.
Poland
Eastern dairy regions are shifting toward powder concentrate formulations as liquid logistics remain costly in remote areas. The country's Chief Veterinary Officer aligns national feed safety standards with EU Green Deal sustainability targets. Podlaskie Voivodeship represents the fastest-expanding procurement zone for shelf-stable additive distribution.
Chemical Silage Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial chemical conglomerates commanding acid premix supply and biotechnology firms anchoring bacterial inoculant development. The vendor base concentrates around three strategic archetypes: diversified chemical majors with REACH-compliant manufacturing infrastructure, dedicated fermentation specialists with strain characterization capabilities, and regional distributors with cooperative procurement relationships. Capacity expansion and portfolio diversification represent the dominant competitive moves, as established players absorb environmental fate testing costs that exclude smaller entrants.
Within the diversified chemical tier, BASF SE exemplifies the industrial backbone supplier archetype, leveraging standardized manufacturing at scale across European cooperatives. Chr. Hansen Holding A/S and Lallemand Inc. occupy positions within the fermentation specialist tier, with the Danish firm representing multi-strain bacterial expertise and the North American entity anchoring yeast-compatible supply relationships. ADDCON GmbH sits among mid-scale German chemical formulators with regional cooperative penetration.
| Leading Market Players |
|---|
| BASF SE |
| ADM |
| DSM Firmenich |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| Kemin Industries |
| Cargill Incorporated |
| ADDCON GmbH |
| Volac International Limited |
| Others |
Value Network & Pricing Analysis
Dairy cooperative procurement concentration in Germany, the Netherlands, and Denmark anchors contract-based pricing with multi-year volume commitments. EFSA-authorized formulations command premiums over mineral salt alternatives, while powder concentrates trade at freight-adjusted discounts in Eastern European markets.
Pricing Analysis
Short lead-time premiums apply to REACH-compliant acid premixes during compressed harvest windows when dairy cooperatives face spoilage risk. Three-tier pricing structure across EFSA-authorized premium formulations, standard bacterial inoculants, and economy mineral salts reflects certification grade and after-sales technical support bundling. Cost compression in unbuffered acid tiers is intensifying because equipment corrosion damage drives buyer migration toward buffered alternatives. Smaller silage producers in Poland and Romania exhibit highest price sensitivity, while vertically integrated Danish collectives prioritize fermentation performance guarantees over per-ton economics.
Supply Chain Analysis
Single-source vulnerability sits with petrochemical-derived propionic acid feedstocks concentrated in German and Belgian industrial chemical corridors. Formulation chemistry draws from crude oil refining byproducts, lactic acid bacterial cultures, and cellulase enzyme preparations. Supply chain risk centers on commodity price volatility in organic acid precursors that exposes margin stability to energy market swings. Distribution runs through cooperative procurement platforms consolidating additive purchasing across multi-farm collectives, with regional distributors serving fragmented Mediterranean livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical silage additives sector sits in a technology-transition phase as sensor-integrated application equipment and automated pH monitoring displace manual dosage calibration. Precision fermentation infrastructure investments are compressing the performance gap between laboratory strain development and on-farm execution.
For Market Incumbents: Hedge against microbiologist talent scarcity by anchoring strain characterization partnerships with Wageningen University and Danish fermentation research clusters. Capacity addition in Poland and Romania captures powder concentrate demand growth while EFSA authorization timelines create regulatory moats against smaller biotech entrants. Backward integration into bacterial culture production reduces dependency on third-party strain suppliers. For New Entrants and Emerging Players: Enzyme-inoculant hybrid formulations offer a technology-first wedge into low-sugar forage segments where fiber digestibility acceleration commands performance premiums. Eastern Poland's dairy belt represents the most penetrable geography given liquid logistics constraints and cooperative procurement consolidation gaps. A go-to-market angle emphasizing shelf-stable powder distribution bypasses established liquid supply chain incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German chemical formulators with REACH-compliant manufacturing infrastructure and regional cooperative relationships in Lower Saxony. Long-term viability over the projection horizon rests on EFSA authorization dossier depth and climate-controlled bunker silo penetration rates in target dairy belts. The signal to watch is cooperative unbundling of technical support from product supply, which shifts procurement power toward independent agronomist networks.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Authorization Investment | Full toxicological dossiers under Regulation (EC) No 1831/2003 lock out non-compliant competitors from German and Dutch procurement. |
| Backward Integration into Strain Development | In-house bacterial culture production reduces dependency on European research institution partnerships for homofermentative strain access. |
| Powder Concentrate Manufacturing Scale-Up | Extended shelf stability opens distribution to Podlaskie Voivodeship and Romanian dairy regions where liquid logistics remain costly. |
| Sensor-Integrated Equipment Partnership | Automated dosage calibration based on real-time dry matter readings anchors premium positioning in 500-ton Dutch harvest operations. |
| Cooperative Procurement Platform Integration | Multi-year supply agreements with Danish and German dairy collectives lock in volume commitments ahead of 2030 Farm to Fork compliance deadlines. |
Research Methodology
EFSA feed additive authorization databases, REACH registration filings with ECHA, and EU customs trade statistics formed the secondary backbone. Primary interviews with dairy cooperative procurement managers, silage equipment distributors, bacterial inoculant R&D directors, and agricultural extension officers validated formulation adoption patterns. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against dairy herd population data anchored volume projections.
Historical trendline analysis of inoculant penetration rates in high-moisture grass silage and acid-based formulation adoption in corn silage informed the projection framework. Segmentation modeling spanned product chemistry, application livestock type, formulation physical state, and farm-scale economics across the analysis window. CAGRs were derived from regression analysis of cooperative procurement contract values and climate-controlled bunker investment cycles. Forecast inputs incorporated Farm to Fork regulatory timeline assumptions and precision fermentation infrastructure deployment rates in Western European dairy belts.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock price shocks, EFSA authorization pathway delays beyond standard timelines, and cooperative merger activity consolidating buyer power. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology adoption S-curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Performance Minerals Additives Market
Additives
Global Cement Additives Market
Additives
Polymeric Plasticizer Market
Additives
United States Betaine Market
Additives
Apocarotenal Market
Additives
Conditioning Agent Market
Additives
Thermal Conductive Additives Market
Additives
Global Chelated Trace Minerals Market
Additives
Friction Modifier Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Middle East Feed Additives Market
Additives
Tartaric Acid Market
Additives
Fuel Additives Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Phenolic Antioxidant Market
Additives
Oilfield Drilling Fluid Additive Market