
 Polyolefin Resin Paints Market | 2026-2036
Polyolefin Resin Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Resin Paints Market Outlook
Aftermarket service revenue is reconfiguring competitive economics across the Polyolefin Resin Paints value chain. Dow leverages captive polyethylene resin production to secure feedstock cost advantages in coating-grade polyolefin supply. SABIC anchors its position through vertical integration from cracker operations to specialty polymer derivatives. AkzoNobel differentiates via water-based polyolefin paint portfolios aligned with tightening environmental standards.
Polyolefin resin paints are thermoplastic-based coating systems formulated from polyethylene, polypropylene, or their copolymers, typically applied at film builds of 25-75 microns to deliver chemical resistance and flexibility on low-surface-energy substrates. These coatings serve primarily to protect automotive plastics, industrial equipment, and marine structures from corrosion, UV degradation, and mechanical wear. Water-based formulations now lead product type dynamics as regulatory pressure on solvent emissions intensifies, while powder coatings represent the fastest-growing segment driven by zero-VOC profiles and overspray recyclability in automotive OEM lines. Marine coatings command premium positioning due to specialized salt-spray resistance requirements and limited qualified supplier pools.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation volumes in the United States, while REACH registration requirements in Europe elevate compliance costs for imported resin systems. China's GB standards on volatile organic compound content in coatings, enforced by MEE, are redirecting domestic production capacity toward water-based and powder technologies. Stakeholders must monitor regulatory divergence across these jurisdictions to align R&D pipelines with diverging compliance thresholds.
Market Dynamics
Water-based polyolefin paint formulations are compressing solvent-borne capacity as EPA NESHAP and REACH VOC limits tighten across automotive OEM supply chains. This technology shift is redrawing raw material sourcing patterns and forcing resin suppliers to reconfigure production assets.
Growth Catalysts
- REACH Phase-Out Deadlines:ECHA restrictions on solvent-based industrial coatings are redirecting European automotive plastic component demand toward compliant water-borne systems.
- China's Dual Carbon Goals:MEE enforcement of GB standards on VOC content is accelerating domestic powder coating line conversions in Yangtze River Delta manufacturing clusters.
- Polypropylene Copolymer Advances:Metallocene-catalyzed resin grades with enhanced adhesion to untreated TPO substrates are eliminating plasma pretreatment steps in bumper painting operations.
Market Restraints
- Propylene Feedstock Volatility:Cracker output fluctuations and naphtha-cracking economics in US Gulf Coast complexes transmit directly to coating-grade polyolefin resin pricing.
- Qualified Marine Coating Supplier Concentration:Salt-spray certification requirements limit viable suppliers for offshore platform applications to a handful of specialty formulators.
- Polyurethane Hybrid Substitution:Two-component water-borne urethane systems with superior scratch resistance are capturing share in premium automotive interior trim segments.
Strategic Opportunities
- India PLI Scheme for Automotive:Production-linked incentives for electric vehicle manufacturing are creating first-mover openings in battery enclosure coating specifications.
- UV-Curable Polyolefin Convergence:Combination of low-temperature cure with zero-VOC profiles opens medical device and electronics housing applications previously blocked by thermal sensitivity.
- Direct-to-Installer Digital Channels:B2B platform procurement of certified coating systems is fragmenting traditional distributor control over body shop supply relationships.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in water-borne polyolefin dispersion stability and corrosion inhibitor compatibility commands premium compensation and extends R&D timelines.
- OEM Specification Lock-In:Multi-year qualification cycles for automotive exterior plastic coatings create switching friction even when superior formulations emerge.
- Cross-Border REACH Compliance:Divergent substance registration requirements between EEA member states and post-Brexit UK REACH fragment regulatory filing costs for imported resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Resin Paints Market |
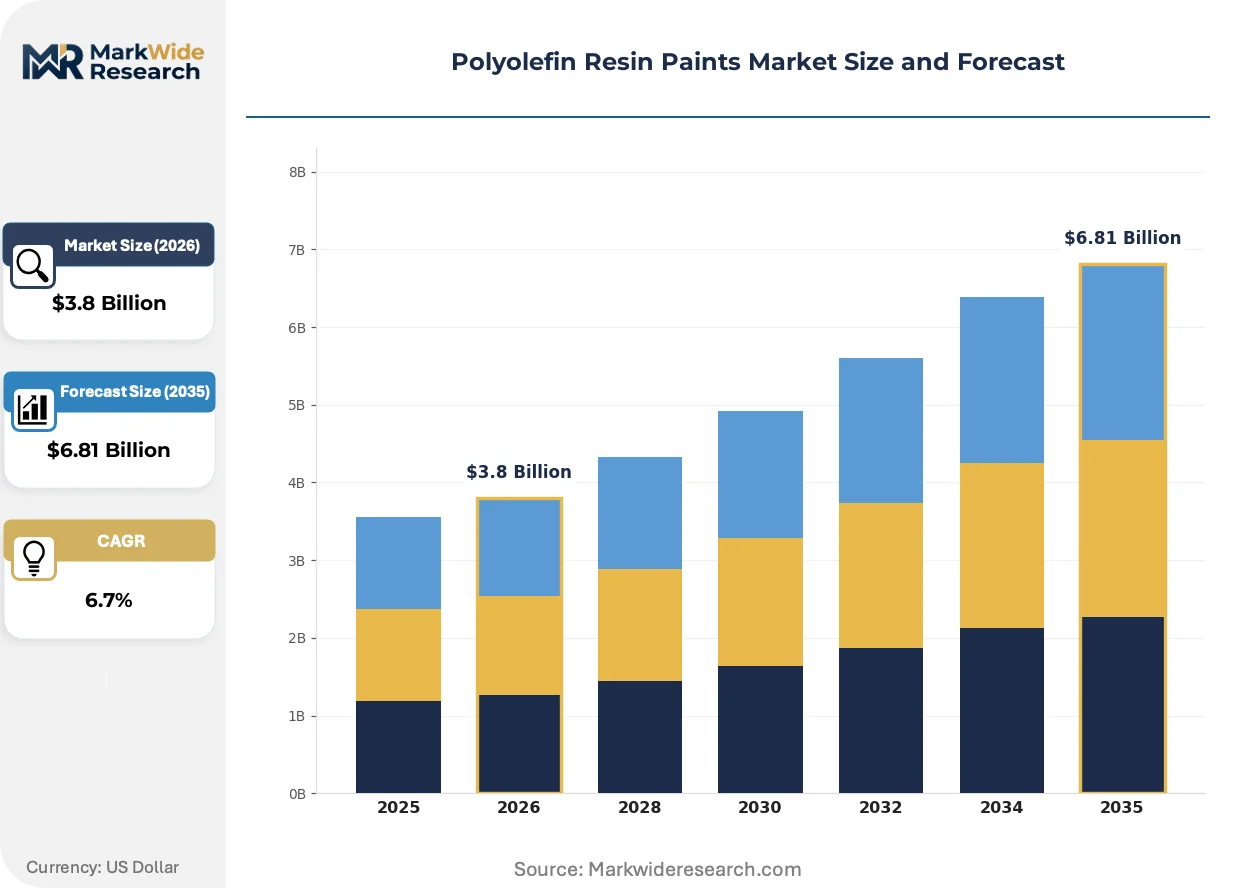
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder Coatings, Emulsion Application: Automotive Coatings, Industrial Coatings, Decorative Paints, Marine Coatings End User: Manufacturers, Contractors, DIY Enthusiasts, Automotive OEMs Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Dow, SABIC, ExxonMobil Corporation, LyondellBasell Industries, Mitsui Chemicals, Borealis AG, AkzoNobel, Sumitomo Chemical, INEOS Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Resin Paints Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and procurement channel structures are undergoing simultaneous recalibration across the polyolefin resin paints value chain.
Self-crosslinking water-borne polyolefin dispersions are collapsing the performance gap between ambient-cure and baked systems in automotive refinish applications. Tier 1 bumper suppliers in Germany and Mexico are adopting these materials to eliminate energy-intensive oven stages. This technology compression is enabling smaller paint shops to bid on OEM warranty repair work previously reserved for factory-authorized facilities with capital-intensive infrastructure.
EPA's National Emission Standards for Hazardous Air Pollutants for miscellaneous metal and plastic parts coatings are tightening permissible HAP content thresholds on a rolling schedule through 2027. US-based industrial coating operations serving agricultural equipment and material handling sectors face staged compliance deadlines that favor early adopters of powder and water-borne technologies. Midwest manufacturing clusters are consolidating solvent-based spray operations and redirecting capital toward electrostatic powder lines with reclaim systems.
Automotive OEMs are unbundling coating procurement from tiered supplier assembly contracts and establishing direct specification relationships with specialty resin formulators. This disintermediation of traditional paint system integrators concentrates technical dialogue between vehicle brand engineering teams and raw material developers. The pattern is most advanced in electric vehicle programs where lightweight plastic body panels require substrate-specific adhesion science that incumbent coating suppliers cannot deliver from standardized portfolios.
Polyolefin Resin Paints Market Segmentation
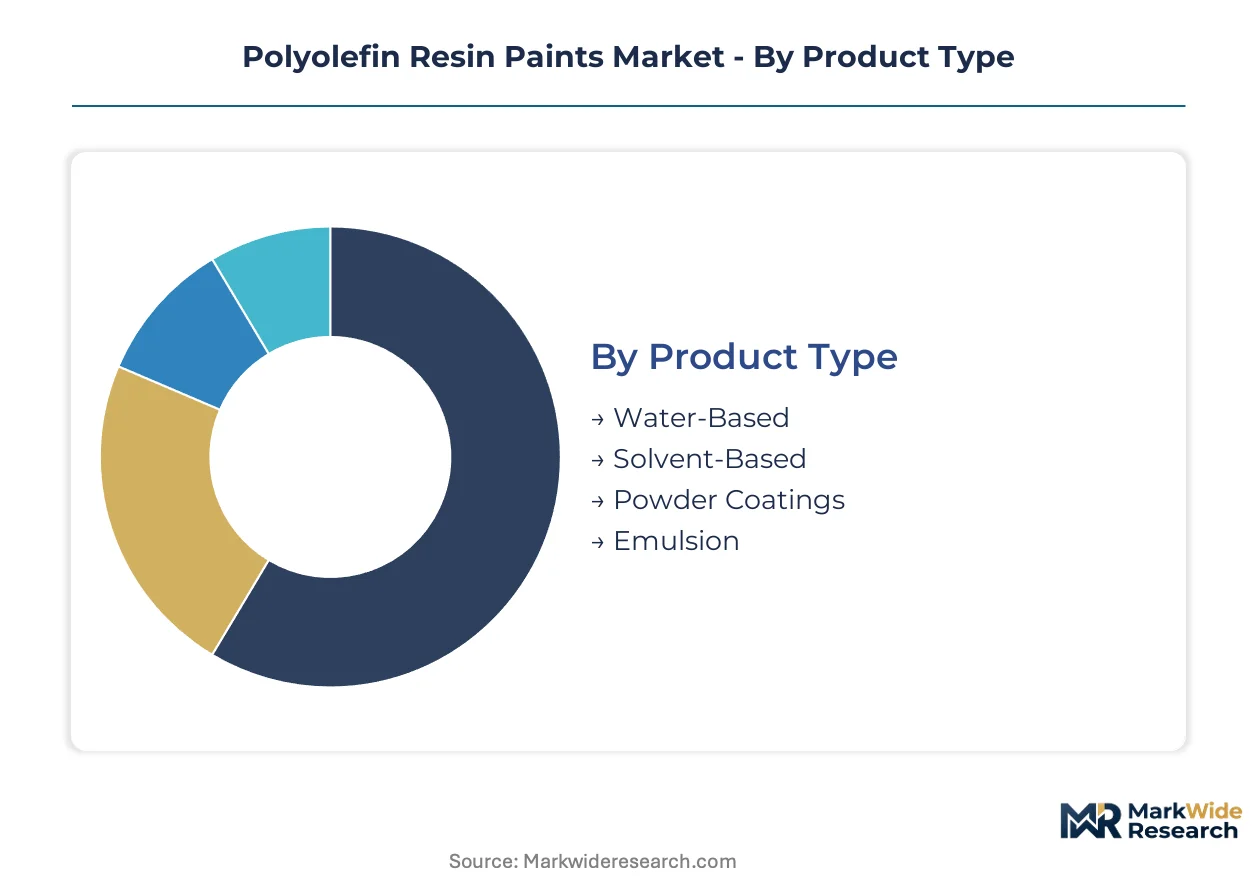
Segmentation in polyolefin resin paints reveals distinct technology lifecycles and procurement rhythms. Water-based formulations turn over fastest as regulatory deadlines force rapid qualification cycles, while marine coatings move slowest due to salt-spray certification barriers. Understanding these velocity differentials helps suppliers align inventory and technical service resources.
Product Type:
Cycle times vary dramatically across formulation chemistries, with ambient-cure systems refreshing specifications annually and baked industrial grades holding formulations stable for five-plus years.
- Water-Based:These dispersions employ self-crosslinking acrylic-modified polyolefin polymers that cure at ambient temperatures. Demand concentrates in German and Mexican automotive bumper operations where energy-intensive oven stages face elimination. EPA NESHAP compliance deadlines accelerate specification turnover.
- Powder Coatings:Zero-VOC thermoplastic powders with overspray recyclability dominate Yangtze River Delta manufacturing conversions. China's MEE enforcement of GB standards redirects capital toward electrostatic lines with reclaim systems in domestic automotive OEM facilities.
- Solvent-Based:Conventional alkyd-modified polyolefin solutions retain foothold in marine maintenance applications where substrate compatibility outweighs emissions constraints.
- Emulsion:Aqueous dispersion systems serve decorative interior markets with lower performance thresholds and price-sensitive procurement.
Water-based systems anchor the volume base while powder coatings gain share at the steepest rate.
Application:
Margin structures diverge sharply across end-use environments, with salt-exposed marine commands premium pricing and commoditized decorative trades on thin spreads.
- Automotive Coatings:Exterior plastic component finishes requiring adhesion to untreated TPO substrates without plasma pretreatment. Specification authority is shifting from tiered integrators to direct OEM engineering relationships in electric vehicle programs.
- Marine Coatings:Salt-spray-resistant systems for offshore platforms with qualified supplier pools limited by certification requirements. North Sea and Gulf of Mexico operators pay substantial premiums for documented performance histories.
- Industrial Coatings:Agricultural equipment and material handling sectors in US Midwest clusters face staged EPA compliance deadlines favoring early powder and water-borne adopters.
- Decorative Paints:Lower-specification interior and exterior architectural applications with price-driven procurement through retail and contractor channels.
Automotive coatings generate the revenue concentration while marine coatings deliver the highest margin per liter applied.
End User:
Procurement sophistication scales with technical specification authority, from standardized catalog orders to multi-year qualification partnerships.
- Automotive OEMs:Direct specification relationships with resin formulators are unbundling from traditional tiered supplier contracts. Lightweight plastic body panels in electric vehicle programs demand substrate-specific adhesion science.
- Manufacturers:Industrial coating operations with in-house application lines and capital equipment investments in electrostatic systems.
- Contractors:Body shop and refinish operations bidding on warranty repair work previously reserved for factory-authorized facilities.
- DIY Enthusiasts:Consumer retail segment with limited technical support requirements and price-elastic demand.
Automotive OEMs concentrate specification authority while contractors represent the most fragmented procurement base.
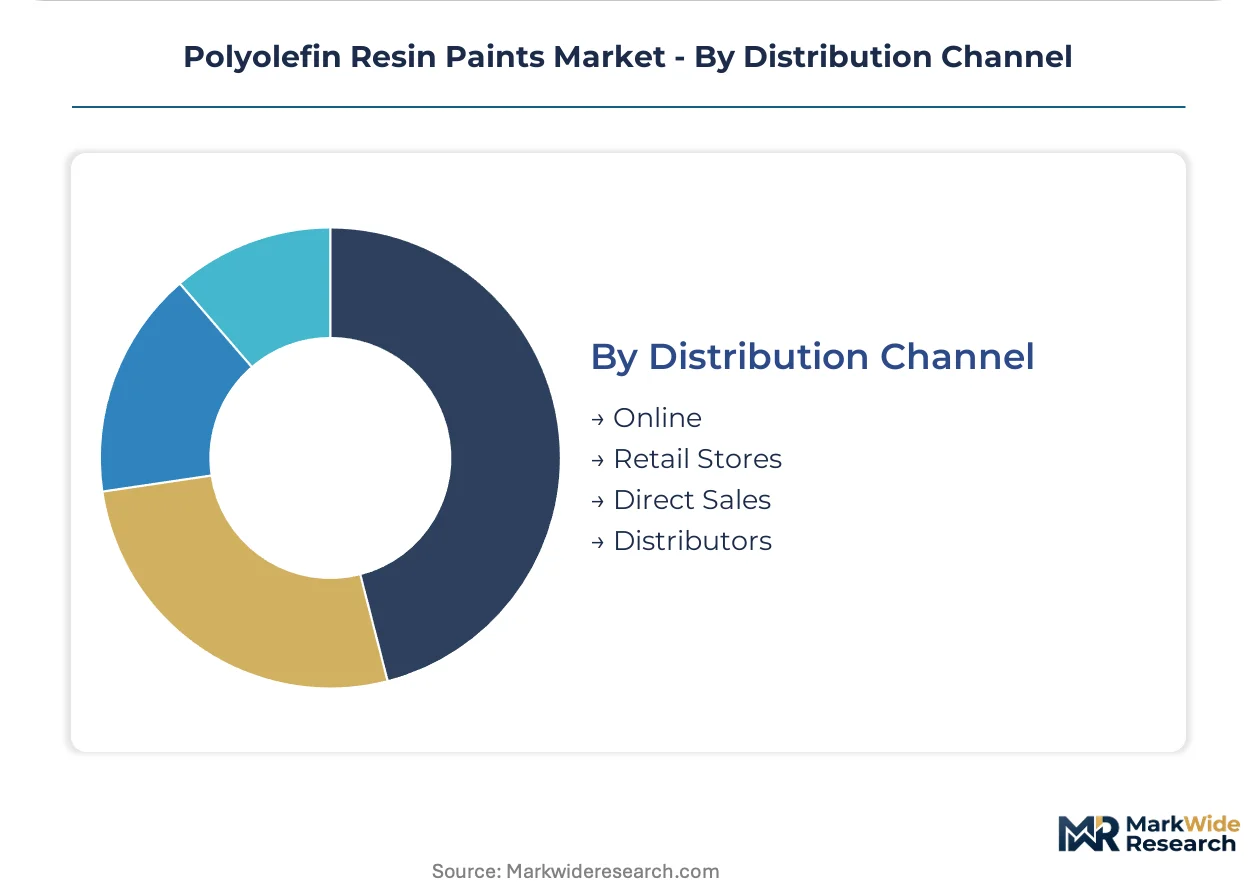
Distribution Channel:
Channel control is fragmenting as digital platforms disintermediate traditional distributor relationships over certified coating systems.
- Direct Sales:Technical dialogue between vehicle brand engineering teams and raw material developers concentrates in high-specification automotive and marine applications.
- Distributors:Traditional body shop supply relationships face erosion from B2B platform procurement of certified systems.
- Online:Digital channels fragmenting control over specification and certification documentation in mid-market segments.
- Retail Stores:Point-of-purchase availability for decorative and light industrial applications with immediate fulfillment requirements.
Direct sales capture the specification value while online channels expand most quickly in mid-tier procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes polyolefin resin paints predominantly for automotive OEM plastic components, while the United States directs larger volumes toward industrial equipment and marine maintenance applications. European demand concentrates on compliant water-borne systems for exterior automotive finishes. This consumption-mix differential shapes regional formulation priorities and regulatory compliance investments.
China
Domestic automotive production scaling and infrastructure investment sustain industrial coating consumption across Yangtze River Delta manufacturing clusters. MEE enforcement of GB standards on VOC content redirects capital toward electrostatic powder lines with reclaim systems in Shanghai and Jiangsu province facilities. Metallocene-catalyzed resin grades with enhanced TPO adhesion are eliminating plasma pretreatment steps in bumper painting operations concentrated in Suzhou and Ningbo.
United States
Agricultural equipment and material handling sectors in Midwest manufacturing clusters drive solvent-to-water-borne conversion timelines. EPA NESHAP rolling compliance deadlines through 2027 constrain permissible HAP content thresholds for miscellaneous metal and plastic parts coatings. Ohio and Michigan industrial coating operations face staged compliance deadlines favoring early powder and water-borne technology adopters with capital-intensive reclaim infrastructure.
Germany
Tier 1 automotive bumper suppliers adopt self-crosslinking water-borne polyolefin dispersions to eliminate energy-intensive oven stages in refinish applications. ECHA restrictions on solvent-based industrial coatings redirect European automotive plastic component demand toward compliant water-borne systems. Cologne and Stuttgart engineering centers concentrate specification authority for electric vehicle lightweight plastic body panel programs.
Japan
Precision electronics housing and medical device manufacturers pursue UV-curable polyolefin convergence for thermally sensitive substrate applications. METI industrial standards guide low-temperature cure formulation development for specialty coating segments. Kansai region chemical complexes anchor resin production capacity serving domestic automotive and electronics OEM specifications.
India
Production-linked incentives for electric vehicle manufacturing create first-mover openings in battery enclosure coating specifications under the PLI scheme. Domestic automotive production scaling in Tamil Nadu and Maharashtra sustains coating demand as OEMs localize supply chains. Chennai and Pune manufacturing clusters concentrate powder coating line conversions driven by cost-competitive electrostatic application infrastructure.
Polyolefin Resin Paints Market Competitive Environment
Capability concentration sits with specialty resin formulators possessing substrate-specific adhesion science; scale advantage sits with integrated petrochemical producers controlling cracker-to-derivative value chains. The market structures around three tiers: captive resin suppliers with backward integration into polyethylene production, independent coating specialists with formulation IP, and regional distributors with body shop channel control. Dominant competitive moves include direct specification relationships with automotive OEM engineering teams and asset reconfiguration toward water-borne and powder production capacity.
Among integrated petrochemical producers, Dow and SABIC exemplify the captive resin supplier archetype through upstream control over coating-grade polyolefin feedstock economics. AkzoNobel occupies a position within the independent coating specialist tier, differentiated via water-based portfolio alignment with tightening environmental standards. These three companies represent distinct strategic positions: feedstock security through in-house resin production, regulatory compliance through formulation specialization, and channel access through technical service depth.
| Leading Market Players |
|---|
| Dow |
| SABIC |
| ExxonMobil Corporation |
| LyondellBasell Industries |
| Mitsui Chemicals |
| Borealis AG |
| AkzoNobel |
| Sumitomo Chemical |
| INEOS Group Holdings |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Yangtze River Delta powder coating lines compresses supplier pricing power while simultaneously accelerating water-borne formulation adoption across automotive OEM procurement. This utilization dynamic forces resin suppliers to absorb feedstock volatility through contract structures rather than spot market adjustments.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and integrated polyolefin resin suppliers, insulating buyers from propylene feedstock swings while locking in volume commitments. Three-tier pricing structure across premium marine certification, standard industrial grade, and economy decorative tiers reflects salt-spray testing investment and qualified supplier pool scarcity. Cost compression in water-borne dispersions intensifies as EPA NESHAP compliance deadlines force specification turnover and capacity expansion. DIY enthusiasts and small contractors exhibit highest price sensitivity, whereas marine platform operators accept substantial premiums for documented performance histories.
Supply Chain Analysis
Export-control regimes on metallocene catalyst technologies limit resin grade flows from US Gulf Coast complexes to certain Asian manufacturing clusters, fragmenting supply security calculations. Production concentrates in China, the United States, and Germany, with coating-grade polyolefin feedstock drawing from naphtha-cracking operations and captive polyethylene resin streams. Supply chain risk centers on single-source vulnerability for marine salt-spray certified formulations, where limited qualified supplier pools create qualification bottlenecks. Distribution runs through direct technical sales for automotive OEM specification relationships, while B2B digital platforms fragment traditional body shop distributor control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement authority as automotive OEMs unbundle coating specifications from tiered supplier contracts, creating direct interoperability between vehicle engineering teams and resin formulators.
For Market Incumbents: Insulate specification relationships by embedding technical service teams within OEM engineering centers and accelerating self-crosslinking water-borne dispersion R&D to outpace polyurethane hybrid substitution threats. Deepen backward integration into cracker operations to secure feedstock cost advantages against propylene volatility. Prioritize REACH and EPA NESHAP pre-compliance certification investments to capture specification turnover windows. For New Entrants and Emerging Players: Pursue battery enclosure coating specifications under India's PLI scheme for electric vehicles, where first-mover qualification openings remain unclaimed by established marine and automotive specialists. Target UV-curable polyolefin convergence for medical device and electronics housing applications previously blocked by thermal sensitivity constraints. Establish direct-to-installer digital channels to bypass entrenched distributor relationships in mid-market body shop segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty resin formulators with captive marine certification and multi-year OEM qualification partnerships, suggesting superior cash-flow durability. Acquisition targets should emphasize substrate-specific adhesion IP and water-borne production asset configurations aligned with regulatory trajectories. Watch for inflection signals in electric vehicle plastic body panel adoption rates, which concentrate specification authority with raw material developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | Captive polyethylene resin supply secures feedstock cost advantages against propylene volatility swings. |
| Water-Borne Formulation Capacity Expansion | EPA NESHAP and REACH compliance deadlines redirect automotive OEM specification demand toward qualified suppliers. |
| Marine Salt-Spray Certification Investment | Limited qualified supplier pools enable premium pricing for offshore platform coating specifications. |
| Direct OEM Engineering Relationships | Unbundling from tiered supplier contracts concentrates technical dialogue with vehicle brand engineering teams. |
| UV-Curable Polyolefin R&D Convergence | Low-temperature cure opens medical device and electronics housing applications blocked by thermal sensitivity. |
Study Parameters
A standing panel of automotive OEM coating specification engineers, marine platform procurement managers, industrial plant maintenance directors, and specialty resin formulator R&D leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with downstream application operators and upstream petrochemical procurement specialists. Secondary validation drew from EPA NESHAP regulatory filings, ECHA REACH registration databases, SEC 10-K disclosures from integrated chemical producers, and Yangtze River Delta manufacturing cluster trade data. Bottom-up volume estimates triangulated against top-down value projections.
Scenario-bracketing around regulatory compliance deadlines and electric vehicle plastic body panel adoption rates bounded the forecast range across the projection horizon. Segmentation modeling incorporated formulation chemistry, application environment, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified installation base expansion and specification turnover velocity. Industry-specific inputs included metallocene catalyst technology diffusion rates and marine salt-spray certification pipeline backlogs.
Sensitivities concentrate around EPA NESHAP enforcement intensity, REACH substance restriction amendments, and propylene feedstock volatility transmission. Forecasts reflect assumptions regarding automotive OEM unbundling timelines and water-borne dispersion performance parity achievement. Material shifts in electric vehicle lightweighting adoption or marine platform maintenance cycle extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Water Color Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market