
 Nigeria Paint and Protective Coatings Market | 2026-2036
Nigeria Paint and Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Paint and Protective Coatings Market Insights
Nigeria's domestic manufacturing corridor is narrowing the gap between local supply and national consumption. Berger Paints Nigeria Plc anchors its position through extensive distribution networks across the Niger Delta and northern states. Chemical and Allied Products PLC leverages backward integration into resin production to control input costs. Meyer PLC specializes in industrial-grade alkyd and epoxy formulations for the oil and gas maintenance segment.
Paint and protective coatings comprise liquid or powder-applied films that cure to form adherent barriers against corrosion, weathering, and chemical attack, typically formulated with binders such as acrylic, alkyd, epoxy, or polyurethane polymers plus pigments and functional additives. Their primary purpose is to extend asset life across buildings, vehicles, and industrial equipment exposed to tropical humidity, ultraviolet radiation, and saline atmospheres. Architectural Paints dominates volume due to relentless housing and commercial stock expansion in Lagos, Abuja, and Port Harcourt. Industrial Coatings commands premium pricing from offshore platform operators and pipeline contractors requiring salt-spray resistance and thermal tolerance. Automotive Paints trails in share but offers margin expansion potential as local vehicle assembly incentives stimulate OEM finishing demand.
The Standards Organisation of Nigeria mandates NIS certification for all imported and domestically manufactured coatings, while the National Agency for Food and Drug Administration and Control regulates anti-fouling and biocidal formulations under pesticide-adjacent frameworks. These bodies enforce volatile organic compound thresholds and heavy metal restrictions that determine which formulations gain market access. Stakeholders must track regulatory alignment between Nigerian standards and evolving EU REACH export requirements that influence raw material sourcing decisions.
Market Dynamics
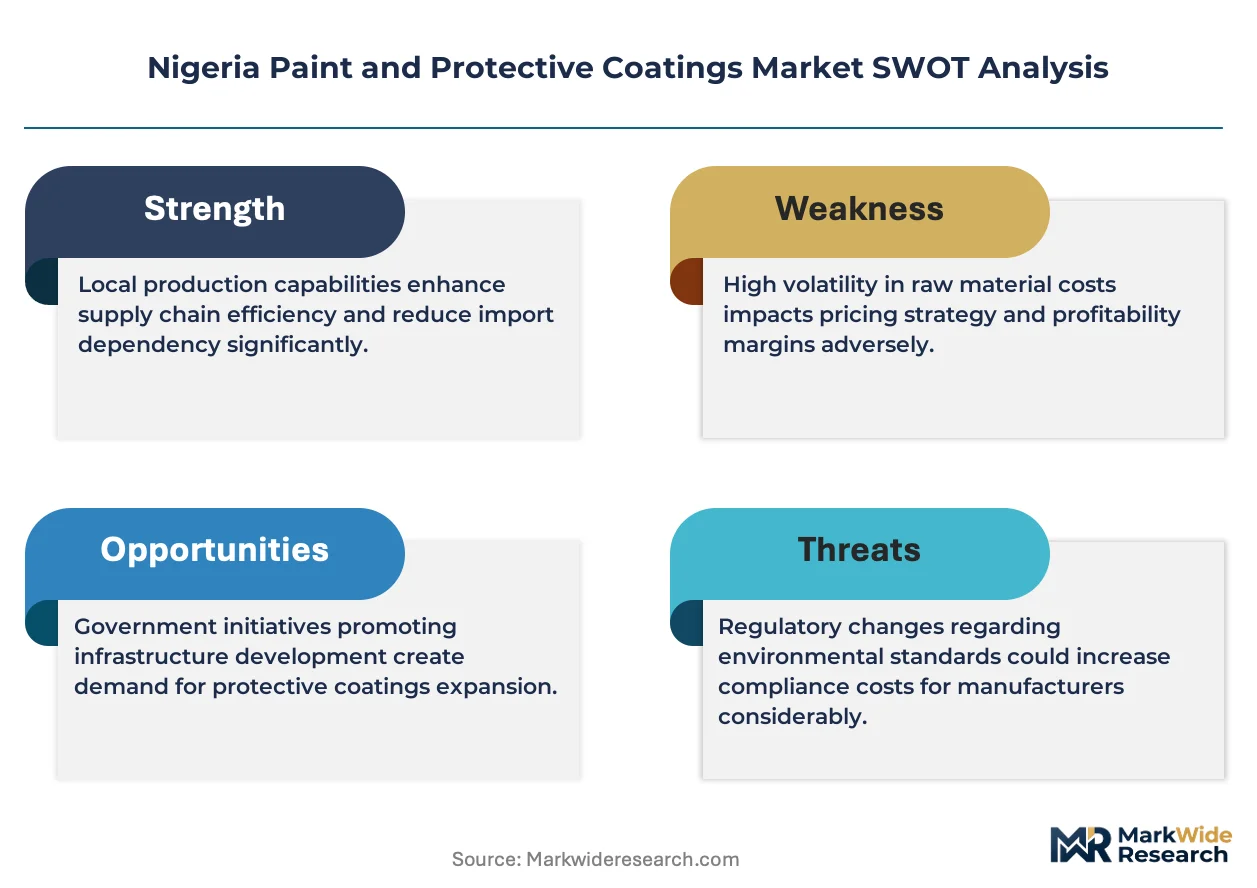
Formulation compliance with SON NIS certification is compressing product development timelines while redirecting R&D expenditure toward heavy metal substitution and VOC reduction chemistry. This regulatory compression is reshaping competitive positioning between importers and domestic compounders.
Growth Catalysts
- Lagos-Abuja construction corridor:Residential and commercial building permits in these cities are expanding architectural paint consumption faster than national GDP. Cement-to-paint ratios in new builds are tightening as developers standardize finishing specifications.
- SON mandatory certification:The Standards Organisation of Nigeria's NIS mark enforcement is eliminating substandard imports and clearing shelf space for compliant domestic manufacturers. This creates volume redistribution toward certified formulators.
- Epoxy-alkyd hybrid chemistry:Advances in resin blending are extending maintenance intervals for offshore platforms in the Niger Delta, reducing total cost of ownership for oil and gas asset operators.
Market Restraints
- Titanium dioxide import dependency:Nigeria lacks domestic TiO2 production, exposing formulators to currency-driven input cost volatility and dollar liquidity constraints at Lagos ports.
- Resin supply concentration:Backward integration into alkyd and acrylic resin production remains limited to two domestic players, creating bottleneck risk for independent compounders in Kano and Onitsha.
- REACH alignment burden:Export-oriented manufacturers must dual-formulate to satisfy both SON thresholds and evolving EU REACH substance restrictions, raising compliance overhead without domestic market benefit.
Strategic Opportunities
- Port Harcourt industrial maintenance:Offshore platform decommissioning schedules are creating cyclical demand spikes for high-performance anti-corrosive systems that local supply chains currently underserve.
- NAFDAC biocidal registration pathway:Anti-fouling coatings for marine applications face streamlined approval under revised pesticide-adjacent frameworks, opening access to fishing fleet and harbor infrastructure contracts.
- Distributor financing innovation:Inventory credit facilities tied to SON certification status could unlock working capital for northern state distributors currently constrained by cash-and-raw-materials procurement cycles.
Industry Challenges
- Formulation chemist scarcity:Universities in Nigeria graduate fewer polymer science specialists than the coatings sector requires, forcing manufacturers to recruit from food and detergent industries and retrain for resin compatibility testing.
- NIS certification timeline compression:SON laboratory backlog extends product approval from submission to market entry, freezing working capital in pre-launch inventory and delaying revenue recognition for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Paint and Protective Coatings Market |
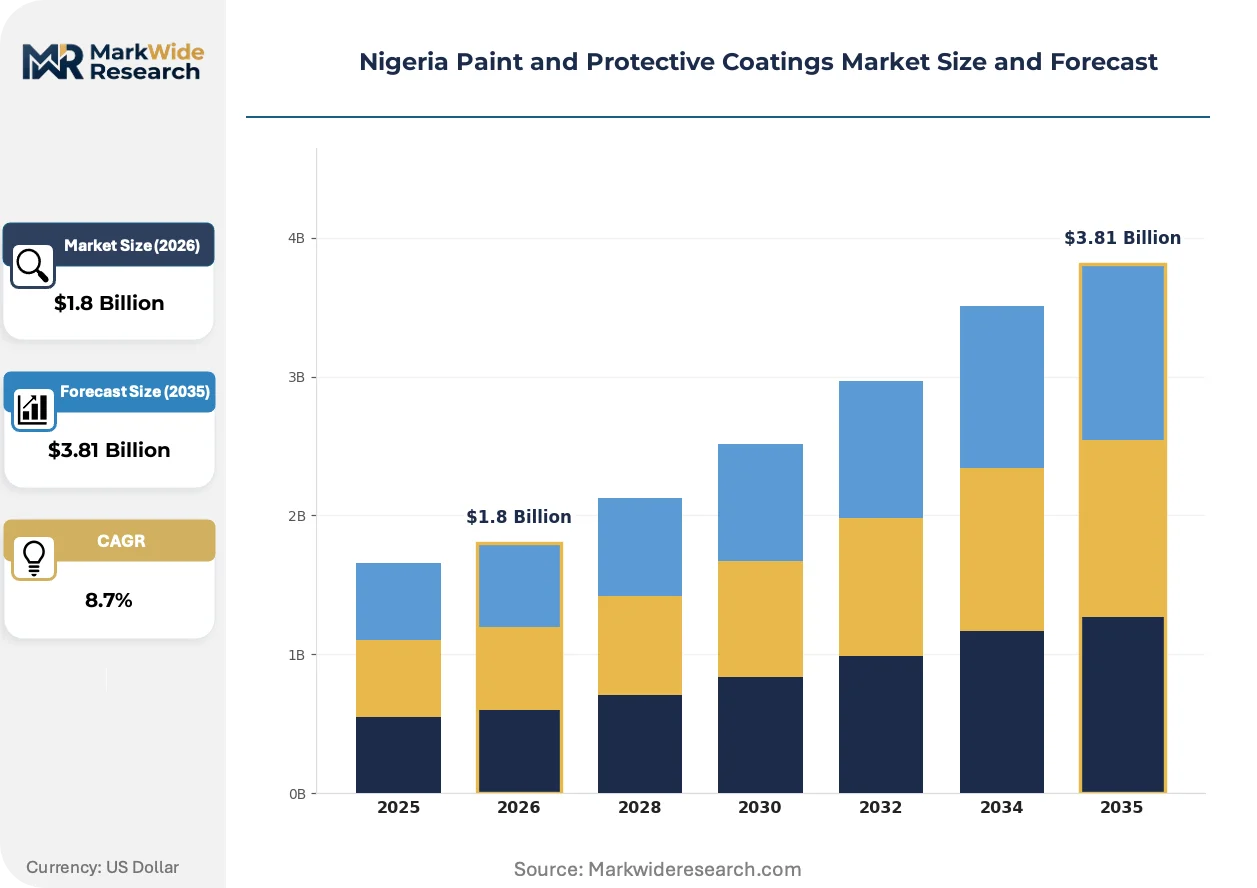
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Paints, Industrial Coatings, Automotive Paints, Special Purpose Coatings Application: Residential, Commercial, Infrastructure, Automotive End User: Construction, Automotive Manufacturers, Furniture, Industrial Formulation: Acrylic, Alkyd, Epoxy, Polyurethane |
| Companies Covered | Akzo Nobel N.V., Premier Paints Plc, Berger Paints Nigeria Plc, President Paints Nigeria, PCMN PLC, Chemical and Allied Products PLC, Meyer PLC, Jotun Powder Coatings, PPG Industries, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Paint and Protective Coatings Market Trends and Innovations
Digital color matching and predictive maintenance analytics are penetrating formulation and application workflows. These technologies are compressing specification cycles and enabling performance-based contracting in industrial segments.
Waterborne acrylic-urethane hybrid systems are virtualizing solvent-borne alkyd dominance in architectural maintenance coatings. Facility managers in Abuja commercial complexes are specifying these systems for interior refurbishment to satisfy SON VOC thresholds. This chemistry shift is virtualizing traditional solvent-based supply relationships and forcing distributor inventory reconfiguration toward low-VOC SKUs.
SON alignment with EU REACH substance restrictions is tightening heavy metal limits in pigment formulations. Domestic compounders are reformulating lead chromate and cadmium-based colorants ahead of scheduled prohibition dates. Industrial coatings for oil and gas applications face the steepest substitution costs due to thermal stability requirements.
Certification-driven procurement is consolidating buyer preference around SON NIS-marked products. Large construction contractors in Lagos are pre-qualifying suppliers based on certification status, displacing informal channel relationships. This behavior shift is most visible in government housing projects where contract terms mandate traceable compliance documentation.
Nigeria Paint and Protective Coatings Market Segmentation
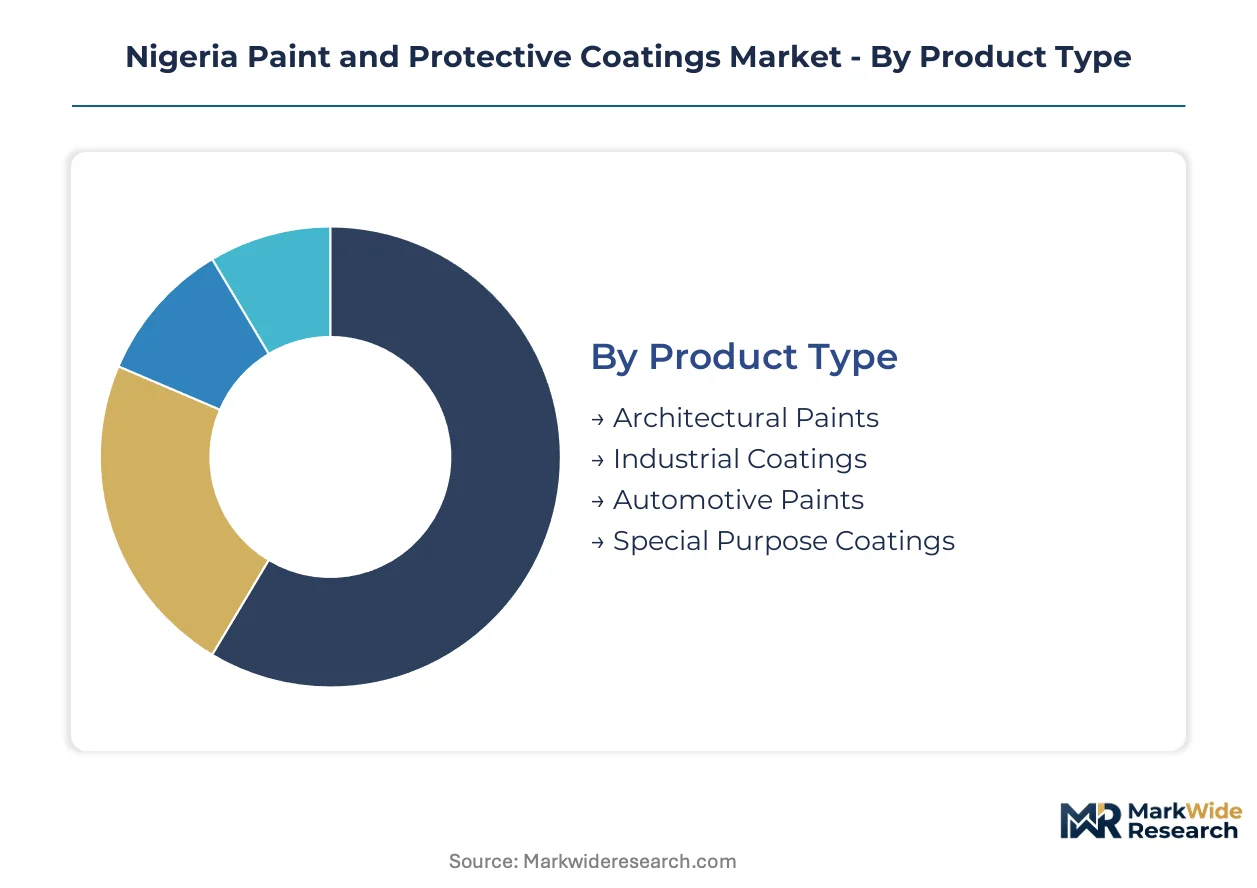
Segmentation in Nigeria's paint and protective coatings market reveals how formulation chemistry, end-use requirements, and certification standards intersect to create distinct competitive arenas. Understanding these divisions exposes where domestic manufacturers hold cost advantages versus where import dependency persists.
Product Type:
Mature architectural formulations coexist with emerging high-performance industrial systems as construction activity diversifies across Lagos, Abuja, and Port Harcourt.
- Architectural Paints:Waterborne acrylic and alkyd emulsions formulated for interior and exterior building surfaces dominate household and commercial refurbishment cycles. Demand concentrates in Lagos residential developments where cement-to-paint ratios are tightening as developers standardize finishing specifications, though currency volatility in titanium dioxide imports compresses margin stability for formulators.
- Industrial Coatings:Epoxy and polyurethane systems engineered for corrosion resistance, thermal tolerance, and chemical protection serve oil and gas asset operators in the Niger Delta. Offshore platform maintenance schedules in Port Harcourt are generating cyclical demand spikes for salt-spray-resistant formulations that local supply chains currently underserve.
- Automotive Paints:Basecoat-clearcoat systems and electrodeposition primers for vehicle finishing operations supply assembly plants and aftermarket refinishing channels.
- Special Purpose Coatings:Intumescent fire-retardant, anti-fouling marine, and hygienic coating systems address niche regulatory or environmental protection requirements.
Architectural Paints retains volume leadership; Industrial Coatings holds the steepest expansion curve.
Application:
Application patterns track Nigeria's urbanization gradient, with cost tier differentiation separating premium commercial specifications from mass residential consumption.
- Residential:Interior and exterior wall coatings, wood finishes, and decorative enamels applied in single-family homes and multi-unit housing across Lagos and Abuja.
- Commercial:High-durability coatings for office complexes, retail centers, and hospitality facilities where facility managers in Abuja commercial complexes are specifying waterborne acrylic-urethane hybrids to satisfy SON VOC thresholds.
- Infrastructure:Protective systems for bridges, pipelines, power transmission structures, and water treatment facilities exposed to tropical humidity and saline atmospheres.
- Automotive:OEM finishing and collision repair coatings applied in assembly plants and body shops.
Residential commands absolute volume; Commercial delivers the strongest margin expansion.
End User:
End user concentration reflects Nigeria's economic structure, with construction sector procurement patterns determining formulation priorities for domestic compounders.
- Construction:Developers, contractors, and facility managers purchasing architectural and protective coatings for building envelopes, structural steel, and interior finishes. Large construction contractors in Lagos are pre-qualifying suppliers based on SON NIS certification status, displacing informal channel relationships in government housing projects.
- Automotive Manufacturers:Vehicle assembly plants requiring OEM-grade basecoats, primers, and clearcoats for production line finishing.
- Furniture:Wood coating applications for residential and commercial furniture production, including nitrocellulose lacquers and polyurethane varnishes.
- Industrial:Oil and gas operators, manufacturing facilities, and marine service companies procuring high-performance protective systems.
Construction dominates procurement volume; Industrial generates the highest per-liter value realization.
Formulation:
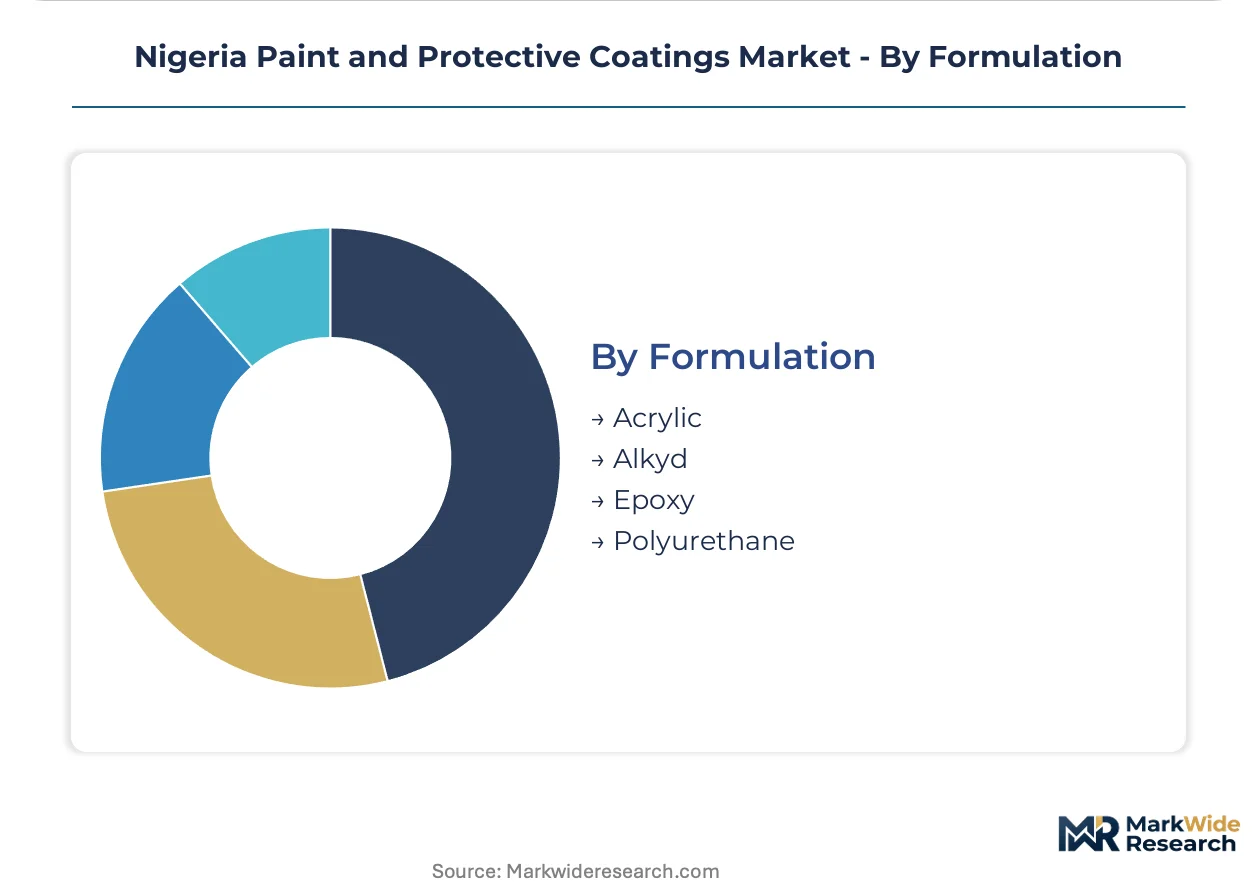
Formulation chemistry selection hinges on performance requirements and regulatory compliance trajectory, with waterborne systems displacing solvent-borne legacy products.
- Acrylic:Water-dispersible polymers providing exterior durability, color retention, and application ease for architectural coatings. Advances in acrylic-urethane hybrid chemistry are extending maintenance intervals while satisfying SON VOC thresholds.
- Alkyd:Oil-modified polyester resins offering gloss retention and substrate penetration for metal and wood applications. Backward integration into alkyd resin production remains limited to two domestic players, creating supply concentration risk for independent compounders.
- Epoxy:Two-component thermosetting systems delivering chemical resistance and adhesion for industrial and marine protective applications.
- Polyurethane:Aliphatic and aromatic isocyanate-based coatings providing abrasion resistance and UV stability for high-performance finishes.
Acrylic leads architectural volume; Epoxy captures the industrial premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Standards Organisation of Nigeria anchors regulatory enforcement across the national market, with SON NIS certification requirements extending from Lagos ports to northern distributor networks. Regional consumption patterns track infrastructure investment corridors, creating distinct competitive arenas across Nigeria's economic zones.
Lagos State
Residential tower construction in Lekki and Ikoyi corridors is accelerating architectural paint consumption beyond national averages. Lagos State Building Control Agency mandates surface finishing standards that pre-qualify SON-certified suppliers for government housing tenders. Cement-to-paint ratios are tightening across Eko Atlantic and Ibeju-Lekki developments as developers standardize multi-coat specifications.
Federal Capital Territory
Commercial complex refurbishment in Abuja's Central Business District is driving waterborne acrylic-urethane hybrid adoption for interior VOC compliance. Federal Ministry of Works specifications for public building maintenance require traceable NIS certification documentation. Facility managers in Maitama and Wuse districts are pre-qualifying coating suppliers based on SON laboratory test reports.
Rivers State
Offshore platform maintenance schedules in Port Harcourt generate cyclical demand spikes for salt-spray-resistant epoxy systems. Department of Petroleum Resources enforcement of asset integrity standards mandates protective coating inspection protocols for Niger Delta operators. Onne and Warri industrial clusters face undersupply of high-performance anti-corrosive formulations qualified for marine atmospheric exposure.
Kano State
Northern distributor networks serving residential construction in Kano metropolitan area face working capital constraints from cash-and-raw-materials procurement cycles. Kano State Urban Planning and Development Authority building permit data shows accelerating housing stock expansion requiring architectural emulsion supply. Dala and Nassarawa GRA development zones concentrate demand for economy-tier interior coatings.
Onitsha-Anambra Corridor
Independent compounders in Onitsha industrial zone encounter resin supply bottlenecks from limited domestic alkyd and acrylic production capacity. Anambra State Ministry of Environment enforcement of SON VOC thresholds is accelerating reformulation toward waterborne systems. Nnewi manufacturing cluster spillover is creating secondary demand for industrial maintenance coatings among automotive parts fabricators.
Nigeria Paint and Protective Coatings Market Competitive Landscape
Capability concentration sits with integrated resin producers; scale advantage sits with distribution-heavy architectural specialists. The Nigerian market structures around three tiers: multinational formulators with global R&D access, domestic integrated manufacturers controlling backward resin supply, and regional compounders dependent on imported intermediates. Strategic archetypes include certification-anchored incumbents defending NIS-marked shelf space, hybrid-chemistry innovators extending maintenance intervals for oil and gas clients, and distributor-financed challengers unlocking northern state working capital. Dominant competitive moves involve backward integration into alkyd resin production and SON certification-driven procurement pre-qualification.
Among domestic integrated manufacturers, Berger Paints Nigeria Plc, Chemical and Allied Products PLC, and Meyer PLC occupy positions reflecting distinct strategic archetypes. Berger exemplifies the distribution-anchored incumbent with extensive Niger Delta and northern state networks. Chemical and Allied Products represents the backward-integrated resin controller leveraging in-house alkyd production for input cost management. Meyer sits within the industrial-specialist tier, with positioning tied to oil and gas maintenance segment requirements. These three domestic anchors illustrate how Nigerian formulators are responding to SON regulatory compression and titanium dioxide import dependency through divergent capability investments.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Premier Paints Plc |
| Berger Paints Nigeria Plc |
| President Paints Nigeria |
| PCMN PLC |
| Chemical and Allied Products PLC |
| Meyer PLC |
| Jotun Powder Coatings |
| PPG Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic alkyd resin production is compressing margins for independent compounders while amplifying pricing power for the two integrated manufacturers controlling captive supply. This utilization asymmetry is forcing procurement decisions toward higher-cost import alternatives and reshaping competitive economics across formulation tiers.
Pricing Analysis
Lagos-Abuja price spreads for architectural emulsions exceed interior region differentials by a factor reflecting diesel logistics and port clearance friction. Three-tier pricing structure across premium, standard, and economy levels separates SON-certified imports from domestic NIS-marked formulations and informal channel products. Pricing pressure stems from titanium dioxide dollar-denominated import costs and naira liquidity constraints at Lagos ports. Residential developers in Kano metropolitan area exhibit highest price sensitivity, while oil and gas maintenance contractors in Port Harcourt prioritize performance specifications over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Chemical and Allied Products PLC and Berger Paints Nigeria Plc, which control the majority of domestic alkyd and acrylic resin capacity. Raw material dependencies draw from China for titanium dioxide pigments, India for solvent intermediates, and Europe for specialty epoxy hardeners. Single-source vulnerability concentrates around TiO2 supply, where currency-driven input cost volatility exposes formulators to margin erosion. Distribution runs through distributor networks anchored in Lagos, with northern state channels constrained by cash-and-raw-materials procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's paint and protective coatings market is entering a cyclical recovery phase driven by offshore platform decommissioning schedules in the Niger Delta. This maintenance cycle is creating demand spikes that outpace current local supply capacity.
For Market Incumbents: Entrench certification-anchored positioning by accelerating SON NIS laboratory pre-submission for reformulated low-VOC lines ahead of scheduled prohibition dates. Deepen backward integration into acrylic resin production to reduce dependency on the two domestic suppliers currently controlling captive supply. Defend shelf space against import challengers by extending inventory credit facilities to northern distributors currently frozen by working capital constraints.
For New Entrants and Emerging Players: Pursue white-space opportunity in Port Harcourt industrial maintenance, where offshore platform operators face undersupply of salt-spray-resistant epoxy systems qualified for marine atmospheric exposure. Target Kano distributor financing innovation as entry vector, unlocking procurement relationships currently constrained by cash-and-raw-materials cycles. Lead with waterborne acrylic-urethane hybrid formulations that satisfy Abuja facility manager VOC specifications while avoiding titanium dioxide import dependency of legacy architectural lines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across industrial coatings sub-segments as epoxy-alkyd hybrid chemistry R&D and SON certification compliance absorb working capital. Long-term viability favors integrated manufacturers controlling resin production and certification infrastructure rather than import-dependent compounders. Monitor cyclical demand inflection through Department of Petroleum Resources asset integrity inspection schedules and offshore platform maintenance tender announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Chemical and Allied Products PLC's captive alkyd supply insulates margins from import cost volatility. |
| SON NIS Certification Acceleration | Laboratory pre-submission compresses approval timelines and freezes working capital in compliant inventory. |
| Distributor Financing Program Launch | Inventory credit facilities unlock northern state procurement relationships constrained by cash cycles. |
| Waterborne Formulation Transition | Acrylic-urethane hybrid chemistry satisfies Abuja VOC thresholds while displacing solvent-borne legacy supply. |
| Industrial Maintenance Contracting | Performance-based agreements for Port Harcourt offshore platforms extend maintenance intervals and capture premium pricing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at Lagos and Port Harcourt manufacturing facilities, procurement leads at downstream construction contractors, distribution channel partners serving Kano and Onitsha networks, and technical R&D directors overseeing formulation reformulation. Secondary validation drew from Standards Organisation of Nigeria certification registries, National Agency for Food and Drug Administration and Control biocidal approval databases, customs and trade data tracking titanium dioxide import volumes, and SEC filings of listed Nigerian paint manufacturers. Bottom-up demand modeling triangulated against top-down macroeconomic construction indicators.
Calibration against historical volume and value trajectories informed projection mechanics across the modeling period. Segmentation dimensions included product type tier, application end-use, formulation chemistry, and regional consumption cluster. CAGRs were derived from regression analysis of construction permit data, cement-to-paint ratio trends, and oil and gas capital expenditure cycles. Industry-specific forecast inputs incorporated SON regulatory timeline assumptions and offshore platform maintenance schedule periodicity.
Sensitivities concentrate around naira-dollar exchange rate volatility, SON laboratory backlog duration, and Department of Petroleum Resources enforcement intensity for asset integrity standards. Quarterly review of Lagos port clearance times, Kano building permit issuance rates, and Port Harcourt offshore tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Industrial Paint Booth Market