
 Packaging Resins Market | 2026-2036
Packaging Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Resins Market Intelligence
The development of food-contact-approved recycled polyethylene terephthalate (rPET) is reorganizing the value chain for beverage and food container applications. Dow Inc. leverages its material science expertise to produce advanced resins that incorporate higher percentages of post-consumer recycled content. SABIC competes through its certified circular polymer portfolio, which is derived from advanced chemical recycling processes. These innovations directly address brand owner sustainability commitments and tightening regulatory pressures.
Packaging resins are thermoplastic polymers specifically formulated for conversion into a wide array of containers, films, and closures. These materials, including high-density polyethylene and polypropylene, are characterized by properties like barrier performance, sealability, and processability through methods like injection and blow molding. Polyethylene terephthalate (PET) and polypropylene (PP) represent the major volume segments, driven by their extensive use in beverage bottles and rigid containers, respectively. The food & beverage application remains the largest end-market, commanding the most stringent performance and safety requirements for materials.
The market operates under strict regulatory oversight for material safety and environmental impact. Compliance with food contact rules from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) is non-negotiable. Frameworks like the EU's REACH regulation and China's GB standards also govern chemical composition and recycling targets. Producers must navigate the trade-off between achieving higher recycled content, maintaining packaging integrity, and managing production costs.
Market Dynamics
The primary structural force is the collision between circular economy mandates and the unyielding performance requirements of food-contact packaging. This tension compels innovation in material science to incorporate recycled content without compromising safety, barrier properties, or processing efficiency.
Growth Catalysts
- Regulatory Mandates:The European Union's targets for recycled content in plastic packaging compel resin producers to innovate formulations, particularly for PET and PE used in beverage and food containers.
- Food & Beverage Expansion:Sustained demand for both flexible and rigid packaging in the food & beverage sector, especially in Southeast Asian economies, provides a consistent volume base for resin consumption.
- Chemical Recycling Scale-up:Investment in advanced recycling technologies offers a pathway to produce high-quality polymers from post-consumer waste, creating a new source of premium feedstock for demanding applications.
Market Restraints
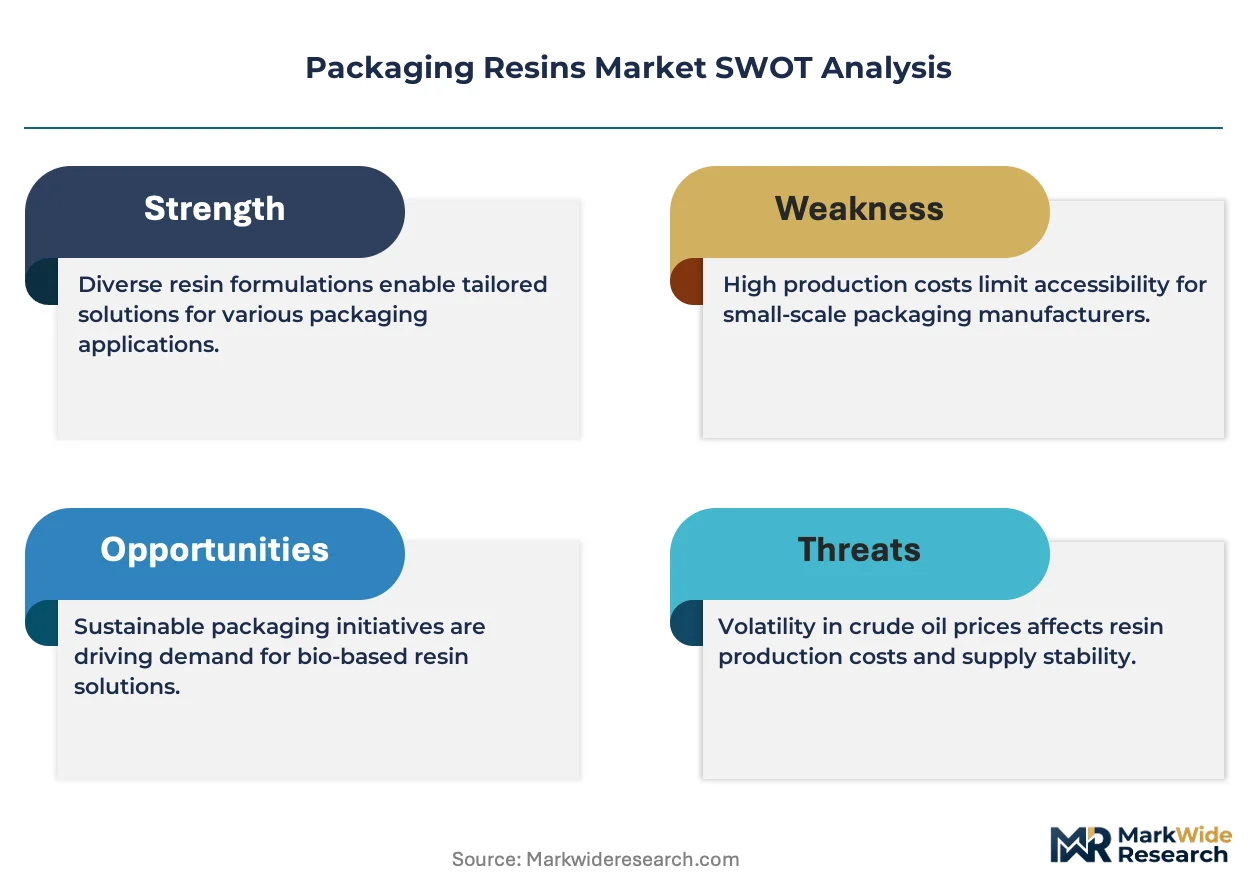
- Feedstock Volatility:Resin production costs remain directly linked to volatile petrochemical feedstock prices, creating margin pressure and pricing unpredictability for converters and brand owners.
- Performance Degradation:Incorporating higher percentages of mechanically recycled content can degrade key properties like clarity, strength, and barrier performance, limiting its use in sensitive applications.
- Global Regulatory Divergence:Navigating conflicting or differing food contact regulations between jurisdictions like the US (FDA), Europe (EFSA), and China (GB standards) increases compliance costs and time-to-market.
Strategic Opportunities
- High-Barrier Mono-Materials:Developing single-polymer packaging solutions with enhanced barrier properties presents a major opportunity, as these are designed for easier recycling compared to multi-layer structures.
- Bioplastics Integration:The development of bio-based or biodegradable resins for specific short-life applications, such as food service ware, offers a route to diversify beyond traditional fossil-fuel-based polymers.
- Digital Product Passports:Implementing traceability systems to track polymer batches and recycled content can unlock premium value and demonstrate compliance with regulations like the EU's CSRD.
Industry Challenges
- Recycling Infrastructure Gaps:The lack of harmonized collection, sorting, and processing infrastructure for post-consumer plastic waste creates a bottleneck for supplying high-quality recycled feedstock at scale.
- Capital-Intensive Technology:Building new chemical recycling plants or upgrading extrusion lines to handle recycled materials requires significant capital investment, posing a barrier for smaller producers.
- Certification Timelines:Achieving food-contact approval from bodies like EFSA or the FDA for new recycled polymer formulations is a lengthy and expensive process that can delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Resins Market |
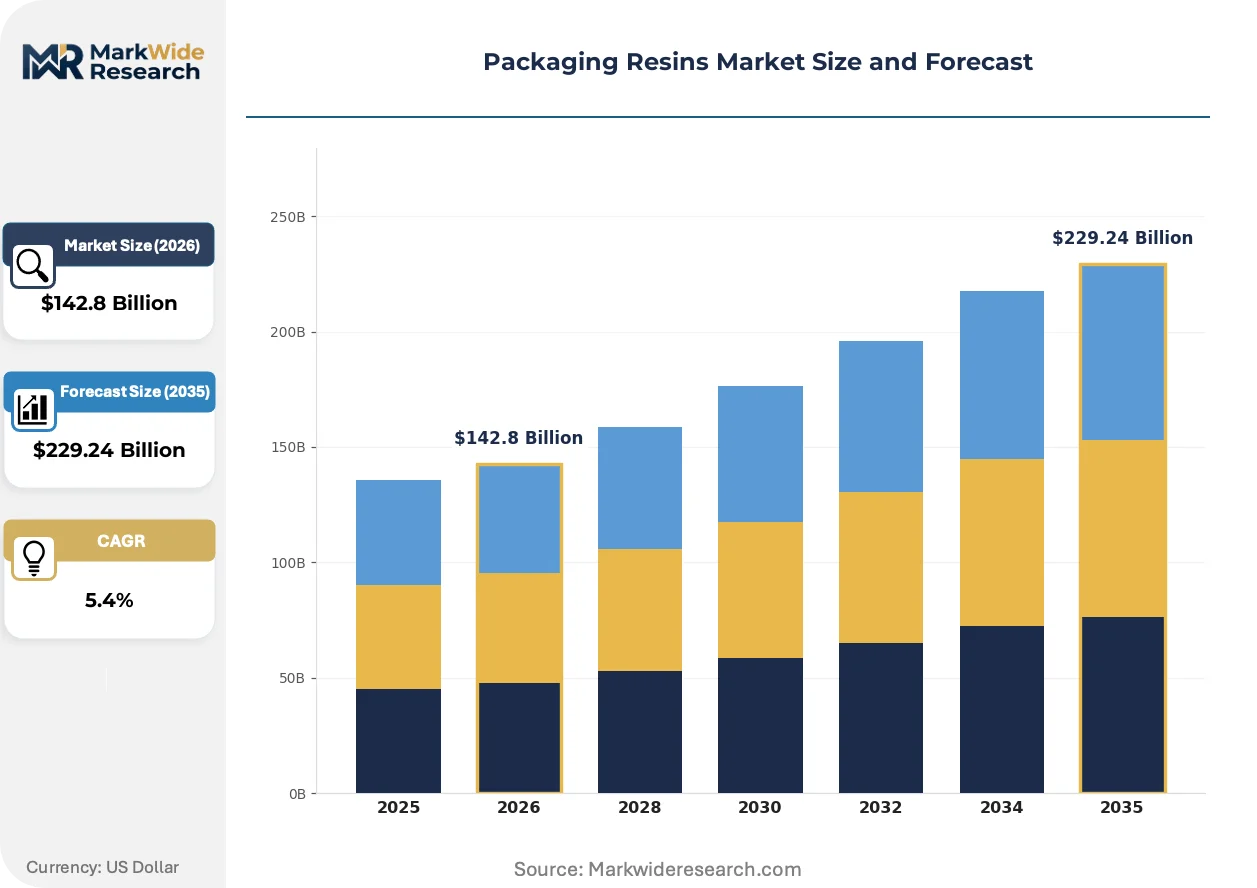
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $229.24 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Form: Granules, Pellets, Powders, Sheets, Films Application: Food & Beverage, Personal Care, Household Goods, Pharmaceuticals, Industrial Packaging End User: Consumer Goods Manufacturers, Pharmaceutical Companies, Cosmetic Producers, Chemical Plants, Electronics Brands |
| Companies Covered | ExxonMobil Corporation, China Petrochemical Corporation, LyondellBasell Industries Holdings B.V., SABIC, Dow Inc., BASF SE, Reliance Industries Limited, Borealis AG, Braskem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Resins Market Strategic Shifts & Innovations
Innovation in the packaging resins sector is now intrinsically linked to circular economy principles. Material science advancements are no longer solely focused on performance enhancement but on creating polymers compatible with recycling and reuse systems under mounting regulatory pressure.
Advanced chemical recycling provides a method to break down mixed plastic waste into its molecular building blocks. Food and beverage brand owners are adopting polymers derived from this process to meet ambitious recycled content pledges. This development is bifurcating the market, creating a premium tier of certified circular polymers distinct from conventional fossil-based resins and lower-grade mechanical recyclates.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes legally binding targets for recycled content in plastic packaging. This policy forces the entire value chain, from resin producers to converters, to re-engineer products and supply chains. The beverage sector is most directly impacted, accelerating development of food-contact approved rPET to ensure compliance for bottles.
A behavioral shift among CPG companies is altering purchasing criteria away from a singular focus on cost. Procurement decisions increasingly weigh factors like certified recycled content, carbon footprint data, and supplier transparency. This is most visible in North America and Europe, where brand reputation is closely tied to demonstrable sustainability efforts.
Packaging Resins Market Segmentation
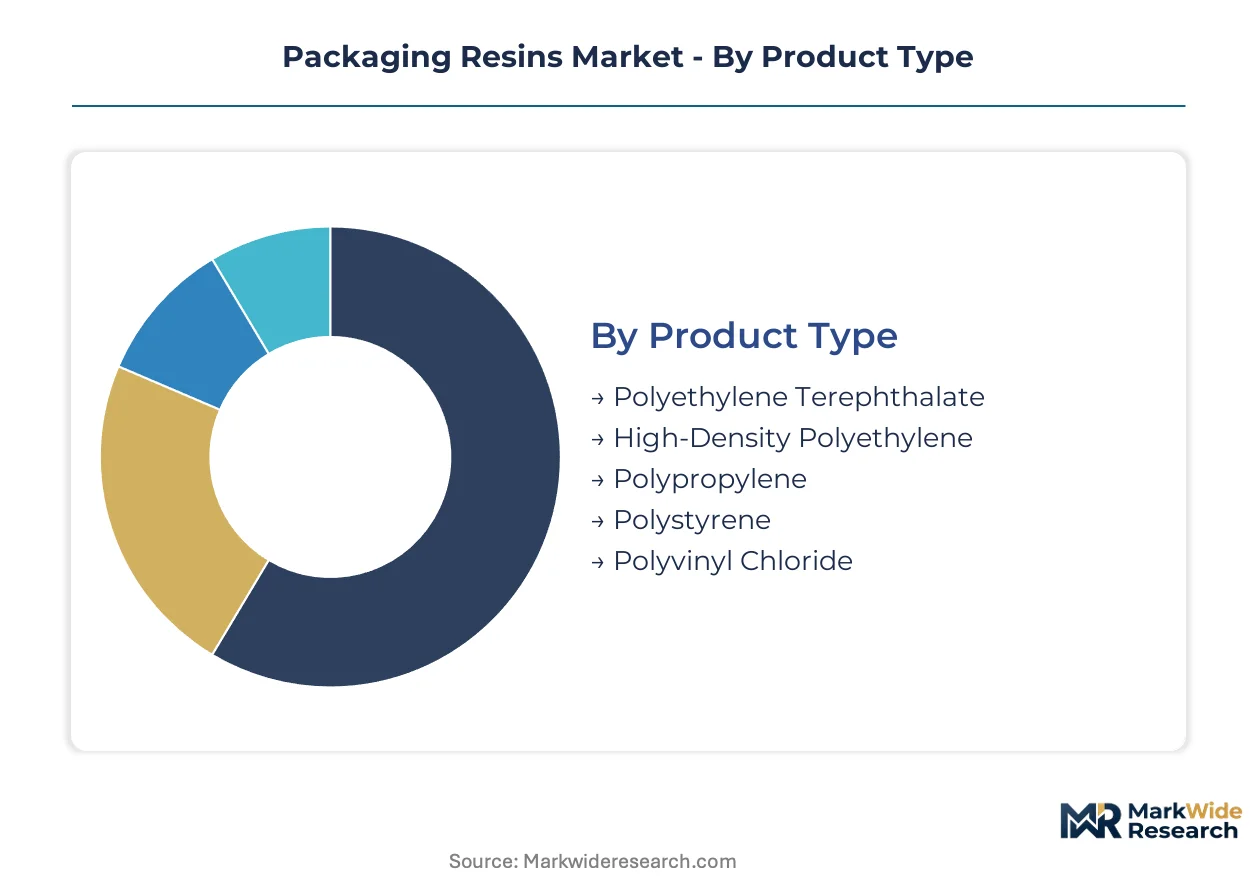
The packaging resins market is broadly segmented by material properties, forms, applications, and end-user requirements. Understanding these segments clarifies specific performance needs and regulatory landscapes shaping product development.
Product Type:
Margin pools in product types concentrate around specialized formulations and those meeting stringent food contact and recycled content demands.
- Polyethylene Terephthalate (PET):This clear, strong thermoplastic is widely used for beverage bottles and food containers. Demand is driven by global mandates for food-contact-approved recycled content, especially in Europe.
- Polypropylene (PP):A robust, versatile thermoplastic with high strength-to-weight ratio, PP is extensively employed in rigid packaging like tubs and caps. Its food and beverage applications sustain consistent volume.
- High-Density Polyethylene (HDPE):Opaque, rigid, and impact-resistant, HDPE is common for milk jugs and detergent bottles.
- Polystyrene (PS):This transparent, rigid thermoplastic finds use in disposable food service items and protective packaging.
- Polyvinyl Chloride (PVC):Known for clarity and barrier properties, PVC is used in blister packaging, though its use faces environmental scrutiny.
Polyethylene Terephthalate holds the dominant share, while Polypropylene is closing the gap fastest in diverse rigid packaging.
Form:
The form of packaging resins directly impacts processing methods and suitability for various applications, optimizing manufacturing efficiency.
- Granules:These uniform particles are the primary feedstock for injection molding and extrusion, critical for rigid containers and caps due to consistent flow.
- Films:Thin, flexible resin sheets are crucial for flexible packaging, offering barrier properties and sealability for pouches and bags. Demand is high in food preservation.
- Pellets:Larger than granules, pellets are commonly used in extrusion and blow molding for bottles.
- Powders:Fine resin particles, powders are utilized in specialized applications like rotational molding.
- Sheets:Thicker, pre-formed resin sheets are thermoformed into trays and blisters for rigid packaging.
Granules dominate initial processing stages, with Films seeing rapid expansion in flexible packaging solutions.
Application:
Volume in applications is heavily influenced by consumer goods consumption and demand for convenience and extended shelf-life.
- Food & Beverage:This largest segment demands resins with excellent barrier properties and safety certifications for rigid and flexible containers. FDA and EFSA oversight is strict.
- Pharmaceuticals:Packaging for pharmaceuticals requires resins with high purity, chemical inertness, and precise barrier performance. Compliance with stringent regulatory standards is paramount.
- Personal Care:Resins are used in bottles and jars for cosmetics, prioritizing aesthetic appeal and chemical resistance.
- Household Goods:This category includes packaging for cleaning products, requiring durability and chemical compatibility.
- Industrial Packaging:Resins provide robust solutions for bulk containers and protective films in shipping and logistics.
The Food & Beverage application drives the largest volume, while Pharmaceuticals demand specialized high-performance resins.
End User:
End-user procurement patterns are shaped by brand reputation, sustainability commitments, and consistent material supply for large manufacturing.
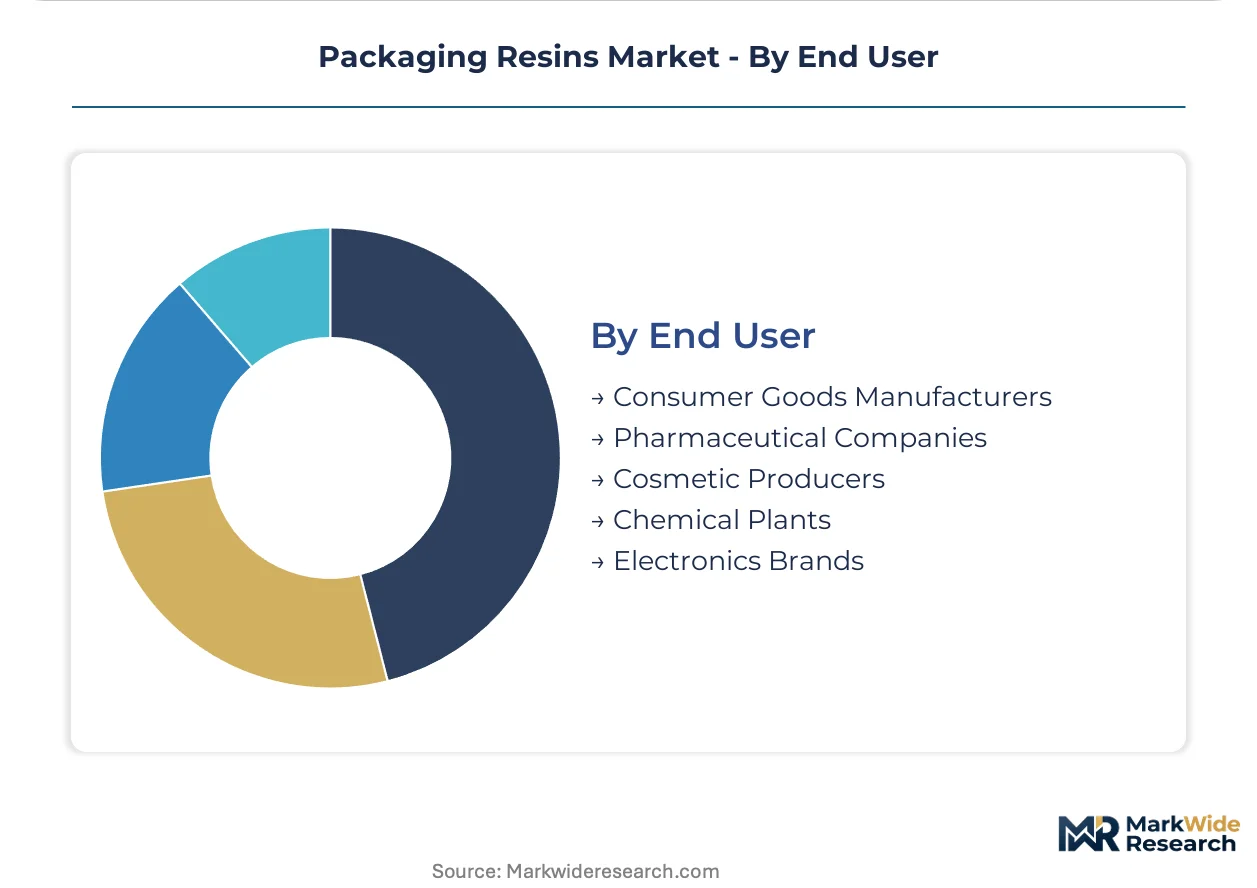
- Consumer Goods Manufacturers:These companies procure resins for diverse products, from food to personal care. Procurement decisions increasingly weigh certified recycled content and carbon footprint data.
- Pharmaceutical Companies:Procurement focuses on resins meeting rigorous safety, barrier, and regulatory compliance for drug packaging. Material traceability is critical.
- Cosmetic Producers:These end-users prioritize resins offering aesthetic appeal and chemical resistance for their product lines.
- Chemical Plants:Resins are procured for industrial containers, emphasizing chemical resistance and durability for various substances.
- Electronics Brands:Packaging for electronics requires resins providing impact and static protection, used in trays and films.
Consumer Goods Manufacturers represent the largest end-user segment, while Pharmaceutical Companies require resins meeting rigorous safety and regulatory standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Thailand export packaging resins to global markets, supporting diverse consumer goods industries. This export-driven manufacturing leverages cost advantages and growing regional demand. Regulatory incentives in these nations further stimulate resin production capacity.
China
China's vast consumer market and booming e-commerce drive significant demand for packaging resins. The country's GB standards for food contact materials dictate polymer formulations. Manufacturers in the Yangtze River Delta region focus on developing advanced sustainable packaging solutions.
United States
The United States' large food and beverage sector fuels consistent demand for rigid and flexible packaging resins. FDA regulations for food contact polymers ensure material safety and compliance. Gulf Coast chemical complexes actively expand production capacity for polyethylene and polypropylene.
Germany
Germany's robust industrial base and premium consumer goods segment require high-performance packaging resins. EU's REACH regulation and EFSA guidelines shape material development for circularity. The Rhine-Ruhr area chemical industry focuses on advanced polymer formulations with recycled content.
India
India's expanding middle class and organized retail sector contribute to a rising demand for packaged goods. BIS standards for plastic products influence resin specifications and quality. Gujarat's chemical industry attracts significant investment for new resin manufacturing units.
Vietnam
Vietnam's export-oriented manufacturing sector and growing domestic consumption create strong demand for packaging resins. Government policies support foreign direct investment in plastics manufacturing capabilities. The Southern Economic Region sees significant expansion in packaging film production.
Packaging Resins Market Key Industry Players
Listed leaders compete with private specialists across innovation in sustainable resins. The market exhibits consolidation at the top, driven by integrated petrochemical giants, while specialized polymer producers and advanced recycling technology providers contribute to fragmentation. Companies pursue capacity expansion and strategic partnerships for feedstock, alongside portfolio diversification into recycled content.
At the scale-driven end, ExxonMobil Corporation anchors the market with its extensive petrochemical production capabilities. Dow Inc. and SABIC represent key players leveraging material science expertise to produce advanced resins, including certified circular polymers derived from chemical recycling processes. These companies occupy a position at the forefront of addressing brand owner sustainability commitments and tightening regulatory pressures. Their efforts drive the development of high-performance materials with increased post-consumer recycled content.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| China Petrochemical Corporation |
| LyondellBasell Industries Holdings B.V. |
| SABIC |
| Dow Inc. |
| BASF SE |
| Reliance Industries Limited |
| Borealis AG |
| Braskem |
| Others |
Cost & Logistics Intelligence
Months of inventory held by converters directly influences short-term resin pricing power, reflecting the concentrated production capacity in Southeast Asia and the US Gulf Coast. This dynamic links material availability to immediate cost structures for packaging manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for packaging resins, establishing baseline prices. Price differentiation stems from certified recycled content and geographic delivery cost. Pricing pressure stems from volatile petrochemical feedstock prices, impacting margins for converters. Consumer Goods Manufacturers exhibit high price sensitivity, while Pharmaceutical Companies prioritize material purity and regulatory compliance over cost, demonstrating lower price sensitivity.
Supply Chain Analysis
Global shipping lane congestion underwrites the regionalization of packaging resin supply chains, emphasizing production hubs in China, the United States, and Saudi Arabia. Resin manufacturing heavily relies on crude oil and natural gas as primary petrochemical feedstocks. Commodity price volatility represents a significant structural risk across the entire value chain. Distribution runs through direct sales from major producers to large-scale converters, supplemented by regional distributors serving smaller packaging firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among major CPG companies is reshaping competitive positioning within the packaging resins market, shifting power dynamics towards larger, more demanding buyers. This necessitates strategic adjustments across the value chain.
For Market Incumbents: Secure long-term feedstock contracts to mitigate petrochemical price volatility, a persistent threat to margin stability. Incumbents should invest heavily in advanced chemical recycling technologies to meet tightening regulatory pressures, such as the EU's PPWR. Develop high-performance mono-material packaging solutions through focused R&D, enhancing material circularity. Capacity addition in Southeast Asian export hubs offers a strategic lever for market share defense.
For New Entrants and Emerging Players: Anchor in specialized bio-based resins for specific short-life applications, targeting the underpenetrated food service ware segment. New entrants can also focus on developing digital product passport solutions to enable traceability and compliance with emerging regulations like the EU's CSRD. A go-to-market angle emphasizing certified circularity and a lower carbon footprint will differentiate offerings. This strategy creates an entry point against established fossil-based polymer producers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified petrochemical conglomerates seeking to divest non-core or less sustainable assets, presenting acquisition opportunities for focused investors. The market offers long-term viability over the next 5-10 years, driven by circular economy mandates. Specialized material science firms with proprietary recycling technologies or unique bio-resin formulations represent attractive acquisition archetypes. The speed of regulatory approvals for new food-contact recycled content technologies is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Reinforces export-oriented production for global consumer goods. |
| Advanced Chemical Recycling Investment | Provides premium feedstock for demanding food and beverage applications. |
| Mono-Material R&D | Simplifies packaging structures, enhancing post-consumer recyclability. |
| Bioplastics Portfolio Diversification | Addresses demand for renewable alternatives in specific short-life applications. |
| Digital Traceability Platform | Enables compliance with EU CSRD and premium valuation for certified content. |
Research Approach
The analysis maps packaging resin types, application segments, and regional markets, each validated through primary interviews with industry executives. Conversations included resin producers, packaging converters, brand owners, and recycling infrastructure operators. Secondary research leveraged EU PPWR reports, FDA guidelines, EFSA opinions, and customs trade data. This approach ensured robust bottom-up and top-down triangulation for market sizing.
Forecast outputs underwent rigorous consistency checks against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including product type, form, application, end-user, and regional regulatory frameworks. Compound annual growth rates derived from historical data, expert insights, and projected market dynamics. Key industry-specific forecast inputs included petrochemical feedstock price trends and evolving recycled content mandates.
Underlying assumptions cover macroeconomic stability and technological development, with deviation risk concentrated in geopolitical shifts or unforeseen regulatory changes. Forecasts reflect these assumptions, acknowledging potential impact from supply chain disruptions or rapid material science breakthroughs. Practitioners should keep alternative scenarios live as global trade policies and circular economy initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Water-Borne Resins Market