
 India Flooring Resins Market | 2026-2036
India Flooring Resins Market Size, Share, and Industry Trends Forecast 2026-2036
India Flooring Resins Market Insights
Skilled applicator availability for epoxy and polyurethane systems is bifurcating the India flooring resins landscape into organized contractors and informal labor pools. Sika AG leverages its certified installer network to dominate premium commercial specifications across western India. Asian Paints anchors its position through backward integration into resin manufacturing and extensive distribution reach into tier-two cities. Huntsman International LLC competes on specialized aliphatic polyurethane formulations for UV-stable exterior deck coatings.
India flooring resins comprise thermosetting polymer binders—epoxy, polyurethane, acrylic, and phenolic chemistries—formulated with curatives, fillers, and pigments to achieve compressive strengths exceeding 50 MPa and chemical resistance for industrial environments. These materials bond to concrete substrates to create seamless, hygienic surfaces for manufacturing floors, healthcare facilities, and transportation infrastructure. Epoxy formulations lead volume consumption due to their cost-performance ratio in heavy industrial flooring, while polyurethane segments capture margin pools in flexible, crack-bridging applications for multi-level parking structures and cold storage facilities. The liquid form dominates installation workflows for self-leveling and trowel-applied systems, though powder variants gain traction in pre-formulated industrial screeds requiring extended shelf stability.
BIS mandates under the Construction Chemicals certification scheme shape product compliance thresholds, while state-level pollution control boards enforce VOC emission limits that favor waterborne and low-solvent resin systems. The CEA's energy efficiency codes for commercial buildings indirectly drive demand for reflective and cool-roof flooring coatings in institutional projects. Stakeholders must monitor evolving green building rating requirements and state-level RERA enforcement intensity to anticipate specification shifts in residential and commercial segments.
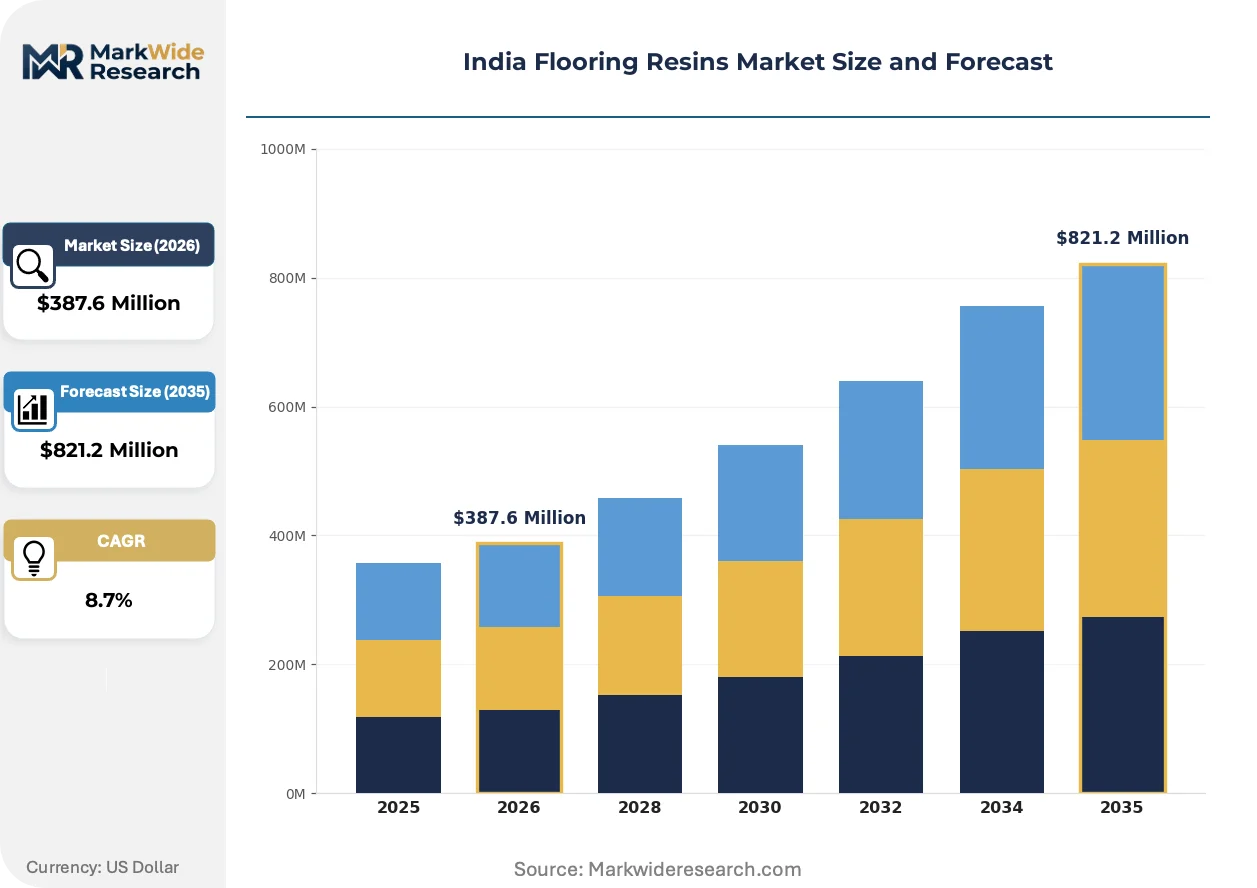
Market Dynamics
BIS certification mandates under the Construction Chemicals scheme are compressing informal supply channels and forcing capital investment into quality infrastructure among domestic resin formulators. This regulatory tightening coincides with warehousing corridor expansion in Maharashtra and Gujarat, creating dual pressure on manufacturers to scale certified capacity rapidly.
Growth Catalysts
- Industrial Corridor Investments:Dedicated freight corridors and logistics parks in Maharashtra, Gujarat, and Karnataka are generating concentrated demand for high-performance epoxy and polyurethane flooring systems in distribution centers and cold storage facilities.
- CEA Energy Efficiency Codes:Commercial building mandates for reflective surfaces are pulling cool-roof and light-reflective resin coatings into institutional specifications across tier-one cities.
- Formal Sector Consolidation:BIS quality thresholds are accelerating exit of uncertified local blenders, opening volume share for organized manufacturers with in-house testing laboratories and documented traceability.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin prices track bisphenol-A and epichlorohydrin import costs, exposing margin compression when crude oil benchmarks spike and rupee weakens against dollar-denominated contracts.
- Import Concentration in Specialty Hardeners:Aliphatic amine curatives and isocyanate prepolymers for UV-stable polyurethane systems remain dominated by suppliers from Germany, Switzerland, and South Korea, creating forex-linked supply risk.
- Substitution by Polished Concrete:Laser-screeded and densified concrete systems are capturing budget-sensitive industrial specifications where chemical resistance requirements are moderate, particularly in light manufacturing and assembly operations.
Strategic Opportunities
- Tier-Two City Penetration:Organized distribution networks into Indore, Coimbatore, and Visakhapatnam remain underdeveloped relative to Mumbai and Bengaluru, offering first-mover positioning as warehousing decentralizes.
- Waterborne Formulation Expansion:State Pollution Control Board VOC limits in Maharashtra and Gujarat are creating regulatory pull for low-solvent epoxy and polyurethane systems with compliant emission profiles.
- Healthcare Infrastructure Buildout:Antimicrobial resin flooring specifications for hospital expansion under Ayushman Bharat are opening specialized application segments requiring certified hygiene performance.
Industry Challenges
- Certified Applicator Scarcity:Self-leveling epoxy and polyurethane screed installation demands trained crews with moisture testing and substrate preparation competency, creating bottlenecked project execution timelines.
- BIS Compliance Timeline Compression:Laboratory testing and documentation requirements for Construction Chemicals certification are extending product launch cycles by four to six months for reformulated resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Flooring Resins Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Phenolic End User: Residential, Commercial, Industrial, Institutional Application: Flooring, Coatings, Adhesives, Sealants Form: Liquid, Powder, Granules, Paste |
| Companies Covered | Sika AG, RPM International Inc., Saint-Gobain, Mapei S.p.A, Thermax Limited, Asian Paints, Aditya Birla Chemicals, Atul Ltd., Huntsman International LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Flooring Resins Market Trends and Innovations
Product formulation and specification workflows in Indian flooring resins are diverging along performance-tier lines, with premium segments demanding extended durability warranties and economy segments prioritizing installed cost minimization.
Hybrid epoxy-polyurethane systems are fragmenting traditional chemistry boundaries by combining epoxy substrate adhesion with polyurethane topcoat flexibility. Automotive manufacturing facilities in Chennai and Pune are specifying these hybrids for assembly line areas requiring both chemical resistance and thermal shock tolerance. The technology is fragmenting established specification categories that previously separated rigid epoxy industrial floors from flexible polyurethane deck coatings.
BIS mandatory certification under the Construction Chemicals scheme is forcing laboratory investment and quality documentation upgrades among domestic formulators. Manufacturers without in-house testing infrastructure are exiting or partnering with certified toll blenders to maintain market access. Western India manufacturers with existing quality systems are absorbing displaced volume from informal competitors.
Project bundling is compressing standalone flooring contracts into larger turnkey interior packages. General contractors in Bengaluru and Hyderabad commercial developments are absorbing resin flooring scope into broader fit-out agreements, marginalizing specialized applicators without direct developer relationships. This consolidation is most visible in Grade-A office and retail mall specifications where single-point accountability reduces interface risk.
India Flooring Resins Market Segmentation
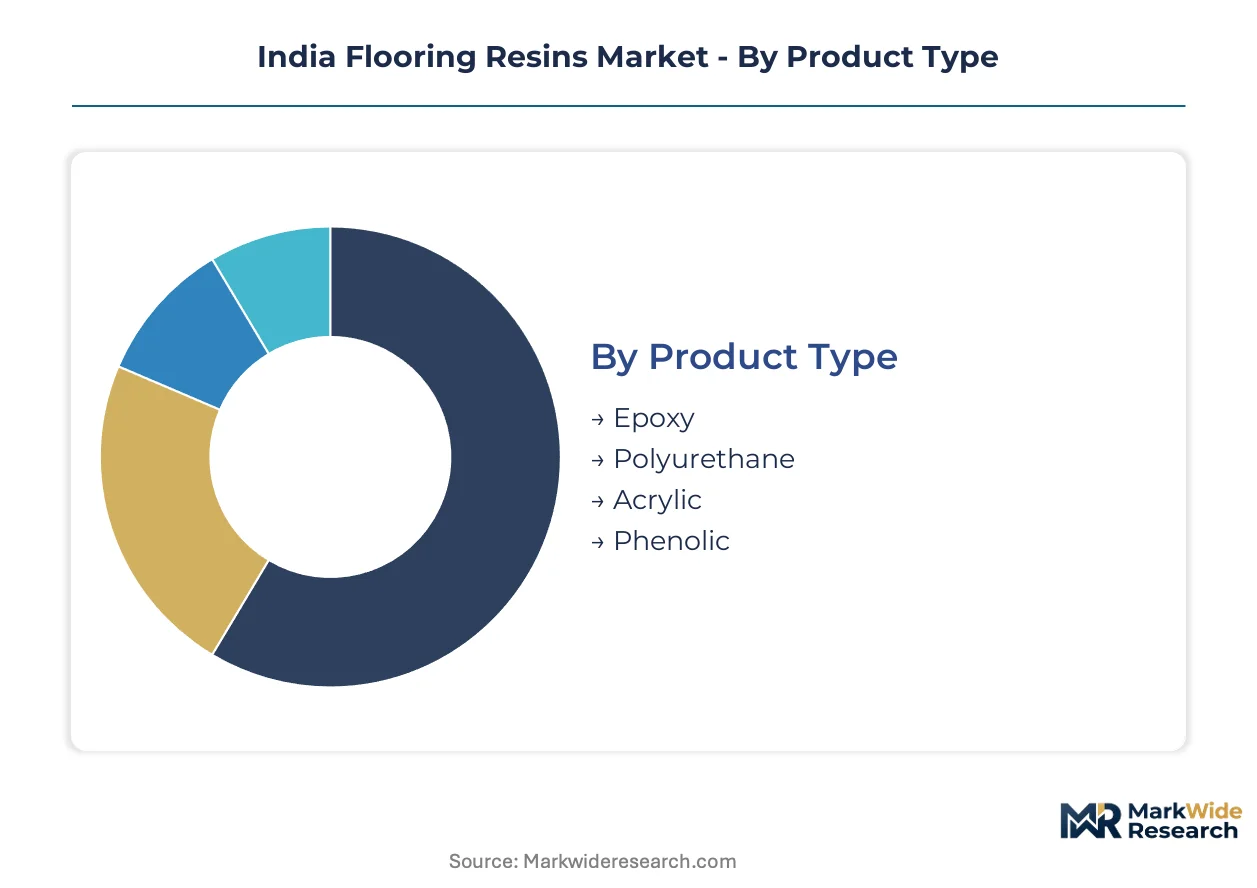
Segmentation in the India flooring resins market reveals how product chemistry, application environment, and physical form create distinct competitive arenas with divergent margin structures and regulatory exposure. Understanding these divisions exposes where BIS certification pressures concentrate and which segments offer escape from petrochemical feedstock volatility.
Product Type:
Epoxy formulations dominate domestic consumption across Maharashtra and Gujarat industrial corridors, while polyurethane systems attract premium specifications in Bengaluru and Chennai commercial developments. Acrylic and phenolic chemistries serve specialized export-oriented niches with tighter volume but higher per-kilogram realizations.
- Epoxy:Thermosetting polymers formulated from bisphenol-A and epichlorohydrin deliver compressive strength exceeding 50 MPa and chemical resistance for heavy manufacturing environments. Demand concentrates in Pune and Ahmedabad automotive plants and warehousing clusters where cost-performance ratios outweigh flexibility requirements. BIS certification timelines hit this segment hardest due to volume scale and reformulation frequency.
- Polyurethane:Aliphatic and aromatic isocyanate prepolymers provide crack-bridging flexibility and UV stability for multi-level parking structures and exterior deck coatings. Bengaluru commercial real estate developers specify these systems for thermal shock tolerance in climate-exposed applications. Import dependence on German and South Korean curative suppliers creates forex-linked margin pressure.
- Acrylic:Waterborne emulsion systems serve decorative commercial flooring with moderate durability requirements and faster installation turnaround.
- Phenolic:High-temperature resistant formulations target specialized industrial applications with extreme thermal exposure profiles.
Epoxy holds the largest share; momentum sits with polyurethane as commercial specifications prioritize flexibility warranties.
End User:
Cost tier stratification separates specification-grade industrial projects from price-sensitive residential applications, with institutional segments offering regulatory-stable demand under government healthcare expansion.
- Industrial:Manufacturing facilities, logistics parks, and cold storage operations demand certified high-performance systems with documented compressive strength and chemical resistance. Maharashtra warehousing corridor investments and Gujarat port-connected industrial zones generate concentrated volume for epoxy and polyurethane screeds. BIS Construction Chemicals certification is non-negotiable for contractor qualification.
- Commercial:Retail malls, Grade-A offices, and hospitality developments in Mumbai and Hyderabad drive specifications for aesthetic finish and warranty-backed durability. Project bundling into turnkey interior packages is compressing standalone flooring contracts and marginalizing specialized applicators without developer relationships.
- Institutional:Hospital expansion under Ayushman Bharat pulls antimicrobial resin flooring with certified hygiene performance into specialized application segments.
- Residential:Tier-two city apartments and builder floors prioritize installed cost minimization over extended durability, exposing this segment to polished concrete substitution.
Industrial commands volume leadership; institutional segments are expanding most quickly on healthcare infrastructure buildout.
Application:
Volume concentration in flooring systems contrasts with margin opportunity in adhesives and sealants where formulation complexity creates pricing power.
- Flooring:Self-leveling and trowel-applied systems constitute the dominant application, spanning industrial screeds, commercial decorative finishes, and hygienic healthcare surfaces. Installation workflow demands for moisture testing and substrate preparation competency create certified applicator scarcity bottlenecks in tier-two markets.
- Coatings:Cool-roof and light-reflective formulations gain traction under CEA energy efficiency codes for commercial buildings in tier-one cities.
- Adhesives:Specialized bonding agents for resin flooring installation and substrate priming offer formulation margin pools distinct from bulk flooring materials.
- Sealants:Joint fillers and expansion joint systems complete seamless flooring assemblies in industrial and transportation infrastructure applications.
Flooring anchors absolute volume; coatings are climbing the fastest on regulatory pull for reflective surfaces.
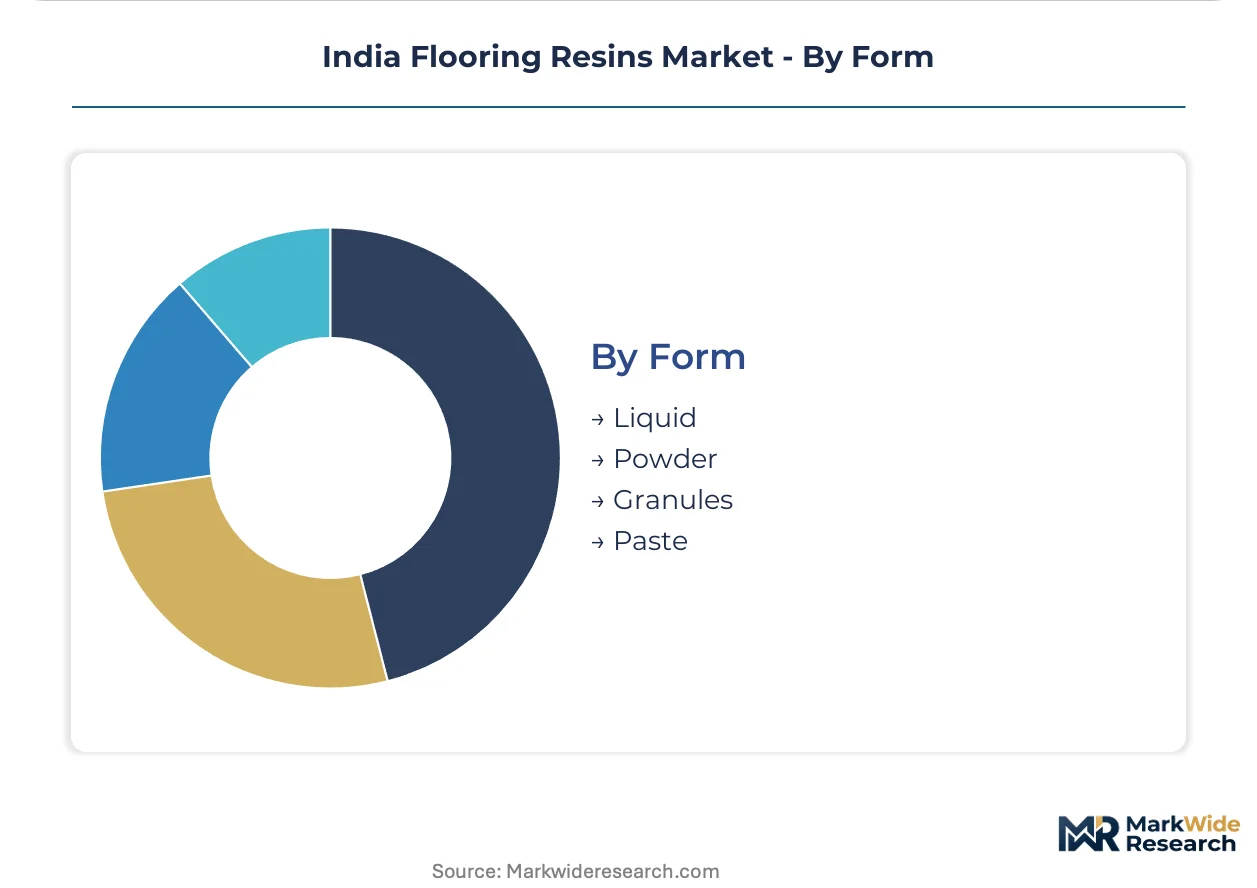
Form:
Physical state determines supply chain configuration, with liquid systems demanding just-in-time logistics and powder variants enabling extended shelf stability for remote project sites.
- Liquid:Self-leveling and trowel-applied resin systems dominate installation workflows for seamless flooring completion. Western India organized manufacturers with captive distribution networks control this form factor through rapid delivery to Mumbai and Ahmedabad project sites.
- Powder:Pre-formulated industrial screeds with extended shelf stability serve warehousing projects in Indore and Visakhapatnam where logistics decentralization creates inventory carrying advantages.
- Granules:Broadcast aggregates for slip-resistant and decorative flake finishes in commercial and institutional applications.
- Paste:High-build trowel-grade compounds for repair mortars and coving details in hygiene-critical environments.
Liquid maintains dominant share; powder formats are gaining share fastest on warehousing decentralization into tier-two corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates and warehousing corridor investments are redistributing flooring resins demand across Indian states. State-level pollution control boards enforce differentiated VOC limits that favor low-solvent systems in industrialized regions.
Maharashtra
Dedicated freight corridors and Mumbai-Pune logistics parks drive epoxy screed specifications for distribution centers. State Pollution Control Board emission limits in Maharashtra favor waterborne polyurethane formulations in Thane and Navi Mumbai manufacturing zones. The Jawaharlal Nehru Port Trust hinterland anchors concentrated demand for chemical-resistant industrial flooring.
Gujarat
Port-connected industrial zones in Ahmedabad and Vadodara generate volume for heavy-duty resin systems in automotive and pharmaceutical manufacturing. BIS Construction Chemicals certification is non-negotiable for contractor qualification in Gandhinagar warehousing clusters. Dahej and Mundra port infrastructure projects specify UV-stable polyurethane deck coatings for exterior exposure.
Karnataka
Bengaluru commercial real estate developers specify flexible polyurethane systems for multi-level parking structures requiring thermal shock tolerance. The state's pollution control board enforces VOC thresholds that accelerate waterborne formulation adoption in Whitefield and Electronic City IT corridors. Mysuru and Tumkur warehousing decentralization creates tier-two demand pockets.
Tamil Nadu
Chennai automotive assembly facilities specify hybrid epoxy-polyurethane systems combining chemical resistance with crack-bridging flexibility. CEA energy efficiency codes for commercial buildings pull cool-roof resin coatings into institutional specifications. Sriperumbudur and Oragadam industrial belts concentrate demand for certified high-performance flooring.
Telangana
Hyderabad pharmaceutical and biotechnology parks demand antimicrobial resin flooring with certified hygiene performance. State-level RERA enforcement intensity shapes specification standards in residential and commercial segments. Genome Valley and Pocharam industrial corridors generate specialized application demand for seamless hygienic surfaces.
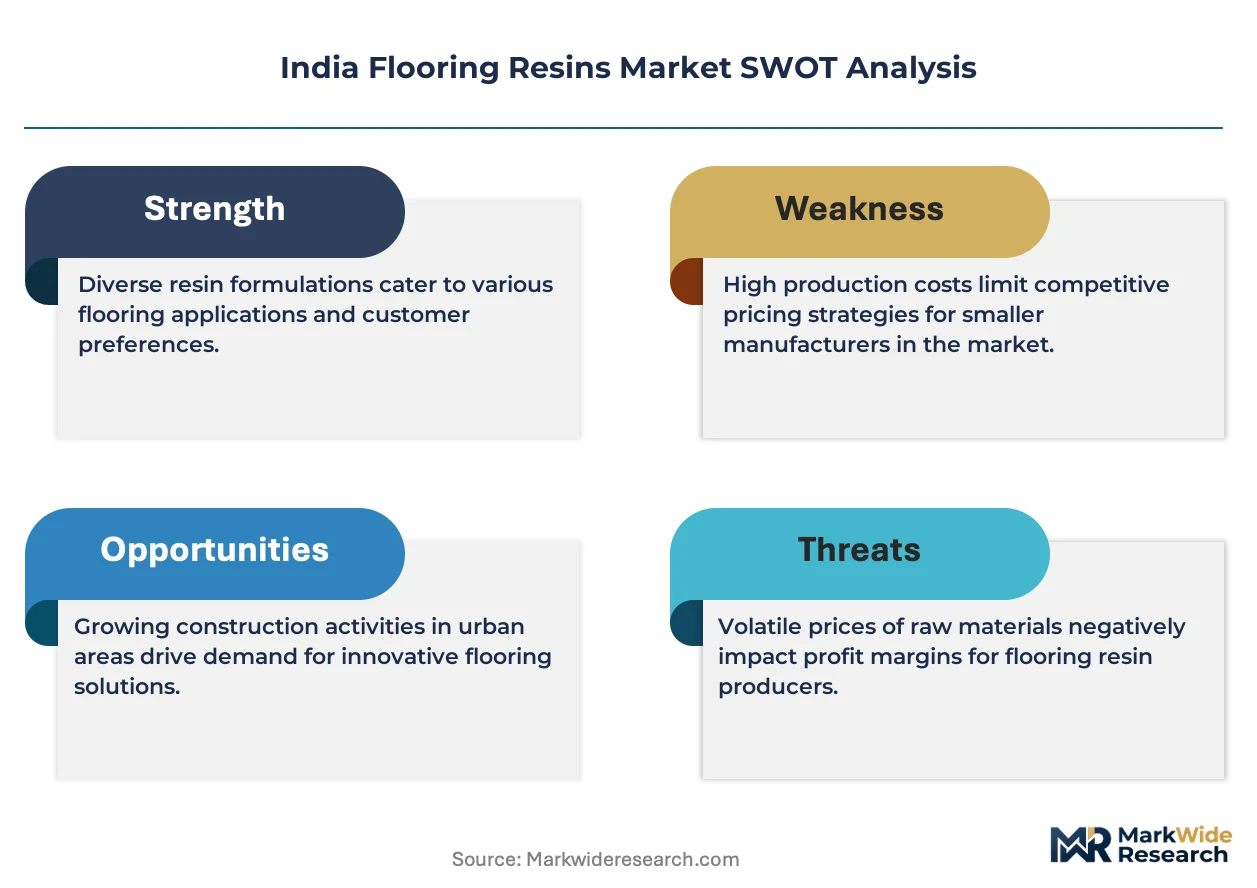
India Flooring Resins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the India flooring resins market. Organized manufacturers with captive resin production and certified installer networks control premium commercial specifications. Three archetypes dominate: multinational chemical conglomerates with global formulation libraries, domestic paint and coatings majors with backward integration into resin manufacturing, and specialized construction chemical firms with application expertise. Competitive intensity centers on BIS certification acquisition and certified applicator network expansion.
Among Switzerland-based chemical specialists, Sika AG exemplifies the integrated leader archetype through its certified installer network dominance in western India. Asian Paints anchors the domestic integrated tier with extensive distribution reach into tier-two cities and in-house resin manufacturing capabilities. Huntsman International LLC occupies a position among specialty chemical multinationals competing on aliphatic polyurethane formulations for UV-stable applications.
| Leading Market Players |
|---|
| Sika AG |
| RPM International Inc. |
| Saint-Gobain |
| Mapei S.p.A |
| Thermax Limited |
| Asian Paints |
| Aditya Birla Chemicals |
| Atul Ltd. |
| Huntsman International LLC |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at western India resin manufacturing clusters shapes both supply concentration and price floors for domestic formulators. BIS certification mandates compress informal blending capacity, forcing capital investment that elevates minimum viable scale and hardens pricing tiers across Maharashtra and Gujarat production zones.
Pricing Analysis
Long-term offtake contracts dominate procurement for large warehousing and automotive manufacturing projects, insulating certified manufacturers from spot volatility in petrochemical feedstocks. Project-based pricing structures separate BIS-certified systems from uncertified alternatives, with quality grade and certification level driving 20-30% spreads between organized and informal supply. Price erosion runs through economy-tier residential applications where polished concrete substitution intensifies. Industrial buyers demonstrate lowest price sensitivity due to warranty and durability requirements, while residential developers in tier-two cities exhibit acute cost consciousness.
Supply Chain Analysis
Port congestion at Jawaharlal Nehru Port Trust elevates inbound logistics costs for bisphenol-A and epichlorohydrin shipments from China, South Korea, and Germany. Domestic formulation draws from imported epoxy intermediates, aliphatic amine curatives from Switzerland and South Korea, and local mineral fillers. Single-source vulnerability concentrates in specialty isocyanate prepolymers for UV-stable polyurethane systems. Distribution runs through organized manufacturer networks with captive applicator certification programs serving Mumbai, Ahmedabad, and Bengaluru project corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India flooring resins sits in early-cycle expansion as warehousing corridor investments and BIS formalization create structural room for organized manufacturers to capture displaced informal volume. Penetration in tier-two cities remains below saturation thresholds despite accelerating specification demand.
For Market Incumbents: Consolidate applicator network control through exclusive certification partnerships in Indore, Coimbatore, and Visakhapatnam before competitors establish training infrastructure. Acquire toll-blending capacity from exiting informal formulators to absorb displaced volume without greenfield construction delays. Polished concrete substitution in light manufacturing threatens epoxy screed margins; counter with hybrid system warranties that concrete cannot match.
For New Entrants and Emerging Players: Lead with waterborne formulation platforms targeting Maharashtra and Gujarat State Pollution Control Board VOC compliance deadlines as the regulatory wedge. Tier-two city warehousing decentralization offers the most penetrable geography, with powder-format industrial screeds suited to remote inventory carrying. Partner with regional construction chemical distributors lacking certified resin supply to bypass Sika and Asian Paints direct-sales dominance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among applicator-network-integrated manufacturers with maintenance-service bundling on commercial warranties. Five-to-ten year viability favors targets with captive resin production and BIS laboratory infrastructure already operational. Watch certified installer headcount growth rates as the inflection signal for share capture velocity in emerging geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive supply of bisphenol-A derivatives insulates margin from rupee-dollar volatility in import contracts. |
| Certified Applicator Network Expansion | BIS-mandated installation competency creates bottlenecked execution capacity that controls project access. |
| Waterborne Formulation Platform Launch | Maharashtra and Gujarat VOC limits pull low-solvent systems into regulatory compliance advantage. |
| Tier-Two Distribution Channel Buildout | Indore and Visakhapatnam warehousing decentralization outpaces organized supply infrastructure deployment. |
| Hybrid Epoxy-Polyurethane System Development | Chennai and Pune automotive specifications reward thermal shock tolerance that pure chemistries cannot deliver. |
Research Methodology
A spread of perspectives from plant managers at resin formulators, procurement leads at logistics park developers, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, BIS certification registries, SEC filings of listed coatings manufacturers, and state industrial development corporation project announcements. Bottom-up volume estimates from application-grade consumption patterns triangulated against top-down value projections from organized manufacturer revenue disclosures.
Segmentation dimensions modeled span product chemistry tier, end-use industry vertical, physical form factor, and state-level regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating industrial corridor investment pipelines and BIS compliance phase-in schedules. Forecast inputs include warehousing square footage absorption rates and automotive manufacturing capacity expansion timelines.
Underlying assumptions cover BIS certification enforcement continuity and petrochemical feedstock price band stability, with deviation risk concentrated in rupee depreciation spikes and informal sector exit velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market