
 Global Polypropylene Random Copolymer Market | 2026-2036
Global Polypropylene Random Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Random Copolymer Market Foresight
Middle Eastern petrochemical producers is repositioning global supply chains through advantaged feedstock economics. SABIC leverages integrated propane dehydrogenation complexes to sustain cost-competitive random copolymer exports. LyondellBasell Industries anchors North American supply through its Houston Ship Channel manufacturing complex. Braskem differentiates via bio-based polypropylene development at its Triunfo complex in Brazil.
Polypropylene random copolymer consists of propylene monomer chains with randomly distributed ethylene comonomer units, typically at one to seven weight percent ethylene content, produced via Ziegler-Natta or metallocene catalysis in slurry or gas-phase reactors. This molecular architecture yields amorphous regions that enhance optical clarity and impact resistance for transparent packaging and medical applications. The injection molding segment dominates processing volumes for thin-wall food containers and closures where cycle time efficiency determines converter economics. Extrusion-based packaging films represent the fastest-growing application as brand owners convert from polystyrene and PVC to random copolymer for thermoformed trays. Medical devices command premium pricing tiers due to USP Class VI and ISO 10993 biocompatibility certification requirements.
The US FDA regulates food-contact polypropylene under 21 CFR 177.1520, while the EU REACH framework governs monomer residual limits and additive migration for consumer goods applications. China's SAMR enforces GB standards for plastic food packaging materials that constrain imported random copolymer specifications. Japan's METI chemical substance reporting requirements create additional compliance layers for Asian supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions that will reshape material circularity requirements and recycling infrastructure investments.
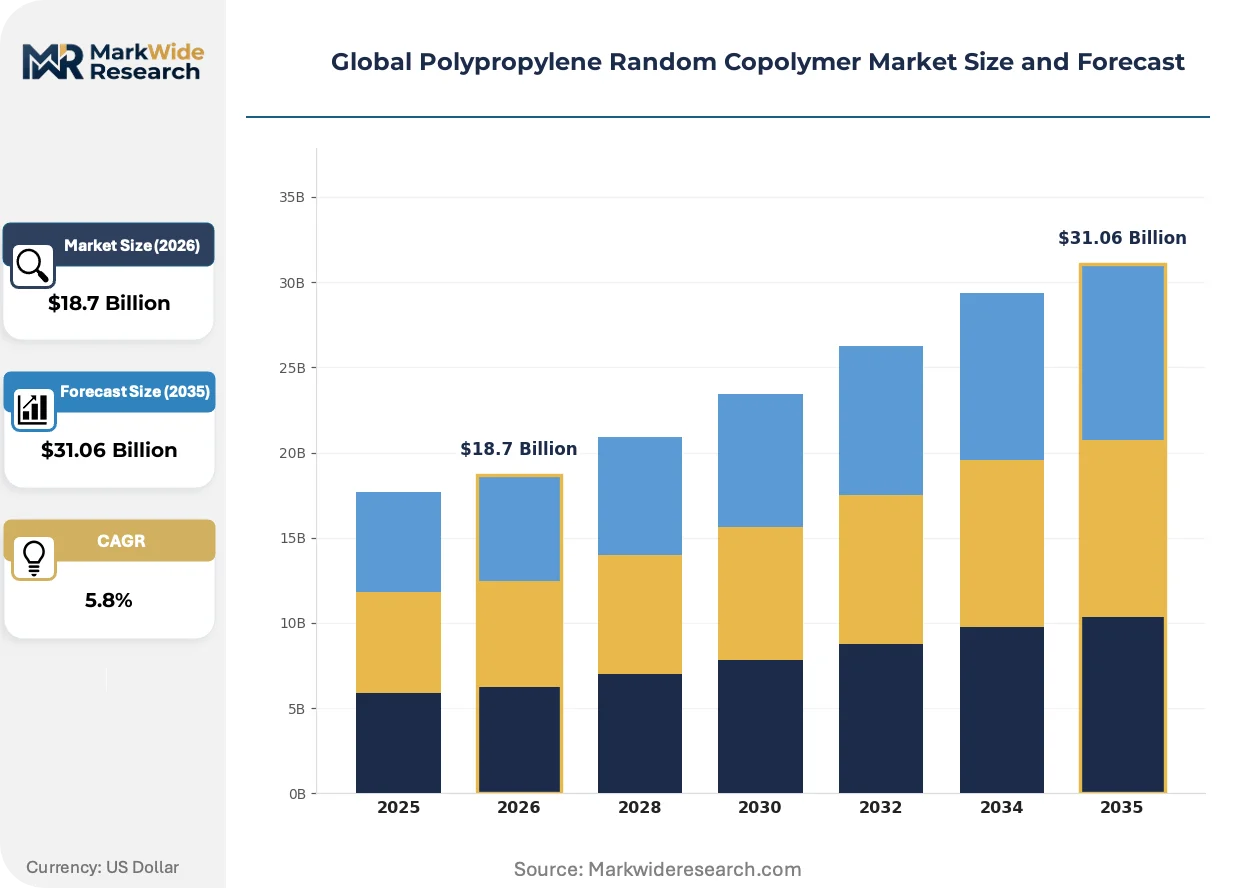
Market Dynamics
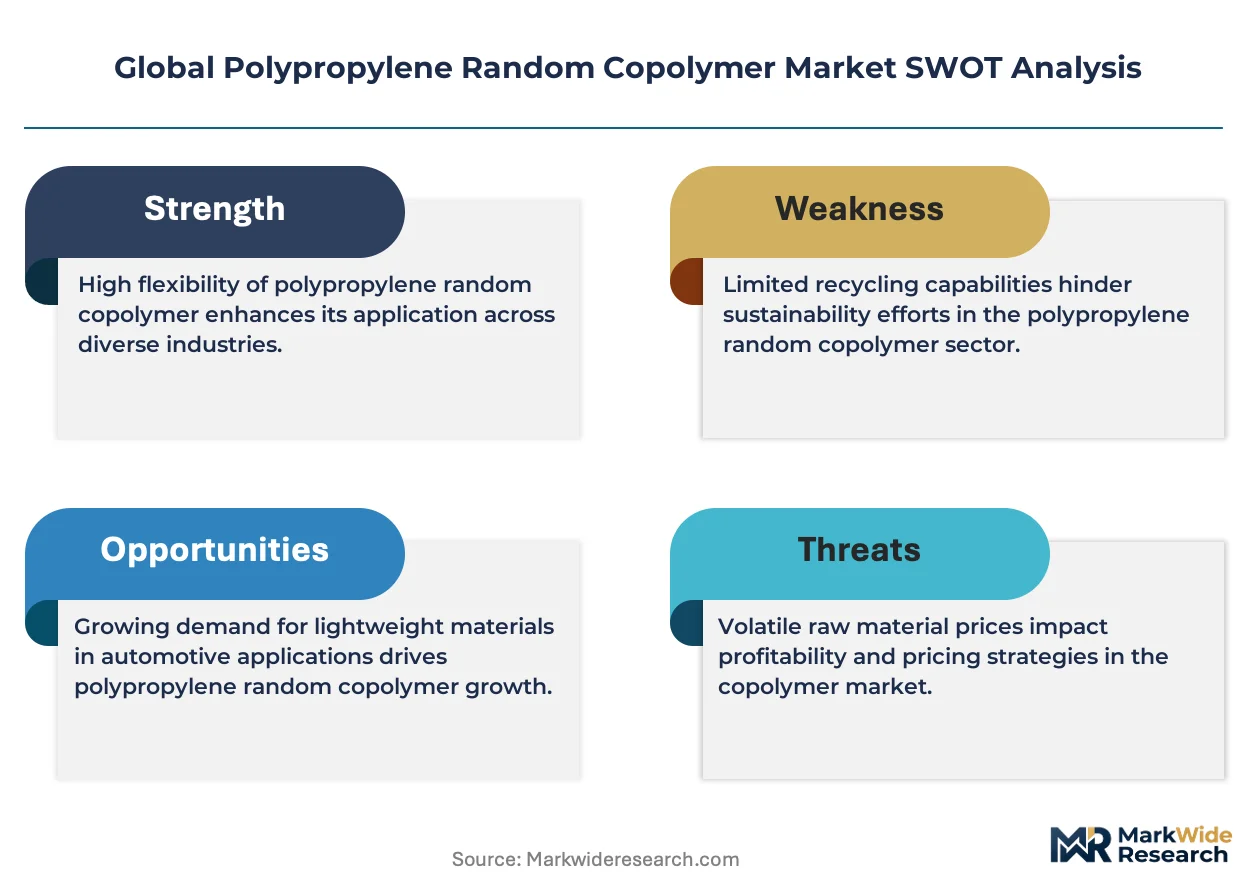
Propane dehydrogenation feedstock economics are compressing global supply chain margins, forcing converters to rebalance procurement between Middle Eastern export volumes and regional integrated production.
Growth Catalysts
- EU REACH compliance mandates:ECHA chemical safety requirements for monomer residuals are accelerating certified random copolymer procurement across European food packaging converters.
- Metallocene catalysis adoption:Advanced single-site catalyst systems enable tighter ethylene distribution control, yielding optical clarity grades that displace polystyrene in thermoformed tray applications.
- Yangtze River Delta concentration:China's integrated petrochemical clusters supply domestic converters with rail-served random copolymer, reducing import dependency for injection molding operations.
Market Restraints
- Propane feedstock volatility:PDH unit economics swing with regional propane-naphtha price spreads, compressing margin predictability for non-integrated producers.
- Supply concentration risk:Middle Eastern export volumes dominate seaborne trade, exposing Asian converters to shipping rate fluctuations and port congestion at Jebel Ali.
- Polystyrene residual substitution:Lower-cost crystal polystyrene retains share in non-contact packaging layers where optical clarity requirements remain permissive.
Strategic Opportunities
- Indian food packaging expansion:FSSAI enforcement of plastic food-contact standards creates certified material demand from Mumbai and Ahmedabad converters building cold-chain infrastructure.
- Bio-based polypropylene development:Braskem's sugarcane-derived propylene pathway offers brand owners Scope 3 emission reductions for premium consumer goods packaging.
- Medical device certification tiers:USP Class VI and ISO 10993 biocompatibility standards enable pricing premiums for random copolymer in syringe barrels and diagnostic cassettes.
Industry Challenges
- Metallocene catalyst licensing complexity:Proprietary single-site catalyst intellectual property constrains technology access for regional producers seeking optical-grade production capability.
- Extended producer responsibility compliance:Evolving circular economy frameworks across multiple jurisdictions require traceability system investments that burden mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Random Copolymer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homo Polymer, Random Copolymer, Block Copolymer, Terpolymer Application: Packaging Films, Automotive Components, Consumer Goods, Medical Devices, Electrical Appliances End Use Industry: Packaging, Transport Equipment, Household Goods, Medical Equipment, Electronics Processing Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming, Compression Molding |
| Companies Covered | INEOS Group, Braskem, LyondellBasell Industries, TotalEnergies, Formosa Plastics Corporation, SABIC, Borealis AG, Sumitomo Chemical, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Random Copolymer Market Shifts & Advancements
Random copolymer production technology is converging with sustainability certification requirements, reshaping how converters validate material provenance and performance specifications.
Metallocene single-site catalysis is unifying optical clarity and impact resistance in single-grade random copolymers. European thermoforming converters are adopting these grades for ready-meal trays at accelerating rates. This technology compression is eliminating the historical trade-off between haze values and drop-test performance that forced dual-grade procurement.
China's SAMR enforcement of GB standards for plastic food packaging materials is tightening monomer residual limits for imported random copolymer. Domestic converters must now document compliance through certified testing laboratories before customs clearance. Japanese and South Korean exporters are responding by pre-certifying production lots to Shanghai and Qingdao entry points.
Brand owners are consolidating supplier relationships around certified circular content claims. Major food packaging converters are displacing spot-market purchasing with multi-year offtake agreements tied to mass-balance certification. This behavioral shift is most visible in Germany and the Netherlands, where supermarket chains mandate recycled content thresholds for private-label packaging.
Global Polypropylene Random Copolymer Market Segmentation
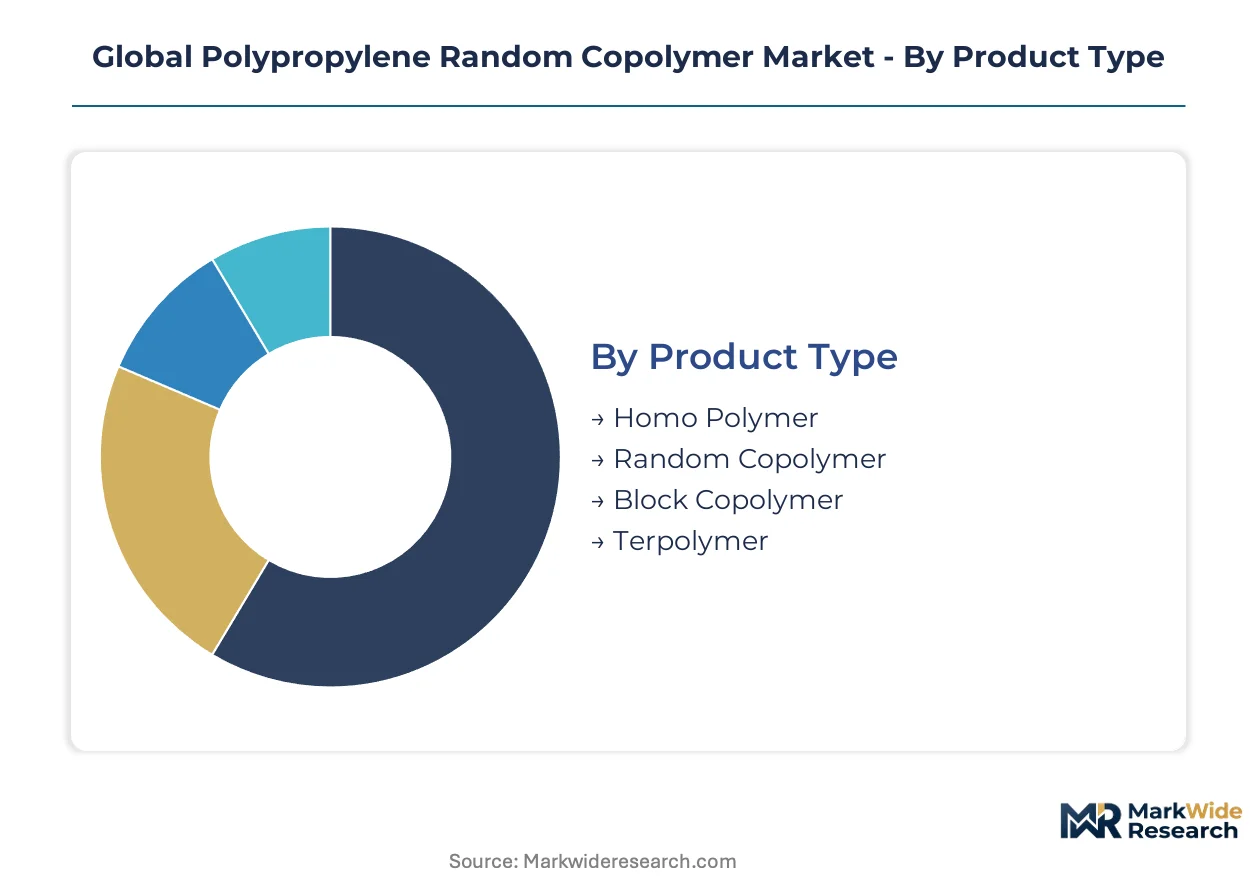
Polypropylene random copolymer procurement patterns diverge sharply across processing technologies and end-use specifications. Converters select grades based on ethylene content, melt flow index, and certification tiers that determine allowable applications in food contact and medical environments.
Product Type:
Standardization dominates commodity grades while specialty variants command formulation premiums for optical clarity and impact balance.
- Homo Polymer:Crystalline polypropylene with uniform propylene sequences delivers maximum stiffness and heat resistance for rigid packaging and automotive underhood components. Demand concentrates in China's appliance manufacturing clusters where cost-efficient injection molding of washing machine tubs and dishwasher racks requires high flexural modulus.
- Random Copolymer:Ethylene comonomer units randomly distributed at one to seven weight percent create amorphous regions that enhance transparency and low-temperature ductility. European thermoforming converters are displacing polystyrene in ready-meal trays as ECHA REACH compliance tightens monomer residual limits for food-contact materials.
- Block Copolymer:Segmented architecture with crystalline homopolymer blocks and rubbery ethylene-propylene copolymer blocks balances stiffness with impact resistance for automotive bumpers and interior trim.
- Terpolymer:Incorporation of additional comonomers such as butene-1 or hexene-1 enables ultra-low sealing temperatures for specialty packaging films.
Most installed capacity flows through Random Copolymer. Expansion is steepest in Terpolymer for high-performance flexible packaging.
Application:
Volume scale separates commodity packaging from premium medical segments where certification tiers multiply pricing power.
- Packaging Films:Biaxially oriented and cast film grades exploit random copolymer clarity for thermoformed trays and lidding applications. Japanese converters at Osaka and Nagoya industrial zones are converting from PVC to meet METI chemical substance reporting requirements for consumer goods.
- Automotive Components:Interior trim and bumper substrates utilize block copolymer impact resistance. German OEM specifications for recycled content integration are forcing compounders to certify mass-balance random copolymer for door panel applications.
- Consumer Goods:Transparent storage containers and housewares demand high-flow random copolymer grades for thin-wall injection molding efficiency.
- Medical Devices:Syringe barrels, diagnostic cassettes, and IV components require USP Class VI and ISO 10993 biocompatibility certification that restricts qualified supplier pools to metallocene-capable producers.
- Electrical Appliances:Refrigerator liners and dishwasher tubs specify homopolymer stiffness with random copolymer cap layers for aesthetic surfaces.
Capacity utilization peaks in Packaging Films. Medical Devices deliver the steepest margin expansion trajectory.
End Use Industry:
Regulatory stringency fragments procurement patterns across jurisdictions with divergent food-contact and medical device standards.
- Packaging:Food-contact random copolymer must satisfy FDA 21 CFR 177.1520 in the United States, EU REACH migration limits, and China's SAMR GB standards simultaneously for export-oriented converters.
- Transport Equipment:Automotive lightweighting mandates are displacing ABS and polycarbonate with mineral-filled random copolymer for instrument panel substrates.
- Household Goods:Storage container manufacturers in India's Gujarat and Maharashtra states are scaling random copolymer procurement as FSSAI enforcement tightens plastic food-contact compliance.
- Medical Equipment:Sterilization-resistant grades for gamma and autoclave exposure command pricing premiums three to five times above commodity packaging tiers.
- Electronics:Thin-wall connectors and housings require high-flow grades with dimensional stability for surface-mount technology compatibility.
Most compounder output serves Packaging. Medical Equipment absorbs capacity additions fastest.
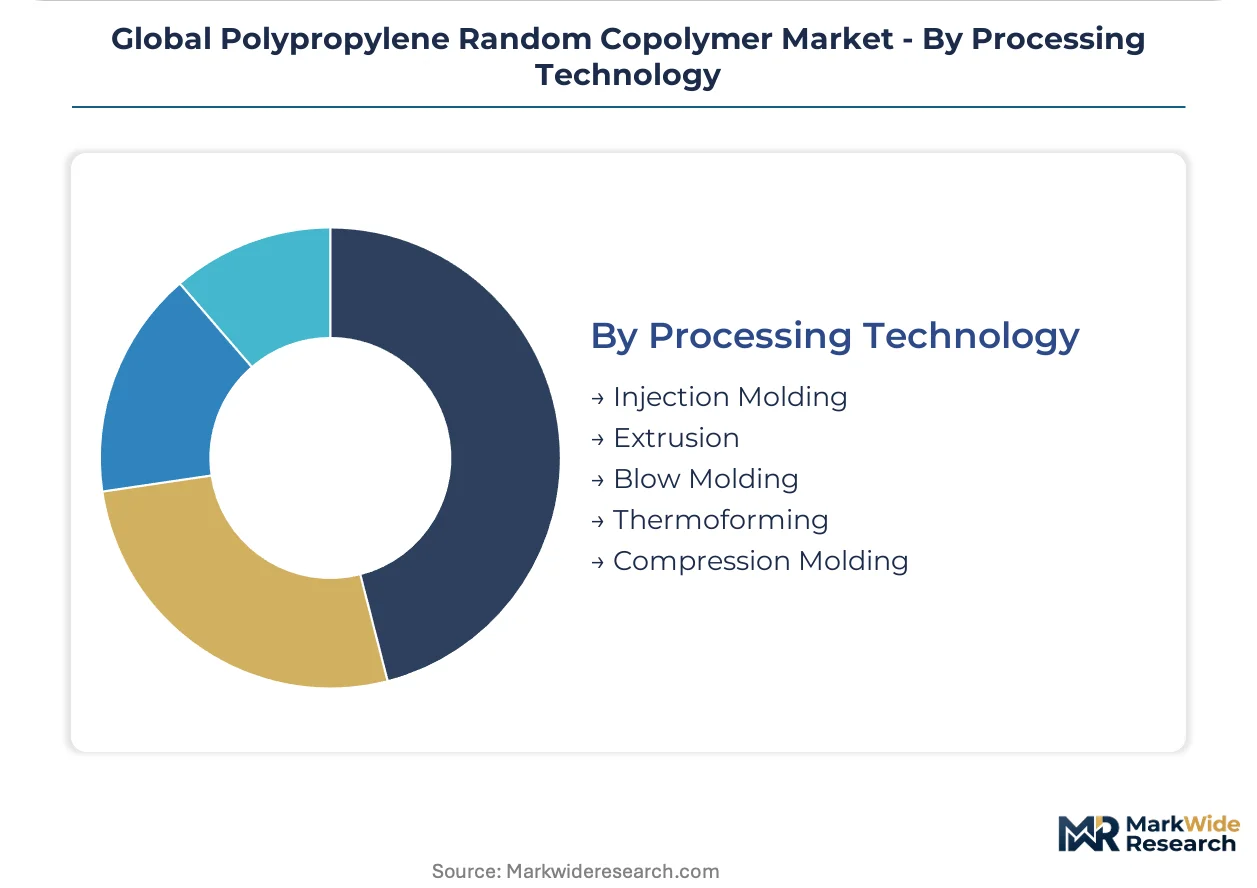
Processing Technology:
Cycle time economics and capital intensity separate high-volume injection molding from specialized thermoforming operations.
- Injection Molding:High-flow random copolymer grades enable sub-five-second cycle times for thin-wall food containers and closures. The Yangtze River Delta petrochemical cluster supplies rail-served material to domestic converters, reducing import dependency for high-volume production.
- Extrusion:Sheet and film extrusion lines are expanding most quickly in Vietnam and Indonesia as brand owners relocate thermoforming operations from China to diversify supply chain risk.
- Blow Molding:Random copolymer clarity grades displace PET in single-serve beverage bottles and personal care containers where squeezability matters.
- Thermoforming:European ready-meal tray producers are adopting metallocene random copolymer to unify optical clarity with drop-test performance in single-grade procurement.
- Compression Molding:Long-fiber thermoplastic composites utilize random copolymer matrices for automotive structural components requiring crash energy absorption.
Injection Molding commands the largest installed base. Thermoforming is climbing fastest as European converters displace polystyrene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting polypropylene random copolymer production toward jurisdictions with advantaged feedstock economics and streamlined compliance pathways. Middle Eastern producers exploit integrated propane dehydrogenation complexes to undercut European and Asian manufacturing costs.
China
Food packaging converters in the Yangtze River Delta are expanding random copolymer procurement for high-clarity containers. SAMR enforcement of GB standards for plastic food packaging materials tightens monomer residual limits for imported material. Domestic petrochemical complexes in Ningbo and Shanghai supply rail-served random copolymer, reducing import dependency for injection molding operations.
Germany
Thermoforming converters are displacing polystyrene in ready-meal trays as ECHA REACH compliance elevates certified material specifications. The EU Green Deal and extended producer responsibility frameworks reshape material circularity requirements for packaging converters. Industrial clusters in North Rhine-Westphalia and Bavaria anchor European demand for mass-balance certified random copolymer grades.
United States
FDA 21 CFR 177.1520 compliance underpins food-contact random copolymer procurement across Midwestern packaging converters. The Houston Ship Channel manufacturing complex anchors North American supply through integrated production and deepwater export capability. Medical device manufacturers in Minnesota and Massachusetts drive premium-tier demand for USP Class VI certified grades.
Saudi Arabia
SABIC leverages integrated propane dehydrogenation complexes to sustain cost-competitive random copolymer exports to Asian and European markets. The country's national industrial regulator enforces chemical safety standards aligned with EU REACH for export-oriented production. Jubail Industrial City concentrates petrochemical capacity serving seaborne trade lanes through Jebel Ali transshipment.
India
FSSAI enforcement of plastic food-contact standards creates certified material demand from Mumbai and Ahmedabad converters building cold-chain infrastructure. DGFT import regulations constrain random copolymer specifications for food packaging applications. Gujarat's petrochemical corridor and Maharashtra's converter base absorb capacity additions fastest among emerging markets.
Global Polypropylene Random Copolymer Market Competitive Landscape
Middle Eastern producers anchor one tier through feedstock-integrated economics; European and North American specialists hold differentiated positions through certification-tier premiums and proximity to regulated end-markets. Market structure concentrates around state-affiliated petrochemical complexes and multinational chemical conglomerates with integrated polypropylene capabilities. Three archetypes dominate: feedstock-integrated exporters, regulatory-certified regional suppliers, and metallocene-capable specialty producers. Competitive moves center on capacity expansion in advantaged feedstock regions and strategic partnerships for circular content certification.
Among feedstock-integrated exporters, SABIC and Braskem exemplify the archetype of producers leveraging regional propane economics for seaborne supply. LyondellBasell Industries occupies a position within the North American specialist tier, representing regulatory-proximate manufacturing aligned with FDA compliance requirements. These three companies anchor distinct competitive vectors: Middle Eastern cost leadership, Latin American bio-based differentiation, and North American certification-tier access.
| Leading Market Players |
|---|
| INEOS Group |
| Braskem |
| LyondellBasell Industries |
| TotalEnergies |
| Formosa Plastics Corporation |
| SABIC |
| Borealis AG |
| Sumitomo Chemical |
| ExxonMobil Chemical |
| Others |
Supply & Pricing Matrix
Sovereign-backed petrochemical producers in Saudi Arabia and state-affiliated complexes across China anchor supply discipline through integrated propane dehydrogenation economics, translating feedstock cost advantages into pricing power over seaborne export markets. This ownership pattern compresses margin volatility for integrated players while forcing non-integrated converters toward long-term offtake contracts to secure volume certainty.
Pricing Analysis
Distributor margin layers in European thermoforming channels absorb 8-12 percentage points before material reaches ready-meal tray converters. Contract-based long-term offtake dominates procurement as brand owners consolidate supplier relationships around mass-balance certification tiers. Price differentiation separates USP Class VI medical grades from commodity packaging tiers by three to five multiples. Pricing pressure stems from PDH unit economics swinging with propane-naphtha spreads, squeezing non-integrated producers. Mid-scale converters in Vietnam and Indonesia exhibit highest price sensitivity due to working capital constraints.
Supply Chain Analysis
Workforce availability constraints in Jubail Industrial City and Ningbo petrochemical zones limit operational flexibility at PDH complexes during turnaround seasons. Supply concentrates in Saudi Arabia, China, and South Korea, with Middle Eastern exports dominating seaborne trade lanes. Raw material dependencies center on propane feedstock, metallocene catalyst systems, and specialized additive packages. Single-source vulnerability runs through Jebel Ali transshipment congestion during peak export windows. Distribution runs through rail-served domestic networks in China and barge-connected river terminals in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where ECHA REACH compliance and USP Class VI certification tiers command sustainable premiums over commodity grades. Demand is shifting toward metallocene-produced optical clarity specifications that displace polystyrene in European ready-meal packaging.
For Market Incumbents: Anticipate propane feedstock volatility by securing backward integration into PDH capacity or captive propane supply agreements. Defend certification-tier pricing power through metallocene catalyst licensing investments that constrain regional competitor access. Prioritize mass-balance audit trail systems to meet evolving extended producer responsibility frameworks in Germany and the Netherlands.
For New Entrants and Emerging Players: Launch via direct-to-converter distribution partnerships in India's Gujarat and Maharashtra corridors where FSSAI enforcement creates certified material shortages. Target medical device converters in Minnesota and Massachusetts seeking second-source USP Class VI supply beyond incumbent qualified supplier pools. White-space penetration is most achievable in bio-based polypropylene segments where Braskem's sugarcane pathway remains the sole commercial-scale offering.
For Investors and Strategic Acquirers: Feedstock-integrated Middle Eastern producers are the most active acquirer in this space, seeking metallocene technology access and European regulatory-proximate manufacturing footprints. Long-term viability favors targets with dual capability in commodity scale and specialty certification tiers. Watch for inflection in Chinese SAMR enforcement stringency as a signal for import displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propane Dehydrogenation | SABIC and Braskem leverage captive propane supply to sustain cost-competitive export economics. |
| Metallocene Catalyst Licensing Agreement | Single-site technology access enables optical clarity grades that displace polystyrene in European thermoforming. |
| Mass-Balance Certification Program | German supermarket chains mandate recycled content thresholds for private-label packaging procurement. |
| Long-term Supply Agreement with Medical Device OEMs | USP Class VI and ISO 10993 tiers restrict qualified supplier pools to three-to-five-year contract structures. |
| Joint Venture in Yangtze River Delta | Domestic Chinese production reduces import dependency for injection molding converters in Ningbo and Shanghai. |
Research Methodology
Coverage spans Asia-Pacific, Europe, North America, and Middle East, with primary inputs from each region's petrochemical manufacturing clusters. The approach combines interviews with plant managers at integrated polypropylene complexes, procurement leads at food packaging converters, distribution channel partners, and technical R&D directors for catalyst systems. Secondary validation draws from customs and trade data, SEC 10-K filings of listed chemical conglomerates, ACC and Cefic industry reports, and SAMR GB standard enforcement notices. Bottom-up capacity utilization models and top-down end-use demand estimates undergo triangulation.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including grade tier (commodity versus optical clarity versus medical certification), end-use industry (packaging, automotive, medical devices), processing technology (injection molding, extrusion, thermoforming), and regional production hub concentration. CAGRs derive from elasticity-adjusted demand projections and capacity addition schedules. Industry-specific forecast inputs include PDH unit operating rates and ECHA REACH compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propane price volatility spikes or sudden regulatory enforcement shifts in China or India. The analysis reflects assumptions about metallocene catalyst technology diffusion and circular content certification adoption trajectories. Material deviation in Middle Eastern export policy or Chinese import substitution acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market