
 Polyether Ketone (PEK) Market | 2026-2036
Polyether Ketone (PEK) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyether Ketone (PEK) Market Analytics
Germany's specialty chemical hub is narrowing the European supply deficit for high-performance ketone polymers. Victrex plc leverages its Lancashire manufacturing base to sustain aerospace-grade PEK output across multiple continents. Ensinger GmbH anchors Central European distribution through its Baden-Württemberg compounding facilities. Solvay competes via its Brussels-headquartered polymer science division with broad fluoropolymer and ketone expertise.
Polyether ketone denotes a semi-crystalline aromatic thermoplastic containing ether and ketone linkages in its backbone, typically processed above 340°C to achieve melt flow suitable for injection molding and extrusion. PEK delivers continuous service temperatures near 260°C, chemical resistance to hydrocarbons, and mechanical retention under load, serving as a metal replacement in structural aerospace brackets, surgical implants, and downhole oil components. Aerospace applications command premium positioning due to flame-smoke-toxicity certification requirements and long qualification cycles. Medical device-grade PEK-P formulations are expanding fastest as orthopedic OEMs seek titanium alternatives with bone-matching modulus. Industrial equipment demand for PEK-R pellets remains mature, with margin pools concentrating in compounded sheet and film forms for semiconductor fabrication tooling.
EMA medical device regulations and REACH substance restrictions shape European PEK formulation standards, while FAA airworthiness directives influence North American aerospace qualification pathways. FDA 510(k) clearance requirements for implantable PEK devices create multi-year barriers to entry for unproven resin suppliers. ISO 10993 biocompatibility testing protocols further filter medical-grade material approvals. Stakeholders must monitor evolving MDR clinical evidence requirements in Europe and assess whether captive compounding investments or qualified tolling partnerships better secure supply chain continuity under tightening chemical substance scrutiny.
Market Dynamics
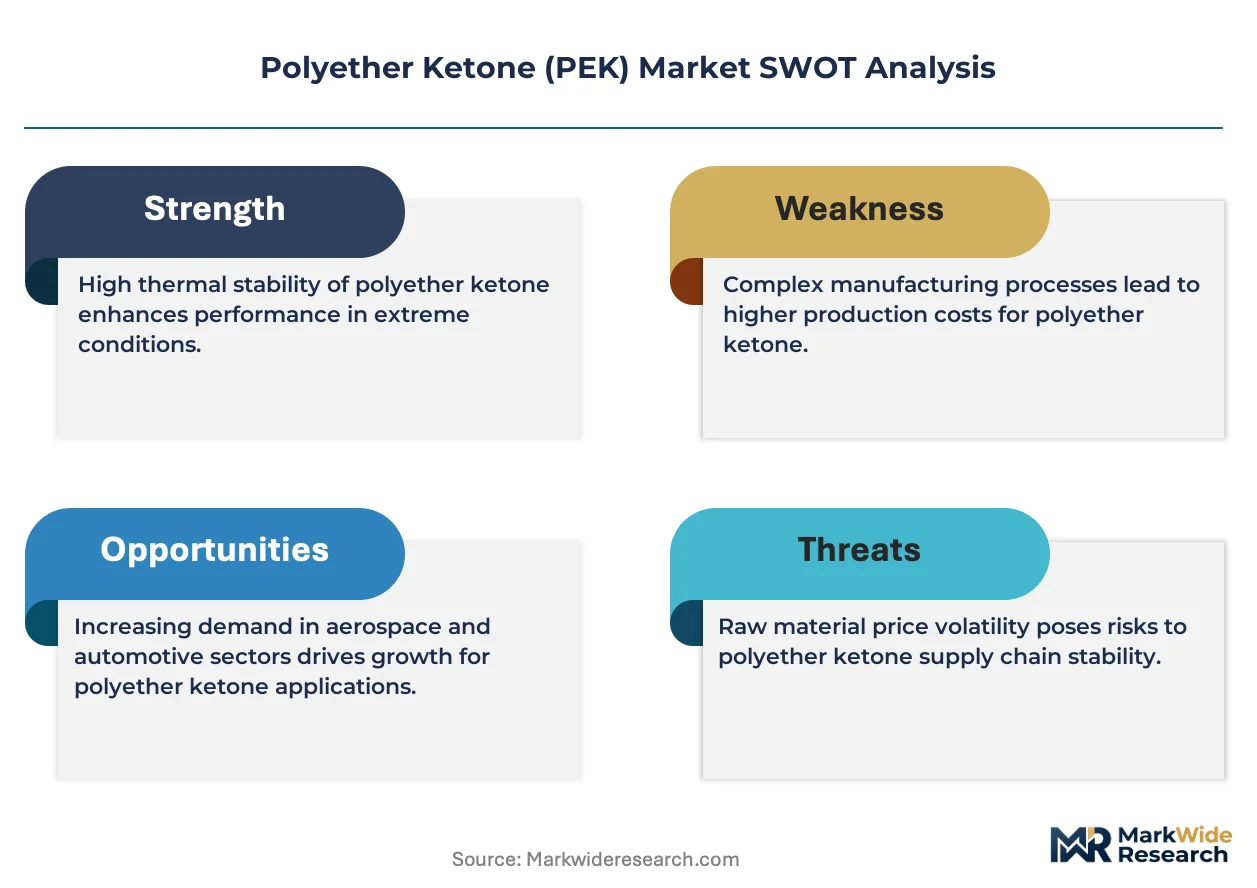
Aerospace thermoplastic composite programs are compressing PEK qualification timelines as airframers pursue out-of-autoclave processing for next-generation narrowbody platforms. This demand acceleration collides with tightening EU chemical substance oversight, creating supply-side friction for resin compounders serving dual-use medical and aerospace grades.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:REACH-compliant PEK formulations gain preferential access to automotive and aerospace procurement frameworks, displacing legacy halogenated polymers in structural brackets and electrical housings.
- Titanium substitution in orthopedic implants:PEK-OPTIMA and carbon-fiber-reinforced variants address modulus-matching requirements for spinal fusion cages and trauma fixation plates, accelerating FDA 510(k) filing volumes.
- Downhole oil tool refurbishment cycles:Hydrocarbon extraction operators in the Permian Basin and North Sea are specifying PEK seals and connectors for extended-reach drilling assemblies exposed to sour gas environments above 200°C.
Market Restraints
- Fluoropolymer feedstock cost volatility:PEK synthesis relies on difluorobenzophenone intermediates whose pricing tracks hexafluoropropylene oxide supply disruptions, compressing compounder margins during energy price spikes.
- Single-source crystallization technology concentration:High-purity PEK resin production depends on proprietary continuous polymerization systems concentrated among three European equipment licensors, creating bottleneck risk for new market entrants.
- PEEK incumbent substitution defense:Victrex and Solvay are extending PEEK temperature ratings and reducing crystallization cycle times to defend aerospace bracket applications against PEK displacement.
Strategic Opportunities
- Saudi Arabia and UAE medical device manufacturing zones:SFDA and MOHAP are streamlining implantable polymer registration pathways, creating first-mover advantages for PEK-P suppliers establishing compounding partnerships in King Abdullah Economic City.
- Convergence of additive manufacturing and topology optimization:Laser sintering of PEK powders with generative design software enables patient-specific cranial implants and lightweight aerospace ducting with lattice structures impossible through injection molding.
- EU MDR clinical evidence grandfathering provisions:PEK implant suppliers with pre-2021 CE marks can leverage existing biocompatibility data to accelerate expanded indication approvals before 2028 regulatory deadlines.
Industry Challenges
- High-temperature polymer processing specialist scarcity:Melt temperatures above 360°C require extrusion technicians trained in thermal degradation prevention and residence time control, with limited vocational pipeline output in Lancashire and Baden-Württemberg industrial corridors.
- FAA airworthiness qualification timeline compression:PEK composite laminate certification for primary structure applications demands 18-24 month flame-smoke-toxicity testing cycles, misaligning with airframer platform development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyether Ketone (PEK) Market |
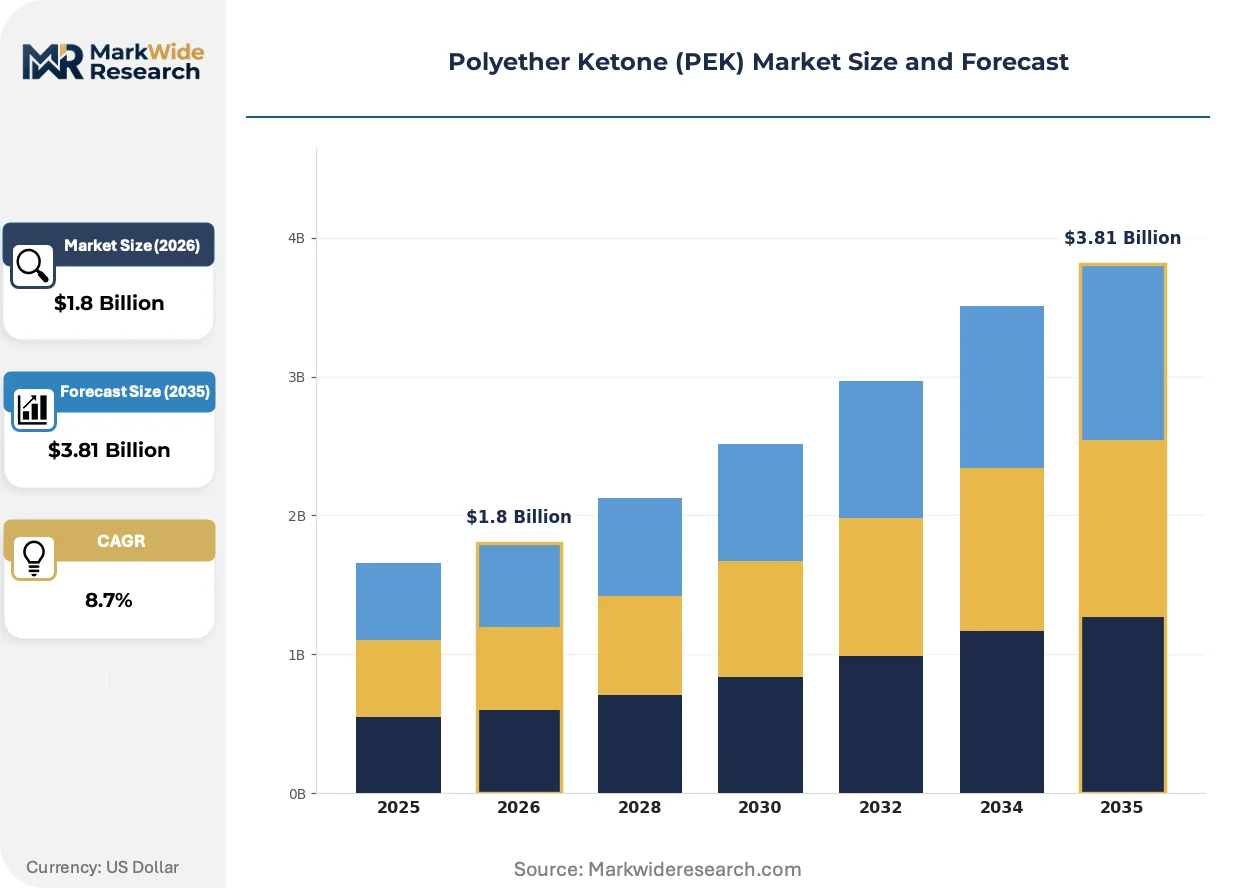
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEK-F, PEK-P, PEK-R, PEK-M Application: Aerospace, Automotive, Medical Devices, Industrial Equipment End User: Manufacturers, Suppliers, Research Institutions, Contractors Form: Pellets, Powders, Sheets, Films |
| Companies Covered | Panjin Zhongrun High Performance Polymers Co., Ltd., Jilin Joinature Polymer Co., Ltd., Victrex plc, Ensinger GmbH, DuPont, Evonik Industries AG, Celanese Corporation, SA BIC, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyether Ketone (PEK) Market Evolving Landscape
Thermoplastic composite welding techniques and recycled feedstock integration are redefining PEK value chain economics. These shifts compress processing energy requirements while opening circular material pathways previously blocked by crystalline polymer reprocessing limitations.
Carbon fiber-reinforced PEK (CF/PEK) prepreg systems are hybridizing automated fiber placement with ultrasonic consolidation, eliminating autoclave curing for aerospace stringers and floor beams. Boeing and Airbus tier-one suppliers in Toulouse and Hamburg are qualifying these out-of-autoclave laminates for secondary structure applications, reducing capital intensity and cycle time by half relative to thermoset alternatives.
EMA's 2023 update to MDR Annex I general safety and performance requirements is forcing PEK implant manufacturers to submit post-market clinical follow-up data on wear debris and osseointegration performance. German notified bodies in Berlin and Munich are prioritizing submissions with ISO 10993-18 chemical characterization profiles, delaying approvals for legacy titanium-comparative studies lacking polymer-specific endpoints.
Orthopedic OEM procurement departments are consolidating resin supplier relationships to secure volume commitments and technical support integration. Stryker and Zimmer Biomet are reducing qualified PEK pellet sources from five to two per manufacturing site, concentrating purchasing power with Ensinger and Victrex while demanding dedicated compounding line access and real-time batch release documentation.
Polyether Ketone (PEK) Market Segmentation
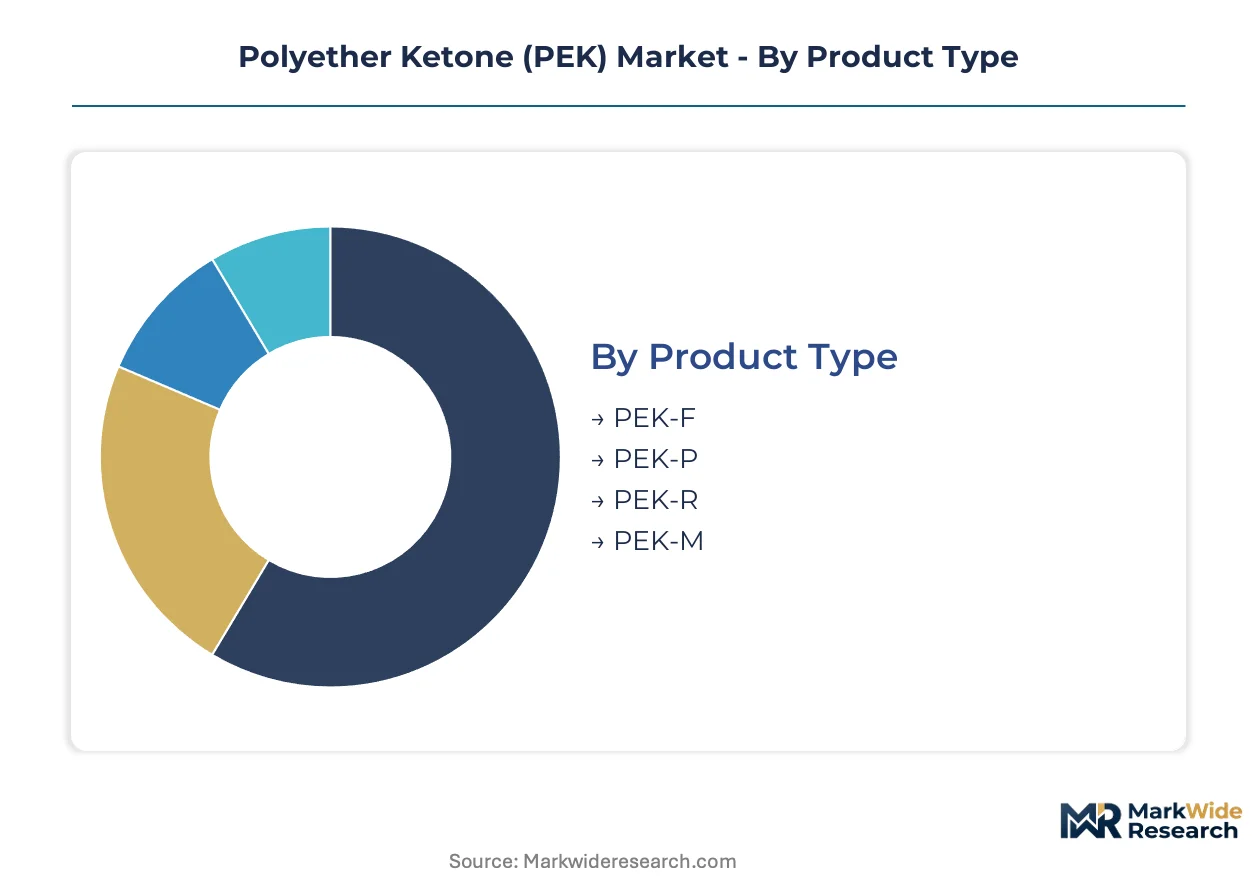
PEK resin specifications diverge sharply across aerospace, medical, and industrial end-uses, with each segment demanding distinct crystallinity profiles and certification pathways. Understanding these dimensional splits reveals where margin pools concentrate and where qualification barriers protect incumbent positions.
Product Type:
Cost tier differentiation separates commodity-grade formulations from aerospace-certified and medical-device-grade variants with tiered pricing structures.
- PEK-F:Standard unreinforced resin serving general industrial brackets and electrical connectors. Demand concentrates in German automotive supplier parks around Stuttgart, where REACH-compliant formulations displace legacy halogenated polymers in under-hood housings.
- PEK-P:High-purity medical-grade variant with enhanced biocompatibility profiles for implantable devices. Orthopedic OEMs in Warsaw and Minneapolis are consolidating procurement around PEK-P suppliers with dedicated compounding lines and real-time batch release documentation.
- PEK-R:Reinforced grade with glass or carbon fiber loading for structural load-bearing applications.
- PEK-M:Modified copolymer grade engineered for specific melt-flow characteristics in thin-wall molding.
PEK-F holds installed capacity. PEK-P is rotating up the share rankings.
Application:
Volume concentration tracks regulatory intensity, with aerospace and medical commanding premium positioning over automotive and industrial segments.
- Aerospace:Thermoplastic composite laminates for primary and secondary structures requiring flame-smoke-toxicity certification. Boeing and Airbus tier-one suppliers in Toulouse and Hamburg are qualifying out-of-autoclave PEK stringers, compressing cycle times by half relative to thermoset alternatives.
- Medical Devices:Spinal fusion cages, trauma fixation plates, and cranial implants seeking titanium substitution. EMA's MDR Annex I updates are forcing post-market clinical follow-up submissions on wear debris and osseointegration performance.
- Automotive:Under-hood electrical housings and thermal management components.
- Industrial Equipment:Semiconductor fabrication tooling and downhole oil seals for sour gas environments.
Aerospace commands qualification premiums. Medical Devices is climbing the fastest.
End User:
Customer type determines technical support intensity and contract structure, from arm's-length commodity supply to embedded engineering partnerships.
- Manufacturers:Tier-one aerospace and orthopedic OEMs with consolidated supplier bases and volume commitment requirements. Stryker and Zimmer Biomet are reducing qualified PEK pellet sources from five to two per manufacturing site, concentrating purchasing power with resin compounders offering dedicated line access.
- Suppliers:Distributors and compounders serving mid-tier industrial accounts with standardized pellets and technical datasheets.
- Research Institutions:Universities and national laboratories developing next-generation PEK formulations and processing methods.
- Contractors:Oilfield service companies and medical device contract manufacturers specifying PEK for refurbishment cycles and patient-specific implants.
Manufacturers anchor procurement volume. Research Institutions are expanding pilot-scale demand.
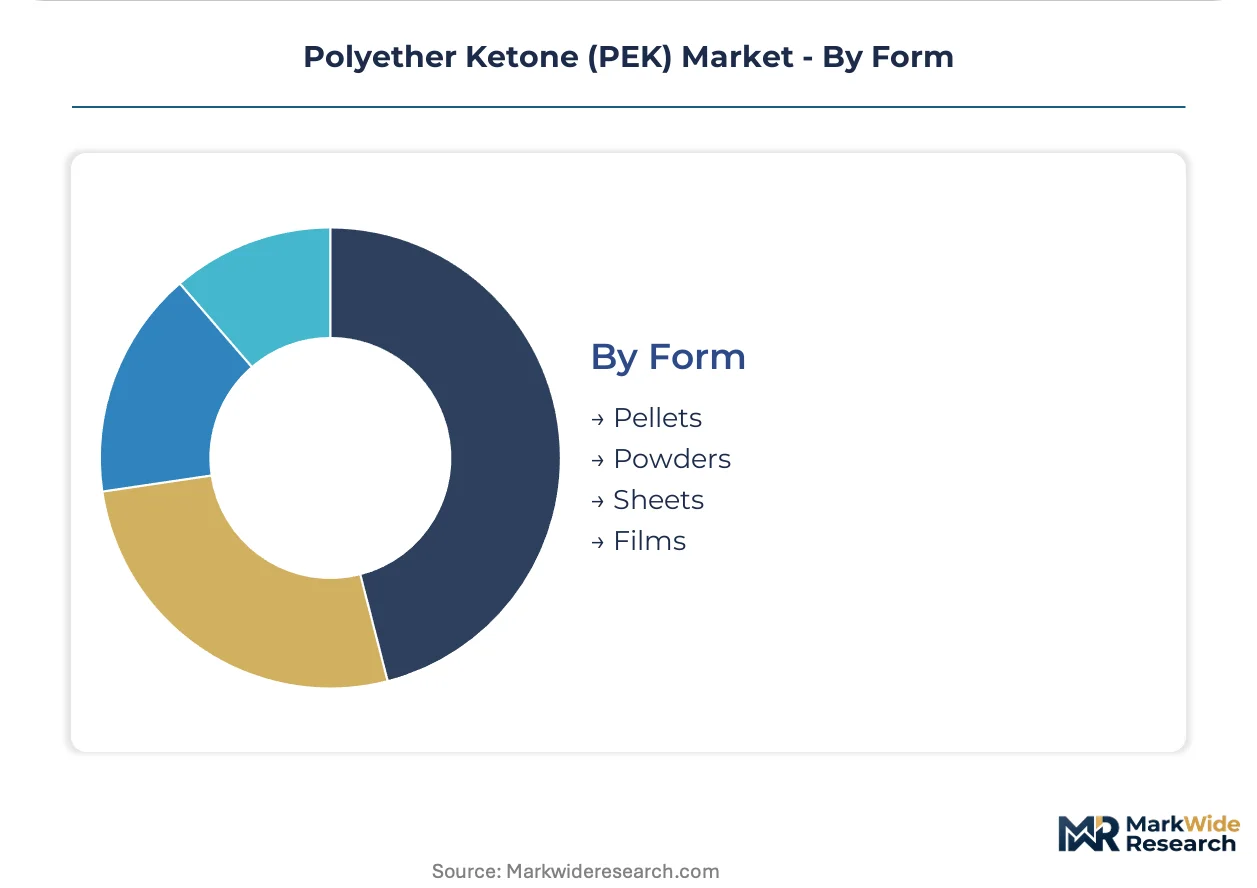
Form:
Supply concentration varies by processing method, with pellets dominating injection molding and powders enabling additive manufacturing expansion.
- Pellets:Standard extruded and cut resin for injection molding and extrusion. Ensinger's Baden-Württemberg compounding facilities and Victrex's Lancashire operations anchor European pellet supply for aerospace and medical grades.
- Powders:Fine-ground resin for laser sintering and compression molding. Convergence with generative design software enables patient-specific cranial implants and lightweight aerospace ducting with lattice structures impossible through conventional molding.
- Sheets:Compression-molded plate stock for CNC machining of prototype and low-volume components.
- Films:Thin-gauge extruded material for electrical insulation and flexible circuit substrates.
Pellets hold installed capacity. Powders are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European PEK formulation standards, while FAA airworthiness directives shape North American aerospace qualification. Demand clusters concentrate in Germany's industrial corridor, the US Permian Basin oilfield services hub, and China's Yangtze River Delta medical device manufacturing zones.
United States
FAA flame-smoke-toxicity certification requirements drive aerospace-grade PEK demand for thermoplastic composite airframes. FDA 510(k) clearance pathways for implantable devices create multi-year barriers protecting established resin suppliers. Boeing tier-one suppliers in Wichita and Seattle are qualifying out-of-autoclave PEK stringers for next-generation narrowbody platforms.
Germany
EU Green Deal industrial decarbonization mandates favor REACH-compliant PEK formulations in automotive under-hood housings. EMA's MDR Annex I updates force post-market clinical follow-up submissions on orthopedic implant performance. Frankfurt and Leverkusen anchor Central European compounding capacity for medical and aerospace grades.
China
NMPA medical device registration reforms accelerate PEK-P implant approvals for spinal fusion applications. MIIT standards for high-performance polymers support domestic substitution in semiconductor fabrication tooling. Shanghai and Suzhou medical device manufacturing zones concentrate orthopedic OEM procurement activity.
Saudi Arabia
SFDA streamlining of implantable polymer registration pathways creates first-mover advantages for PEK suppliers establishing compounding partnerships. MOHAP alignment with Gulf Cooperation Council technical regulations enables regional market access from single manufacturing bases. King Abdullah Economic City anchors planned medical device manufacturing zone development.
United Kingdom
Post-Brexit UKCA marking requirements for medical devices run parallel to retained EU MDR standards, creating dual certification burdens for PEK implant suppliers. MHRA consultation on future medical device regulations signals potential divergence from EMA frameworks. Lancashire manufacturing bases sustain aerospace-grade PEK output across multiple continents.
Polyether Ketone (PEK) Market Competitive Landscape
Capability concentration sits with specialized polymer compounders; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: integrated resin producers with captive polymerization technology, independent compounders serving qualified tolling partnerships, and regional distributors managing specification-grade inventory. Dominant competitive moves include capacity expansion in medical-device-grade formulations and strategic partnerships with orthopedic OEMs seeking dedicated line access.
Among UK-based specialists, Victrex plc occupies a position exemplifying aerospace-grade resin production anchored in Lancashire manufacturing infrastructure. Within the German compounding tier, Ensinger GmbH represents Central European distribution capacity through Baden-Württemberg facilities. At the diversified chemical conglomerate vector, Solvay S.A. sits within the Brussels-headquartered polymer science division with broad fluoropolymer and ketone expertise.
| Leading Market Players |
|---|
| Panjin Zhongrun High Performance Polymers Co., Ltd. |
| Jilin Joinature Polymer Co., Ltd. |
| Victrex plc |
| Ensinger GmbH |
| DuPont |
| Evonik Industries AG |
| Celanese Corporation |
| SA BIC |
| Solvay |
| Others |
Value Network & Pricing Analysis
German difluorobenzophenone feedstock concentration anchors margin capture at the polymerization tier, with downstream medical-device compounders extracting premium spreads through FDA 510(k) certification bundling and dedicated line access contracts.
Pricing Analysis
European aerospace-grade PEK commands spreads over Asian industrial formulations due to REACH compliance certification costs and flame-smoke-toxicity testing documentation. Pricing stratifies across medical-device-grade, aerospace-certified, and standard industrial tiers based on purity profiles and qualification depth. Cost compression in commodity PEK-F runs through energy price volatility in German chemical parks. Orthopedic OEMs exhibit lowest price sensitivity due to titanium substitution value capture, while automotive under-hood suppliers face acute margin pressure from halogenated polymer incumbents.
Supply Chain Analysis
Ensinger and Victrex hold captive tolling capacity across Baden-Württemberg and Lancashire compounding corridors. Supply concentrates in Germany, the United Kingdom, and China's Yangtze River Delta medical device zones. PEK synthesis draws from hexafluoropropylene oxide intermediates and high-purity diphenyl ether feedstocks. Single-source crystallization technology licensing creates bottleneck vulnerability for new resin entrants. Distribution runs through qualified compounders serving aerospace tier-one suppliers and orthopedic OEMs with batch-specific certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and real-time batch release documentation are expanding faster than resin tonnage as orthopedic OEMs consolidate supplier relationships and demand embedded quality assurance integration.
For Market Incumbents: Insulate aerospace-grade positioning through backward integration into difluorobenzophenone intermediates and expansion of Lancashire polymerization capacity. PEEK incumbent substitution defense from Victrex and Solvay threatens bracket application displacement; counter via accelerated out-of-autoclave composite qualification with Boeing and Airbus tier-one suppliers. Certification investment in FDA 510(k) dual-submission pathways with notified bodies anchors medical-device switching costs. For New Entrants and Emerging Players: Establish a beachhead in Saudi Arabia's King Abdullah Economic City medical device zone through SFDA registration partnerships with regional distributors. The Gulf Cooperation Council alignment offers lowest regulatory friction for implantable polymer first-movers. Target orthopedic contract manufacturers in Warsaw and Minneapolis seeking qualified PEK-P second sources through dedicated compounding line joint ventures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-device-grade PEK-P formulations due to ISO 10993-18 chemical characterization equipment requirements and dedicated clean-room compounding infrastructure. Five-to-ten year viability favors acquiring mid-scale German compounders with existing EMA notified body relationships and captive polymerization tolling agreements. Watch FDA 510(k) filing volumes for carbon-fiber-reinforced PEK-OPTIMA variants as inflection signal for titanium substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Intermediates | Captures margin pools currently concentrated among German chemical parks serving PEK polymerization. |
| Out-of-Autoclave Composite Qualification | Compresses Boeing and Airbus tier-one supplier cycle times by half versus thermoset alternatives. |
| SFDA Registration Partnership | Unlocks Gulf Cooperation Council medical device market access from Saudi manufacturing bases. |
| ISO 10993-18 Chemical Characterization Investment | Accelerates EMA MDR Annex I approval timelines with Berlin and Munich notified bodies. |
| Dedicated Compounding Line Joint Venture | Secures volume commitments from Stryker and Zimmer Biomet procurement consolidation strategies. |
Research Methodology
Cross-validation between primary interviews with polymerization plant managers, orthopedic OEM procurement leads, aerospace tier-one supplier quality directors, and EMA regulatory affairs specialists anchors the qualitative findings. Secondary sources include ECHA REACH substance registration databases, FDA 510(k) premarket notification filings, SEC 10-K disclosures from listed chemical conglomerates, and German customs trade data on difluorobenzophenone intermediate flows. Bottom-up resin capacity modeling and top-down end-use demand estimation were triangulated across the analysis window.
Calibration against historical PEK-PEEK substitution elasticities and aerospace thermoplastic composite adoption curves shaped the projection framework. Segmentation dimensions modeled include product grade tier, application regulatory intensity, end-user technical support requirements, and regional production hub clustering. CAGRs were derived from fitted adoption curves rather than linear extrapolation. Forecast inputs incorporated EU Green Deal industrial decarbonization mandate compliance costs and FAA flame-smoke-toxicity certification timeline compression.
Stress conditions across hexafluoropropylene oxide supply disruptions, REACH substance restriction expansions, and orthopedic OEM supplier consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on qualification timeline compression and regulatory grandfathering provisions. Quarterly review of FDA 510(k) filing volumes and EMA notified body approval backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Thermoplastic Starch (TPS) Market